
 ASEAN OOH and DOOH Market | 2026-2036
ASEAN OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN OOH and DOOH Market Insights
Market Context
Static billboard revenue is narrowing as programmatic digital inventory captures premium media budgets across Southeast Asia. JCDecaux SE leverages its airport concession network to dominate transit advertising in Singapore and Bangkok. Plan B Media Public Company Limited anchors Thailand's street furniture and retail mall screen portfolio. Dentsu Group Inc. competes through integrated media buying platforms that bundle DOOH with digital and television campaigns.
Technical Definition and Segments
Out-of-home and digital out-of-home advertising encompasses physical display surfaces—ranging from static vinyl billboards to networked LED and LCD screens with content management systems—that deliver brand messaging to audiences in public transit systems, roadways, retail environments, and urban thoroughfares. LED Displays lead the technology segment due to brightness performance and outdoor durability in tropical climates, while Interactive formats within the Advertising Format dimension represent the fastest-expanding margin pool as advertisers demand engagement metrics and real-time audience measurement. Mall Displays sustain premium pricing through controlled indoor environments and dwell-time advantages over roadside inventory.
Regulatory Environment
Thailand's National Broadcasting and Telecommunications Commission governs screen placement along roadways, while Singapore's Land Transport Authority regulates transit advertising content in MRT stations and bus shelters. Malaysia's local council bylaws and Indonesia's regional permitting systems create fragmented compliance requirements that shape deployment timelines and capital recovery models. Stakeholders must monitor evolving data privacy frameworks around facial analytics and mobile device proximity tracking as these technologies integrate with DOOH measurement stacks.
Market Dynamics
Programmatic trading infrastructure is collapsing the traditional insertion order model across Southeast Asian media markets, compressing campaign activation timelines from weeks to hours and redistributing margin pools from media owners to data-enabled buying platforms.
Growth Catalysts
- Transit infrastructure expansion:Jakarta's MRT Phase 2 and Ho Chi Minh City's metro construction are generating captive audience environments with extended dwell times that command premium CPMs from FMCG and financial services advertisers.
- Malaysia's Communications and Multimedia Act amendments:Streamlined digital screen licensing procedures are accelerating deployment timelines in Kuala Lumpur's commercial districts and Penang's heritage zones.
- Facial analytics integration:Anonymous audience measurement systems are enabling impression-level verification that attracts performance marketing budgets from e-commerce and quick-commerce platforms.
Market Restraints
- LED panel import dependency:Southeast Asian operators rely on Shenzhen and Seoul supply chains for high-brightness outdoor modules, exposing margins to shipping cost volatility and currency fluctuations.
- Thailand's NBTC placement restrictions:Roadway setback requirements and brightness curfews limit screen density along Bangkok's arterial corridors, constraining inventory growth in the region's highest-value advertising market.
- Static vinyl substitution:Low-cost printed billboard formats retain share in Indonesia's tier-2 and tier-3 cities where electricity infrastructure and advertiser sophistication lag metro centers.
Strategic Opportunities
- Philippines provincial penetration:Cebu, Davao, and Iloilo present underscreened markets where first-mover retail mall networks can establish monopoly positions before regulatory frameworks mature.
- 5G-enabled real-time content:Singapore's nationwide 5G coverage and Thailand's AIS/True/DTAC infrastructure investments enable latency-sensitive interactive campaigns that sync mobile engagement with large-format displays.
- Vietnam's Decree 70 implementation:Digital advertising tax clarity and foreign investment liberalization in media services are creating regulatory tailwinds for joint ventures between local operators and international technology providers.
Industry Challenges
- Programmatic talent scarcity:Demand for operators fluent in both SSP/DSP architecture and tropical hardware maintenance exceeds supply across Bangkok, Jakarta, and Singapore hiring markets.
- Fragmented permitting timelines:Indonesia's district-level licensing and Malaysia's state-by-state enforcement create unpredictable capex recovery schedules that complicate portfolio financing.
- Privacy framework uncertainty:Pending restrictions on mobile device proximity tracking and facial recognition in Singapore and Thailand are forcing measurement stack redesigns before technical standards stabilize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN OOH and DOOH Market |
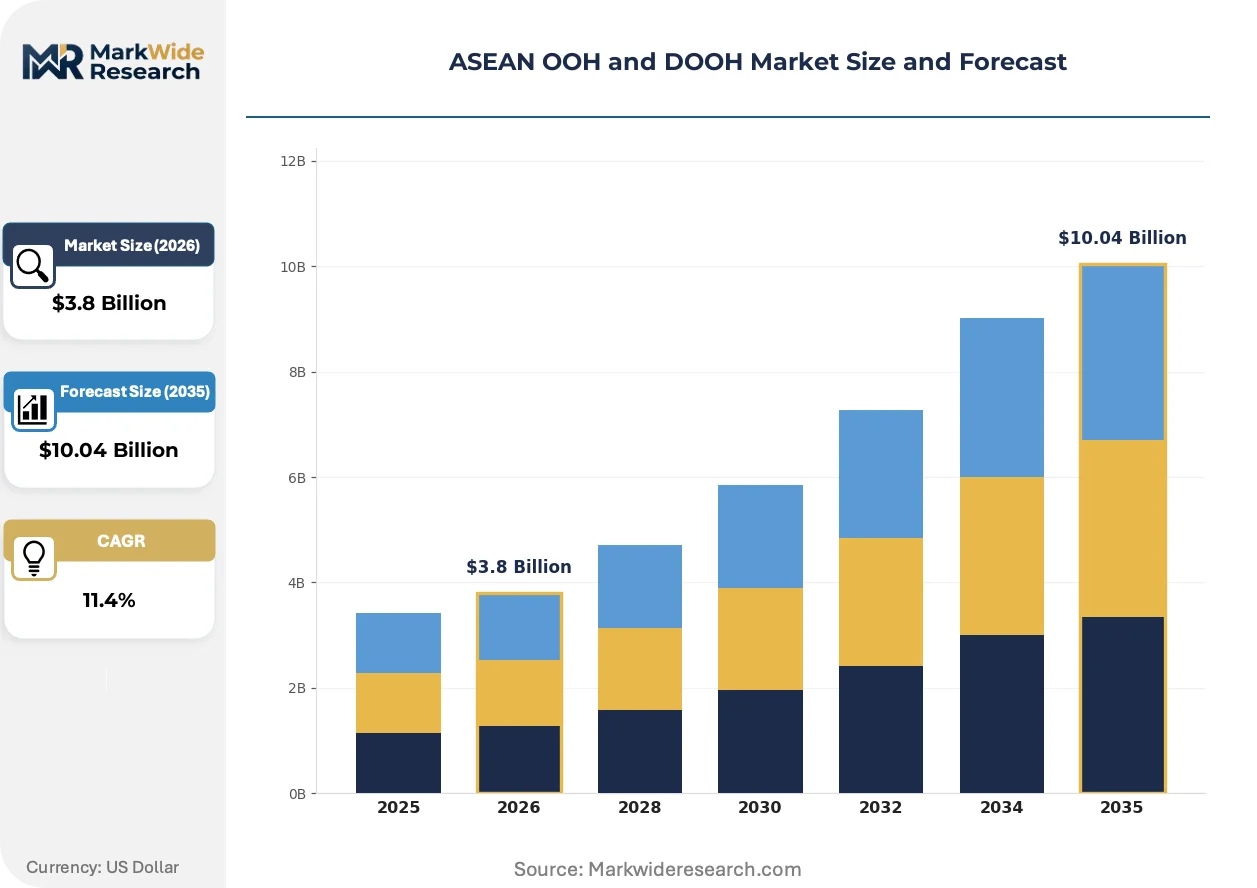
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medium Type: Billboards, Transit Advertising, Digital Screens, Mall Displays Target Audience: Urban Professionals, Tourists, Students, Families Technology: LED Displays, LCD Screens, Neon Signage, Backlit Posters Advertising Format: Static, Dynamic, Interactive, Video |
| Companies Covered | JCDecaux SE, Mooving Walls, Vistar Media, Moove Media Pte Ltd, EYE Indonesia, Clear Channel Singapore Pte Ltd, Plan B Media Public Company Limited, Dentsu Group Inc., Hakuhodo DY Holdings Inc., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN OOH and DOOH Market Trends and Innovations
Convergence between physical display networks and mobile-first audience data is redefining how Southeast Asian advertisers attribute store visits and purchase intent to out-of-home exposures.
Edge computing deployments in screen enclosures are collapsing the latency gap between audience detection and content rotation. Retail mall operators in Singapore and Bangkok are adopting NVIDIA Jetson-based modules that process anonymized demographic signals locally, enabling sub-second creative swaps without cloud round-trips. This architecture is collapsing the technical barrier that previously reserved dynamic optimization for digital channels with superior infrastructure.
Thailand's National Broadcasting and Telecommunications Commission is tightening electromagnetic emissions standards for roadside LED installations above 100 square meters. The revised technical specifications will force hardware refreshes across Bangkok's Sukhumvit and Ratchadaphisek corridors, accelerating replacement cycles for aging SMD modules. Transit shelter operators are responding by specifying compliant driver ICs and shielding enclosures in new procurement tenders.
Retail advertisers are consolidating media buying authority into centralized trading desks that treat DOOH as a performance channel rather than brand awareness. Quick-commerce platforms in Indonesia and Vietnam are demanding CPA-based pricing models that tie screen exposure to app installs and first orders. This behavioral shift is most visible in Jakarta's GrabFood and Gojek partnership networks, where dark kitchen clusters and delivery hub screens carry attribution pixels that sync with mobile ad IDs.
ASEAN OOH and DOOH Market Segmentation
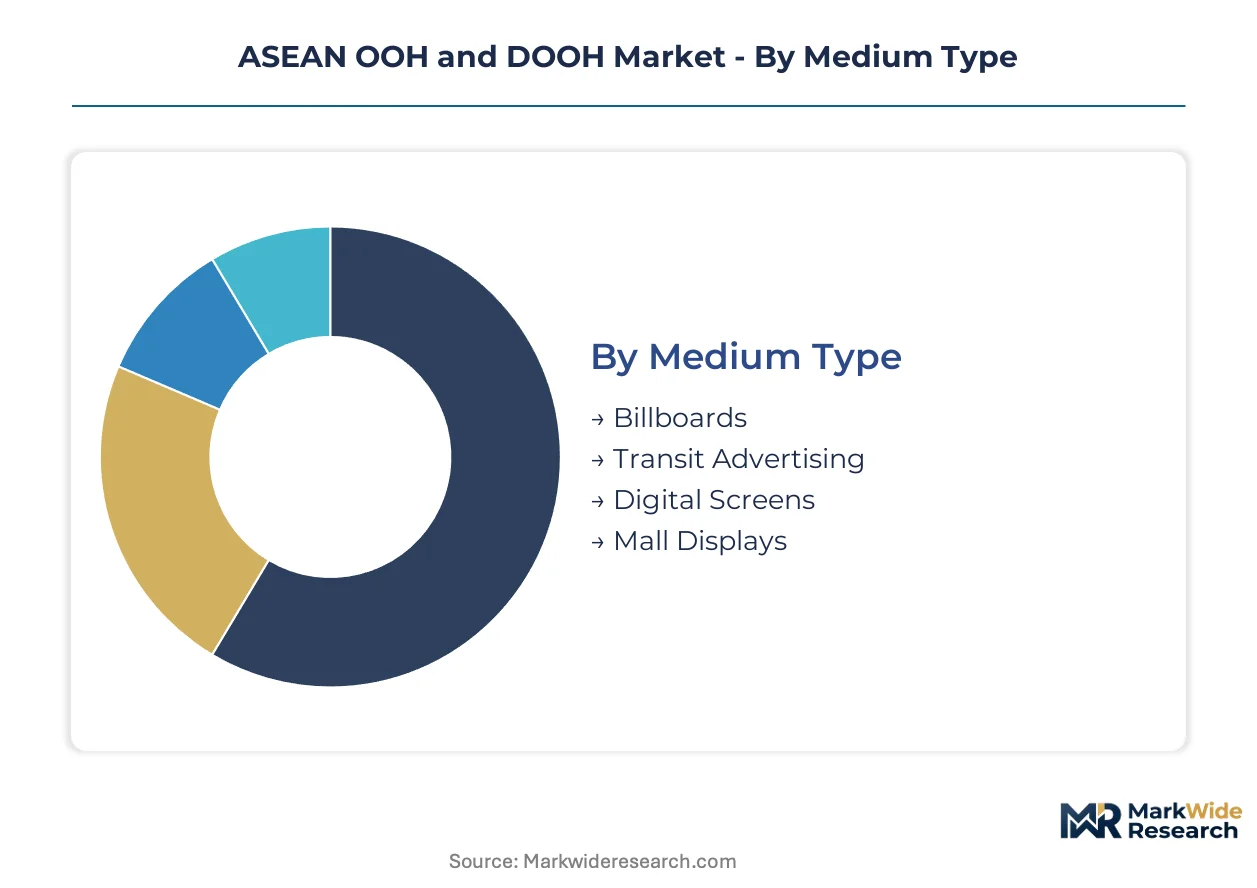
ASEAN advertisers allocate budgets across distinct inventory types that vary in addressability, measurement precision, and creative flexibility. Understanding how these segments intersect with audience mobility patterns and regulatory constraints determines campaign effectiveness across Southeast Asian urban corridors.
Medium Type:
Mature formats dominate revenue concentration while emerging inventory classes reshape deployment capital requirements.
- Billboards:Static vinyl and printed surfaces mounted along arterial roadways and elevated expressways. Indonesia's toll road network and Malaysia's North-South Expressway sustain demand from automotive and telecommunications brands despite narrowing share in premium budgets.
- Transit Advertising:Interior and exterior placements on buses, trains, and station infrastructure. Singapore's MRT and Bangkok's BTS generate captive audience environments where FMCG advertisers command premium CPMs during rush-hour compression.
- Digital Screens:Networked LED and LCD displays with remote content management capability. Ho Chi Minh City's District 1 and Jakarta's Sudirman corridor concentrate deployment as landlords retrofit commercial facades for programmatic revenue streams.
- Mall Displays:Indoor screens and static panels within retail environments. Bangkok's Siam Paragon and Singapore's Orchard Road malls sustain premium pricing through climate-controlled dwell times that roadside inventory cannot match.
Billboards retain volume leadership; Digital Screens hold the steepest expansion curve.
Target Audience:
Audience segmentation follows mobility patterns that concentrate exposure in specific dayparts and geographic nodes.
- Urban Professionals:Commuters aged 25-45 traversing central business districts during peak hours. Singapore's Raffles Place and Jakarta's Sudirman-Thamrin corridor deliver concentrated reach for financial services and business technology advertisers.
- Tourists:Transient visitors in airport, hotel, and heritage zones. Bangkok's Suvarnabhumi Airport and Bali's Ngurah Rai terminal generate high-frequency exposure for hospitality and luxury retail campaigns.
- Students:Young adults concentrated near university districts and mass transit nodes. Kuala Lumpur's Bangsar and Manila's University Belt create predictable audience pools for edtech and consumer electronics brands.
- Families:Multi-generational units in suburban shopping centers and weekend recreation venues. Jakarta's Taman Mini and Singapore's Sentosa Island anchor leisure-focused inventory placements.
Urban Professionals sustain the largest addressable base; Tourists command the highest CPM premiums.
Technology:
Hardware selection balances luminance requirements, power consumption, and content flexibility against total cost of ownership.
- LED Displays:Direct-view diode arrays delivering high brightness for outdoor visibility. Tropical humidity and solar load in Bangkok and Jakarta drive specification toward IP65-rated enclosures and active thermal management systems.
- LCD Screens:Transmissive panels suited for indoor and semi-covered environments. Retail mall operators in Singapore and Kuala Lumpur specify commercial-grade panels with 24/7 duty cycles for concourse and atrium installations.
- Neon Signage:Gas-discharge tube illumination for heritage aesthetic applications. Penang's George Town and Bangkok's Yaowarat Road preserve neon deployments where regulatory heritage protections limit LED retrofit options.
- Backlit Posters:Fluorescent or LED-edged illumination for static creative rotation. Indonesia's tier-2 cities deploy backlit transit shelters where full digital conversion remains economically unviable.
LED Displays anchor outdoor deployment; LCD Screens dominate indoor addressable inventory.
Advertising Format:
Creative capability tiers separate brand awareness from performance-optimized campaign architectures.
- Static:Fixed creative without motion or rotation capability. Vinyl billboards and printed transit panels persist in Vietnam's provincial markets and Indonesia's outer islands where network infrastructure and advertiser sophistication lag metro centers.
- Dynamic:Content rotation triggered by time, weather, or audience density signals. Singapore's Clear Channel and Thailand's Plan B Media deploy daypart-optimized playlists that shift messaging between morning commuter and evening leisure audiences.
- Interactive:Two-way engagement through touch, gesture, or mobile device synchronization. 5G-enabled installations in Bangkok's Siam Square and Jakarta's Grand Indonesia enable real-time QR and NFC activation that collapses the gap between exposure and conversion.
- Video:Full-motion creative with audio capability in controlled environments. Mall atrium screens in Manila's SM Megamall and Singapore's VivoCity deliver cinematic impact that roadside inventory regulations prohibit.
Static formats retain the broadest geographic footprint; Interactive campaigns are climbing the fastest in media plan prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertisers in Vietnam and the Philippines exhibit the highest price elasticity, squeezing margins on standard roadside inventory, while Singapore and Bangkok command premium valuations where transit density and measurement precision justify elevated CPMs.
Singapore
The Land Transport Authority regulates advertising content across MRT stations and bus shelters, creating standardized inventory packages that attract financial services and luxury brands. JCDecaux SE maintains concession dominance at Changi Airport terminals, where dwell-time metrics support performance-based pricing models. The Raffles Place-Shenton Way corridor concentrates the highest-value digital screen deployments.
Thailand
Bangkok's BTS and MRT expansion generates captive audience environments that FMCG advertisers prioritize during rush-hour compression. The National Broadcasting and Telecommunications Commission governs screen placement along arterial roadways through setback requirements and brightness curfews. Plan B Media Public Company Limited anchors street furniture networks across Sukhumvit and Ratchadaphisek commercial corridors.
Indonesia
Jakarta's MRT Phase 2 construction and Surabaya's transit upgrades are reshaping inventory distribution across the archipelago's two largest metropolitan zones. Regional permitting systems at the district level create fragmented compliance timelines that complicate capital recovery schedules. The Sudirman-Thamrin corridor and Bali's Ngurah Rai Airport terminal concentrate premium digital deployments.
Vietnam
Ho Chi Minh City's metro construction and Hanoi's bus rapid transit expansion are generating new captive-audience inventory pools. Decree 70 implementation is clarifying digital advertising tax treatment and foreign investment rules for media services joint ventures. District 1 in Ho Chi Minh City anchors the highest screen density, with provincial markets in Da Nang and Hai Phong presenting first-mover expansion opportunities.
Malaysia
Kuala Lumpur's commercial districts and Penang's heritage zones are experiencing accelerated deployment timelines following Communications and Multimedia Act amendments that streamlined digital screen licensing. Local council bylaws maintain fragmented enforcement across state boundaries. The KLCC-Bukit Bintang corridor and Penang International Airport concentrate premium transit and mall-based inventory.
ASEAN OOH and DOOH Market Competitive Landscape
Transit concession holders and integrated media buying platforms split the market between inventory control and audience data aggregation. The vendor base clusters around three strategic archetypes: airport and transit network operators, street furniture and retail mall screen owners, and agency holding companies with programmatic trading infrastructure. Consolidation pressure is driving concession renewals and technology licensing partnerships rather than outright acquisitions.
Within the transit concession tier, JCDecaux SE and Clear Channel Singapore Pte Ltd occupy positions anchored by long-term airport and municipal contracts. Plan B Media Public Company Limited represents the street furniture and retail mall archetype with concentrated exposure to Thailand's urban corridors. Dentsu Group Inc. sits within the agency holding company tier, bundling DOOH inventory with digital and television campaigns through centralized trading desks.
| Leading Market Players |
|---|
| JCDecaux SE |
| Mooving Walls |
| Vistar Media |
| Moove Media Pte Ltd |
| EYE Indonesia |
| Clear Channel Singapore Pte Ltd |
| Plan B Media Public Company Limited |
| Dentsu Group Inc. |
| Hakuhodo DY Holdings Inc. |
| Others |
Pricing and Supply Chain Analysis
The Shenzhen-Jakarta shipping corridor's freight volatility feeds directly into hardware procurement costs for ASEAN screen operators, compressing margins on imported LED modules while amplifying price differentiation between premium programmatic inventory and static roadside placements.
Pricing Analysis
After-sales service contracts and extended maintenance agreements generate disproportionate lifetime value for hardware vendors serving tropical deployment environments. Three-tier pricing structure across premium, standard, and economy levels separates JCDecaux's airport concession bundles from Plan B Media's street furniture networks and unbranded tier-3 city operators. Cost compression in economy-tier static inventory intensifies because Indonesian district-level permitting extends capital recovery timelines. Quick-commerce advertisers in Jakarta and Ho Chi Minh City exhibit the highest price sensitivity, whereas luxury brands at Singapore Changi tolerate premium CPMs for verified dwell-time metrics.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian import markets dominates procurement risk planning for high-brightness outdoor LED modules. Manufacturing concentrates in Shenzhen, Seoul, and Taipei for driver ICs and SMD packages. Southeast Asian operators draw from these hubs for IP65-rated enclosures and active thermal management systems. Single-source vulnerability persists in specialized components like NVIDIA Jetson edge computing modules for real-time audience analytics. Distribution runs through Bangkok and Singapore as regional logistics hubs before final-mile deployment to Jakarta, Ho Chi Minh City, and Kuala Lumpur.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where programmatic trading infrastructure interoperability determines which inventory pools capture performance marketing budgets from e-commerce advertisers.
For Market Incumbents: Entrench concession dominance through early renewal of airport and transit authority contracts before 5G-enabled interactive formats mature. JCDecaux SE and Clear Channel Singapore must accelerate edge computing deployment in screen enclosures to match the latency performance of digital channels. Vertical integration into facial analytics software stacks defends margin position against data-enabled buying platforms. For New Entrants and Emerging Players: Build out retail mall networks in Cebu's Ayala Center, Davao's SM Lanang Premier, and Iloilo's Festive Walk before regulatory frameworks mature in these underscreened Philippine provincial markets. Vietnam's Decree 70 implementation creates the most penetrable regulatory entry point for joint ventures between local operators and international technology providers. A programmatic-first go-to-market angle bypasses incumbent insertion order relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from media holding company divisions where DOOH assets sit undervalued within broader digital and television portfolios. Five-to-ten year viability hinges on consolidation of fragmented district-level permitting capabilities into scalable national platforms. The signal to watch as inflection indicator is NBTC electromagnetic emissions standard enforcement accelerating hardware replacement cycles across Bangkok's arterial corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Renewal Acceleration | Long-term airport and transit contracts with Singapore's LTA and Bangkok's BTS lock in captive audience inventory pools. |
| Edge Computing Deployment | NVIDIA Jetson-based modules in Bangkok Siam Paragon and Jakarta Grand Indonesia enable sub-second dynamic creative optimization. |
| Programmatic Platform Integration | SSP-DSP interoperability attracts performance marketing budgets from GrabFood and Gojek partnership networks. |
| Provincial Network Expansion | First-mover retail mall screens in Cebu, Davao, and Iloilo establish monopoly positions before regulatory maturity. |
| 5G-Enabled Interactive Format Launch | Latency-sensitive QR and NFC campaigns sync mobile engagement with large-format displays in Singapore's nationwide coverage zones. |
Research Methodology
Operator-level perspectives from media owners, programmatic trading desk heads, transit authority procurement officers, and retail mall asset managers anchored the qualitative base. Primary interviews combined with secondary validation from National Broadcasting and Telecommunications Commission filings, Land Transport Authority concession records, and Communications and Multimedia Act amendment texts. Customs import data for LED modules, SEC 10-K disclosures from JCDecaux SE and Dentsu Group Inc., and district-level permitting databases supplied quantitative foundations. Bottom-up screen inventory counts triangulated against top-down advertising spend estimates from media buying platforms.
Scenario-bracketing framed the analytical approach across the analysis window. Segmentation dimensions modeled include medium type, technology tier, advertising format capability, and target audience mobility pattern. CAGRs derived from installed base expansion rates, replacement cycle acceleration from regulatory compliance deadlines, and programmatic revenue penetration curves. Forecast inputs incorporated MRT Phase 2 construction timelines in Jakarta and Ho Chi Minh City metro expansion milestones.
Sensitivities concentrate around NBTC electromagnetic emissions enforcement timing, Indonesia's district-level permitting harmonization, and facial analytics privacy restriction implementation in Singapore and Thailand. Forecasts reflect documented assumptions about 5G infrastructure rollout pace and quick-commerce advertiser budget allocation shifts. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Germany OOH and DOOH Market
Advertising and Marketing Media
United States OOH and DOOH Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
United States Marketing Agencies Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
Smart Advertising Market
Advertising and Marketing Media
Digital OOH Advertising Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
Digital Advertising Market
Advertising and Marketing Media
Global Programmatic Advertising Platform Market