
 South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market | 2026-2036
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market Insights
Programmatic ad-serving subscription tiers is realigning how media owners package inventory to buyers. JCDecaux South Africa leverages its airport concession network to sustain premium rate card positions. Provantage Media Group anchors township and rural coverage through specialized community billboard portfolios. Primedia Outdoor competes via integrated transit and roadside dominance across major metropolitan areas.
Out-of-home advertising encompasses physical and digital display surfaces positioned in public spaces, including roadside billboards constructed from weather-resistant vinyl or PVC flex substrates, transit shelter panels, and LED-based digital signage units with brightness calibration for daylight visibility. Its commercial purpose centers on delivering brand messaging to audiences during commute, leisure, and purchase-intent moments outside residential environments. Digital signage within the medium type dimension is capturing disproportionate investment as programmatic capabilities mature, while static billboards retain volume leadership in peri-urban expansions. The content format dimension shows interactive and video formats pulling margin pools from legacy static executions, particularly in Sandton and Cape Town CBD premium inventory zones.
South Africa's Advertising Standards Authority enforces the Code of Advertising Practice, which governs truthful messaging and restricts harmful product promotion in OOH placements. The Independent Communications Authority of South Africa (ICASA) regulates spectrum allocation affecting DOOH network connectivity and broadcast content transmission. Municipal bylaws in Johannesburg, Cape Town, and eThekwini control billboard placement, size, and illumination, creating localized compliance burdens that shape market access costs. Stakeholders must monitor evolving municipal spatial planning frameworks and ICASA's spectrum licensing trajectory to anticipate where network expansion faces friction or acceleration.
Market Dynamics
Programmatic trading infrastructure is compressing sales cycles and fragmenting rate card structures across South Africa's OOH inventory pools. Buyers now transact impressions through automated platforms rather than annual contract negotiations, forcing media owners to reprice highway corridor assets in real-time.
Growth Catalysts
- ICASA spectrum liberalization:Expanded 5G and IoT bandwidth allocations enable richer DOOH content delivery and dynamic creative optimization across Johannesburg and Cape Town networks.
- Retail media convergence:Grocery chains and mall operators are monetizing in-store digital screens through programmatic pipes, extending DOOH reach into purchase-intent environments.
- Gauteng highway corridor density:N1, N3, and N12 route networks concentrate commuter volumes that sustain premium pricing for roadside inventory.
Market Restraints
- Film and Publication Board content classification:Pre-publication review requirements for certain imagery categories delay campaign deployment and limit creative flexibility.
- Municipal billboard moratoria:Johannesburg and eThekwini planning departments periodically freeze new outdoor advertising permits, constraining inventory expansion.
- LED hardware import dependency:Display module sourcing concentrates through East Asian supply chains, exposing operators to currency volatility and shipping friction.
Strategic Opportunities
- Eastern Cape township penetration:Underdeveloped DOOH infrastructure in Gqeberha and rural corridors offers first-mover positioning for community-focused inventory plays.
- Dynamic creative optimization:Real-time weather, traffic, and sports data integration enables contextually relevant messaging that commands rate premiums.
- Advertising Standards Authority self-regulatory compliance tools:Automated pre-screening platforms reduce approval timelines and lower campaign cancellation risk.
Industry Challenges
- Programmatic talent scarcity:Shortage of traders and data analysts familiar with South African inventory characteristics and buyer behaviors.
- Static-to-digital site conversion capex:Highway billboard electrification and fiber connectivity require substantial capital deployment with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market |
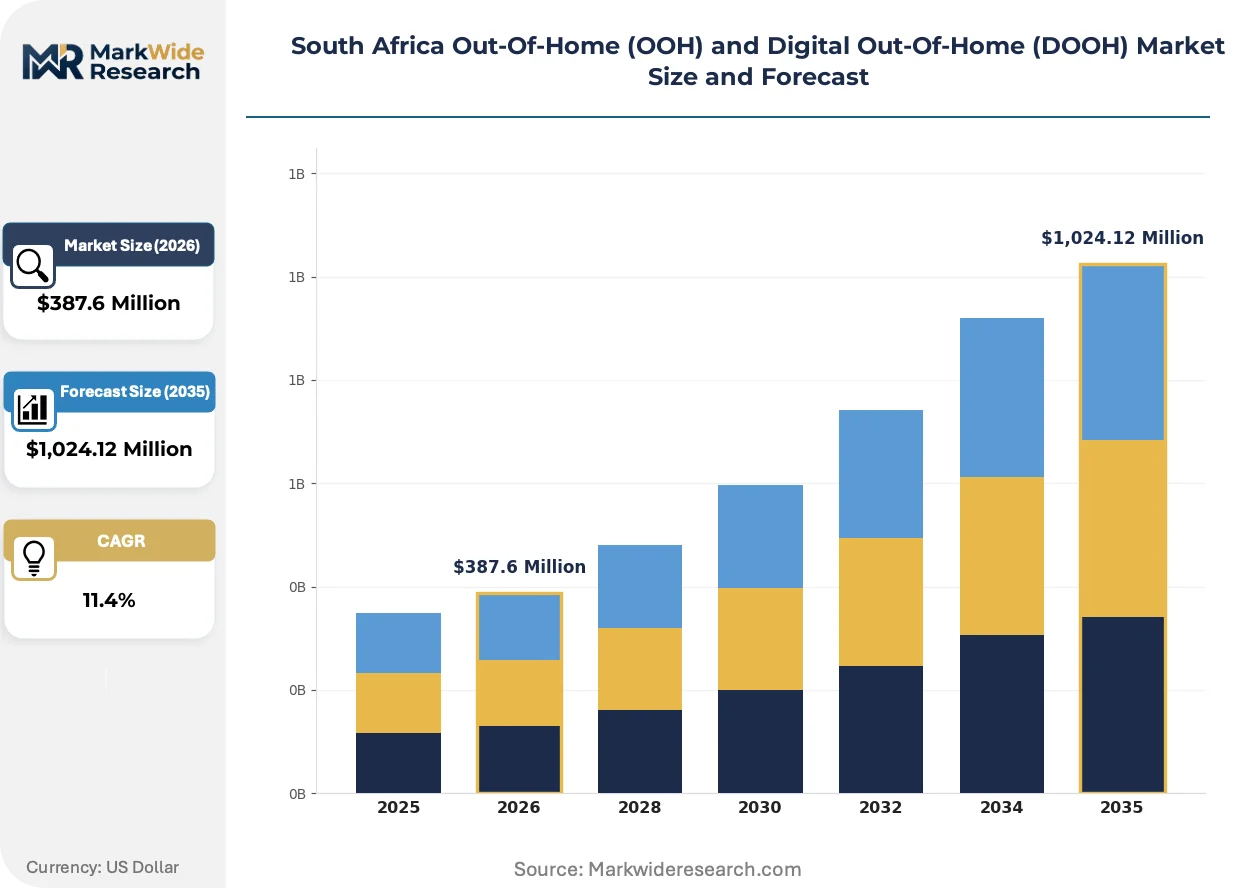
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medium Type: Billboards, Posters, Transit Ads, Digital Signage Audience Segment: Urban Residents, Commuters, Tourists, Retail Shoppers Content Format: Static, Animated, Interactive, Video Advertising Strategy: Brand Awareness, Direct Response, Event Promotion, Sponsorship |
| Companies Covered | JCDecaux South Africa, Provantage Media Group, Primedia Outdoor, Outdoor Network, Tractor Outdoor, Evolv Outdoor, Alliance Media, Clear Channel Outdoor Holdings, APG SGA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market Trends and Innovations
Data-driven audience measurement and automated trading are dissolving traditional media buying workflows. Inventory liquidity and pricing transparency are improving, though operational complexity rises.
Programmatic DOOH platforms are rewriting how media owners package and price inventory. JCDecaux and Primedia Outdoor are deploying private marketplace structures that expose remnant highway and airport slots to demand-side platforms. Buyers now access real-time availability and audience impression data that previously required direct sales negotiation. This compression of transaction friction is enabling smaller advertisers to participate in premium inventory categories.
The Advertising Standards Authority is tightening enforcement of the Code of Advertising Practice around harmful product categories. Alcohol, gambling, and high-fat food messaging face elevated scrutiny in proximity to schools and transport hubs. Operators in Cape Town and Johannesburg are pre-emptively geofencing sensitive zones to avoid campaign takedown orders. Compliance tooling investment is becoming a competitive differentiator among network owners.
Retail brands are consolidating planning across online and physical channels. Shopper marketing teams now execute DOOH as an extension of e-commerce attribution models rather than isolated awareness plays. This integration demands impression-to-sale measurement capabilities that legacy OOH infrastructure cannot support. Sandton and Cape Town CBD inventory zones are seeing the fastest adoption of closed-loop measurement partnerships.
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market Segmentation
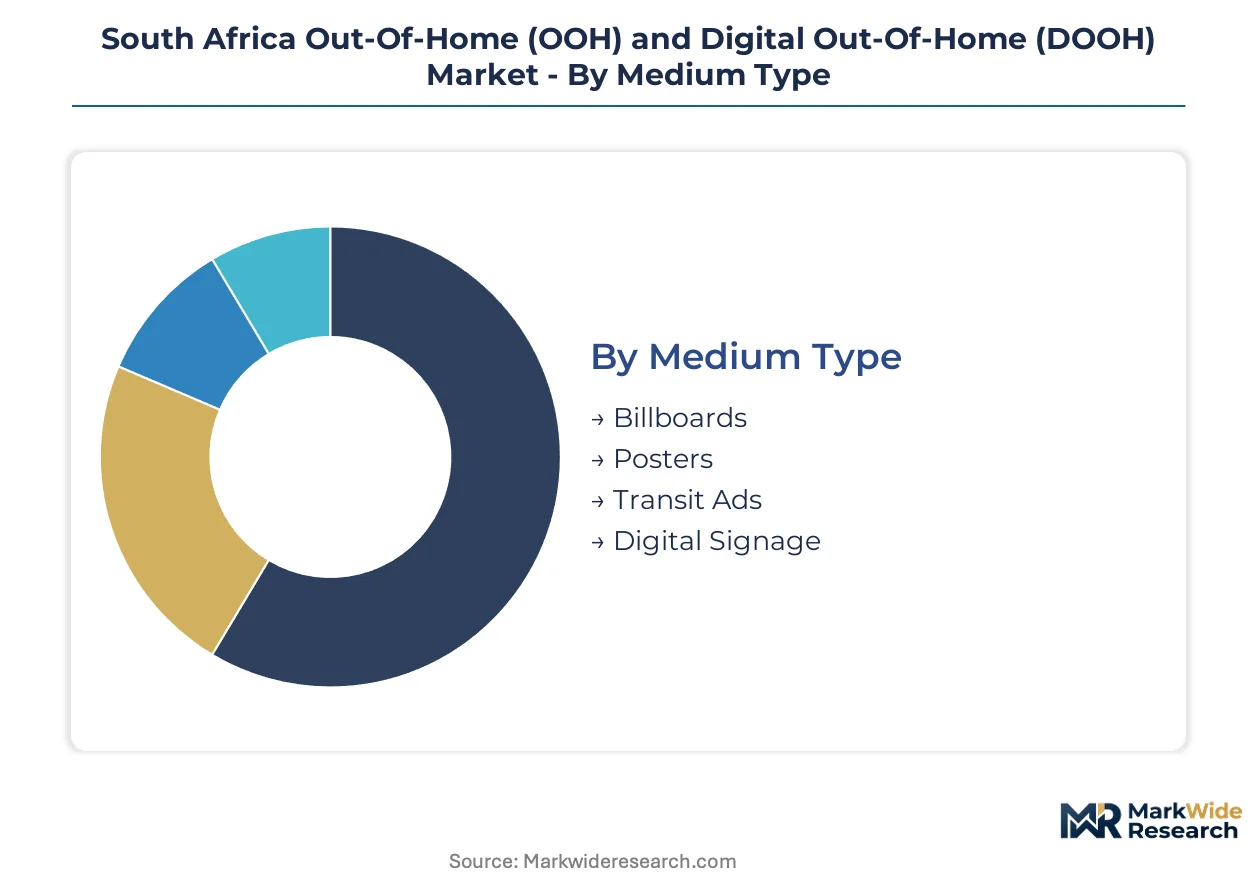
Segmentation reveals how capital deployment and audience access vary across South Africa's OOH landscape. Media owners allocate infrastructure investment differently depending on which medium, audience, format, and strategy combination they target. Understanding these partitions clarifies where rate premiums concentrate and where scale economics dominate.
Medium Type:
Capital intensity varies sharply across physical infrastructure categories, with electrification and connectivity requirements driving upfront spend differentials.
- Billboards:Large-format roadside structures built from weather-resistant vinyl or PVC flex substrates dominate Gauteng's N1, N3, and N12 highway corridors. Static inventory retains volume leadership in peri-urban expansions where electrification costs delay digital conversion.
- Digital Signage:LED-based display units with brightness calibration for daylight visibility command premium rate cards in Sandton and Cape Town CBD zones. Programmatic trading infrastructure is compressing sales cycles for this inventory category.
- Posters:Paper-based transit shelter and street furniture placements require lower capex than billboard structures. Municipal bylaws in Johannesburg and eThekwini control placement density and illumination standards.
- Transit Ads:Interior and exterior placements on buses, taxis, and rail networks anchor township and rural coverage strategies. Primedia Outdoor competes via integrated transit dominance across major metropolitan areas.
Most installed capacity flows through billboards. Expansion is steepest in digital signage.
Audience Segment:
Audience targeting determines yield optimization potential, with commute-pattern density dictating impression value.
- Commuters:Daily highway and transit corridor travelers sustain premium pricing for roadside inventory. Gauteng province's route networks concentrate volumes that justify real-time dynamic creative deployment.
- Urban Residents:Dense metropolitan populations in Johannesburg and Cape Town enable frequency-based campaign planning. ICASA spectrum liberalization supports richer content delivery to these zones.
- Retail Shoppers:Purchase-intent audiences in mall and grocery environments are monetizing through retail media convergence. Closed-loop measurement partnerships are advancing fastest in Sandton and Cape Town CBD.
- Tourists:Airport and hospitality district placements leverage JCDecaux South Africa's concession network. Seasonal demand fluctuation requires flexible rate card structures.
Commuters generate the highest impression density. Retail shoppers are climbing the fastest in advertiser investment priority.
Content Format:
Production and technology costs stratify format selection, with motion and interactivity requiring elevated creative and hardware investment.
- Video:Full-motion content with audio capabilities commands rate premiums on LED networks. Film and Publication Board classification requirements shape permissible imagery and delay deployment timelines.
- Interactive:Touch-enabled and mobile-integrated executions pull margin pools from legacy static formats. Real-time weather, traffic, and sports data integration enables contextually relevant messaging.
- Animated:Digital transitions between static frames balance production cost with attention capture. Advertising Standards Authority self-regulatory compliance tools reduce approval risk for this format.
- Static:Fixed-image vinyl and paper substrates retain cost advantages for broad-reach campaigns. LED hardware import dependency exposes operators to currency volatility when converting static sites.
Static formats retain the largest installed base. Video is gaining share fastest in premium inventory zones.
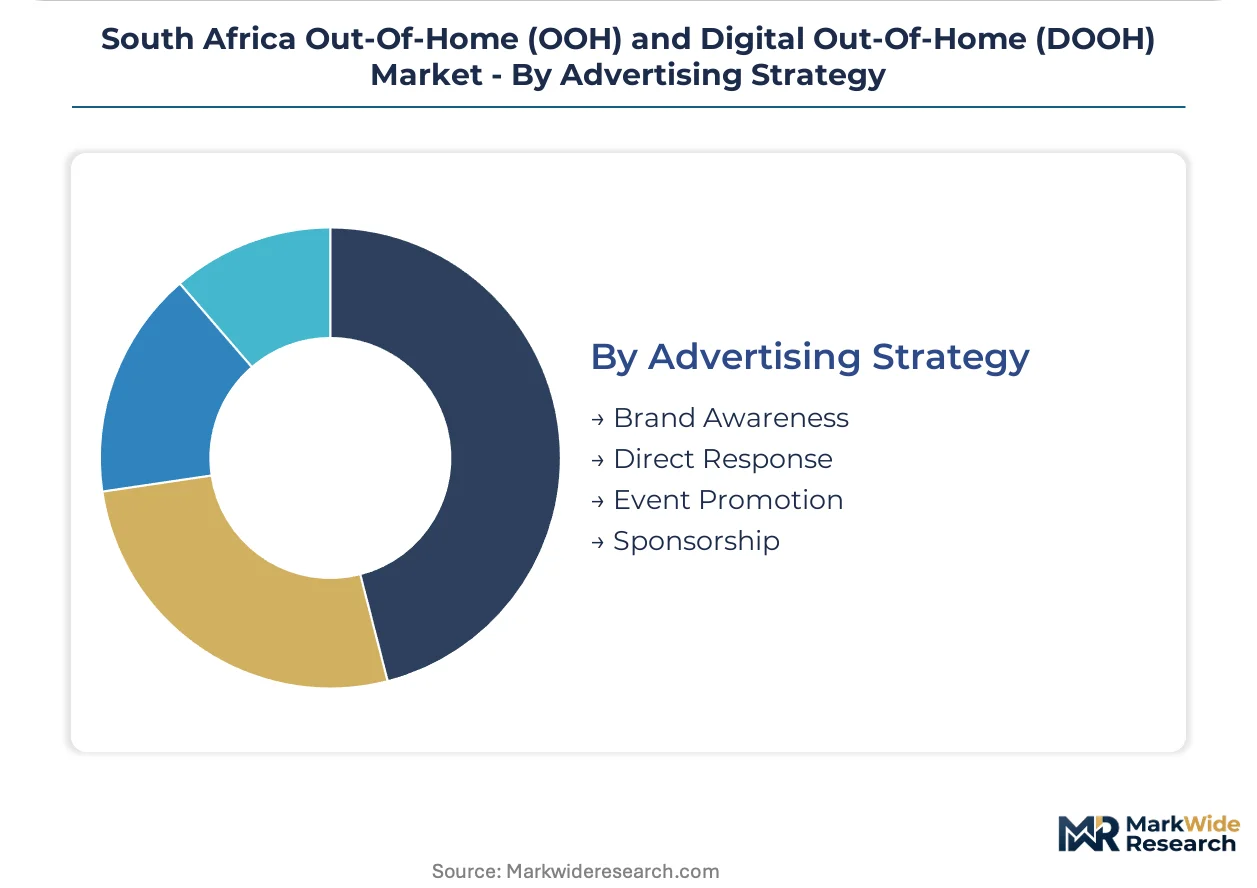
Advertising Strategy:
Strategy selection shapes measurement requirements and sales cycle length, with performance accountability driving technology investment.
- Brand Awareness:Reach and frequency metrics dominate planning for mass-market consumer goods. Annual contract negotiations are fragmenting into programmatic impression trading.
- Direct Response:Attribution modeling demands closed-loop measurement that legacy OOH infrastructure cannot support. Shopper marketing teams now execute DOOH as an extension of e-commerce models.
- Event Promotion:Time-bound campaigns require rapid deployment flexibility that programmatic pipes enable. Municipal billboard moratoria periodically constrain inventory availability for this strategy.
- Sponsorship:Long-term partnership structures favor integrated transit and airport concession networks. JCDecaux leverages its airport positions to sustain premium rate cards.
Brand awareness commands the largest spend allocation. Direct response is expanding most quickly as measurement capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's OOH market outpaces Sub-Saharan neighbors in digital penetration, while Nigeria and Kenya build static inventory bases that attract cross-border investment from regional media groups.
Gauteng Province
The N1, N3, and N12 highway corridors concentrate commuter volumes that sustain premium roadside pricing. Johannesburg municipal bylaws control billboard placement density and illumination standards, creating localized compliance frameworks. Sandton's CBD hosts the densest DOOH network deployment, with programmatic trading infrastructure compressing sales cycles for premium inventory.
Western Cape
Cape Town's tourism economy drives seasonal demand fluctuation for airport and hospitality district placements. The city's Film and Publication Board content classification requirements shape permissible advertising imagery and delay campaign deployment timelines. The CBD and Atlantic Seaboard corridors see fastest adoption of closed-loop measurement partnerships for retail media convergence.
KwaZulu-Natal
eThekwini's municipal planning department periodically freezes new outdoor advertising permits, constraining inventory expansion in Durban metro areas. The province's port logistics corridors generate transit advertising demand from shipping and freight operators. Township and peri-urban expansions retain static billboard dominance where electrification costs delay digital conversion.
Eastern Cape
Gqeberha and rural corridor networks present underdeveloped DOOH infrastructure with first-mover positioning opportunities. Provincial economic development programs target infrastructure investment for coastal tourism routes. Community-focused inventory plays anchor specialized coverage strategies in township markets where national operators maintain limited presence.
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market Competitive Landscape
Top-tier vendors anchor premium airport and highway corridor positions, while mid-tier operators compete through township specialization and rural coverage depth. The market structure stratifies across three tiers: international concession holders with national footprint, diversified domestic media groups with integrated transit portfolios, and regional specialists targeting underserved geographic pockets. Dominant competitive moves include static-to-digital site conversion programs and programmatic platform integration partnerships.
Within the international concession tier, JCDecaux South Africa exemplifies premium rate card positioning through airport network control. Among diversified domestic operators, Primedia Outdoor and Provantage Media Group occupy complementary positions—Primedia via integrated transit and roadside dominance across metropolitan areas, Provantage through specialized community billboard portfolios in township and rural markets. These three companies represent the primary competitive archetypes shaping inventory access and pricing structures.
| Leading Market Players |
|---|
| JCDecaux South Africa |
| Provantage Media Group |
| Primedia Outdoor |
| Outdoor Network |
| Tractor Outdoor |
| Evolv Outdoor |
| Alliance Media |
| Clear Channel Outdoor Holdings |
| APG SGA |
| Others |
Pricing and Supply Chain Analysis
Retail media buyers and programmatic traders concentrate demand in Johannesburg and Cape Town premium zones, forcing media owners toward impression-based rate cards that fragment traditional annual contract structures. This buyer concentration compresses pricing power for highway corridor inventory while elevating yield premiums for closed-loop measurable retail placements.
Pricing Analysis
Capacity additions in Gauteng's DOOH networks are reshaping price floors for static-to-digital conversions. Three-tier pricing structure across premium airport, standard highway, and economy township levels stratifies rate cards by audience density and measurement capability. Price differentiation hinges on ICASA spectrum access for dynamic creative delivery and Film and Publication Board pre-approval status. Cost compression in standard-tier roadside inventory is intensifying because municipal permit moratoria constrain supply expansion. Township-focused operators exhibit highest price sensitivity; airport concession holders maintain lowest sensitivity due to captive audience scarcity.
Supply Chain Analysis
LED module refurbishment and remanufacturing flows from decommissioned European and East Asian display networks feed secondary supply channels for South African operators. Hardware sourcing draws from China, South Korea, and Taiwan for display components, with PVC flex substrates and weather-resistant vinyl anchored in domestic conversion facilities. Supply chain risk centers on single-source vulnerability for high-brightness LED drivers subject to semiconductor allocation constraints. Distribution runs through specialized outdoor advertising contractors and direct media owner sales teams, with programmatic platforms disintermediating traditional agency relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
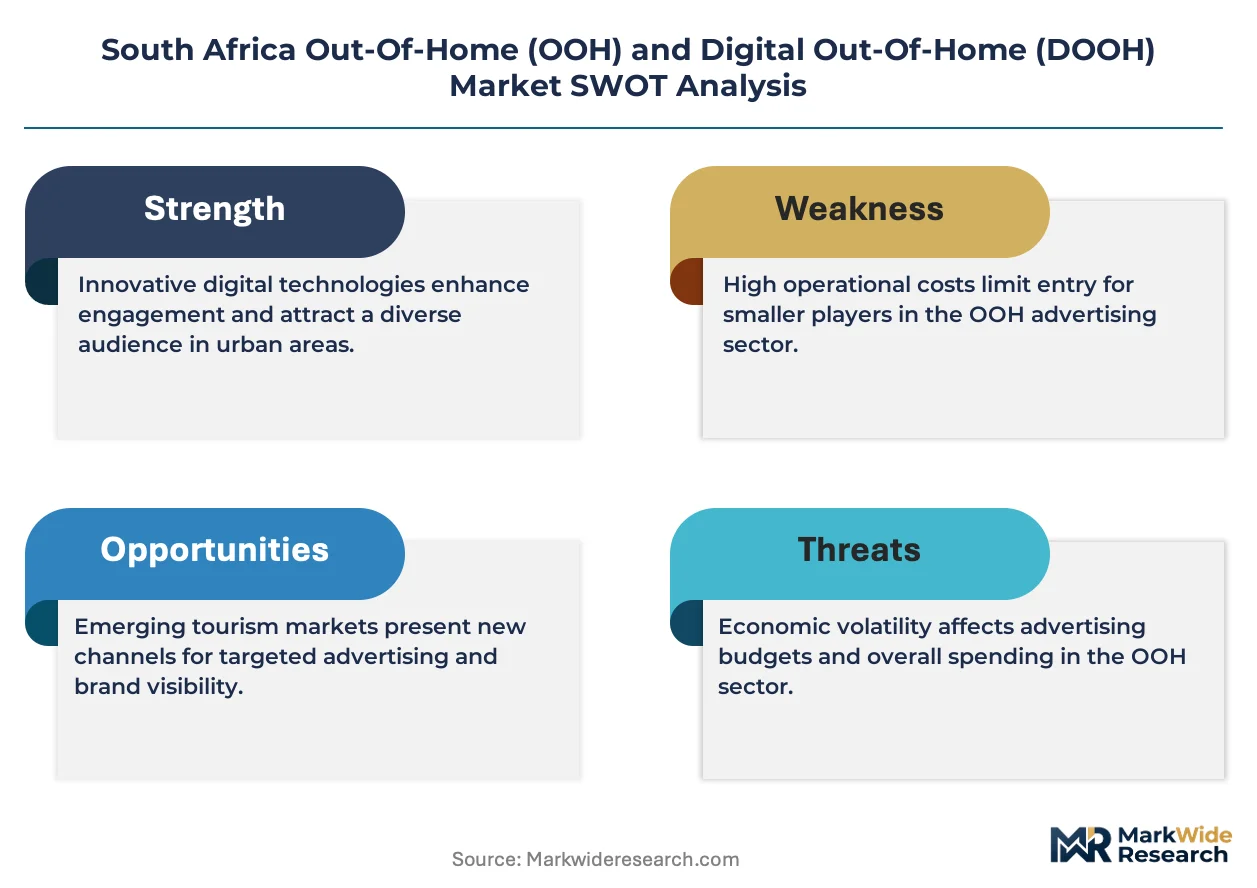
South Africa's OOH market functions as a regulatory compounder where ICASA spectrum liberalization and municipal spatial planning frameworks create demand acceleration for compliant digital infrastructure. The Advertising Standards Authority's tightened enforcement around harmful product categories elevates investment in automated pre-screening capabilities as a competitive necessity.
For Market Incumbents: Anchor premium rate card positions through exclusive airport concession renewals and fiber-connected highway corridor dominance. Defensive consolidation should prioritize static-to-digital conversion programs in Sandton and Cape Town CBD zones where retail media convergence commands measurement premiums. JCDecaux South Africa's network control exemplifies the concession leverage required to resist margin compression from programmatic price transparency.
For New Entrants and Emerging Players: Programmatic trading infrastructure offers a technology-first wedge into remnant inventory monetization for mid-tier media owners. White-space targets concentrate in Eastern Cape township markets where Provantage Media Group's community billboard specialization has not established coverage depth. Gqeberha and rural corridor networks present first-mover positioning for DOOH deployment with lower electrification cost barriers than Gauteng highway conversion.
For Investors and Strategic Acquirers: Private equity firms with media infrastructure portfolios are the most active acquirer in this space, targeting diversified domestic operators with integrated transit and roadside coverage. Long-term viability rests on programmatic platform integration and retail media partnership depth rather than static inventory volume. Acquisition target archetypes include township-specialist billboard operators with municipal permit backlogs and undermonetized digital screen networks. Monitor ICASA's 5G spectrum auction timing and Johannesburg municipal planning department permit issuance velocity as inflection indicators for network expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Programmatic Platform Integration | Private marketplace structures expose remnant inventory to demand-side platforms, compressing sales cycles for JCDecaux and Primedia Outdoor. |
| Static-to-Digital Site Conversion | Highway billboard electrification and fiber connectivity require capital deployment with extended payback periods in peri-urban expansions. |
| Retail Media Partnership | Grocery chains and mall operators monetize in-store digital screens through programmatic pipes, extending DOOH into purchase-intent environments. |
| Automated Compliance Tooling | Pre-screening platforms reduce Advertising Standards Authority approval timelines and lower campaign cancellation risk in sensitive zones. |
| Eastern Cape Geographic Expansion | Underdeveloped DOOH infrastructure in Gqeberha offers first-mover positioning for community-focused inventory plays with limited national operator presence. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with media owners, programmatic platform operators, municipal planning officers, and retail media buyers with secondary validation. Primary sources included JCDecaux South Africa, Primedia Outdoor, and Provantage Media Group executives alongside demand-side platform traders and Advertising Standards Authority compliance officers. Secondary data drew from ICASA spectrum licensing disclosures, Johannesburg and Cape Town municipal bylaws, Film and Publication Board classification determinations, and industry association inventory audits. Bottom-up site-level capacity estimates and top-down advertising spend flows were triangulated to anchor market sizing.
Comparable historical periods spanning pre-pandemic baseline, recovery trajectory, and current normalization phases anchored the forecast window to observable demand patterns. The analytical framework modeled segmentation dimensions across medium type, audience segment, content format, and advertising strategy, with additional granularity for programmatic trading maturity and retail media integration depth. CAGRs were derived from installed base expansion rates, digital conversion timelines, and impression yield improvement curves. Forecast inputs incorporated LED hardware cost deflation, municipal permit issuance velocity, and spectrum allocation trajectories.
The model holds under stable ICASA regulatory implementation and consistent municipal enforcement of existing spatial planning frameworks; deviation in spectrum auction delays or Johannesburg permit moratoria extensions would shift capacity expansion timelines. Forecasts reflect assumptions around hardware import cost stability and programmatic talent pool development. Practitioners should monitor ICASA's 5G licensing calendar and eThekwini planning department permit freeze announcements for early signals of network expansion constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Thailand OOH and DOOH Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Australia OOH and DOOH Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
Programmatic Display Advertising Market
Advertising and Marketing Media
Multiscreen Advertising Market
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
Kids Digital Advertising Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
Global Print Advertising Market
Advertising and Marketing Media
Social Video Advertising Market