
 US Healthcare Advertising Market | 2026-2036
US Healthcare Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare Advertising Market Intelligence
Digital marketing talent scarcity is bifurcating the competitive landscape into agencies with advanced data science capabilities and legacy shops struggling to adapt. Pfizer leverages its in-house creative studios to control messaging consistency across channels. Eli Lilly anchors its strategy in disease-state education campaigns that build prescriber trust before brand conversion. Johnson & Johnson Services Inc. competes through integrated consumer health and pharmaceutical narratives that cross-sell portfolio brands.
Healthcare advertising encompasses paid promotional communications for prescription drugs, medical devices, hospital systems, and health services, regulated by specific disclosure requirements including fair balance of risk and benefit information. Its primary purpose is to influence patient behavior and prescriber choice while complying with strict substantiation standards for efficacy claims. Digital media commands the fastest expansion as programmatic buying and audience segmentation enable precision targeting of patient populations. Television retains the largest share of pharmaceutical budgets due to mass reach among older demographics. Social media campaigns represent an emerging margin pool where platforms negotiate specialized health content moderation protocols.
FDA's Office of Prescription Drug Promotion monitors broadcast and digital direct-to-consumer advertisements for misleading efficacy representations. FTC enforcement actions against unsupported health claims in dietary supplement and telehealth advertising create compliance costs that favor established pharmaceutical advertisers with legal infrastructure. State-level attorneys general in California and New York supplement federal oversight with consumer protection suits targeting deceptive medical marketing. Stakeholders must weigh the capital requirements of first-party health data platforms against the regulatory exposure of third-party audience targeting as privacy rules tighten.
Market Dynamics
Programmatic media buying is decomposing traditional agency relationships as pharmaceutical advertisers build first-party data infrastructure to bypass intermediary markups and comply with tightening HIPAA constraints on patient targeting.
Growth Catalysts
- Connected TV expansion:Streaming platforms enable addressable advertising to specific patient demographics with measurable attribution, drawing budget migration from broadcast television.
- FTC health product guidelines:Enforcement clarity reduces legal uncertainty for compliant advertisers, concentrating spend among established pharmaceutical players with regulatory infrastructure.
- Oncology center clustering:Concentrated prescriber populations in metropolitan hospital networks enable efficient field marketing deployment and localized digital geofencing campaigns.
Market Restraints
- FDA fair balance requirements:Mandatory risk disclosure in direct-to-consumer advertisements consumes creative runtime and degrades message retention among viewers.
- First-party data infrastructure costs:Building compliant health data platforms requires capital investment that excludes mid-sized agencies from precision targeting capabilities.
- California attorney general enforcement:State-level consumer protection suits create jurisdictional compliance complexity beyond federal FDA oversight.
Strategic Opportunities
- Texas metropolitan hospital networks:Underserved prescriber concentration in Dallas and Houston offers lower CPMs than saturated California and New York markets.
- Social media health content protocols:Platform-specific moderation frameworks for pharmaceutical messaging create new inventory pools with reduced competition.
- Telehealth integration:Convergence of advertising and virtual care platforms enables closed-loop attribution from impression to prescription fulfillment.
Industry Challenges
- Data science talent scarcity:Programmatic buying and audience segmentation require specialized skills that legacy agency workforces lack.
- Cross-channel message consistency:Maintaining compliant fair balance across streaming, social, and search formats demands integrated creative operations that strain fragmented agency structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare Advertising Market |
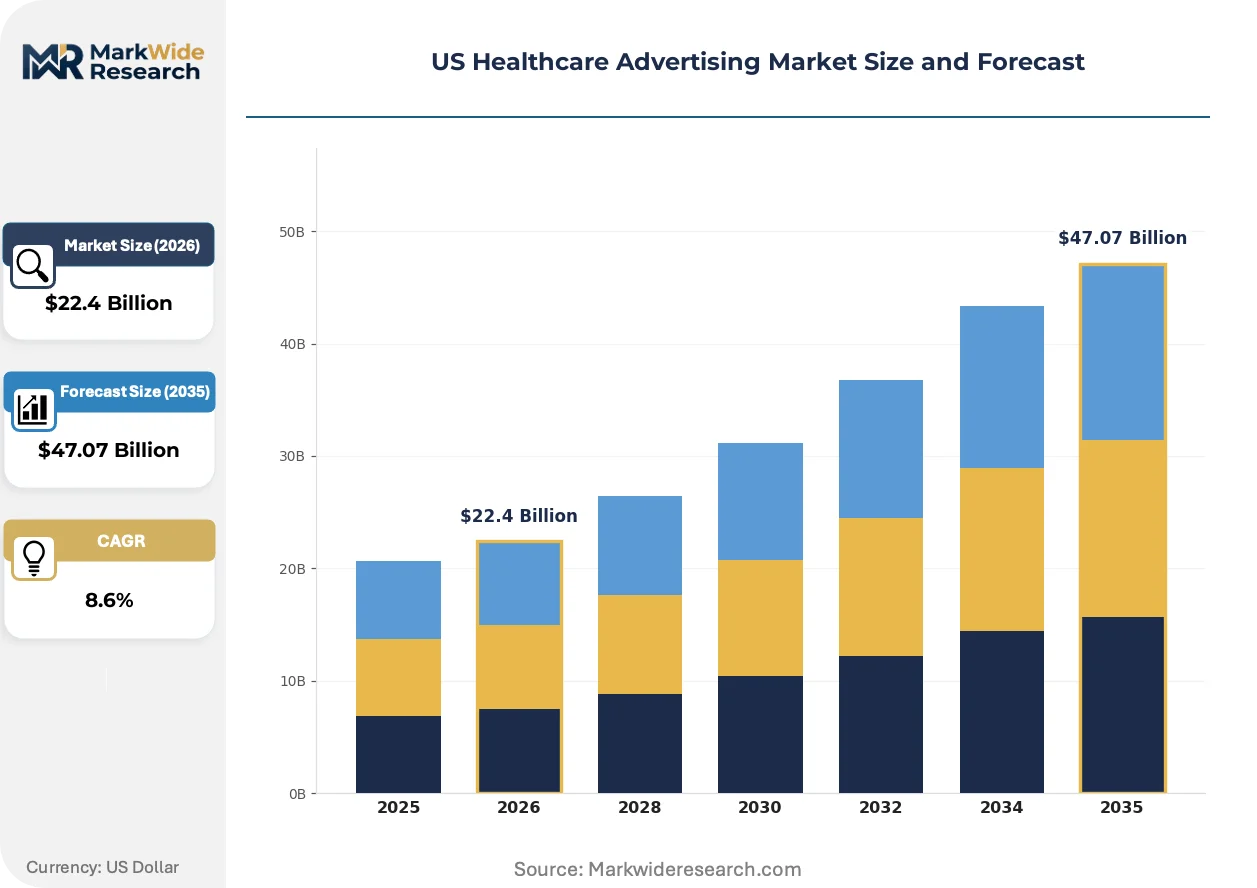
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $47.07 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Digital, Television, Print, Radio Target Audience: Patients, Healthcare Professionals, Caregivers, Employers Ad Format: Display Ads, Video Ads, Sponsored Content, Social Media Campaigns Service Type: Branding, Awareness Campaigns, Lead Generation, Retargeting |
| Companies Covered | Johnson & Johnson Services Inc., Pfizer Inc., Eli Lilly and Company, Merck & Co. Inc., AstraZeneca plc, GSK plc, Novartis AG, Sanofi S.A., F. Hoffmann-La Roche Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare Advertising Market Strategic Shifts & Innovations
Artificial intelligence is restructuring how pharmaceutical advertisers generate, test, and deploy creative assets across regulated channels.
Generative AI tools for pharmaceutical creative development are decomposing traditional copywriting and visual production workflows. Mid-sized agencies adopt automated variant generation to compete with in-house studios at Pfizer and Eli Lilly. This technology is compressing production timelines from weeks to days while forcing agencies to restructure creative departments around prompt engineering and regulatory pre-approval systems.
FDA's Office of Prescription Drug Promotion is intensifying scrutiny of AI-generated claims in digital advertisements. The regulator now requires human substantiation review for algorithmically drafted efficacy language. Broadcast and connected TV direct-to-consumer campaigns face the steepest compliance adjustments as advertisers implement automated flagging systems paired with legal team checkpoints.
Patient advocacy organizations now demand co-creation rights in disease-state education campaigns. Pharmaceutical advertisers respond by embedding community representatives in creative development rather than treating them as post-hoc validators. This behavioral shift is most visible in oncology advertising, where survivor narratives require authentic stakeholder input to pass internal medical-legal review and avoid social media backlash.
US Healthcare Advertising Market Segmentation
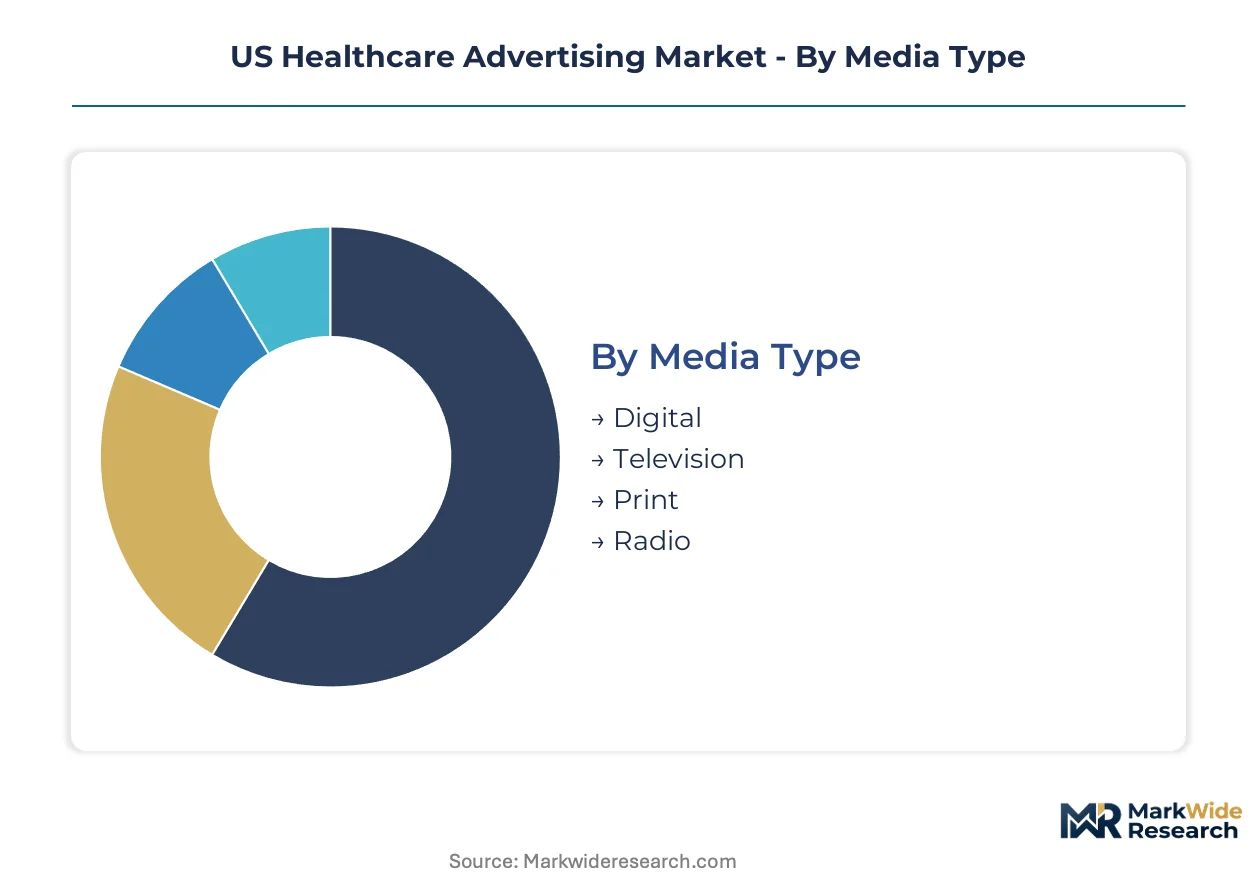
Healthcare advertising segmentation reveals how budget allocation splits across channels with divergent compliance burdens and audience precision. Pharmaceutical advertisers prioritize segments offering closed-loop attribution while navigating FDA fair balance requirements.
Media Type:
Margin pools concentrate in addressable inventory where first-party data enables HIPAA-compliant patient targeting without intermediary platforms.
- Digital:Programmatic buying across endemic health sites and connected TV enables geofenced targeting of oncology centers in Texas and California. FDA's Office of Prescription Drug Promotion monitors these channels for misleading efficacy claims, raising compliance infrastructure costs.
- Television:Broadcast and cable retain the largest share of pharmaceutical budgets due to mass reach among Medicare-eligible demographics. Mandatory risk disclosure consumes creative runtime, degrading message retention.
- Print:Medical journal advertising targets prescriber audiences with detailed efficacy data. Declining readership concentrates spend in top-tier publications.
- Radio:Local spot advertising supports hospital system campaigns and regional pharmacy chains. Limited fair balance flexibility constrains direct-to-consumer drug promotion.
Digital holds installed capacity. Television is rotating up the share rankings as connected TV subsumes traditional broadcast budgets.
Target Audience:
Customer type determines creative complexity, with professional-facing content requiring denser clinical substantiation than consumer campaigns.
- Patients:Direct-to-consumer campaigns demand FDA-compliant fair balance of risk and benefit information. Streaming platforms enable addressable creative versioning by diagnosis and geography.
- Healthcare Professionals:Prescriber-targeted advertising in medical journals and endemic digital platforms emphasizes clinical trial data. Eli Lilly anchors strategy here with disease-state education preceding brand conversion.
- Caregivers:Campaigns targeting family decision-makers require distinct emotional framing and simplified risk communication. Social media health content protocols create specialized inventory pools.
- Employers:B2B health services advertising promotes wellness programs and insurance products. Self-funded plan sponsors in Texas metropolitan hospital networks represent concentrated demand.
Healthcare Professionals holds installed capacity. Patients is climbing the fastest as connected TV enables precision demographic targeting.
Ad Format:
Production cost tiers separate automated variant generation from premium custom creative requiring legal pre-approval.
- Display Ads:Banner and native units on endemic health sites support retargeting of condition-specific audiences. Programmatic infrastructure enables real-time creative optimization.
- Video Ads:Connected TV and pre-roll formats command premium CPMs for pharmaceutical advertisers seeking measurable attribution. FDA scrutiny intensifies for algorithmically generated claims.
- Sponsored Content:Disease-state education articles and patient testimonials require authentic stakeholder co-creation to pass medical-legal review. Survivor narratives dominate oncology advertising.
- Social Media Campaigns:Platform-specific moderation frameworks for pharmaceutical messaging create emerging margin pools with reduced competition. California attorney general enforcement adds jurisdictional complexity.
Video Ads holds installed capacity. Social Media Campaigns is gaining share fastest as platforms negotiate specialized health protocols.
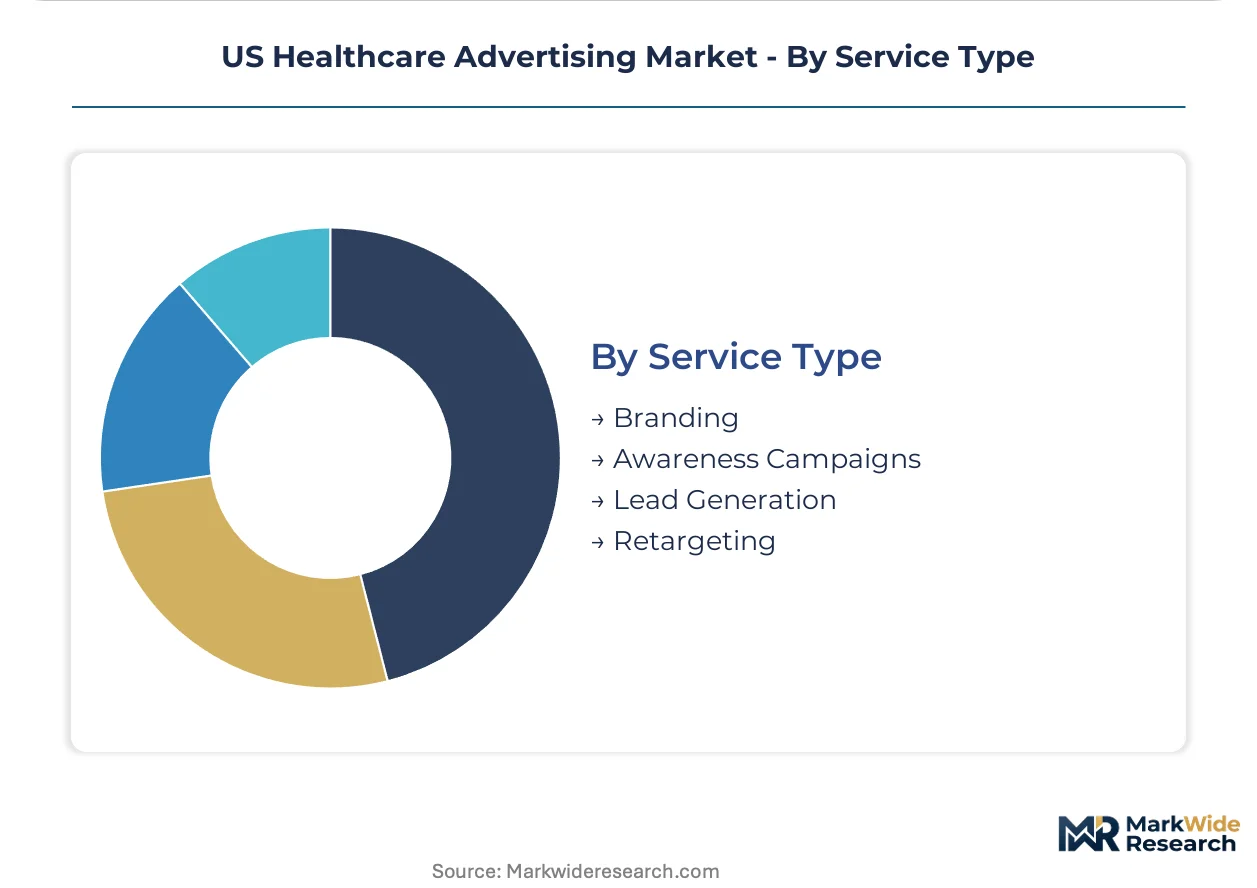
Service Type:
Maturity curves separate established branding disciplines from emerging performance marketing requiring closed-loop attribution infrastructure.
- Branding:Portfolio-level narrative development integrates consumer health and pharmaceutical divisions. Johnson & Johnson Services Inc. competes through cross-selling campaigns.
- Awareness Campaigns:Disease-state education builds prescriber trust before brand-specific conversion. Patient advocacy organizations now demand embedded co-creation rights.
- Lead Generation:Telehealth integration enables direct appointment scheduling from advertisement click-through. Convergence of advertising and virtual care platforms creates attribution advantages.
- Retargeting:First-party data infrastructure supports HIPAA-compliant audience re-engagement. Capital requirements exclude mid-sized agencies from precision capabilities.
Branding holds installed capacity. Lead Generation is rotating up the share rankings through telehealth platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California, Texas, and New York concentrate healthcare advertising spend through distinct channel mixes—streaming platforms dominate West Coast campaigns while Texas emphasizes hospital network geofencing and New York retains broadcast television for Medicare-eligible audiences.
California
Oncology center clustering in Los Angeles and San Francisco drives demand for precision targeting capabilities. The state's attorney general supplements FDA oversight with consumer protection suits targeting deceptive medical marketing. Digital agencies in Silicon Valley build first-party data infrastructure to serve pharmaceutical advertisers navigating HIPAA constraints.
Texas
Metropolitan hospital networks in Dallas and Houston offer underserved prescriber concentrations with lower CPMs than coastal markets. State regulations align with federal FTC health product guidelines while allowing flexible telehealth integration for closed-loop attribution. Self-funded employer plans in the Dallas-Fort Worth corridor generate concentrated B2B health services advertising demand.
New York
Medicare-eligible demographics in the New York Metro sustain broadcast television's largest share of pharmaceutical budgets. The state attorney general enforces consumer protection standards that exceed federal baselines, creating jurisdictional compliance complexity. Manhattan-based media buyers specialize in integrated campaigns spanning connected TV and endemic health platforms.
Greater Boston
Academic medical centers and biotech clusters generate specialized advertising for clinical trial recruitment and prescriber education. Massachusetts aligns with FDA fair balance requirements while supporting disease-state education campaigns through research institution partnerships. Cambridge-area agencies focus on oncology and rare disease narratives requiring dense clinical substantiation.
Florida
Retiree density in the Southeast corridor sustains direct-to-consumer television campaigns with mandatory risk disclosure formats. The state's regulatory environment defers to federal FDA oversight for pharmaceutical advertising while permitting aggressive telehealth platform integration. Miami-based hospital systems deploy localized digital geofencing to capture seasonal population flows.
US Healthcare Advertising Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in healthcare advertising. Pharmaceutical manufacturers with in-house creative studios control messaging consistency across streaming and connected TV channels. Mid-sized agencies compete through automated variant generation and disease-state education expertise. Consolidation pressures favor established players with regulatory infrastructure over legacy shops lacking data science capabilities.
Within the integrated manufacturer tier, Johnson & Johnson Services Inc., Pfizer Inc., and Eli Lilly and Company exemplify divergent strategic archetypes. Johnson & Johnson occupies a position emphasizing cross-portfolio consumer health narratives. Pfizer anchors the in-house studio model for channel-consistent messaging control. Eli Lilly exemplifies disease-state education prioritization to build prescriber trust before brand conversion. These three structures represent the dominant competitive templates reshaping agency relationships.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Pfizer Inc. |
| Eli Lilly and Company |
| Merck & Co. Inc. |
| AstraZeneca plc |
| GSK plc |
| Novartis AG |
| Sanofi S.A. |
| F. Hoffmann-La Roche Ltd. |
| Others |
Cost & Logistics Intelligence
FDA's Office of Prescription Drug Promotion gates both creative agency qualification and price differentiation simultaneously, concentrating premium budgets among shops with regulatory infrastructure while excluding mid-sized competitors from precision targeting capabilities. HIPAA constraints on patient data handling further stratify the market, as compliant first-party infrastructure requires capital investment that only integrated manufacturers and established agencies can deploy.
Pricing Analysis
Long-term retainer contracts dominate pharmaceutical advertising relationships, with annual commitments securing dedicated creative teams and regulatory pre-approval workflows. Three-tier pricing structure across premium, standard, and economy levels separates in-house studio operations from full-service agencies and automated variant generation shops. Pricing pressure stems from programmatic buying tools that compress media margins and force creative fee transparency. Hospital networks and regional pharmacy chains exhibit highest price sensitivity, while oncology-focused manufacturers prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Port congestion on the Los Angeles-Long Beach corridor elevates inbound logistics costs for physical production materials and event marketing assets shipped to California-based agencies. Creative talent concentrates in New York, Los Angeles, and London, while technology infrastructure providers cluster in Silicon Valley and Seattle. Raw material dependencies span cloud computing capacity, specialized health data platforms, and broadcast production equipment. Single-source vulnerability runs through dominant programmatic platforms that control addressable inventory access. Distribution runs through direct manufacturer-agency relationships and holding company networks that aggregate media buying power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of data science talent capable of navigating HIPAA-compliant audience segmentation is bifurcating competitive outcomes, rewarding organizations that build captive capabilities while marginalizing legacy shops dependent on generalist workforces.
For Market Incumbents: Fortify regulatory infrastructure investments to maintain messaging control as FDA intensifies AI-generated claim scrutiny. Deepen vertical integration into first-party data platforms to bypass intermediary markups and capture closed-loop attribution advantages. Counter the threat of automated variant generation tools by embedding legal checkpoints earlier in creative workflows. For New Entrants and Emerging Players: FDA's accelerated review pathway for disease-state education campaigns offers a certification fast-track into prescriber-facing content before brand-specific conversion. Target Texas metropolitan hospital networks where prescriber concentration exceeds agency saturation. Pursue telehealth platform partnerships as the primary go-to-market angle, enabling direct appointment scheduling from advertisement engagement. For Investors and Strategic Acquirers: California attorney general enforcement reshapes the acquisition landscape by elevating compliance infrastructure to primary valuation consideration. Long-term viability across the analysis window favors targets with integrated legal-creative workflows over pure-play digital shops. Monitor FDA guidance on AI substantiation requirements as the critical inflection signal for portfolio rebalancing toward human-in-the-loop capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Infrastructure Buildout | HIPAA-compliant patient targeting bypasses intermediary platforms and captures margin pools in addressable CTV inventory. |
| AI Governance Framework Implementation | Human substantiation review systems satisfy FDA Office of Prescription Drug Promotion requirements for algorithmically drafted claims. |
| Disease-State Education Portfolio Expansion | Prescriber trust-building precedes brand conversion and aligns with Eli Lilly's demonstrated strategic archetype. |
| Telehealth Platform Integration | Closed-loop attribution from impression to prescription fulfillment compresses conversion funnels and demonstrates measurable ROI. |
| Patient Advocacy Co-Creation Protocol | Embedded community representatives in creative development satisfy medical-legal review and mitigate social media backlash risk. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical marketing executives, creative agency account directors, regulatory affairs specialists, and hospital system procurement managers. Secondary validation drew from FDA Office of Prescription Drug Promotion enforcement letters, FTC health product advertising guidelines, CMS Medicare prescription drug data, and hospital network procurement disclosures. Bottom-up spend estimates across media channels and service types were triangulated against top-down manufacturer budget allocations.
Across the analysis window, the forecasting framework modeled segmentation dimensions including media type, target audience, ad format, and service type alongside therapeutic area concentration and regional regulatory cluster. CAGRs were derived from spend trajectory analysis calibrated to historical budget migration patterns from broadcast to connected television. Forecast inputs incorporated programmatic buying adoption curves, HIPAA enforcement intensity, and oncology center geographic clustering.
Decision-makers should treat outputs as directional under assumptions of sustained FDA oversight intensity and stable telehealth platform integration; material deviation would warrant model refresh. Specific risk factors include state-level attorney general enforcement divergence, AI-generated claim regulatory reversals, and privacy rule tightening that restricts third-party audience targeting. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
North America Public Relation Services Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Billboard and Outdoor Advertising Market
Advertising and Marketing Media
Malaysia OOH and DOOH Market
Advertising and Marketing Media
Global Printed Signage Market
Advertising and Marketing Media
In-Game Advertising Market
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
Digital Advertising Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Out of Home Advertising Market