
 N-Methyl Pyrrolidone Market | 2026-2036
N-Methyl Pyrrolidone Market Size, Share, and Industry Trends Forecast 2026-2036
N-Methyl Pyrrolidone Market Foresight
Electronics-grade purity specifications are bifurcating the competitive landscape into premium and commodity supply tiers. BASF SE leverages its integrated petrochemical feedstock network to sustain cost-advantaged production of high-purity grades. Mitsubishi Chemical Corporation anchors its position through captive supply relationships with Japanese semiconductor fabs. Eastman Chemical Company differentiates via proprietary recovery and recycling technologies that reduce virgin solvent intensity.
N-Methyl Pyrrolidone is a polar aprotic solvent with a boiling point of 202°C and dipole moment of 4.09 D, synthesized through gamma-butyrolactone reaction with monomethylamine, valued for its exceptional solvency toward polyvinylidene fluoride binders and aromatic hydrocarbons. Electronics-grade material commands the deepest margin pool as battery cathode manufacturing and semiconductor photoresist stripping drive volume. Industrial-grade supply remains mature across coatings and paints applications where price sensitivity limits premium penetration. Pharmaceutical-grade demand occupies a narrower but defensible niche governed by pharmacopeial compliance.
EPA oversight under the Toxic Substances Control Act and REACH registration requirements in Europe are elevating compliance costs for producers without closed-loop recovery systems. China's MEE environmental enforcement and GB standards for volatile organic compound emissions are reshaping plant-level investment priorities across the Yangtze River Delta manufacturing belt. Stakeholders must weigh backward integration into gamma-butyrolactone against partnership models with established recyclers as regulatory thresholds tighten.
Market Dynamics
Electronics-grade purity requirements are splitting the N-Methyl Pyrrolidone market into two distinct supply tiers, with battery cathode manufacturing and semiconductor photoresist stripping driving premium-grade volume while industrial coatings absorb commodity output.
Growth Catalysts
- Electric vehicle battery cathode production:Lithium-ion cell manufacturers in China, South Korea, and Germany are scaling solvent-intensive electrode coating lines, pulling high-purity N-Methyl Pyrrolidone into dedicated supply contracts.
- REACH registration thresholds:ECHA mandates for substance volume tracking and safety data sheet alignment are forcing solvent recovery investments that favor established producers with closed-loop infrastructure.
- Photoresist stripping in advanced nodes:Sub-7 nanometer semiconductor fabs are specifying ultra-low metal content grades, creating specification premiums that commodity suppliers cannot match.
Market Restraints
- Gamma-butyrolactone feedstock volatility:Petrochemical derivative pricing tracks butadiene and acetylene markets, compressing margin predictability for non-integrated producers.
- Yangtze River Delta concentration:Over half of global electronics-grade capacity sits within a 300-kilometer radius in eastern China, exposing supply chains to localized environmental enforcement actions.
- Aqueous cleaning formulation substitution:Semiconductor fabs in Japan and Taiwan are piloting surfactant-based alternatives for certain stripping steps, threatening volume in mature process nodes.
Strategic Opportunities
- Solid-state battery electrolyte precursors:Sulfide-based cell architectures under development at Korean and Japanese OEMs require polar aprotic solvents for slurry preparation, opening adjacent demand pools.
- India's PLI scheme for cell manufacturing:Reliance Industries and Ola Electric are building gigafactories in Gujarat and Tamil Nadu, creating first-mover advantages for solvent suppliers establishing local blending capacity.
- MEE carbon intensity audits:China's environmental ministry is rewarding facilities with solvent recovery rates above 95 percent with expedited permitting, favoring technology leaders.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP compliance for pharmaceutical-grade material requires 18-24 month stability studies, delaying market entry for new production assets.
- Legacy coatings customer switching costs:Industrial paint formulators in mature markets maintain long-term supply agreements that resist premium-grade substitution despite performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Methyl Pyrrolidone Market |
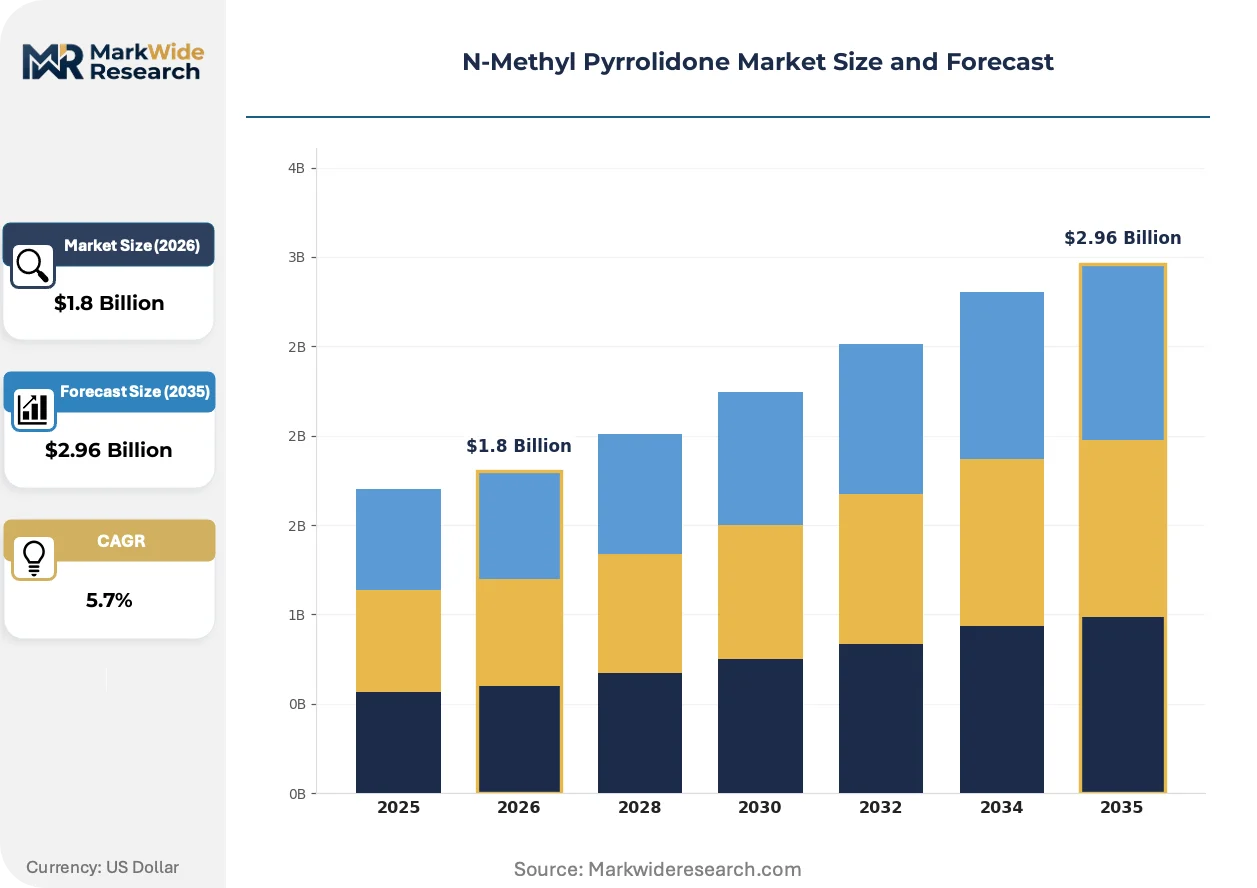
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics Grade, Industrial Grade, Pharmaceutical Grade, Cosmetic Grade Application: Coatings, Paints, Adhesives, Pharmaceuticals End User: Manufacturing, Healthcare, Automotive, Electronics Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Eastman Chemical Company, Shandong Qingyun Changxin Chemical Science-Tech Co., Ltd, BASF SE, Hefei TNJ Chemical Industry Co., Ltd, Puyang Guangming Chemicals Co., Ltd., LyondellBasell Industries N.V., Mitsubishi Chemical Corporation, Zhejiang Realsun Chemical Industry Co., Ltd., Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Methyl Pyrrolidone Market Shifts & Advancements
Closed-loop solvent recovery systems are becoming the primary axis of competitive differentiation as environmental enforcement tightens across major manufacturing jurisdictions and virgin material costs escalate.
Membrane-based separation technology is supplanting thermal distillation for electronics-grade N-Methyl Pyrrolidone reclamation. Korean battery manufacturers are installing on-site recovery units at cathode coating facilities to reduce virgin solvent intensity by 60-70 percent. This shift is compressing demand for merchant high-purity supply while elevating technology licensors and equipment providers in the value chain.
REACH authorization requirements for substances of very high concern are extending compliance obligations to downstream users of recovered solvents. German chemical distributors are demanding chain-of-custody documentation from Asian reclaimers, reshaping trade flows toward integrated producers with certified recovery assets. Battery cathode manufacturers with European offtake agreements are most exposed to documentation burdens.
Long-term offtake contracting is displacing spot market purchasing among top-tier battery cell producers. Korean and Chinese cathode manufacturers are locking in five-to-seven year supply agreements with fixed volume tiers and price adjustment clauses tied to feedstock indices. This concentration of procurement decision-making at headquarters procurement functions is marginalizing smaller regional distributors.
N-Methyl Pyrrolidone Market Segmentation
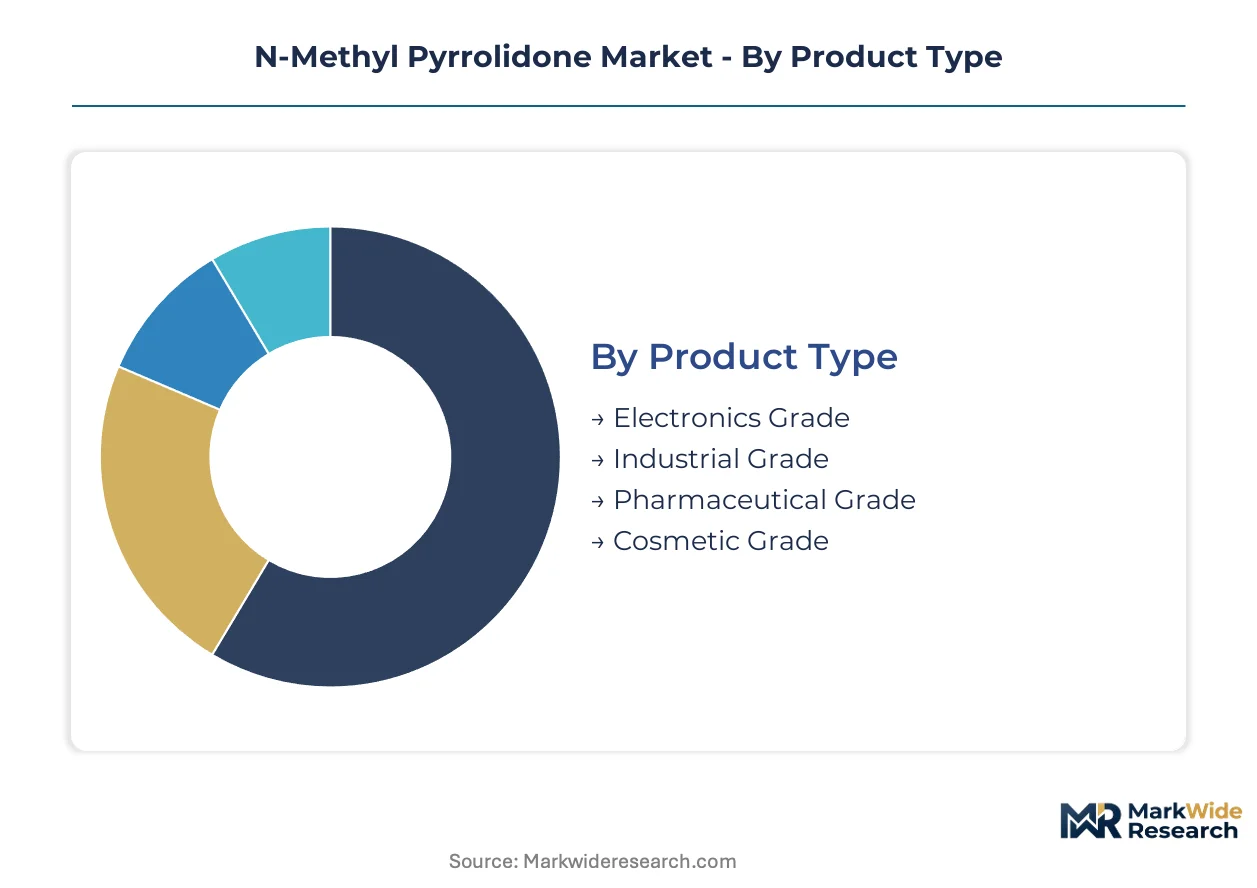
Segmentation in N-Methyl Pyrrolidone reveals how purity specifications and end-use technical requirements dictate channel economics. Electronics-grade material flows through markedly different commercial pathways than industrial formulations, with recovery infrastructure and regulatory documentation becoming decisive in supplier selection.
Product Type:
Electronics-grade product moves predominantly through direct sales channels with long-term contracts, while industrial and pharmaceutical grades utilize distributor networks for fragmented customer bases.
- Electronics Grade:Ultra-low metal content specifications below 10 parts per billion enable cathode slurry preparation for lithium-ion cells and photoresist stripping at sub-7 nanometer semiconductor nodes. Korean and Chinese battery manufacturers are locking in five-to-seven year supply agreements with fixed volume tiers, pulling high-purity material away from spot market availability.
- Industrial Grade:Standard purity levels serve coatings and paints where price sensitivity limits premium penetration. German and Japanese industrial formulators maintain long-term supply agreements that resist grade substitution despite performance advantages, compressing margin pools for commodity producers.
- Pharmaceutical Grade:USP and EP compliance requires 18-24 month stability studies, creating steep barriers to entry for new production assets and concentrating supply among established pharmacopeial-certified producers.
- Cosmetic Grade:Narrow niche governed by cosmetic ingredient regulations in the European Union and United States, with demand concentrated in premium personal care formulations.
By volume, Industrial Grade leads. By growth pace, Electronics Grade is climbing the fastest.
Application:
Application segments align with margin tiers: coatings and paints absorb commodity output at thin spreads, while pharmaceutical and advanced electronics applications sustain premium pricing through technical barriers.
- Coatings:Mature demand across architectural and industrial protective coatings where solvent recovery economics rarely justify closed-loop investment, keeping virgin material intensity high.
- Paints:Price-competitive decorative and automotive refinish segments in China and India where local distributors dominate procurement and resist specification upgrades.
- Adhesives:Polymer dissolution applications for high-performance bonding in automotive and electronics assembly, with demand tracking electric vehicle platform rollouts in Germany and South Korea.
- Pharmaceuticals:Drug synthesis and formulation applications requiring pharmacopeial certification, with procurement concentrated at headquarters level for multinational manufacturers.
Coatings generates the largest absolute volume. Pharmaceuticals holds the steepest expansion trajectory as synthetic complexity increases.
End User:
End user concentration determines contract structure: automotive and electronics buyers centralize procurement, while healthcare and manufacturing segments fragment across regional distributors.
- Manufacturing:Broad industrial base spanning coatings, adhesives, and chemical processing with procurement dispersed across plant-level purchasing functions.
- Healthcare:Pharmaceutical manufacturers and medical device producers requiring pharmacopeial documentation and batch-level traceability, favoring integrated producers with certified quality systems.
- Automotive:Electric vehicle battery cathode production in China, South Korea, and Germany is scaling solvent-intensive electrode coating lines and pulling high-purity material into dedicated supply contracts.
- Electronics:Semiconductor fabs in Taiwan and Japan specifying ultra-low metal content grades for photoresist stripping, creating specification premiums that commodity suppliers cannot match.
Manufacturing absorbs the most volume. Electronics is gaining share fastest as battery production scales.
Distribution Channel:
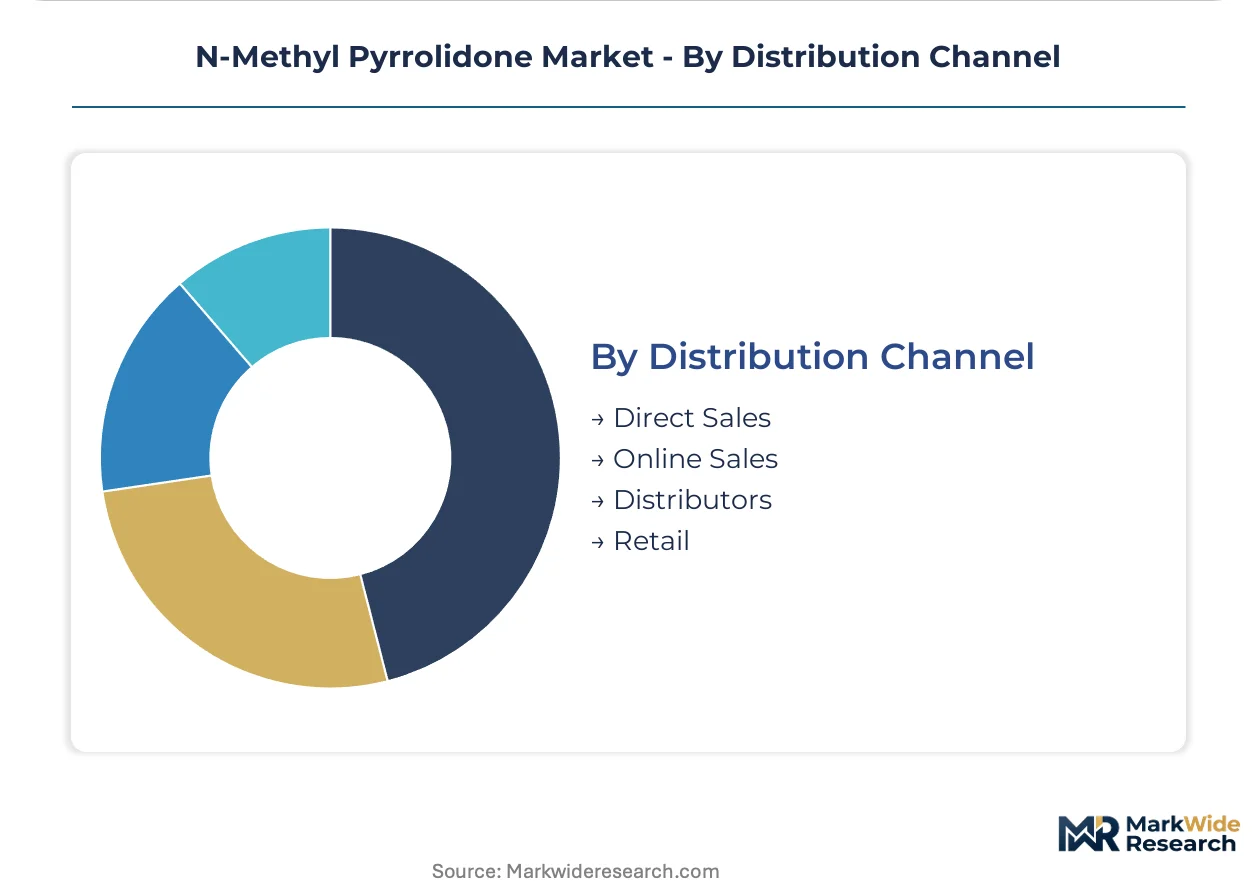
Channel structure reflects customer scale and documentation burden: direct sales dominate where regulatory compliance and technical service requirements are highest.
- Direct Sales:Long-term contracts with Korean and Chinese cathode manufacturers, German semiconductor chemical distributors, and multinational pharmaceutical producers requiring chain-of-custody documentation.
- Online Sales:Emerging channel for small-volume industrial buyers and research institutions, constrained by hazardous material shipping regulations and bulk packaging economics.
- Distributors:Regional chemical distributors serving fragmented coatings and paints customers in mature markets, with German distributors demanding REACH-compliant documentation from Asian reclaimers.
- Retail:Minimal presence limited to specialty solvent blends for consumer and light industrial applications, with regulatory labeling requirements suppressing growth.
Distributors handle the largest volume flow. Direct Sales is expanding most quickly as battery and semiconductor producers consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Half of global electronics-grade capacity clusters within 300 kilometers of Shanghai, exposing supply chains to localized environmental enforcement while concentrating technical expertise and feedstock access.
China
Cathode coating lines for lithium-ion cells at CATL and BYD pull high-purity solvent into dedicated supply contracts across Jiangsu and Zhejiang provinces. MEE carbon intensity audits reward facilities with recovery rates above 95 percent with expedited permitting. The Yangtze River Delta manufacturing belt hosts the densest concentration of battery and semiconductor chemical processing globally.
South Korea
LG Energy Solution and Samsung SDI are scaling electrode production for European and North American EV markets, driving solvent-intensive manufacturing at Gyeonggi and Ulsan complexes. K-REACH alignment with EU substance tracking requirements elevates documentation burdens for imported reclaimed material. Korean battery manufacturers are installing on-site recovery units to reduce virgin solvent intensity.
Germany
BASF SE leverages integrated petrochemical feedstock networks at Ludwigshafen to sustain cost-advantaged production of high-purity grades for domestic cathode manufacturers. ECHA mandates for substance volume tracking and safety data sheet alignment force solvent recovery investments that favor established producers. German chemical distributors are demanding chain-of-custody documentation from Asian reclaimers, reshaping trade flows.
United States
EPA oversight under the Toxic Substances Control Act elevates compliance costs for producers without closed-loop recovery systems, particularly affecting merchant suppliers serving semiconductor fabs in Arizona and Texas. The Inflation Reduction Act's domestic content incentives are pulling battery cell manufacturing toward Michigan and Georgia, creating new demand nodes for electronics-grade material.
Japan
Mitsubishi Chemical Corporation anchors supply relationships with Tokyo Electron and Shin-Etsu Chemical for photoresist stripping at sub-7 nanometer nodes, where ultra-low metal content specifications create insurmountable barriers for commodity suppliers. METI guidance on critical chemical supply chain resilience is encouraging domestic stockpiling and dual-sourcing arrangements.
N-Methyl Pyrrolidone Market Competitive Landscape
Concentration sits with integrated petrochemical majors and regional Chinese producers that control gamma-butyrolactone feedstock access. Three archetypes dominate: multinational chemical conglomerates with backward integration into butadiene derivatives, mid-scale Chinese specialists serving battery supply chains through geographic proximity, and technology licensors monetizing membrane-based recovery systems. Competitive moves center on capacity expansion in Yangtze River Delta free trade zones and strategic partnerships with Korean cathode manufacturers seeking supply security.
Within the integrated multinational tier, BASF SE and Mitsubishi Chemical Corporation exemplify archetypes built on captive feedstock networks and long-term fab relationships respectively. Among Chinese specialists, Shandong Qingyun Changxin Chemical Science-Tech Co., Ltd and Zhejiang Realsun Chemical Industry Co., Ltd occupy positions shaped by proximity to battery manufacturing clusters and responsiveness to MEE environmental enforcement. Eastman Chemical Company represents the technology-differentiated vector, with market positioning derived from proprietary recovery and recycling capabilities rather than virgin production scale.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Shandong Qingyun Changxin Chemical Science-Tech Co., Ltd |
| BASF SE |
| Hefei TNJ Chemical Industry Co., Ltd |
| Puyang Guangming Chemicals Co., Ltd. |
| LyondellBasell Industries N.V. |
| Mitsubishi Chemical Corporation |
| Zhejiang Realsun Chemical Industry Co., Ltd. |
| Ashland |
| Others |
Supply & Pricing Matrix
Forty-five to sixty days of inventory cover for electronics-grade material signals tight supply discipline in a market where Yangtze River Delta concentration grants Chinese producers outsized pricing leverage over Korean and German cathode manufacturers. This lead-time band compresses further when MEE environmental audits trigger unplanned maintenance at Jiangsu purification facilities, forcing buyers into premium spot purchases.
Pricing Analysis
REACH registration thresholds dictate the pricing tier structure across the N-Methyl Pyrrolidone market, separating certified reclaimers with closed-loop documentation from commodity suppliers facing authorization barriers. Three-tier pricing structure across electronics, industrial, and pharmaceutical grades reflects purity certification levels and chain-of-custody compliance costs. Cost compression in industrial-grade supply is intensifying because coatings formulators resist specification upgrades despite performance advantages. Battery cathode manufacturers show least price sensitivity, accepting fixed-volume premiums for five-to-seven year offtake security.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elevate landed costs for European distributors sourcing reclaimed material from Yangtze River Delta reclaimers. Supply concentrates in China, South Korea, and Germany, with over half of electronics-grade capacity clustering within 300 kilometers of Shanghai. Feedstock dependency rests on gamma-butyrolactone derived from butadiene and acetylene derivatives, plus monomethylamine supply from regional ammonia producers. Single-source vulnerability runs through Yangtze River Delta environmental enforcement exposure. Distribution runs through direct long-term contracts for premium grades and regional chemical distributors for fragmented industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proprietary membrane-based recovery technology represents the scarce capability that separates technology-differentiated suppliers from feedstock-dependent commodity producers in this market. Mastery of closed-loop solvent reclamation at 95-plus percent recovery rates now determines permitting access and margin sustainability.
For Market Incumbents: Consolidate recovery technology leadership through exclusive licensing arrangements with Korean equipment providers and capacity additions in Jiangsu free trade zones. Aqueous cleaning formulation substitution threatens mature semiconductor process nodes, demanding accelerated R&D into solid-state battery electrolyte precursor applications. Captive gamma-butyrolactone supply remains the decisive lever against feedstock volatility. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade certification to exploit 18-24 month stability study barriers that deter rapid competitor entry. India's PLI scheme for cell manufacturing offers the most penetrable geography, with Gujarat and Tamil Nadu gigafactories requiring local blending capacity. Partner with established European distributors to satisfy German chain-of-custody documentation requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because REACH authorization and MEE carbon intensity audits will progressively exclude non-integrated reclaimers. Target technology licensors with proven membrane separation systems and established relationships with Korean cathode manufacturers. Watch for Korean OEM solid-state battery pilot announcements as the inflection signal for sulfide-based electrolyte precursor demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gamma-Butyrolactone | BASF SE leverages Ludwigshafen petrochemical networks to insulate margin from butadiene volatility. |
| On-Site Recovery Unit Installation | LG Energy Solution reduces virgin solvent intensity by 60-70 percent at Gyeonggi cathode coating lines. |
| Pharmaceutical-Grade Certification Investment | USP and EP compliance creates 18-24 month barriers that concentrate supply among established producers. |
| Long-Term Supply Agreement Structuring | CATL and BYD lock five-to-seven year contracts with fixed volume tiers tied to feedstock indices. |
| Joint Venture with Equipment Technology Licensor | Membrane-based separation partnerships accelerate MEE permitting for 95-plus percent recovery rates. |
Research Methodology
Desk research of customs trade data, SEC 10-K filings, and ECHA registration databases preceded structured interviews with cathode coating plant managers, Korean battery procurement leads, German semiconductor chemical distributors, and membrane separation technology licensors. Primary fieldwork with downstream OEMs validated secondary estimates of recovery system installation rates and virgin solvent intensity trends. Bottom-up capacity modeling and top-down demand triangulation from electric vehicle production forecasts were cross-referenced for convergence.
Variance decomposition across grade tier, end-use industry, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume build-ups rather than aggregate trend extrapolation. Forecast inputs incorporated MEE carbon intensity audit schedules, K-REACH alignment timelines, and solid-state battery electrolyte precursor development milestones at Korean and Japanese OEMs.
Material uncertainties — feedstock derivative price spikes, unplanned Yangtze River Delta environmental enforcement actions, and aqueous cleaning formulation substitution rates in mature semiconductor nodes — sit outside the modeled envelope. Forecasts reflect documented assumptions about recovery technology adoption curves and regulatory threshold enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Monochlorobenzene Market
Solvents
Para Nitrochlorobenzene Market
Solvents
Chloroacetonitrile Market
Solvents
Citrus Solvents Market
Solvents
Mono Propylene Glycol Market
Solvents
Fluorinated Solvents Market
Solvents
Global Ethyl Lactate Market
Solvents
Wax Dispersion Market
Solvents
1, 1-Difluoroethane Market
Solvents
Asia Pacific Industrial Solvents Market
Solvents
Global Solvents Market
Solvents
North America Toluene Market
Solvents
Vapor Degreasing Solvents Market
Solvents
Europe Acetonitrile Market
Solvents
2-Butanone Market
Solvents
Oxygenated Solvents Market