
 Alkyl Acetates Market | 2026-2036
Alkyl Acetates Market Size, Share, and Industry Trends Forecast 2026-2036
Alkyl Acetates Market Analysis
Pharmaceutical-grade specification upgrades are collapsing the gap between industrial and refined alkyl acetate tiers. Eastman Chemical Company leverages its integrated acetic acid position to sustain cost-advantaged supply of high-purity esters. INEOS anchors European supply through dedicated oxo-alcohol and ester assets at Rotterdam and Lavéra. Yangtze River Acetyls dominates captive acetyl chemistry flows into acetate esters for Asian coatings demand.
Alkyl acetates are ester compounds formed from acetic acid and alcohols, typically manufactured via Fischer esterification or carbonylation routes, with purity grades spanning industrial solvents to fragrance-grade specifications above 99.5 percent. These compounds function primarily as solvents, intermediates, and flavoring or fragrance carriers across process industries. Acetate solvents leads product type segmentation due to entrenched demand from paints and coatings formulators, while acetate plasticizers captures faster structural growth as phthalate substitution accelerates in flexible PVC applications. The solvents segment concentrates margin pools in pharmaceutical-grade and electronics-grade specifications where impurity thresholds tighten.
EPA hazardous air pollutant standards under NESHAP constrain solvent emissions from coatings operations, pushing formulators toward higher-purity, lower-VOC alkyl acetate grades. REACH registration requirements and ECHA substance evaluation cycles in Europe impose full supply chain transparency on importers, favoring producers with documented substance dossiers. FDA food additive and indirect food contact regulations govern acetate ester use in flavoring applications, creating qualification barriers for non-cGMP suppliers. Stakeholders must monitor evolving solvent exemption lists and bio-based content thresholds as regulatory differentiation becomes a procurement filter.
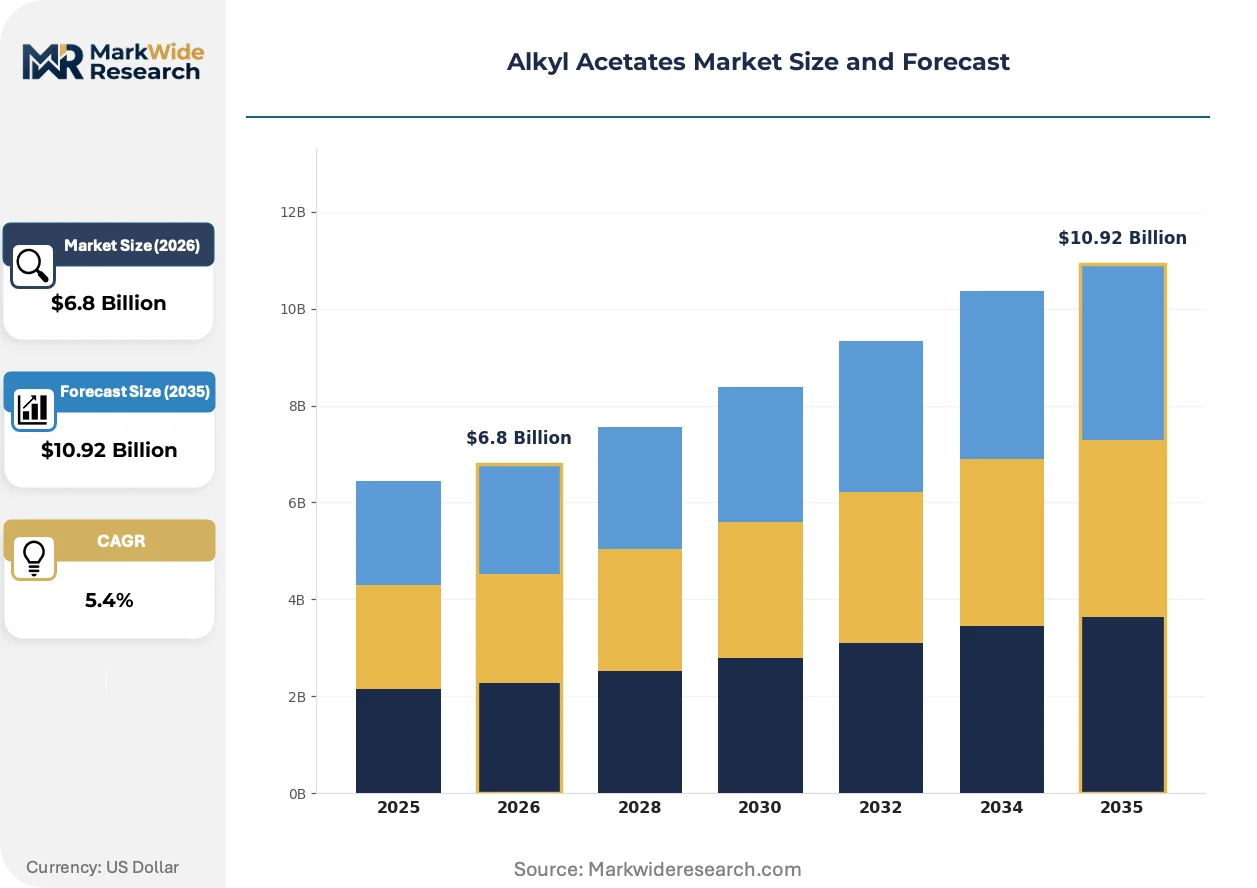
Market Dynamics
Pharmaceutical-grade purity thresholds are collapsing the historical gap between industrial and refined alkyl acetate tiers, forcing suppliers to requalify existing capacity rather than build new assets. This specification compression is redrawing margin pools across the value chain.
Growth Catalysts
- EPA NESHAP solvent standards:Hazardous air pollutant limits on coatings operations are pulling formulators toward higher-purity, lower-VOC alkyl acetate grades that reduce emissions compliance burden.
- Phthalate substitution in flexible PVC:Acetate plasticizers are capturing structural growth as non-phthalate alternatives gain preference in medical tubing, food packaging, and children's products.
- China coatings capacity expansion:Acetic acid feedstock availability and regional supply chain investment are concentrating acetate ester demand in East Asian manufacturing clusters.
Market Restraints
- Acetic acid price volatility:Feedstock cost swings compress ester margins unpredictably, particularly for non-integrated producers lacking captive acetyl chemistry.
- REACH registration burden:Full supply chain transparency requirements and ECHA substance evaluation cycles impose qualification barriers on importers without documented dossiers.
- Waterborne coating substitution:Solvent-based systems face displacement in architectural applications where aqueous technologies meet performance thresholds.
Strategic Opportunities
- Bio-based content mandates:EU Green Deal thresholds and emerging corporate sustainability procurement filters create premium positioning for esters with verified renewable carbon content.
- Electronics-grade specifications:Semiconductor and display manufacturing in South Korea and Taiwan are opening ultra-high-purity acetate demand with impurity thresholds below 10 parts per billion.
- Direct pharmaceutical supply contracts:cGMP-certified producers can bypass distributor markups by qualifying directly with formulation houses facing FDA drug master file requirements.
Industry Challenges
- Analytical chemistry talent scarcity:Gas chromatography and mass spectrometry expertise for trace impurity detection is concentrated among retiring specialists in European and North American laboratories.
- cGMP facility retrofit costs:Existing industrial ester plants require capital-intensive cleanroom modifications, dedicated utilities, and validated cleaning protocols to meet pharmaceutical-grade standards.
- Cross-border substance dossier harmonization:Divergent data requirements between REACH, TSCA, and China's MEE chemical inventory create redundant registration expenses for multi-territory suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkyl Acetates Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetate Solvents, Acetate Esters, Acetate Plasticizers, Acetate Coatings End Use Industry: Paints & Coatings, Food & Beverage, Personal Care, Pharmaceuticals Application: Solvent, Flavoring Agent, Fragrance, Intermediate Packaging Type: Drums, Jerricans, Bottles, Bulk Containers |
| Companies Covered | Sipchem, INEOS, Eastman Chemical Company, Arkema, The Dow Chemical Company, Celanese Corporation, Yangtze River Acetyls, Sasol, Korea Alcohol Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkyl Acetates Market Emerging Trajectories
Carbonylation-based ester production routes are gaining traction against conventional Fischer esterification, promising sharper purity profiles and reduced wastewater burden. These process shifts are compressing the technical gap between commodity and specialty grades.
Membrane separation technology for final-stage purification is displacing traditional distillation sequences in high-purity acetate finishing. Electronics and pharmaceutical formulators in Japan and Taiwan are specifying membrane-polished grades for sub-ppm impurity control. This displacement is forcing European and North American producers to license or develop in-house membrane capabilities to defend specification-sensitive accounts.
REACH authorization and restriction proposals under ECHA's SVHC roadmap are tightening solvent classification thresholds for reproductive toxicity and environmental persistence. Industrial coatings formulators in Germany and France are pre-emptively reformulating around candidate-listed substances. The affected segments are accelerating qualification of alternative ester blends before sunset dates harden supply risk.
Consolidated procurement by multinational coatings houses is compressing supplier rosters and extending contract durations. PPG, AkzoNobel, and Sherwin-Williams are centralizing acetate buying through regional hubs with unified specification standards. This concentration is most visible in Western Europe, where three distributors now handle the majority of pharmaceutical-grade ester flows into Benelux and Nordic manufacturing sites.
Alkyl Acetates Market Segmentation
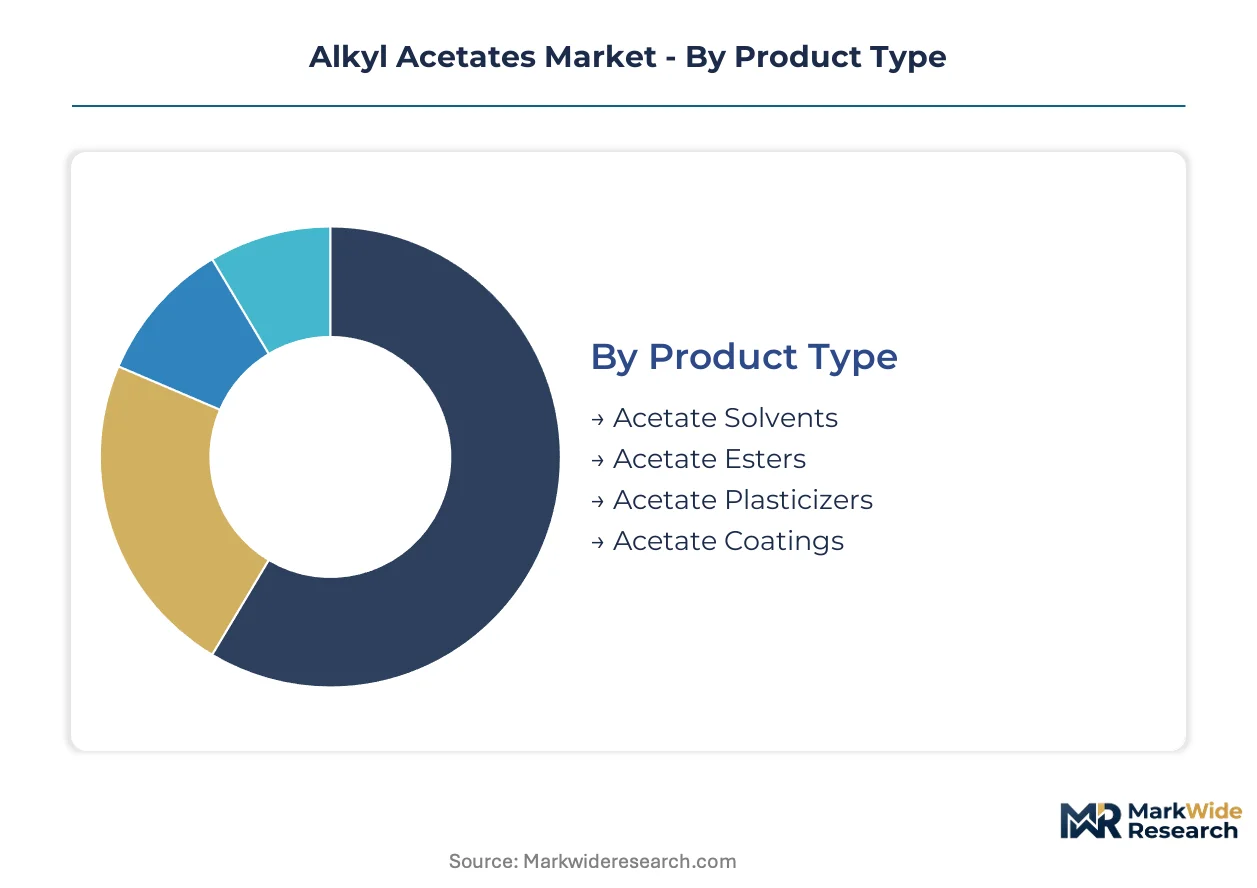
Segmentation in alkyl acetates reveals how purity thresholds and regulatory exposure fragment margin pools across otherwise chemically similar products. Specification-grade differentiation now determines supplier qualification more than molecular structure alone.
Product Type:
Substitution pressure from waterborne technologies and bio-based alternatives hits solvent grades hardest, while plasticizer segments gain defensive positioning through phthalate displacement mandates.
- Acetate Solvents:Industrial-grade esters with purity specifications typically ranging from 85% to 99%, formulated for coatings thinning, extraction processes, and cleaning applications. Paints and coatings formulators in Germany and France are pre-emptively shifting specifications as ECHA evaluates reproductive toxicity classifications for conventional solvent candidates.
- Acetate Plasticizers:Higher-molecular-weight esters engineered for flexible PVC compatibility, delivering plasticizing efficiency without ortho-phthalate structural concerns. Medical tubing manufacturers and food packaging converters in the United States are accelerating qualification under FDA indirect food contact frameworks.
- Acetate Esters:Mid-tier refined grades serving fragrance compounding and specialty chemical synthesis.
- Acetate Coatings:Pre-formulated resin systems incorporating acetate carriers for automotive and industrial OEM applications.
Acetate solvents retain volume leadership; acetate plasticizers hold the steepest expansion curve.
End Use Industry:
Margin concentration follows regulatory stringency, with pharmaceutical and food-contact applications commanding certification premiums over industrial coatings.
- Paints & Coatings:The largest volume sink for industrial-grade acetate solvents, spanning architectural, automotive, and protective formulations. EPA NESHAP hazardous air pollutant limits are forcing U.S. formulators toward higher-purity, lower-VOC ester grades that reduce emissions compliance burdens and avoid solvent mixture reporting thresholds.
- Pharmaceuticals:High-purity acetate solvents and intermediates governed by FDA drug master file requirements and EU GMP Annex 1 contamination control standards. cGMP-certified producers in Switzerland and Ireland are capturing direct supply contracts with formulation houses, bypassing distributor markups through validated manufacturing protocols.
- Food & Beverage:Flavoring-grade esters meeting FDA food additive regulations and EFSA purity specifications for direct and indirect contact.
- Personal Care:Fragrance carriers and solvent systems for cosmetics formulations, subject to EU Cosmetics Regulation (EC) 1223/2009 safety assessments.
Paints and coatings anchors absolute volume; pharmaceuticals delivers the highest margin per kilogram.
Application:
Functional role determines purity investment, with process solvents tolerating broader specifications than molecules entering final consumer products.
- Solvent:Process applications including extraction, crystallization, and reaction media across chemical manufacturing. Electronics-grade specifications for semiconductor and display manufacturing in South Korea and Taiwan are opening ultra-high-purity demand with impurity thresholds below 10 parts per billion.
- Intermediate:Building-block molecules for pharmaceutical active ingredient synthesis and agrochemical production. The segment concentrates value in documented supply chain transparency under REACH registration requirements, favoring producers with complete substance dossiers.
- Flavoring Agent:Food-grade esters delivering characteristic fruity notes to beverages and confectionery.
- Fragrance:Cosmetic and household product applications requiring organoleptic consistency and minimal residual odor.
Solvent applications dominate tonnage; intermediate sales capture the premium pricing tier.
Packaging Type:
Container selection reflects customer scale and regulatory documentation requirements, with bulk formats concentrating among qualified industrial buyers.
- Bulk Containers:ISO tanks and flexitanks for integrated coatings manufacturers and pharmaceutical formulators with validated receiving infrastructure. Multinational coatings houses including PPG, AkzoNobel, and Sherwin-Williams are centralizing acetate procurement through regional hubs with unified specification standards.
- Drums:Standard 200-liter steel and polyethylene drums serving mid-scale industrial users and distributor inventories.
- Jerricans:Portable 20-30 liter containers for laboratory, pilot-scale, and specialty chemical applications.
- Bottles:Small-format packaging for analytical reagent, fragrance compounding, and food-grade sampling requirements.
Bulk containers command the highest volume share; bottles carry the steepest per-liter markup.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports alkyl acetate intermediates to coatings formulators across Germany, the United States, and South Korea, while European and North American producers retain pharmaceutical-grade supply chains domestically.
United States
Coatings manufacturers in Ohio and Texas consume industrial-grade acetate solvents for automotive OEM applications. EPA NESHAP hazardous air pollutant standards constrain solvent emissions, pushing formulators toward higher-purity ester grades. The Gulf Coast petrochemical corridor anchors acetic acid feedstock supply for integrated ester producers.
Germany
Industrial coatings houses in Bavaria and North Rhine-Westphalia pre-emptively reformulate around ECHA SVHC candidate substances. REACH registration requirements impose full supply chain transparency on importers. The Frankfurt-Rhine-Main cluster concentrates pharmaceutical-grade acetate demand from formulation houses.
China
Yangtze River Delta coatings capacity expansion drives acetate ester consumption for architectural and protective applications. MEE chemical inventory regulations tighten substance documentation requirements for domestic producers. Ningbo and Nanjing host integrated acetyl chemistry complexes serving regional acetate supply.
South Korea
Semiconductor and display manufacturers in Gyeonggi Province specify electronics-grade acetates with impurity thresholds below 10 parts per billion. MFDS pharmaceutical regulations govern solvent use in drug manufacturing. The Seoul Capital Area concentrates ultra-high-purity demand from Samsung and LG supply chains.
Switzerland
Pharmaceutical formulation houses in Basel and Zurich source cGMP-certified acetate solvents for active ingredient synthesis. Swissmedic drug manufacturing standards exceed EU GMP Annex 1 baselines. The Basel Life Sciences cluster anchors high-margin pharmaceutical-grade ester procurement.
Alkyl Acetates Market Vendor Landscape
Listed leaders compete with private specialists across integrated acetyl chemistry positions. The vendor base organizes around three tiers: multinational chemical conglomerates with captive feedstock, regional ester specialists serving coatings clusters, and state-affiliated producers leveraging domestic acetic acid supply. Strategic moves concentrate on cGMP facility retrofits and membrane purification licensing.
Within the multinational tier, Eastman Chemical Company and INEOS occupy positions defined by integrated acetic acid and oxo-alcohol assets. Yangtze River Acetyls anchors the state-affiliated archetype with captive supply chain control. These three exemplify how feedstock integration and regional regulatory compliance separate margin pools.
| Leading Market Players |
|---|
| Sipchem |
| INEOS |
| Eastman Chemical Company |
| Arkema |
| The Dow Chemical Company |
| Celanese Corporation |
| Yangtze River Acetyls |
| Sasol |
| Korea Alcohol Industrial |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between coatings manufacturers and integrated acetic acid producers lock in supply access and price visibility across multi-year horizons. These arrangements insulate buyers from feedstock volatility while committing suppliers to volume guarantees that justify cGMP facility investments.
Pricing Analysis
Current-generation Fischer esterification routes command lower unit costs against prior-generation batch processing, while next-generation carbonylation technologies promise sharper purity profiles at capital premiums. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and economy-grade levels separates margin pools, with certification tier and volume scale as primary differentiation drivers. Pricing pressure stems from acetic acid feedstock volatility compressing margins for non-integrated producers. Coatings formulators exhibit highest price sensitivity due to commoditized solvent demand, while pharmaceutical houses accept premiums for validated supply chains.
Supply Chain Analysis
China and the United States anchor acetic acid feedstock production, with Germany and Switzerland concentrating pharmaceutical-grade finishing capacity. Alkyl acetate supply chains draw from methanol, ethanol, and butanol oxo-alcohol streams, plus acetic acid as the core acylating agent. Single-source vulnerability concentrates in Yangtze River Delta integrated complexes serving Asian coatings demand. Distribution runs through regional distributor hubs in Western Europe and direct-supply contracts for qualified pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as waterborne coating technologies and bio-based ester alternatives erode solvent-grade volume. Incumbents must navigate phthalate displacement mandates accelerating acetate plasticizer demand while protecting legacy solvent positions.
For Market Incumbents: Compound defensive positioning through backward integration into acetic acid feedstock and membrane purification technology licensing. Secure cGMP certifications ahead of FDA drug master file requirements tightening supplier rosters. Prioritize long-term offtake contracts with multinational coatings houses centralizing procurement through regional hubs. For New Entrants and Emerging Players: Differentiate on bio-based content verification and electronics-grade impurity specifications below 10 parts per billion. Target South Korean and Taiwanese semiconductor manufacturers with ultra-high-purity acetate demand. Pursue direct qualification with pharmaceutical formulation houses bypassing distributor markups through validated manufacturing protocols. For Investors and Strategic Acquirers: Capital is best deployed toward integrated acetyl chemistry assets with captive feedstock positions and established REACH dossiers. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale alone. Watch for ECHA SVHC sunset dates as inflection indicators accelerating reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| cGMP Facility Retrofit | Enables direct supply contracts with FDA-regulated pharmaceutical formulation houses. |
| Membrane Purification Licensing | Defends specification-sensitive accounts in South Korean electronics manufacturing. |
| Backward Integration into Acetic Acid | Insulates margin pools from feedstock volatility compressing non-integrated producers. |
| Bio-Based Content Certification | Captures EU Green Deal premium positioning for verified renewable carbon esters. |
| REACH Dossier Completion | Eliminates import barriers for European coatings and pharmaceutical supply chains. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant managers at integrated ester producers, procurement leads at coatings OEMs, distribution channel partners, and technical R&D directors; alongside secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance dossier databases. Bottom-up volume modeling triangulated against top-down market sizing across value chain participants.
Across the projection horizon, the analytical framework modeled segmentation dimensions including purity grade tier, end-use industry concentration, packaging format scale, and regional production hub configuration. CAGRs were derived through trend extrapolation of historical volume flows and elasticity-adjusted demand projections. Forecast inputs incorporated EPA NESHAP compliance timelines and ECHA SVHC evaluation cycles as regulatory demand shapers.
Material uncertainties — acetic acid price volatility, REACH authorization outcomes, and waterborne coating substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement intensity and technology adoption curves. Recalibration cycles align with material shifts in ECHA substance evaluation timelines and coatings industry procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Antiknock Agents Market
Additives
Fuel Additives Market
Additives
Oxygen Scavengers Market
Additives
Viscosity Reducing Agents Market
Additives
Maltitol Based on Corn Starch Market
Additives
Glycol Acetate Market
Additives
Defoaming Coating Additives Market
Additives
Global Isononanoic Acid Market
Additives
Anti-Pollution Ingredients Market
Additives
Gelatin Peptones Market
Additives
Apocarotenal Market
Additives
Global Isosorbide Market
Additives
Green Polymer Additive Market
Additives
Indonesia Feed Additives Market
Additives
Butyrate Additives Market
Additives
Phthalate Plasticizer Market