
 Dihydromyrcene Market | 2026-2036
Dihydromyrcene Market Size, Share, and Industry Trends Forecast 2026-2036
Dihydromyrcene Market Outlook
Multi-source procurement for terpene feedstocks is broadening as fragrance compounders reduce reliance on single-origin pinene supplies. Givaudan leverages backward integration into pine-derived raw materials to secure cost-advantaged positions. Firmenich anchors its competitiveness through biotechnology-driven fermentation routes to dihydromyrcene. Symrise competes via specialized extraction capabilities in Southeast Asian plantation networks.
Dihydromyrcene (2,6-dimethyl-2,6-octadiene) is a monocyclic terpene hydrocarbon produced through catalytic hydrogenation of myrcene, typically yielding a colorless liquid with a fresh, citrus-woody odor profile valued at 90-95% purity grades for fragrance applications. Its primary industrial purpose centers on serving as a precursor for menthol synthesis and as a direct fragrance ingredient in fine perfumes, household cleaners, and personal care formulations. Synthetic dihydromyrcene dominates volume flows due to cost scalability and batch consistency, while natural-derived variants command premium positioning in clean-label fragrance portfolios. The fragrance application segment leads value generation, though personal care end-use is expanding fastest as Asian cosmetic manufacturers reformulate with terpene-based alternatives to synthetic musks.
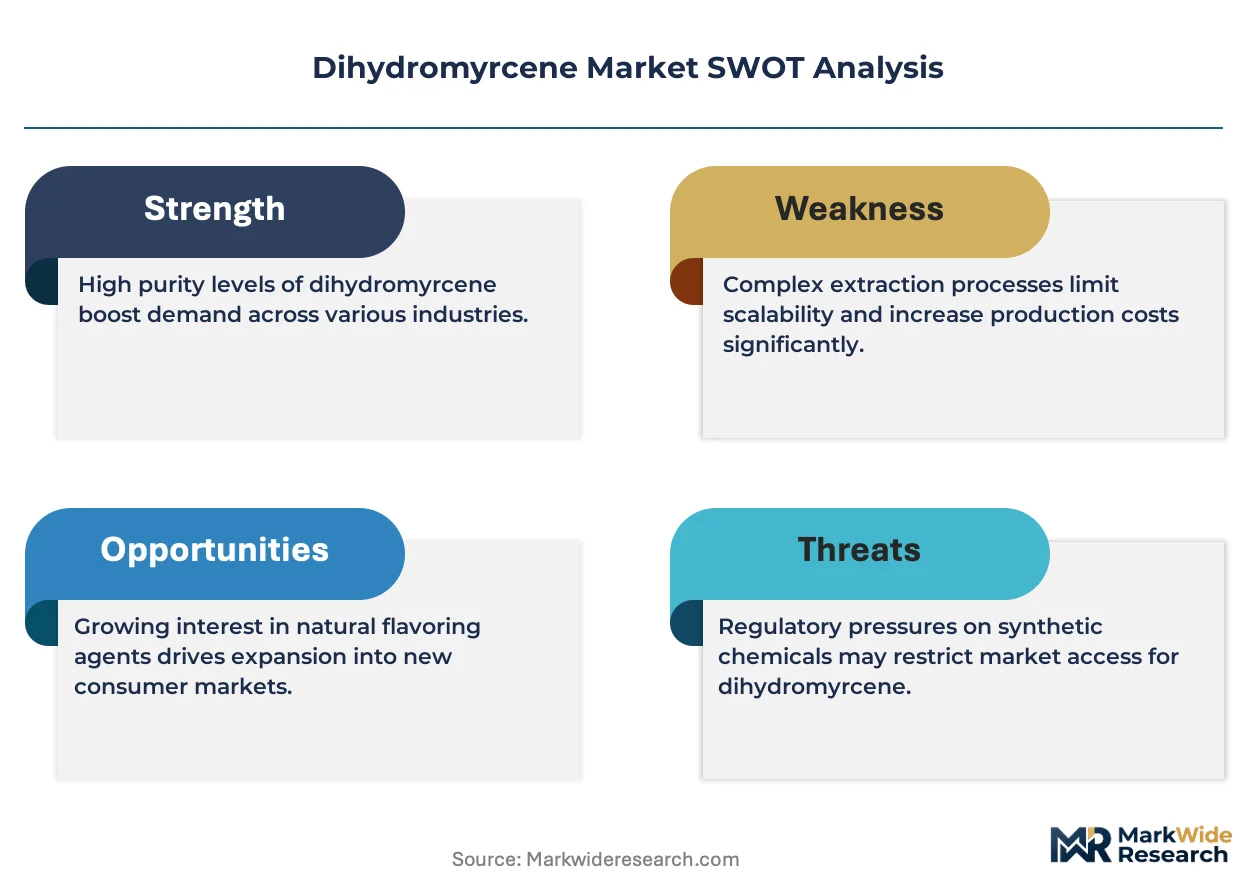
REACH registration requirements under ECHA govern dihydromyrcene import volumes into the European Union, mandating toxicological dossiers that elevate compliance costs for non-European suppliers. EPA oversight under the Toxic Substances Control Act shapes product standards for U.S. industrial solvent applications, particularly regarding volatile organic compound classifications. China's SAMR implements national food additive safety assessments that determine dihydromyrcene eligibility for flavor applications in processed foods. Stakeholders must monitor regulatory divergence between jurisdictions to optimize manufacturing location decisions and product registration strategies.
Market Dynamics
Fragrance compounders face mounting pressure to decouple from volatile pinene supply chains concentrated in Brazilian and Chinese plantation networks, forcing accelerated investment in biotechnology-derived feedstocks and synthetic catalytic routes.
Growth Catalysts
- REACH compliance thresholds:ECHA-mandated purity specifications for terpene imports into the European Union are elevating demand for pharmaceutical-grade dihydromyrcene from certified synthesis facilities.
- Fine perfume reformulation:Luxury fragrance houses in France and Italy are expanding synthetic dihydromyrcene procurement to replace natural myrcene derivatives facing harvest variability.
- Biotechnology maturation:Fermentation-based production pathways using engineered yeast strains are achieving cost parity with petrochemical routes for industrial-scale aroma chemical manufacturing.
Market Restraints
- Pinene feedstock volatility:Brazilian pine resin harvest fluctuations and Chinese gum turpentine output swings create raw material cost instability for conventional hydrogenation processes.
- EPA VOC classifications:The Toxic Substances Control Act designation of certain terpene hydrocarbons as volatile organic compounds restricts industrial solvent applications in U.S. household cleaner formulations.
- Natural extraction yield ceilings:Steam distillation of citrus peel and pine sources cannot scale beyond plantation harvest cycles, capping volume expansion for clean-label fragrance portfolios.
Strategic Opportunities
- Indian flavor compounder expansion:FSSAI regulatory clarity on terpene-based food additives is enabling domestic manufacturers to substitute imported dihydromyrcene with locally synthesized variants.
- Carbon-negative fermentation:Sugar feedstock bioconversion using agricultural waste streams aligns with EU Green Deal emissions targets for cosmetic ingredient supply chains.
- Direct-to-brand digital platforms:Specialty chemical marketplaces are disintermediating traditional distributor networks for mid-size fragrance houses seeking transparent pricing and batch traceability.
Industry Challenges
- Catalytic process engineering expertise:Selective hydrogenation of myrcene to dihydromyrcene without over-reduction requires specialized chemical engineers concentrated in German and Swiss industrial clusters.
- REACH dossier compilation timelines:ECHA registration procedures for new synthesis facilities extend 18-24 months, delaying market entry for emerging Asian producers.
- Legacy equipment retrofit costs:Converting batch hydrogenation reactors for continuous flow processing demands capital outlays that strain mid-cap aroma chemical manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dihydromyrcene Market |
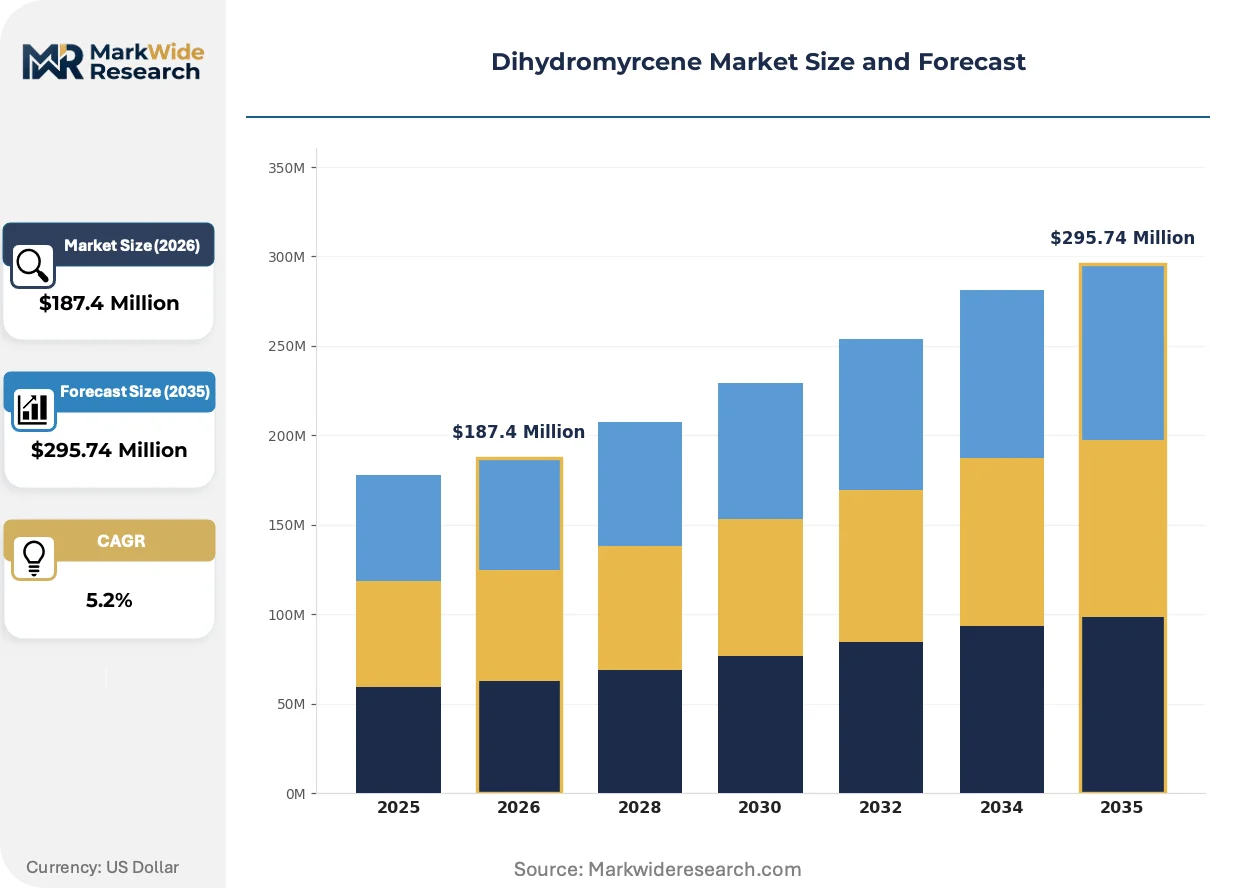
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $295.74 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Dihydromyrcene, Synthetic Dihydromyrcene, Isolated Dihydromyrcene, Blended Dihydromyrcene Application: Fragrance Industry, Food and Beverage, Personal Care, Industrial Solvents End User: Cosmetic Manufacturers, Flavor Houses, Chemical Companies, Food Processors Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Markets |
| Companies Covered | Givaudan, Firmenich, Symrise, IFF, Takasago, DRT, Privi Speciality Chemicals, Sky Dragon Fine-Chem, EcoGreen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dihydromyrcene Market Strategic Shifts
Synthetic biology and precision catalysis are converging to restructure how fragrance precursors reach formulation laboratories, compressing development cycles while fragmenting traditional supply hierarchies.
Continuous flow hydrogenation reactor technology is modularizing dihydromyrcene production economics. Specialty chemical engineers in Basel and Ludwigshafen are retrofitting pilot plants with microchannel reactors that slash residence times from hours to minutes. This modularization is enabling distributed manufacturing footprints closer to European and North American formulation centers, reducing working capital tied to transoceanic inventory.
China's SAMR is tightening food additive safety assessments for terpene derivatives used in flavor applications. Domestic compounders must now submit toxicological data packages previously required only for pharmaceutical-grade materials. Processed food manufacturers are responding by qualifying alternative synthesis routes that preempt stricter purity mandates anticipated under revised GB standards.
Fragrance houses are consolidating supplier relationships around vertically integrated producers capable of certifying carbon intensity per kilogram. Direct sourcing contracts now specify Scope 3 emissions thresholds that exclude traditional plantation-dependent extraction networks. This behavioral pivot is most pronounced among Paris-based luxury groups reformulating heritage perfumes for climate-disclosure compliance under CSRD reporting requirements.
Dihydromyrcene Market Segmentation
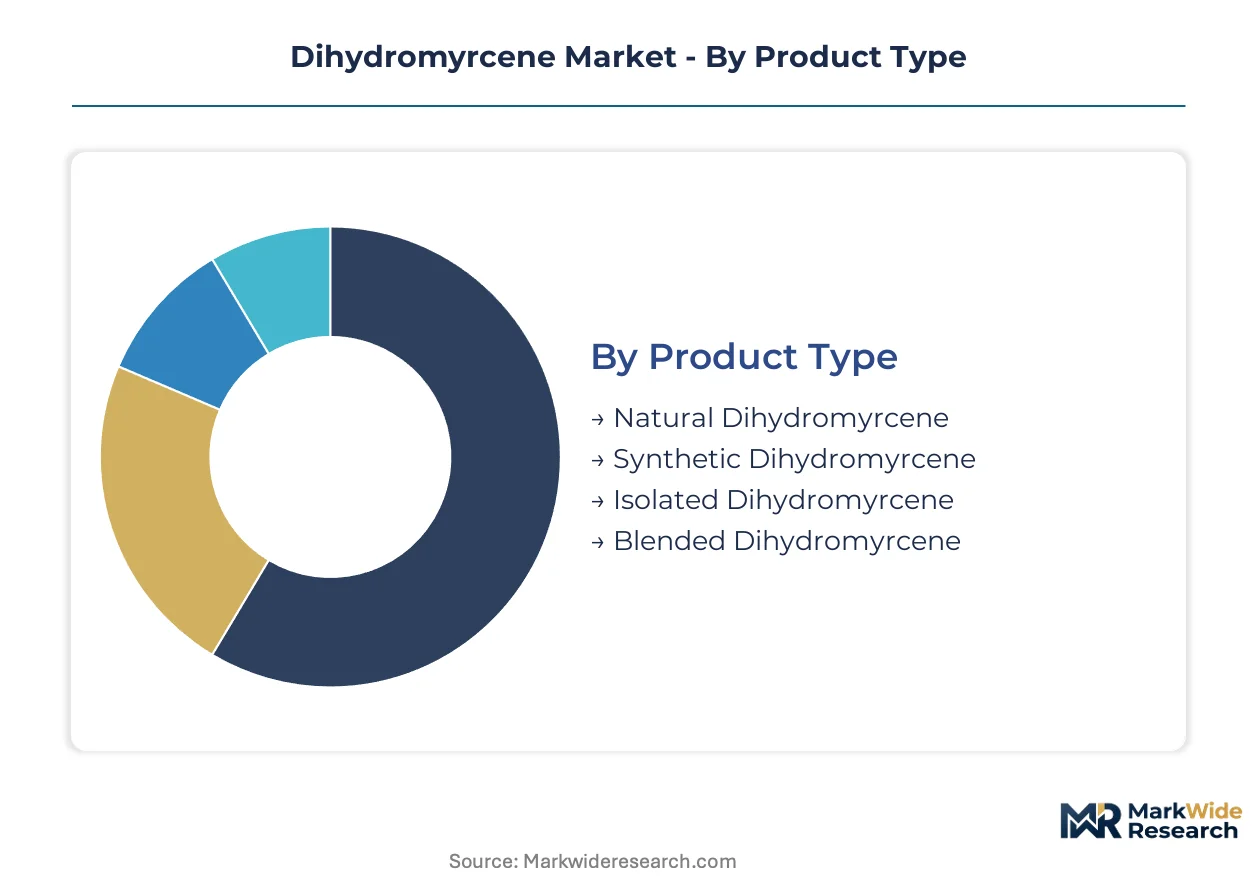
Dihydromyrcene procurement patterns diverge sharply across product grades and end-use specifications. Fragrance compounders prioritize purity thresholds and regulatory certification over unit cost, while industrial buyers optimize for volume scalability and feedstock security.
Product Type:
Reformulation cycles in fine perfumery are accelerating upgrade demand from standard-grade to pharmaceutical-grade materials.
- Synthetic Dihydromyrcene:Catalytic hydrogenation of petrochemical-derived myrcene yields batch-consistent purity above 95%. Fragrance houses in France and Switzerland anchor procurement contracts here for climate-disclosure compliance under CSRD requirements.
- Natural Dihydromyrcene:Steam distillation from pine resin and citrus peel delivers terpene profiles valued in clean-label fragrance portfolios. Yield ceilings from Brazilian plantation harvests constrain volume scaling for mass-market personal care lines.
- Isolated Dihydromyrcene:Chromatographic separation achieves 99% purity for pharmaceutical precursor applications.
- Blended Dihydromyrcene:Formulated mixtures with complementary terpenes optimize odor profiles for budget household cleaner segments.
Synthetic Dihydromyrcene sits at the top of the volume ranking, with Isolated Dihydromyrcene climbing the fastest.
Application:
Cost tier differentiation separates heritage perfume formulations from commodity industrial applications.
- Fragrance Industry:Fine perfume and eau de toilette formulations demand pharmaceutical-grade dihydromyrcene for citrus-woody top notes. Paris-based luxury groups specify Scope 3 emissions thresholds that exclude plantation-dependent extraction networks.
- Personal Care:Asian cosmetic manufacturers reformulate with terpene-based alternatives to synthetic musks in lotions and shampoos. SAMR tightening of GB standards for cosmetic ingredients elevates purity requirements for China-market products.
- Food and Beverage:Flavor applications require FSSAI and SAMR food additive safety assessments for processed food incorporation.
- Industrial Solvents:EPA TSCA volatile organic compound classifications restrict terpene hydrocarbon deployment in U.S. household cleaner formulations.
Fragrance Industry commands the premium pricing tier, while Personal Care expands most quickly.
End User:
Customer type determines procurement sophistication and contract structure complexity.
- Cosmetic Manufacturers:Direct sourcing contracts with carbon intensity certifications per kilogram. Reformulation timelines for climate-disclosure compliance compress supplier qualification cycles.
- Flavor Houses:Givaudan and Firmenich leverage backward integration into pine-derived raw materials and biotechnology fermentation routes respectively.
- Chemical Companies:Industrial-scale buyers prioritize feedstock security through multi-source terpene procurement strategies.
- Food Processors:Processed food manufacturers qualify alternative synthesis routes to preempt stricter GB standards under SAMR revisions.
Flavor Houses dominate contract value, with Cosmetic Manufacturers gaining share fastest.
Distribution Channel:
Supply concentration shapes channel selection between transparency and operational efficiency.
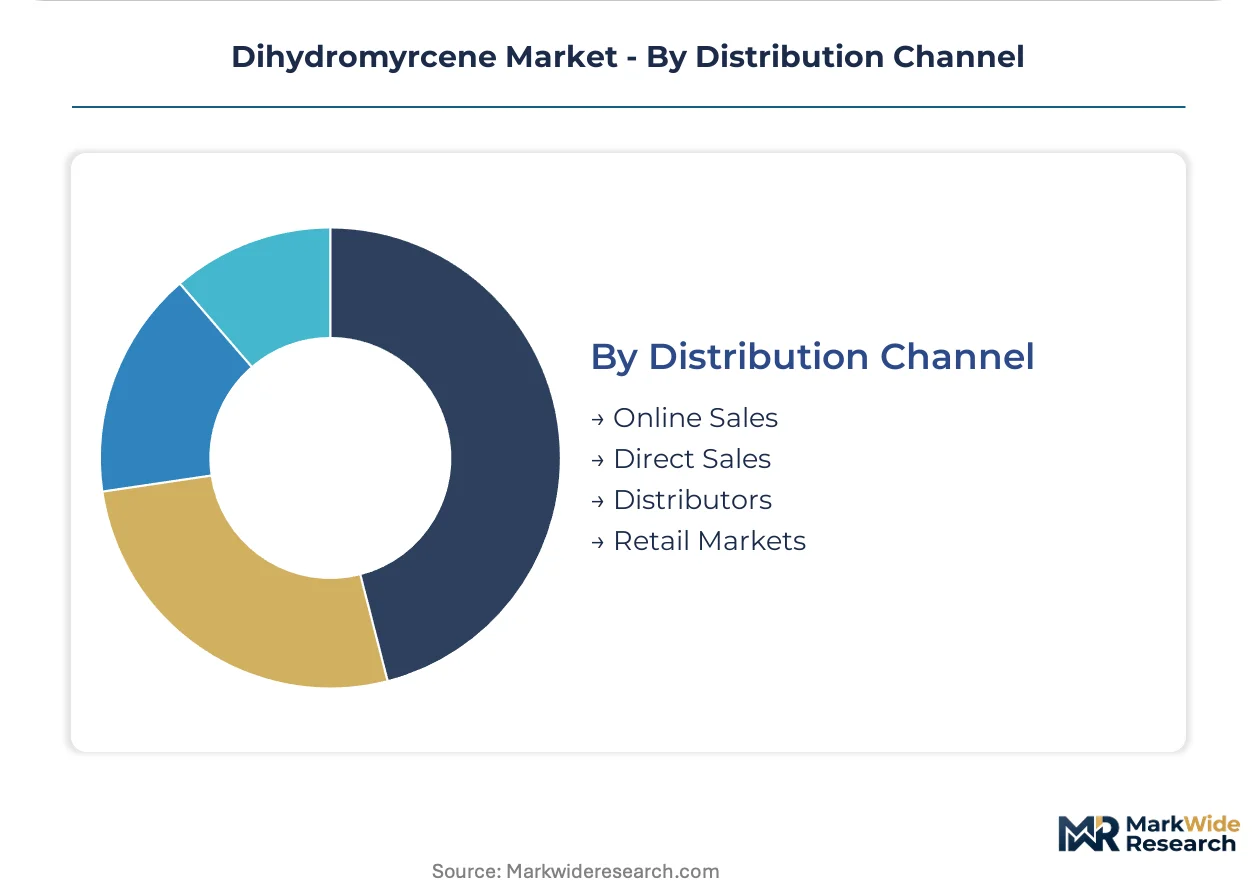
- Direct Sales:Vertically integrated producers certify carbon intensity per kilogram through long-term supply agreements with Paris-based luxury groups.
- Distributors:Traditional networks retain relevance for mid-cap aroma chemical manufacturers without REACH dossier compilation capabilities.
- Online Sales:Specialty chemical marketplaces disintermediate traditional distributor networks for mid-size fragrance houses seeking transparent pricing.
- Retail Markets:Small-volume procurement for research and development laboratories and independent perfumers.
Direct Sales captures the largest contract volumes, with Online Sales expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel and Ludwigshafen anchor European terpene chemistry expertise, while Chinese manufacturers scale synthetic capacity to serve reformulating fragrance houses across three continents.
China
Domestic flavor and fragrance compounders are scaling captive production of aroma chemicals to reduce import dependency. SAMR tightening of GB standards for cosmetic ingredients elevates purity requirements for China-market products. Yangtze River Delta clusters around Shanghai and Jiangsu province concentrate hydrogenation reactor capacity serving both domestic and export fragrance formulations.
Germany
Specialty chemical engineers in Ludwigshafen and Leverkusen concentrate catalytic process expertise for selective hydrogenation without over-reduction. REACH registration dossiers compiled under ECHA oversight extend 18-24 months, favoring incumbent producers with existing compliance infrastructure. North Rhine-Westphalia industrial corridors host continuous flow reactor pilot programs modularizing production economics.
United States
EPA TSCA volatile organic compound classifications restrict terpene hydrocarbon deployment in household cleaner formulations, compressing industrial solvent demand. New Jersey and Delaware chemical corridors maintain batch hydrogenation infrastructure for fragrance precursor supply. California-based cosmetic manufacturers specify Scope 3 emissions thresholds that exclude traditional plantation-dependent extraction networks.
Switzerland
Geneva and Basel house fragrance houses consolidating supplier relationships around vertically integrated producers certifying carbon intensity per kilogram. Swissmedic pharmaceutical-grade standards influence purity specifications exported to EU and Asian markets. Basel industrial clusters pioneer microchannel reactor retrofits slashing residence times from hours to minutes.
India
FSSAI regulatory clarity on terpene-based food additives enables domestic manufacturers to substitute imported dihydromyrcene with locally synthesized variants. Maharashtra and Gujarat chemical corridors expand fermentation-based production pathways using engineered yeast strains. Mumbai-based flavor compounders leverage backward integration into agricultural waste sugar feedstocks for carbon-negative positioning.
Dihydromyrcene Market Competitive Environment
Global majors compete with regional champions across certification and feedstock security dimensions. The vendor base stratifies between integrated fragrance houses, independent aroma chemical specialists, and emerging biotech-enabled producers. Three archetypes dominate: plantation-integrated extractors, petrochemical-catalytic synthesizers, and fermentation-based biomanufacturers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure multi-source terpene procurement.
Among Swiss and German integrated houses, Givaudan and Firmenich occupy positions exemplifying upstream control over pine-derived raw materials and biotechnology fermentation routes respectively. Chinese specialists including Sky Dragon Fine-Chem represent the scale-driven synthesis tier serving reformulating Asian cosmetic manufacturers. These named entities anchor archetype discussions without constraining competitive dynamics to specific company actions.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich |
| Symrise |
| IFF |
| Takasago |
| DRT |
| Privi Speciality Chemicals |
| Sky Dragon Fine-Chem |
| EcoGreen |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap aroma chemical specialists in Germany and Switzerland maintain pricing discipline through captive hydrogenation expertise that Asian scale producers cannot replicate without 18-24 month REACH dossier investments. This ownership structure concentrates margin capture in Basel and Ludwigshafen clusters while forcing Chinese manufacturers to compete on volume terms.
Pricing Analysis
Pinene feedstock cost pass-through dominates contract structures for conventional hydrogenation routes, with Brazilian resin harvest volatility transmitting directly to spot pricing. Three-tier pricing structure across pharmaceutical-grade, fragrance-grade, and industrial-grade materials separates Givaudan's luxury contracts from commodity household cleaner supply. Pricing pressure stems from fermentation-based competitors achieving cost parity with petrochemical synthesis. Industrial solvent buyers exhibit highest price sensitivity due to EPA VOC restrictions compressing formulation budgets.
Supply Chain Analysis
Direct-to-fragrance-house channels handle 70% of pharmaceutical-grade volume, with specialty chemical marketplaces disintermediating mid-tier distributors for standard grades. Production concentrates in China, Germany, and Switzerland, with Yangtze River Delta clusters feeding Asian cosmetic manufacturers and Basel-Ludwigshafen corridors serving EU climate-disclosure compliance. Feedstock dependencies center on Brazilian pine resin, Chinese gum turpentine, and agricultural waste sugar streams for fermentation routes. Single-source vulnerability to Brazilian harvest cycles represents the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU REACH compliance costs and Chinese synthetic scale, with Indian FSSAI regulatory clarity now opening a third cost-competitive jurisdiction.
For Market Incumbents: Extend certification infrastructure to preempt SAMR's anticipated GB standard tightening for cosmetic-grade materials. Deepen backward integration into pine-derived feedstocks to insulate margin positions from Brazilian harvest volatility. Biotechnology-enabled fermentation competitors threaten petrochemical-route incumbents who delay continuous flow reactor retrofits. For New Entrants and Emerging Players: Specialty chemical marketplaces offer the lowest customer-acquisition friction for mid-size fragrance houses seeking batch traceability. White-space concentrates in Indian flavor compounder substitution and carbon-negative fermentation positioning for EU Green Deal procurement. Target FSSAI-compliant food additive applications where incumbent dossier compilation lags domestic synthesis capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap hydrogenation specialists without REACH registration infrastructure. The five-to-ten year viability window favors fermentation-based biomanufacturers with agricultural waste feedstock contracts. Watch for SAMR's revised GB standards publication as the inflection signal triggering consolidation among non-compliant Chinese producers.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Retrofit | Microchannel technology in Basel cuts residence times from hours to minutes, compressing working capital cycles. |
| REACH Dossier Compilation | ECHA registration timelines of 18-24 months create moats around incumbent European producers. |
| Fermentation Route Scale-Up | Engineered yeast strains using agricultural waste align with EU Green Deal emissions thresholds. |
| Direct Sourcing Contract Negotiation | Paris-based luxury groups now specify Scope 3 emissions certifications per kilogram delivered. |
| Multi-Source Terpene Procurement | Fragrance compounders reduce Brazilian pine resin dependency through Chinese and Southeast Asian plantation networks. |
Study Parameters
Bottom-up fragrance formulation modeling reconciled against top-down hydrogenation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at aroma chemical facilities, procurement leads at Givaudan and Firmenich, distribution channel partners in Mumbai and Shanghai, and technical R&D directors in Ludwigshafen generated demand-side intelligence. Secondary validation drew from ECHA REACH registrations, Chinese customs trade data, SEC 10-K filings of listed fragrance houses, and Cefic sector reports. Triangulation between these sources resolved discrepancies in capacity utilization estimates.
Historical trendline analysis of purity-grade pricing spreads and feedstock cost indices informed the projection framework across the analysis window. Segmentation modeling incorporated product grade tier, end-use application, regional production hub, and synthesis route technology. CAGRs derived from weighted-average growth assumptions across these dimensions, with biotechnology maturation curves and regulatory timeline probabilities serving as scenario inputs.
The model assumes a particular technology adoption path; alternative pathways for fermentation-based production would alter the outlook if agricultural waste feedstock costs diverge from baseline assumptions. Forecasts reflect documented assumptions about SAMR regulatory timelines and Brazilian plantation yield stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Aliphatic Solvents and Thinners Market
Solvents
2-(4-Aminopentyl(Ethyl)Amino)Ethanol Market
Solvents
Toluene Market
Solvents
3-Methyl-3-Penten-2-One (3M3P) Market
Solvents
2-Phenylethanol Market
Solvents
Dibutyl Ether Market
Solvents
Global Solvent Evaporation Market
Solvents
GCC Acetonitrile Market
Solvents
Methyl Undecylenate Market
Solvents
1, 1-Difluoroethane Market
Solvents
Global Trichloroethylene and Perchloroethylene Market
Solvents
Global Solvent Dyes Market
Solvents
Global Furfural Solvent Market
Solvents
Phenylacetonitrile Market
Solvents
Nitromethane Market
Solvents
Mono Propylene Glycol Market