
 Europe Diet Pills Market | 2026-2036
Europe Diet Pills Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Diet Pills Market Intelligence
The wellness program segment is restructuring procurement patterns across Europe, shifting from discretionary retail purchases toward supervised clinical dispensing. Novo Nordisk A/S leverages its GLP-1 receptor agonist platform to anchor prescription-grade obesity portfolios in Nordic and Western European markets. GlaxoSmithKline plc competes through over-the-counter channels with established fat-blocking formulations, while Sandoz International GmbH specializes in generic alternatives that occupy price-sensitive segments.
Europe diet pills comprise pharmacologically active compounds—synthetic small molecules, peptide analogues, and botanical extracts—formulated to induce satiety, inhibit lipase enzymes, or elevate basal metabolic rate through thermogenic pathways. These products serve medical obesity intervention and elective weight management protocols in both clinical and consumer settings. Appetite suppressants dominate prescription value pools, while metabolism boosters and thermogenic agents capture growing traction in fitness-adjacent channels. The gummies and liquids form categories expand fastest among younger demographics seeking palatable alternatives to tablets and capsules.
EMA's centralized marketing authorization procedures and national regulators such as Germany's BfArM and France's ANSM enforce stringent efficacy and safety thresholds that filter entrants and prolong development timelines. The EU MDR and national pharmacy codes restrict direct-to-consumer advertising for prescription-grade formulations, channeling demand through healthcare clinics and licensed pharmacies. Stakeholders must monitor evolving reimbursement decisions by statutory health insurers in Germany and France, as these determinations will dictate whether prescription diet pills remain concentrated in medical channels or migrate toward broader retail access.
Market Dynamics
EMA's pharmacovigilance tightening is compressing development timelines and forcing manufacturers to front-load safety data collection before centralized marketing authorization submissions. This regulatory pressure is restructuring competitive positioning around clinical evidence depth rather than marketing scale.
Growth Catalysts
- GLP-1 receptor agonist platforms:Peptide-based satiety induction is expanding prescription-grade obesity intervention beyond bariatric surgery candidates into primary care protocols across Nordic markets.
- Germany's reimbursement pathways:Statutory health insurance coverage for obesity management pharmaceuticals is channeling demand through pharmacy-led distribution networks with embedded clinical counseling.
- EU MDR compliance frameworks:Harmonized device-drug combination standards are accelerating cross-border market access for novel delivery mechanisms including subcutaneous auto-injectors.
Market Restraints
- Active pharmaceutical ingredient concentration:Peptide synthesis capacity clusters with contract manufacturers in Switzerland and Ireland, creating supply bottlenecks for scaled GLP-1 production.
- Eficacy-safety threshold elevation:France's ANSM and Germany's BfArM are rejecting marketing authorization applications for sympathomimetic compounds that cleared prior centralized procedures.
- Bariatric surgery substitution:Laparoscopic sleeve gastrectomy cost reductions in Spain and Italy are diverting severe obesity cases from pharmaceutical toward surgical intervention.
Strategic Opportunities
- Poland and Romania pharmacy modernization:Underpenetrated markets with expanding private health insurance penetration offer first-mover positioning for supervised clinical dispensing models.
- Gummies and liquids form factor innovation:Palatable alternatives to tablets are capturing younger demographics seeking wellness-adjacent weight management without prescription stigma.
- CSRD sustainability disclosure mandates:Environmental footprint transparency requirements are creating competitive differentiation for manufacturers with verified green chemistry supply chains.
Industry Challenges
- Peptide formulation expertise scarcity:GLP-1 analog stability engineering and cold-chain logistics management require specialized talent pools concentrated with Nordic biopharma incumbents.
- EU MDR technical documentation burden:Legacy product portfolios face recertification costs and notified body queue delays that compress margin structures for generic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Diet Pills Market |
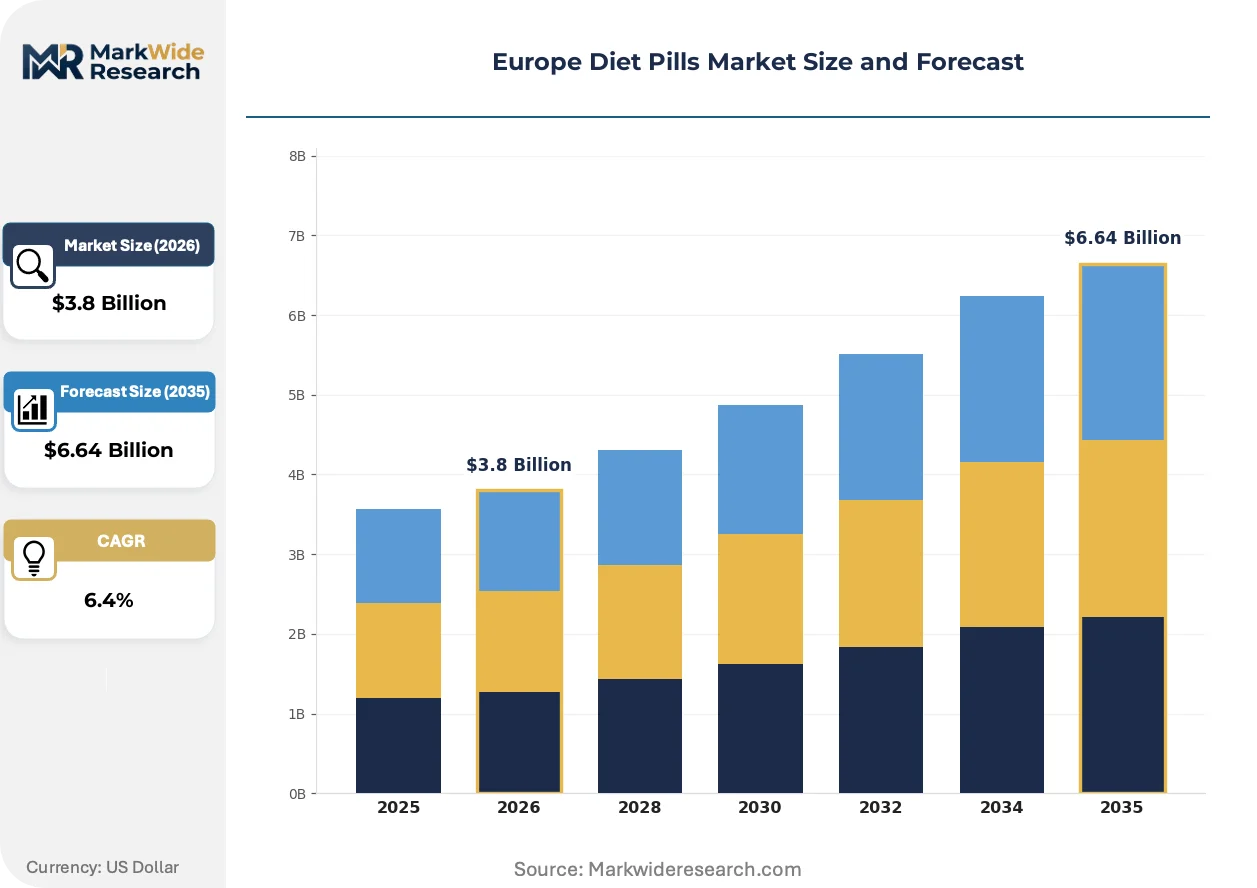
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Appetite Suppressants, Fat Blockers, Metabolism Boosters, Carb Controllers, Thermogenic Agents Form: Tablets, Capsules, Liquids, Powders, Gummies Distribution Channel: Pharmacies, Online Retailers, Specialty Stores, Healthcare Clinics, Direct Selling Customer Type: Weight Management Clinics, Fitness Centers, Wellness Programs, Individual Consumers, Nutritionists |
| Companies Covered | Novo Nordisk A/S, F. Hoffmann-La Roche Ltd, GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd, Sandoz International GmbH, VIVUS Inc, Currax Pharmaceuticals LLC, Bayer AG, Haleon PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Diet Pills Market Strategic Shifts & Innovations
Digital therapeutics integration and personalized nutrition platforms are converging with pharmaceutical interventions, creating hybrid obesity management protocols that blend pharmacological and behavioral components.
Continuous glucose monitoring sensors paired with appetite-suppressant dosing algorithms is modularizing treatment regimens into adaptive, data-driven protocols. Endocrinology clinics in Germany and the Netherlands are piloting these closed-loop systems for prediabetic obesity patients. The technology is modularizing prescriber decision-making from static dosing charts toward real-time metabolic feedback integration.
REACH chemical registration requirements are tightening scrutiny on botanical extract sourcing for over-the-counter thermogenic formulations. Manufacturers must now demonstrate supply chain traceability for ephedra alternatives and caffeine derivatives. Natural health product distributors in France and Italy are reformulating portfolios to preempt authorization withdrawals.
Fitness center wellness programs are displacing discretionary retail purchases with supervised clinical dispensing models. Boutique gym chains in the United Kingdom and Sweden are embedding licensed pharmacists within member health assessments. This channel evolution is most visible in London and Stockholm metropolitan clusters where employer-sponsored wellness subsidies cover pharmaceutical obesity interventions.
Europe Diet Pills Market Segmentation
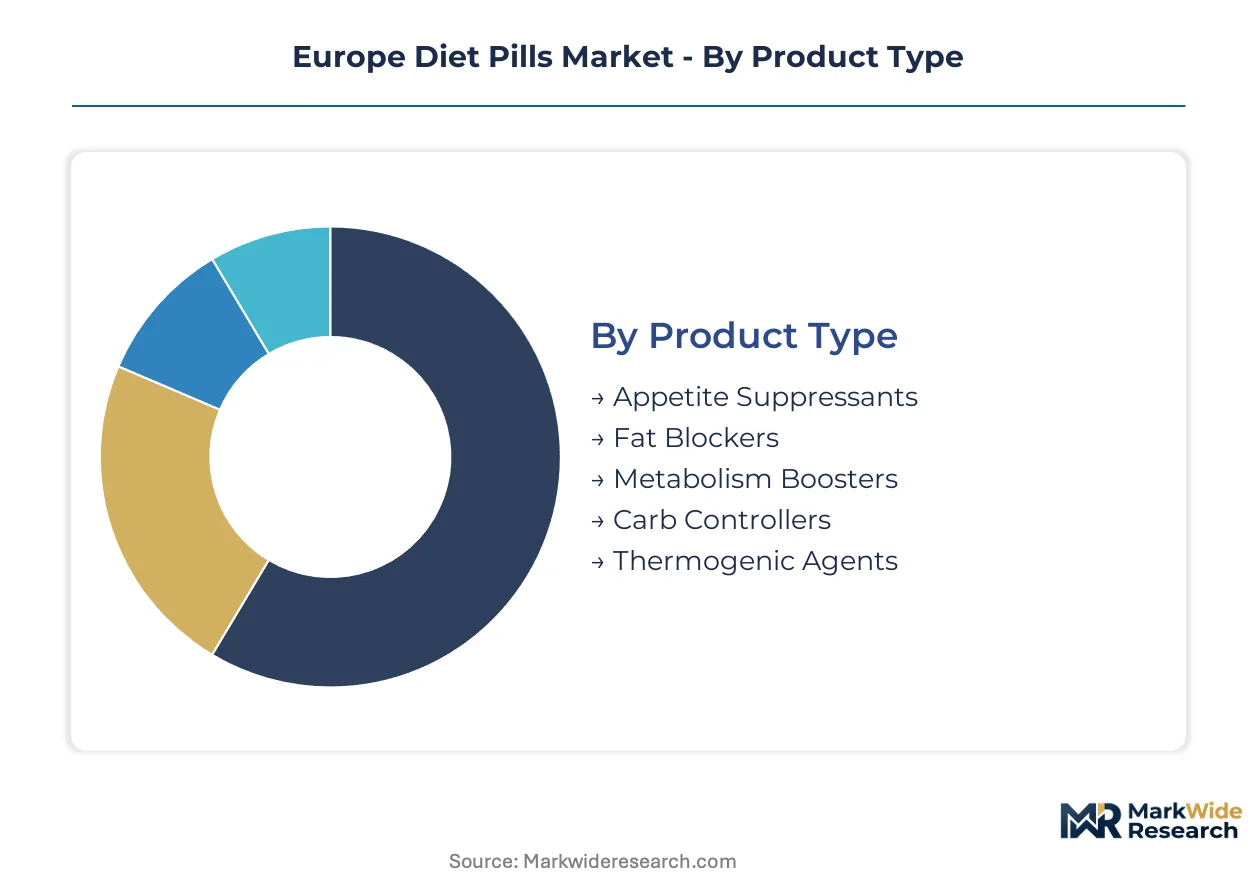
Segmentation in the Europe Diet Pills Market reveals how pharmacological mechanisms, delivery formats, and procurement channels intersect with regulatory pathways and clinical supervision requirements. Understanding these divisions exposes where prescription-grade interventions diverge from consumer wellness products.
Product Type:
Standalone pharmacological agents dominate medical channels, while combination formulations and botanical blends embed within broader wellness protocols across fitness and nutrition programs.
- Appetite Suppressants:GLP-1 receptor agonists and sympathomimetic compounds modulate hypothalamic satiety signaling. Demand concentrates in Germany's statutory health insurance reimbursement pathways for obesity management, where BfArM oversight mandates clinical supervision. Peptide synthesis capacity constraints in Switzerland and Ireland limit supply scalability for Nordic markets.
- Fat Blockers:Lipase inhibitors such as orlistat derivatives prevent dietary triglyceride hydrolysis in the gastrointestinal tract. France's ANSM maintains strict post-marketing surveillance for hepatic adverse events, channeling distribution through pharmacy networks with embedded counseling protocols. Generic competition from Sandoz International GmbH compresses pricing in price-sensitive Southern European segments.
- Metabolism Boosters:Thyroid hormone analogs and mitochondrial uncouplers elevate basal metabolic rate through thermogenic pathways. Individual consumers in the United Kingdom access these through pharmacy-led weight management programs.
- Carb Controllers:Alpha-amylase and alpha-glucosidase inhibitors delay carbohydrate absorption. Wellness programs in Sweden integrate these with continuous glucose monitoring for prediabetic cohorts.
- Thermogenic Agents:Caffeine derivatives and capsaicin analogs stimulate brown adipose tissue activation. REACH registration requirements for botanical sourcing concentrate manufacturing with ECHA-compliant suppliers in the Netherlands.
Appetite Suppressants lead volumes today; Gummies and liquids form categories are gaining share fastest among younger demographics seeking palatable alternatives.
Form:
Cost tier stratification separates premium peptide auto-injector systems from commoditized tablet generics, with palatability innovation commanding margin premiums in direct-to-consumer channels.
- Tablets:Compressed solid dosage forms with established bioequivalence profiles dominate prescription dispensing volumes. Germany's pharmacy codes enforce unit-dose packaging for reimbursement eligibility, embedding these within clinical counseling workflows.
- Capsules:Gelatin or HPMC shells enable modified-release kinetics for acid-sensitive compounds. France's ANSM requires stability data under accelerated aging protocols for marketing authorization renewals.
- Liquids:Aqueous or oil-based solutions improve bioavailability for lipophilic actives. Pediatric and geriatric segments in Italy prefer these for dose titration flexibility.
- Powders:Bulk active ingredients for compounding pharmacies and sports nutrition formulations. Fitness centers in the United Kingdom embed these within personalized macro-nutrition protocols.
- Gummies:Gelatin or pectin matrices mask bitter actives with flavor systems. Younger demographics in Nordic markets drive fastest expansion for wellness-adjacent weight management without prescription stigma.
Tablets and capsules capture the majority of prescription value; gummies are expanding most quickly in employer-sponsored wellness programs.
Distribution Channel:
Customer type concentration distinguishes institutional procurement through weight management clinics from discretionary individual purchases, with channel choice determining regulatory scrutiny intensity.
- Pharmacies:Licensed dispensaries with mandatory pharmacist oversight anchor prescription-grade distribution. Germany's statutory health insurance reimbursement pathways concentrate obesity pharmaceutical procurement through this channel, with embedded clinical counseling requirements under BfArM guidelines.
- Online Retailers:E-commerce platforms with verified prescription authentication systems serve repeat medication fulfillment. France's CNIL data protection requirements complicate patient data handling for cross-border dispensing.
- Specialty Stores:Sports nutrition and wellness retail with trained staff for over-the-counter thermogenic guidance. United Kingdom boutique chains in London metropolitan clusters embed licensed pharmacists for employer-sponsored program eligibility.
- Healthcare Clinics:Endocrinology and bariatric specialist practices with in-house dispensing for GLP-1 initiation protocols. Netherlands pilot programs pair these with continuous glucose monitoring sensor integration.
- Direct Selling:Multi-level marketing networks for botanical and metabolic supplement portfolios. Poland and Romania's expanding private health insurance penetration attracts first-mover positioning for supervised clinical dispensing models.
Pharmacies dominate prescription volumes; healthcare clinics are climbing the fastest as digital therapeutics integration expands.
Customer Type:
Application maturity separates established medical obesity intervention from emerging wellness-adjacent protocols, with supervision depth determining product form and regulatory pathway.
- Weight Management Clinics:Specialized medical facilities with multidisciplinary teams for severe obesity cases. Spain and Italy's laparoscopic sleeve gastrectomy cost reductions divert pharmaceutical intervention toward surgical alternatives for BMI thresholds above 40.
- Fitness Centers:Boutique gym chains with embedded health assessments and licensed pharmacist consultations. Sweden's employer-sponsored wellness subsidies cover pharmaceutical obesity interventions in Stockholm metropolitan clusters.
- Wellness Programs:Corporate and insurer-funded prevention protocols blending behavioral and pharmacological components. Germany's expanding statutory coverage for obesity management pharmaceuticals channels demand through these structured interventions.
- Individual Consumers:Discretionary purchasers of over-the-counter metabolism boosters and thermogenic agents. France's ANSM tightening on sympathomimetic marketing authorizations limits available options.
- Nutritionists:Registered dietitians with prescribing partnerships for meal-replacement and appetite modulation protocols. Netherlands integration with continuous glucose monitoring sensors creates hybrid data-driven treatment regimens.
Weight Management Clinics anchor medical channel volumes; Fitness Centers are gaining share fastest as wellness program procurement displaces discretionary retail purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmacy-led distribution networks anchor European demand for prescription-grade obesity interventions, channeling procurement through statutory health insurance reimbursement pathways that mandate clinical counseling.
Germany
BfArM oversight embeds obesity pharmaceuticals within pharmacy counseling workflows, with statutory health insurers expanding coverage for weight management compounds. Berlin and Munich metropolitan clusters concentrate GLP-1 dispensing through specialized endocrinology clinics. Novo Nordisk A/S leverages Nordic biopharma infrastructure to supply peptide-based therapies through these regulated channels.
France
ANSM's tightened pharmacovigilance for sympathomimetic compounds filters marketing authorization applications through enhanced safety thresholds. Paris and Lyon pharmacy networks maintain strict post-marketing surveillance for hepatic adverse events in lipase inhibitor distribution. The CNIL's data protection requirements complicate cross-border prescription authentication for online fulfillment.
United Kingdom
Employer-sponsored wellness subsidies drive fastest expansion in fitness-center dispensing models, with London boutique gym chains embedding licensed pharmacists within member health assessments. The MHRA's post-Brexit regulatory autonomy maintains alignment with EMA centralized procedures for novel peptide therapies. Manchester and Birmingham clusters pilot continuous glucose monitoring integration with appetite suppressant protocols.
Sweden
Stockholm's metropolitan wellness programs channel pharmaceutical obesity interventions through hybrid digital therapeutics platforms. The Swedish Medical Products Agency enforces EU MDR compliance for subcutaneous auto-injector delivery mechanisms. Nordic peptide synthesis expertise concentrates formulation engineering with contract manufacturers in Uppsala biotech corridors.
Netherlands
Amsterdam and Rotterdam endocrinology clinics pioneer closed-loop systems pairing continuous glucose monitoring with adaptive dosing algorithms. The Dutch Healthcare Authority monitors reimbursement decisions for prediabetic obesity pharmaceutical protocols. Eindhoven's medical device ecosystem supplies sensor hardware for these modular treatment regimens.
Europe Diet Pills Market Key Industry Players
Portfolio diversification dominates the current landscape as incumbents restructure around prescription-grade peptide platforms and over-the-counter botanical formulations. The vendor base stratifies across three tiers: Nordic biopharma specialists with GLP-1 synthesis capabilities, diversified pharmaceutical conglomerates with dual prescription-consumer channels, and generic manufacturers capturing price-sensitive Southern European segments. Strategic archetypes include peptide platform anchors, fat-blocker incumbents, and generic volume players. M&A activity concentrates on peptide formulation expertise acquisition, while capacity expansion targets Switzerland and Ireland contract manufacturing clusters.
Within the peptide platform tier, Novo Nordisk A/S exemplifies Nordic biopharma specialization through its receptor agonist portfolio. GlaxoSmithKline plc occupies a position bridging prescription and consumer channels with established over-the-counter distribution. Sandoz International GmbH represents the generic manufacturer archetype, anchoring price-competitive segments across German and French pharmacy networks. These three entities collectively illustrate how competitive positioning now depends on clinical evidence depth rather than marketing scale, with each archetype responding differently to EMA's front-loaded safety data requirements.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd |
| Sandoz International GmbH |
| VIVUS Inc |
| Currax Pharmaceuticals LLC |
| Bayer AG |
| Haleon PLC |
| Others |
Cost & Logistics Intelligence
Nordic biopharma incumbents with captive peptide synthesis capabilities anchor supply-side pricing power, while German statutory health insurance reimbursement frameworks enforce downstream price discipline through pharmacy-led distribution mandates. This ownership concentration creates asymmetric margin capture: upstream specialists extract premiums from GLP-1 receptor agonist shortages, while generic manufacturers in Southern Europe face compressed spreads under BfArM unit-dose packaging requirements.
Pricing Analysis
Distributor margin layering separates prescription-grade peptide therapies from over-the-counter botanical formulations, with pharmacy networks in Germany and France embedding clinical counseling fees within reimbursement tariffs. Three-tier pricing structure across premium auto-injector systems, standard tablet generics, and economy powder compounding reflects vertical integration depth and cold-chain logistics requirements. Cost compression in generic orlistat segments is intensifying because Sandoz International GmbH and Teva Pharmaceutical Industries Ltd compete on pharmacy tender volumes. Individual consumers accessing thermogenic agents through United Kingdom specialty stores exhibit highest price sensitivity; endocrinology clinics in the Netherlands show lowest sensitivity due to bundled sensor-therapy protocols.
Supply Chain Analysis
Peptide active pharmaceutical ingredient supply rests on contract manufacturing clusters in Switzerland and Ireland, with Nordic biopharma incumbents maintaining captive fermentation capacity for GLP-1 analog production. Key inputs include recombinant DNA host strains, chromatography resins, and borosilicate glass for auto-injector cartridges. Single-source vulnerability concentrates in Swiss lyophilization expertise for peptide stability engineering. Distribution runs through Germany's pharmacy networks with statutory health insurance authentication, supplemented by direct-to-clinic channels for continuous glucose monitoring paired protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's pharmacovigilance tightening and EU MDR recertification mandates compound regulatory barriers to entry, channeling demand toward manufacturers with pre-validated safety databases and notified body relationships.
For Market Incumbents: To counter bariatric surgery substitution in Spain and Italy, deepen peptide formulation expertise through Uppsala biotech corridor partnerships and secure dual-source lyophilization capacity in Switzerland. Prioritize EU MDR technical documentation completion for legacy portfolios before notified body queue delays extend further. Channel control through embedded pharmacy counseling workflows in Germany defends margin position against online retail price transparency. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms for gummies and liquids formats offer lowest regulatory friction entry path, particularly in employer-sponsored wellness programs across Sweden and the United Kingdom. Poland and Romania's expanding private health insurance penetration represents the most penetrable geography for supervised clinical dispensing models without incumbent pharmacy network saturation. Partner with boutique fitness chains for licensed pharmacist co-location to bypass traditional distribution gatekeeping. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with dual prescription-consumer channels are the most active acquirer in this space, seeking peptide platform anchors to offset small-molecule patent cliffs. Target acquisition archetype: Nordic mid-caps with GLP-1 analog pipelines and existing EMA centralized procedure approvals. Watch EMA reimbursement decisions for prediabetic obesity indications as inflection indicator for addressable market expansion beyond severe BMI thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Manufacturing Scale-Up | Switzerland and Ireland capacity expansion addresses GLP-1 supply bottlenecks for Nordic markets. |
| EU MDR Recertification Pathway | Notified body queue management preserves market access for legacy generic portfolios under BfArM oversight. |
| Digital Therapeutics Integration | Netherlands continuous glucose monitoring pairing creates closed-loop obesity protocols with adaptive dosing. |
| Pharmacy Network Partnership | Germany's statutory health insurance reimbursement pathways require embedded clinical counseling compliance. |
| Gummies Form Factor Launch | Palatable alternatives capture younger demographics in employer-sponsored wellness programs across Sweden. |
Research Approach
Coverage spans Germany, France, the United Kingdom, Sweden, and the Netherlands, with primary inputs from each market's regulatory and distribution stakeholders. The analysis combines interviews with drug development executives, regulatory affairs leads at EMA and national agencies, pharmacy procurement managers, and endocrinology clinic directors with secondary validation from EMA centralized procedure filings, BfArM and ANSM authorization databases, ClinicalTrials.gov obesity intervention records, and statutory health insurance reimbursement tariff publications. Bottom-up patient population modeling and top-down pharmaceutical expenditure triangulation cross-verify volume and value estimates.
Rate-of-change decomposition separates volume expansion from price/mix effects across the projection horizon. Segmentation dimensions include pharmacological mechanism, dosage form, distribution channel, and customer type, with regional regulatory cluster effects modeled separately. CAGRs derive from patient population growth, reimbursement expansion scenarios, and substitution elasticity between pharmaceutical and surgical interventions. Forecast inputs incorporate peptide synthesis capacity constraints, EU MDR implementation timelines, and continuous glucose monitoring adoption curves in prediabetic cohorts.
The model assumes a particular technology adoption path for GLP-1 receptor agonist platforms; alternative pathways for oral small-molecule satiety induction would alter the outlook for injection device supply chains. Forecasts reflect assumptions about EMA pharmacovigilance trajectory, statutory health insurance coverage decisions, and bariatric surgery cost curves. Regulatory authorization withdrawals, peptide supply disruptions, or reimbursement restrictions for elective weight management represent specific revision triggers. A small set of named triggers—ANSM sympathomimetic tightening, BfArM obesity pharmaceutical tariff adjustments, and Nordic wellness program subsidy expansions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
India Personalized Nutrition Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
Hydroxymethylbutyrate (HMB) Market
Nutritional Supplements
Calcium Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
South Africa Nutraceuticals Market
Nutritional Supplements
Australia Nutraceuticals Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Collagen Supplements Market
Nutritional Supplements
Throat Lozenges Market