
 Wellness Supplements Market | 2026-2036
Wellness Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Wellness Supplements Market Analysis
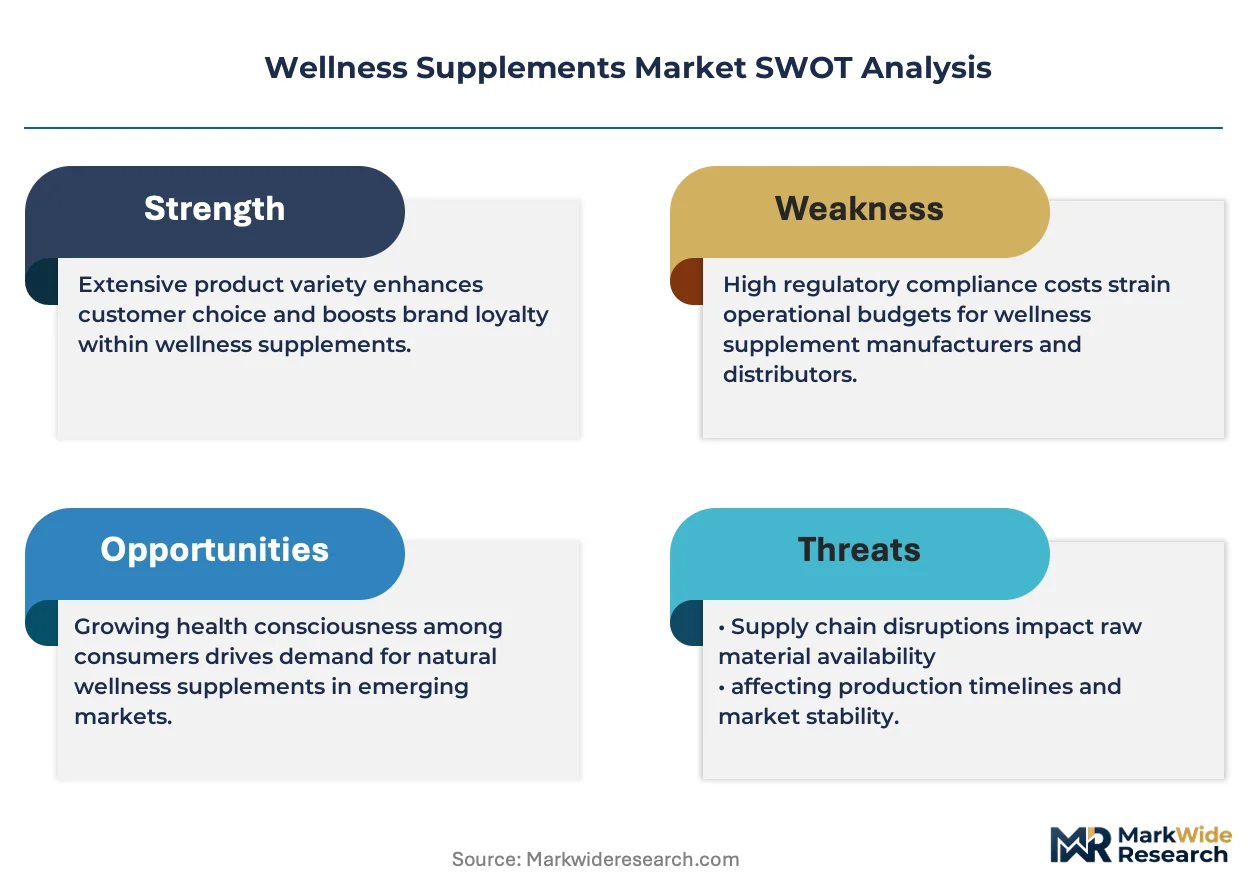
Registered dietitian capacity within functional food R&D is rotating toward personalized nutrition platforms, tightening talent competition between legacy and emerging players. Nestlé Health Science leverages its pharmaceutical-adjacent clinical networks to anchor premium positioning in medical nutrition. Amway Corporation sustains its direct-selling infrastructure across Asian markets, competing on channel intimacy rather than retail shelf space. Abbott Laboratories differentiates through hospital and pharmacy formulary relationships that extend its credibility into consumer wellness.
Wellness supplements encompass biologically active compounds delivered in standardized doses to support physiological function beyond basic nutritional adequacy, including vitamin isolates exceeding Recommended Dietary Allowance thresholds, chelated mineral complexes, and concentrated botanical extracts processed through solvent extraction or supercritical CO2 methods. Vitamins and herbal extracts dominate current revenue pools due to established consumer recognition and lower regulatory friction, while amino acids represent the fastest-growing category as sports performance positioning migrates into mainstream preventive health routines. Tablet and capsule formulations occupy the largest manufacturing volume, though liquid delivery formats are gaining share among pediatric and geriatric end users who present swallowing difficulties.
The FDA's Current Good Manufacturing Practice regulations and the FTC's substantiation requirements for health claims create a dual compliance burden that filters smaller entrants from mass-market distribution. EFSA's health claim authorization process in Europe imposes stricter evidentiary standards, redirecting innovation investment toward clinical trial infrastructure. Stakeholders must monitor how emerging AI-driven personalization engines intersect with existing substantiation frameworks, as regulators grapple with algorithm-generated recommendations that lack traditional randomized controlled trial backing.
Market Dynamics
Direct-to-consumer subscription infrastructure is compressing traditional retail shelf access and forcing legacy brands to rebuild their distribution architecture around recurring revenue models rather than periodic replenishment cycles.
Growth Catalysts
- Amateur athlete penetration:Recreational sports participation is normalizing performance-oriented supplementation beyond professional circles, expanding addressable demand into weekend fitness enthusiasts.
- FDA's evolving NDI pathway:Streamlined notification procedures for novel botanical extracts are accelerating time-to-market for differentiated formulations.
- Supercritical CO2 extraction:This solvent-free processing technology is unlocking standardized potency in herbal concentrates previously limited by batch variability.
Market Restraints
- Raw material concentration:Gelatin capsule shell supply depends heavily on bovine byproduct processing clusters in Brazil and Argentina, exposing formulators to livestock cycle volatility.
- EFSA substantiation burden:The European health claim authorization process demands multi-year clinical investment that filters mid-tier entrants from EU mass-market positioning.
- Plant protein substitution:Pea and rice protein isolates are capturing share among flexitarian consumers who previously purchased whey-based recovery products.
Strategic Opportunities
- Pediatric liquid formats:Swallowing difficulties among children and elderly populations remain underserved by tablet-dominant portfolios, creating white space for palatable suspension technologies.
- AI-driven personalization engines:Algorithmic recommendation systems that integrate microbiome sequencing with lifestyle data are opening subscription stickiness beyond generic multivitamin replenishment.
- Clinical-grade channel migration:Hospital discharge protocols and pharmacy formulary relationships offer credibility extension into preventive health positioning.
Industry Challenges
- Registered dietitian scarcity:Functional food R&D teams compete intensely for credentialed nutrition science talent against personalized nutrition platforms and telehealth services.
- Dual compliance architecture:Simultaneous FDA Current Good Manufacturing Practice adherence and FTC health claim substantiation creates documentation overhead that strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wellness Supplements Market |
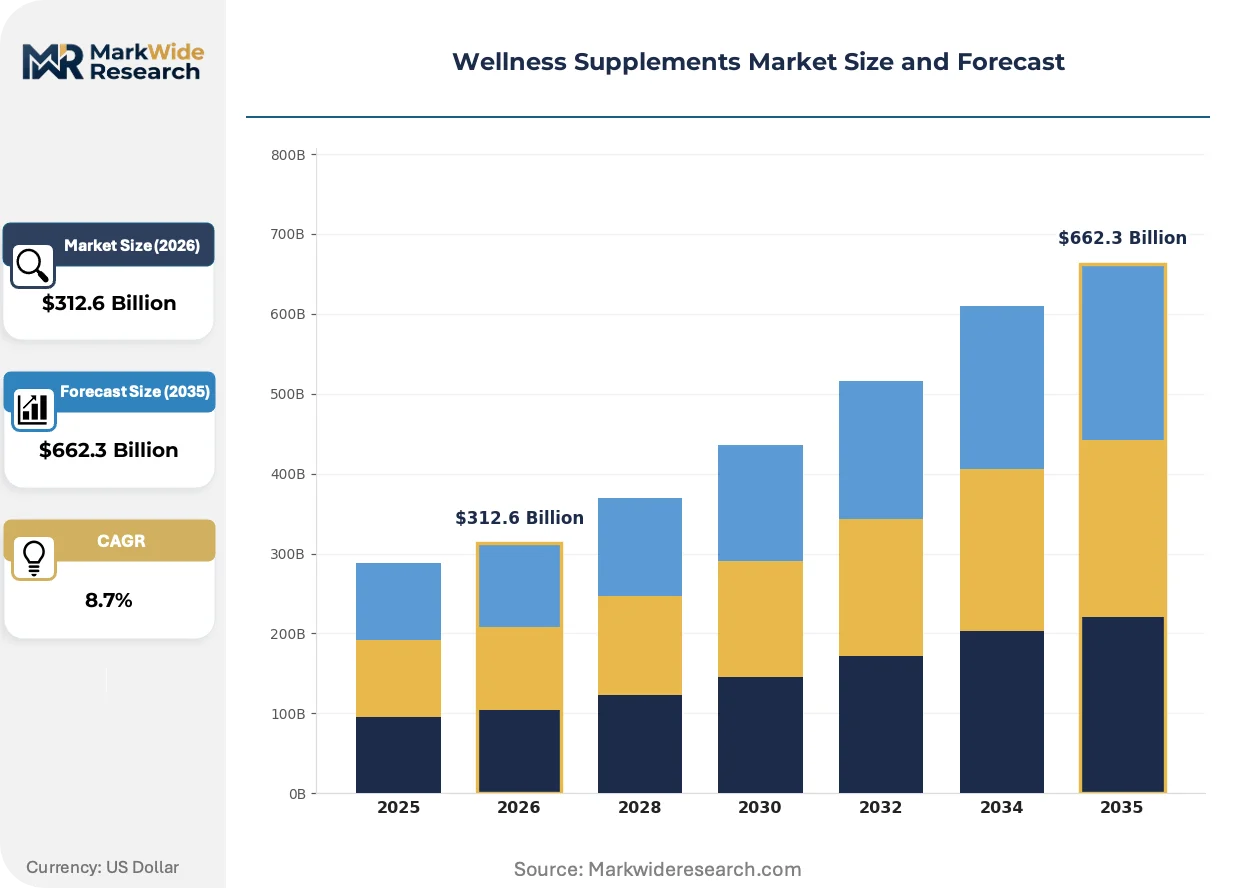
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Amino Acids Formulation Type: Tablets, Capsules, Powders, Liquids End User: Adults, Seniors, Athletes, Children Distribution Channel: Online, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Nestlé Health Science, Amway Corporation, Abbott Laboratories, Herbalife Nutrition Ltd., Glanbia plc, Bayer AG, Otsuka Holdings, GNC Holdings Inc., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wellness Supplements Market Emerging Trajectories
Formulation science and distribution architecture are diverging simultaneously, with manufacturing precision advancing toward individualized dosing while channel control consolidates around platform intermediaries.
Microbiome-targeted synbiotic formulations are fragmenting the traditional probiotic category by combining specific bacterial strains with precision prebiotic substrates matched to metabolic phenotypes. Functional medicine practitioners and longevity-focused consumers are adopting these combinations faster than standard retail channels can merchandise them. This fragmentation is compressing SKU economics for legacy single-strain products while rewarding vertically integrated manufacturers with sequencing partnerships.
EFSA's tightened health claim authorization standards are redirecting European innovation investment toward clinical trial infrastructure rather than marketing differentiation. The industrial consequence is a bifurcation between substantiation-heavy medical nutrition positioning and generic wellness claims that avoid regulatory scrutiny. Sports nutrition and cognitive performance segments are most affected, with several brands withdrawing ambitious claims rather than funding required trials.
Subscription bundling is replacing single-product replenishment as the dominant direct-to-consumer acquisition model, with platforms aggregating multivitamin, sleep, and stress formulations into personalized stacks. This consolidation of purchase decisions into algorithm-curated protocols is disintermediating brand loyalty and transferring margin to platform operators with superior data infrastructure. The United States exhibits the most visible concentration of this behavior, though Asian direct-selling networks are adapting similar bundling logic to their existing distributor relationships.
Wellness Supplements Market Segmentation
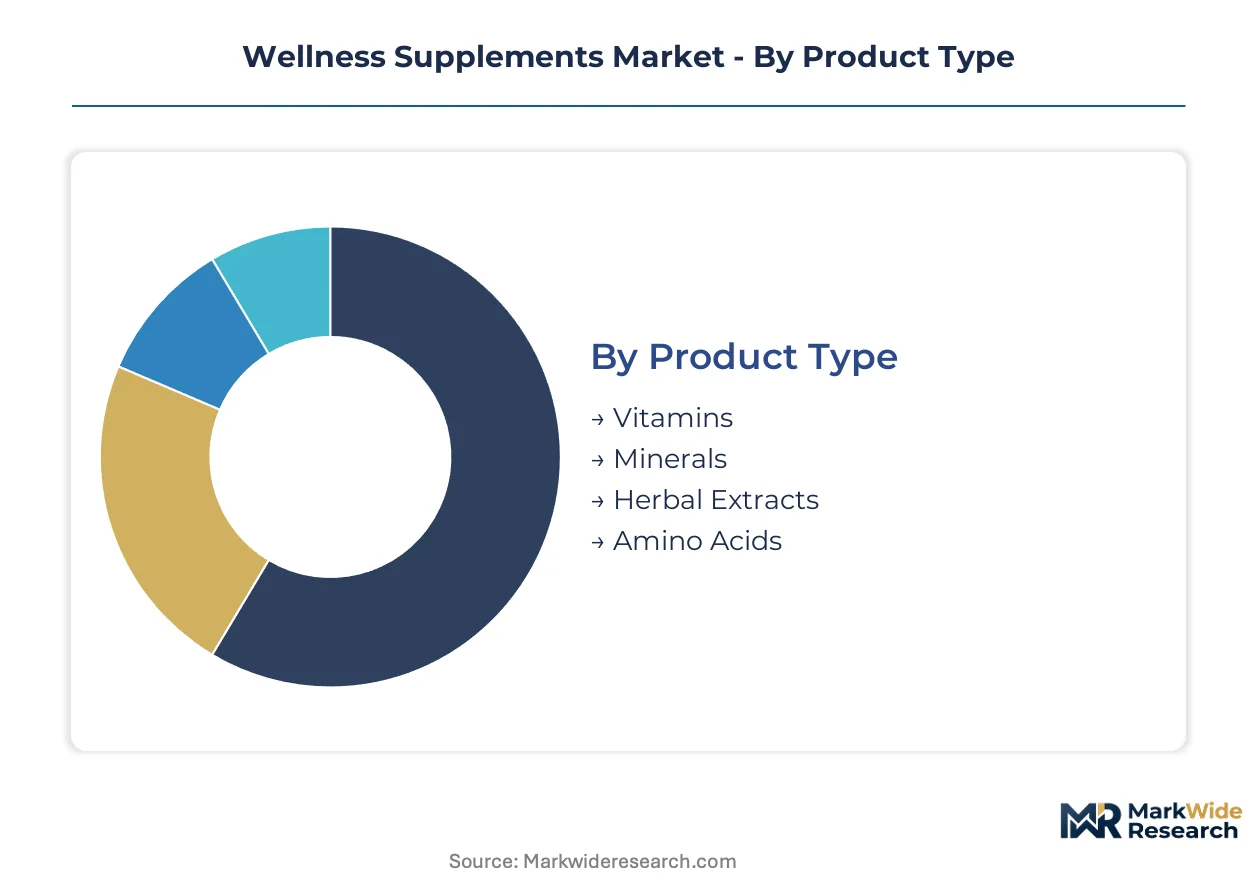
Wellness supplement segmentation reveals how formulation science, delivery mechanisms, and channel architecture create distinct competitive arenas with diverging margin profiles and regulatory exposure. Understanding these boundaries clarifies where substitution threats concentrate versus where proprietary positioning endures.
Product Type:
Substitution pressure from functional foods and fortified beverages weighs most heavily on commodity vitamin and mineral isolates, while concentrated botanical extracts retain differentiation through processing complexity and standardization protocols.
- Vitamins:Synthetic and fermentation-derived isolates deliver single or multi-nutrient doses exceeding standard dietary thresholds. Demand concentrates in the United States among direct-to-consumer subscription platforms that bundle multivitamin protocols with algorithmic personalization. The category faces erosion from beverage fortification and food matrix delivery systems that bypass pill fatigue.
- Herbal Extracts:Solvent-extracted or supercritical CO2-concentrated botanicals deliver standardized phytochemical content with batch-to-batch consistency. European demand through pharmacy channels favors EFSA-substantiated claims, while Asian markets prioritize traditional medicine heritage positioning. Supercritical CO2 processing unlocks premium tier pricing previously limited by variable potency.
- Minerals:Chelated complexes and inorganic salts address bioavailability limitations in standard dietary intake.
- Amino Acids:Branched-chain and essential amino acid isolates target muscle protein synthesis and recovery optimization.
Vitamins retain volume leadership; amino acids hold the steepest expansion curve.
Formulation Type:
Cost tier stratification separates high-volume tablet manufacturing from premium liquid and powder formats that command per-dose premiums through palatability engineering and swallowing accessibility.
- Tablets:Compressed powder matrices with binders and coatings enable high-speed manufacturing at scale. Demand concentrates among adult maintenance users in mass-market retail channels where unit economics favor shelf-stable, transport-dense formats. The segment faces compression from capsule preference among consumers perceiving superior dissolution profiles.
- Capsules:Gelatin or hydroxypropyl methylcellulose shells encase powder or liquid fills with taste-masking benefits. United States direct-to-consumer brands favor capsules for premium positioning and ingredient visibility through transparent shells. Raw material concentration in Brazilian and Argentine bovine processing clusters exposes supply to livestock cycle volatility.
- Powders:Bulk amino acid and protein isolates enable flexible dosing and beverage integration.
- Liquids:Suspension and emulsion technologies address pediatric and geriatric swallowing difficulties with flavor-masked delivery.
Tablets dominate manufacturing volume; liquids are expanding most quickly through pediatric and senior accessibility demand.
End User:
Application intensity varies dramatically across life stages and activity levels, with athletic and senior segments justifying clinical-grade positioning that adult maintenance users rarely support.
- Adults:Working-age consumers aged 18-64 drive baseline preventive supplementation through multivitamin and single-nutrient protocols. United States subscription platforms concentrate acquisition spend here, though churn rates exceed specialized segments due to low perceived efficacy differentiation.
- Athletes:Amateur and professional competitors demand performance-validated formulations with third-party certification for banned substance absence. Sports nutrition positioning migrates into mainstream channels as recreational participation normalizes performance-oriented supplementation beyond elite circles.
- Seniors:Adults 65+ present swallowing difficulties and polypharmacy interactions that favor liquid formats and pharmacist-guided selection.
- Children:Pediatric populations require palatable delivery systems with age-appropriate dosing precision and parental safety assurance.
Adults retain volume leadership; athletes hold the steepest expansion curve.
Distribution Channel:
Channel control consolidation around platform intermediaries is compressing traditional retail shelf access and transferring margin to operators with superior data infrastructure and recurring revenue architecture.
- Online:Direct-to-consumer subscription infrastructure enables algorithm-curated bundling and personalized protocol adjustment based on biometric feedback. United States platforms lead this consolidation, though Asian direct-selling networks adapt similar bundling logic to existing distributor relationships.
- Pharmacies:Hospital discharge protocols and formulary relationships extend credibility into preventive health positioning. European pharmacy channels demand EFSA-compliant claims that filter unsubstantiated products from premium shelf placement.
- Supermarkets:Mass-market retail provides impulse accessibility for commodity vitamin and mineral products with established consumer recognition.
- Health Stores:Specialty retailers cater to enthusiast segments seeking practitioner-grade formulations and novel botanical introductions.
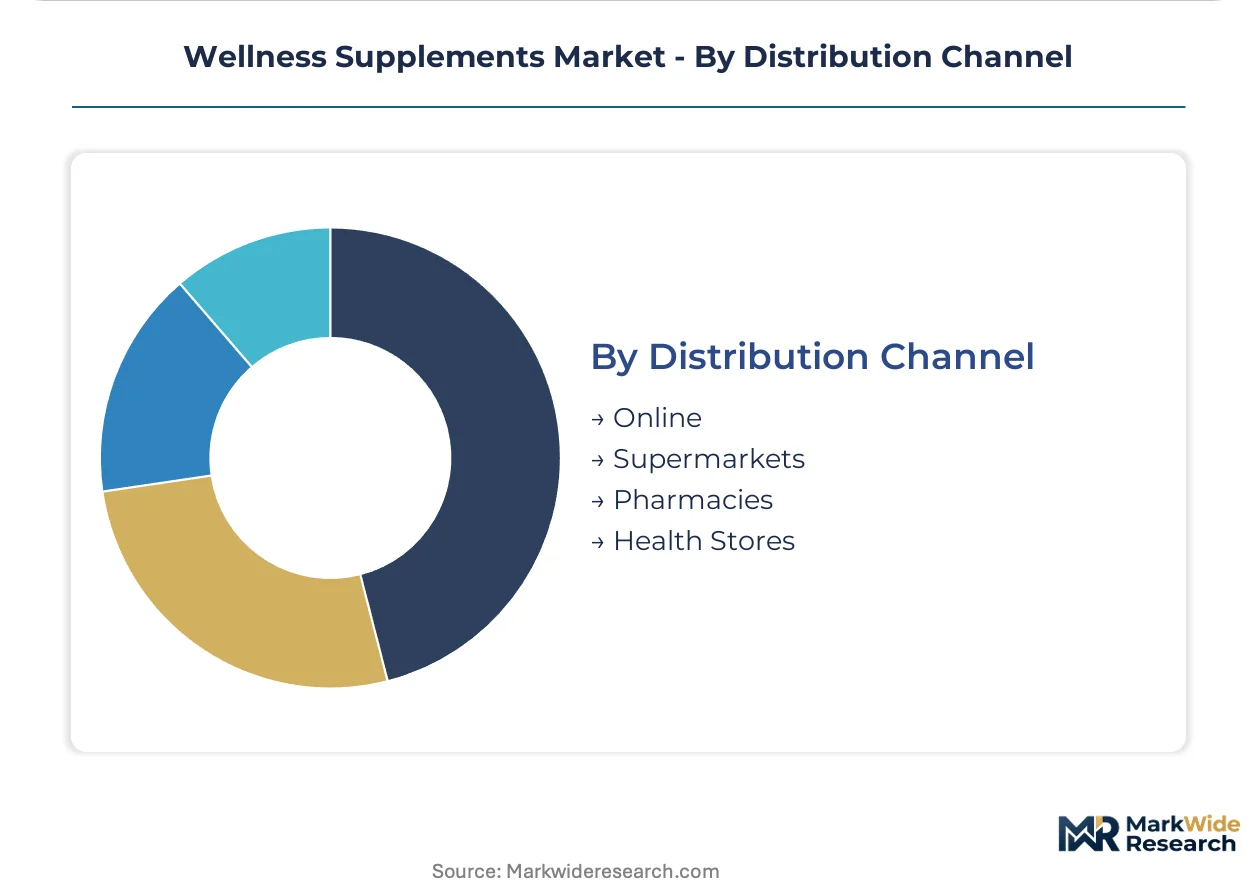
Supermarkets retain volume leadership; online holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets, with direct-to-consumer subscription penetration highest in the United States while pharmacy-channel credibility dominates European purchasing decisions. Asian markets sustain direct-selling networks that resist platform intermediation. These structural differences reshape how formulation science and distribution architecture must align to local purchasing behavior.
United States
Direct-to-consumer subscription platforms concentrate algorithm-curated bundling of multivitamin, sleep, and stress formulations into personalized stacks. FDA Current Good Manufacturing Practice regulations and FTC health claim substantiation requirements create dual compliance burdens that filter smaller entrants from mass-market distribution. New York and California host the densest clusters of platform operators with data infrastructure for recurring revenue models.
Germany
Pharmacy-channel credibility and EFSA-compliant health claim substantiation drive consumer trust in preventive positioning. The EU health claim authorization process demands multi-year clinical investment that redirects innovation toward medical nutrition partnerships. Bavaria and North Rhine-Westphalia concentrate manufacturing facilities serving both domestic pharmacy networks and export markets.
China
Traditional medicine heritage positioning competes with clinical-grade formulations as middle-class consumers seek credibility assurances. NMPA regulations on health food registration and dual carbon goals reshape manufacturing investment toward sustainable processing technologies. Yangtze River Delta clusters around Shanghai dominate supercritical CO2 extraction capacity for standardized botanical concentrates.
Japan
Aging demographics and polypharmacy awareness elevate pharmacist-guided selection of liquid formats and age-appropriate dosing. METI standards for functional food labeling and PMDA oversight of quasi-drugs create tiered regulatory pathways. Kanto region manufacturers specialize in palatable suspension technologies for geriatric swallowing difficulties.
Brazil
Bovine byproduct processing for gelatin capsule shells exposes formulators to livestock cycle volatility while creating raw material concentration risks. ANVISA regulations on dietary supplements and health claims filter unsubstantiated products from pharmacy shelf placement. São Paulo state anchors both capsule shell manufacturing and domestic brand formulation capacity.
Wellness Supplements Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical-adjacent clinical networks competing against direct-selling channel intimacy and platform data infrastructure. Tier differentiation separates substantiation-heavy medical nutrition positioning from generic wellness claims that avoid regulatory scrutiny. Three archetypes dominate: clinical-grade formulators with hospital formulary relationships, direct-selling networks with distributor intimacy, and algorithm-driven subscription platforms with biometric integration. Competitive moves concentrate on M&A for clinical trial infrastructure and strategic partnerships for microbiome sequencing capabilities.
Within the clinical-grade tier, Nestlé Health Science and Abbott Laboratories exemplify pharmaceutical-adjacent positioning that leverages hospital discharge protocols and pharmacy relationships. Amway Corporation anchors the direct-selling archetype across Asian markets, competing on channel intimacy rather than retail shelf access. These three entities represent divergent distribution architectures that resist simple consolidation.
| Leading Market Players |
|---|
| Nestlé Health Science |
| Amway Corporation |
| Abbott Laboratories |
| Herbalife Nutrition Ltd. |
| Glanbia plc |
| Bayer AG |
| Otsuka Holdings |
| GNC Holdings Inc. |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction capacity utilization in Chinese Yangtze River Delta clusters shapes both supply concentration and price floors for standardized botanical concentrates, compressing margins for smaller formulators lacking scale access.
Pricing Analysis
Long-term offtake contracts between Brazilian gelatin processors and United States capsule manufacturers anchor pricing stability for shell materials, while spot purchasing exposes mid-tier brands to livestock cycle volatility. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade EFSA-substantiated formulations from generic wellness claims and commodity vitamin isolates. Cost compression in standard-grade tablets intensifies as beverage fortification substitutes pill-based delivery. Amateur athletes demonstrate lowest price sensitivity due to performance-validation requirements, while adult maintenance users exhibit highest elasticity.
Supply Chain Analysis
Brazil and Argentina anchor bovine-derived gelatin capsule shell production, while China concentrates supercritical CO2 extraction capacity for botanical standardization. Formulation draws from chelated mineral complexes, amino acid isolates, and solvent-extracted phytochemicals. Single-source vulnerability in South American livestock processing exposes shell supply to disease outbreak disruption. Distribution runs through direct-to-consumer subscription platforms, pharmacy formulary networks, and mass-market retail channels with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Registered dietitian scarcity within functional food R&D creates a talent bottleneck that rewards organizations with captive clinical networks or sequencing partnerships.
For Market Incumbents: Compound clinical trial infrastructure investment to defend EFSA-substantiated positioning against algorithm-driven entrants lacking evidentiary depth. Deepen backward integration into supercritical CO2 extraction capacity to secure standardized potency supply. Prioritize microbiome sequencing partnerships that lock in personalized nutrition platform differentiation. For New Entrants and Emerging Players: Pediatric liquid format under-penetration presents service-layer white space where tablet-dominant incumbents under-serve swallowing-difficulty populations. Target pharmacy-guided senior segments in Japan and Germany where pharmacist relationships substitute for brand recognition. Pursue direct-to-clinic sampling programs that bypass saturated subscription acquisition channels. For Investors and Strategic Acquirers: Sequencing-integrated formulation specialists with hospital discharge protocol relationships represent the highest-conviction acquisition archetype across the analysis window. Monitor FDA NDI notification volume as inflection indicator for novel botanical pipeline health. Favor targets with captive registered dietitian teams over pure-play distribution assets.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Infrastructure Expansion | EFSA health claim authorization demands multi-year investment that filters unsubstantiated competitors from premium European pharmacy placement. |
| Microbiome Sequencing Partnership | Synbiotic formulation precision requires bacterial strain-prebiotic substrate matching beyond legacy single-strain probiotic capabilities. |
| Pediatric Liquid Format Development | Palatable suspension technologies address swallowing difficulties in children and geriatric populations underserved by tablet-dominant portfolios. |
| Direct-to-Consumer Subscription Platform | Algorithm-curated bundling transfers margin from brand loyalty to data infrastructure operators with biometric feedback integration. |
| Supercritical CO2 Capacity Addition | Solvent-free botanical extraction unlocks standardized potency pricing previously limited by batch variability in traditional solvent methods. |
Methodological Framework
Cross-validation between primary interviews with formulation scientists, registered dietitians, pharmacy procurement managers, and direct-to-consumer platform operators anchors the qualitative findings. Secondary validation draws from FDA New Dietary Ingredient notifications, EFSA health claim authorization registers, ClinicalTrials.gov supplementation protocols, and customs trade data for raw material flows. Bottom-up segment sizing triangulates against top-down macroeconomic consumption indicators.
Sensitivity analysis across input variables tests forecast robustness over the projection horizon. Segmentation dimensions include product type, formulation format, end-user life stage, and distribution channel architecture. CAGRs derive from modeled adoption curves intersecting with regulatory pathway timelines. Forecast inputs incorporate NDI notification velocity, EFSA authorization success rates, and subscription platform customer acquisition cost trajectories.
Forecasts assume regulatory continuity in FDA Current Good Manufacturing Practice enforcement and EFSA substantiation standards; material policy shifts would require re-modeling. Raw material concentration risks in South American livestock cycles and microbiome-targeted claim scrutiny represent specific revision triggers. Recalibration cycles align with material shifts in NDI notification volume, EFSA authorization decisions, and platform subscriber churn rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
India Personalized Nutrition Market
Nutritional Supplements
Tongkat Ali Extract Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
Maternity Vitamins and Supplements Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
Royal Jelly Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Custom Supplement Formulation Service Market