
 Coq10 Gummies Market | 2026-2036
Coq10 Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
Coq10 Gummies Market Outlook
Aftermarket subscription revenue is reshaping how supplement brands monetize CoQ10 gummy consumers, shifting margin pools from one-time retail purchases toward recurring direct-to-home replenishment. Vitafusion leverages its mass-retail shelf presence to sustain trial-to-repeat conversion at scale. Nature's Bounty anchors its position through backward integration into softgel-to-gummy manufacturing technology. NOW Foods competes on certification density, stacking USP verification with non-GMO Project status to differentiate in crowded retail sets.
CoQ10 gummies are chewable dietary supplements delivering coenzyme Q10 in gelatin or pectin matrices, typically dosed at 100–200 mg per serving to support mitochondrial energy production and cardiovascular function; the format masks the compound's natural bitterness while improving bioavailability through lipid-based carrier systems. Sugar-free formulations now lead product type expansion as diabetic and ketogenic consumers reject traditional sucrose-based matrices, with pectin-derived vegan variants recording the fastest growth trajectory due to clean-label preferences. Pouch packaging is displacing bottles in online channels, where shipping-weight economics and unboxing experience drive subscription retention.
FDA dietary supplement cGMP enforcement and EFSA health claim substantiation requirements are elevating analytical testing burdens, forcing smaller brands to outsource quality documentation or exit the market. The EU's CSRD disclosure mandates will soon require granular supply-chain transparency for imported CoQ10 raw material, advantaging firms with fermented-yeast sourcing over petrochemical-derived synthetic routes. Stakeholders must monitor how FDA's evolving New Dietary Ingredient notification posture affects novel delivery formats before committing capital to next-generation gummy platforms.
Market Dynamics
Clean-label formulation standards under FDA and EFSA guidance are compressing legacy SKU viability while pulling capital toward fermented-yeast sourcing and vegan pectin matrices. This regulatory convergence is redrawing competitive boundaries between synthetic and natural-origin supply chains.
Growth Catalysts
- Preventive Cardiology Adoption:Aging demographics in the United States, Germany, and South Korea are prioritizing convenient supplement formats for cardiovascular maintenance, expanding the addressable consumer base beyond traditional deficiency-driven usage.
- EFSA Health Claim Substantiation:Validated mitochondrial energy claims are enabling premium positioning in European retail channels, differentiating compliant brands from unverified competitors.
- Lipid-Based Carrier Systems:Enhanced bioavailability technologies are improving therapeutic equivalence to softgel formats, eroding historical format-based objections from healthcare practitioners.
Market Restraints
- Kaneka Fermented CoQ10 Concentration:Single-source dependency for premium natural-origin raw material creates supply vulnerability and pricing power asymmetry.
- Synthetic Route Cost Volatility:Petrochemical-derived ubiquinone faces input cost pressure from Solvay and DSM-Firmenich production economics.
- FDA cGMP Enforcement Burden:Elevated analytical testing requirements for novel delivery formats are forcing smaller brands to outsource quality documentation or exit.
Strategic Opportunities
- Subscription Replenishment Channels:Direct-to-home models are capturing recurring revenue pools previously lost to mass retail churn, with pouch packaging optimizing shipping-weight economics.
- Sugar-Free Diabetic Segments:Ketogenic and glycemic-conscious consumers are rejecting sucrose-based matrices, opening formulation differentiation for erythritol and allulose alternatives.
- EU CSRD Supply-Chain Transparency:Mandatory disclosure requirements for imported raw materials will advantage fermented-yeast sourcing over synthetic routes, rewarding early compliance investments.
Industry Challenges
- Softgel-to-Gummy Manufacturing Conversion:Capital equipment retooling for gelatin and pectin matrices demands specialized extrusion and molding infrastructure absent from legacy capsule operations.
- USP Verification Timeline Compression:Certification density requirements for retail placement are extending product development cycles and straining quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coq10 Gummies Market |
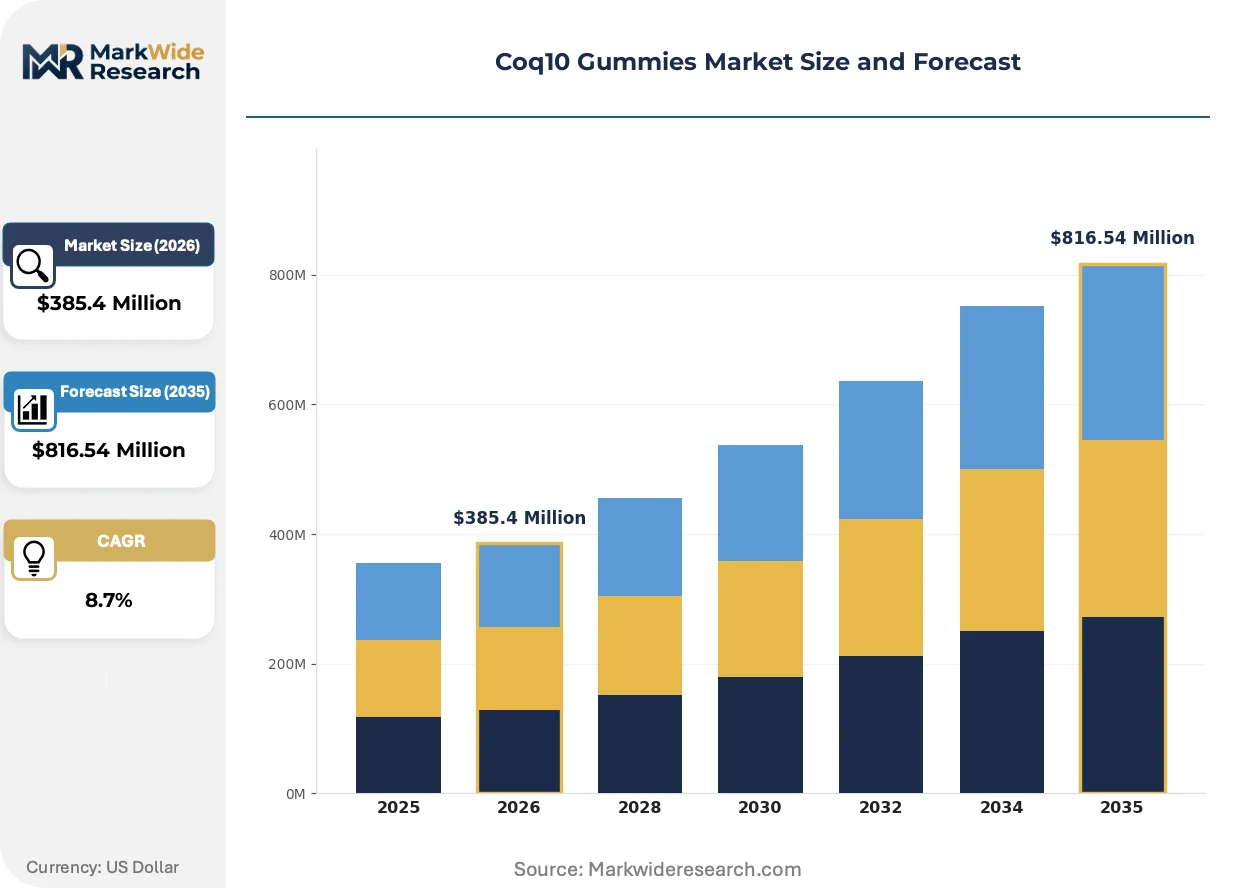
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Vegan, Sugar-Free, Chewable Flavor: Berry, Citrus, Tropical, Mixed Fruit Packaging Type: Bottles, Pouches, Blister Packs, Jars Distribution Channel: Online Stores, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Vitafusion, Nature's Bounty, Nature Made, NOW Foods, Doctor's Best, Jarrow Formulas, Nordic Naturals, Weber Naturals, Jamieson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coq10 Gummies Market Strategic Shifts
Delivery format hybridization is eroding historical boundaries between nutraceutical and pharmaceutical convenience expectations. Three concurrent developments are restructuring how CoQ10 reaches end consumers.
Pectin-based vegan matrices are hybridizing with lipid microencapsulation technologies to replicate the mouthfeel and stability profiles of traditional gelatin gummies. Ketogenic and clean-label consumers in North American natural retail channels are adopting these formulations faster than mass-market sucrose-based alternatives. The convergence is compressing demand for conventional porcine-derived gelatin SKUs and forcing contract manufacturers to retool production lines.
EFSA's evolving health claim substantiation requirements are tightening evidentiary standards for mitochondrial energy positioning statements. Brands with fermented-yeast CoQ10 sourcing are consolidating regulatory documentation advantages over synthetic competitors. German and French retail buyers are now requiring pre-submitted EFSA compliance dossiers as a listing prerequisite, filtering out undercapitalized entrants.
Subscription-based replenishment models are displacing one-time retail purchases as the dominant monetization architecture for recurring-use supplements. Diabetic and aging consumer cohorts in the United States are consolidating purchase decisions around auto-ship programs with flexible dosing intervals. This behavioral pivot is reallocating margin pools from mass retail slotting fees toward direct fulfillment infrastructure and retention analytics capabilities.
Coq10 Gummies Market Segmentation
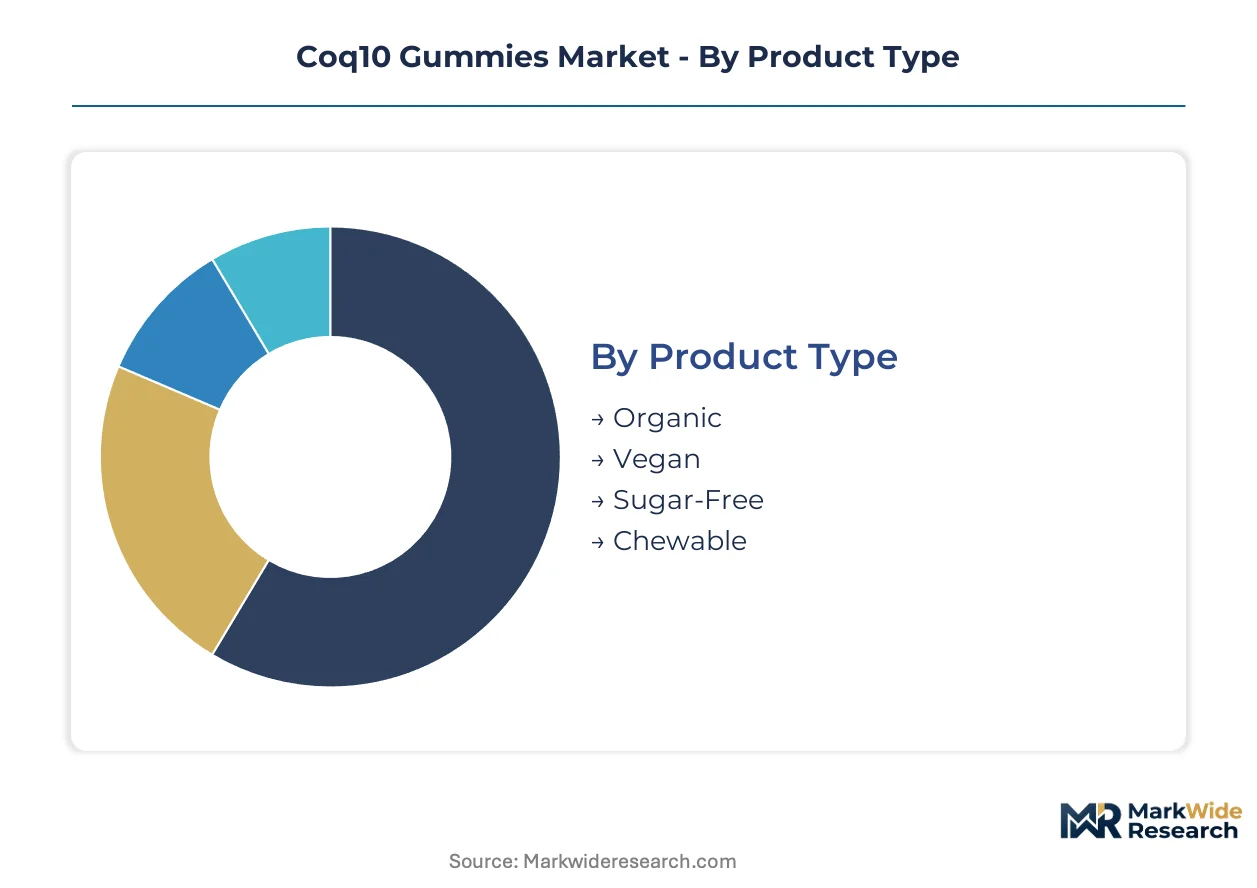
CoQ10 gummy segmentation reveals distinct velocity patterns across formulation and channel dimensions. Product type cycles compress as clean-label preferences accelerate SKU turnover, while packaging formats diverge sharply between retail replenishment and subscription economics.
Product Type:
Cycle times vary dramatically: sugar-free formulations refresh quarterly as diabetic positioning evolves, while organic SKUs turn annually on certification audits.
- Organic:Certified inputs from fermented-yeast CoQ10 and USDA Organic pectin matrices command shelf-space premiums in natural retail channels. German and French buyers now require EFSA-compliant dossiers as listing prerequisites, filtering non-compliant entrants from European distribution.
- Vegan:Pectin-based matrices hybridize with lipid microencapsulation to replicate gelatin mouthfeel and stability profiles. North American natural retail channels adopt these formulations faster than mass-market sucrose alternatives, compressing demand for porcine-derived gelatin SKUs.
- Sugar-Free:Erythritol and allulose alternatives target ketogenic and glycemic-conscious consumers rejecting traditional sucrose matrices.
- Chewable:Gelatin and pectin matrices with lipid-based carrier systems mask CoQ10 bitterness while improving bioavailability.
Sugar-free dominates installed base. Vegan is where expansion concentrates.
Flavor:
Flavor selection tracks demographic targeting precision, with berry and citrus commanding formulation investment while tropical variants serve emerging-market entry.
- Berry:Anthocyanin-compatible natural colorants align with clean-label positioning across US and European mass retail sets.
- Citrus:Ascorbic acid co-formulation opportunities and established consumer acceptance in German and South Korean markets.
- Tropical:Mango and passionfruit profiles target younger demographic trial in online subscription channels.
- Mixed Fruit:Rotation strategies for subscription replenishment programs seeking to reduce flavor fatigue churn.
Berry anchors retail placement. Citrus is climbing the fastest in preventive cardiology positioning.
Packaging Type:
Cost tiers separate single-unit retail from recurring-revenue infrastructure, with pouch economics displacing bottle dominance in direct-to-home channels.
- Bottles:Traditional HDPE and PET containers retain mass-retail shelf presence but face shipping-weight penalties in e-commerce fulfillment.
- Pouches:Flexible film structures optimize shipping-weight economics and unboxing experience for subscription retention. US diabetic and aging cohorts consolidate purchase decisions around auto-ship programs with flexible dosing intervals.
- Blister Packs:Unit-dose compliance packaging for pharmacy channel placement and travel-size trial formats.
- Jars:Premium glass presentations for gift and specialty health store positioning.
Bottles dominate installed base. Pouches are gaining share fastest in margin pool reallocation from retail slotting fees.
Distribution Channel:
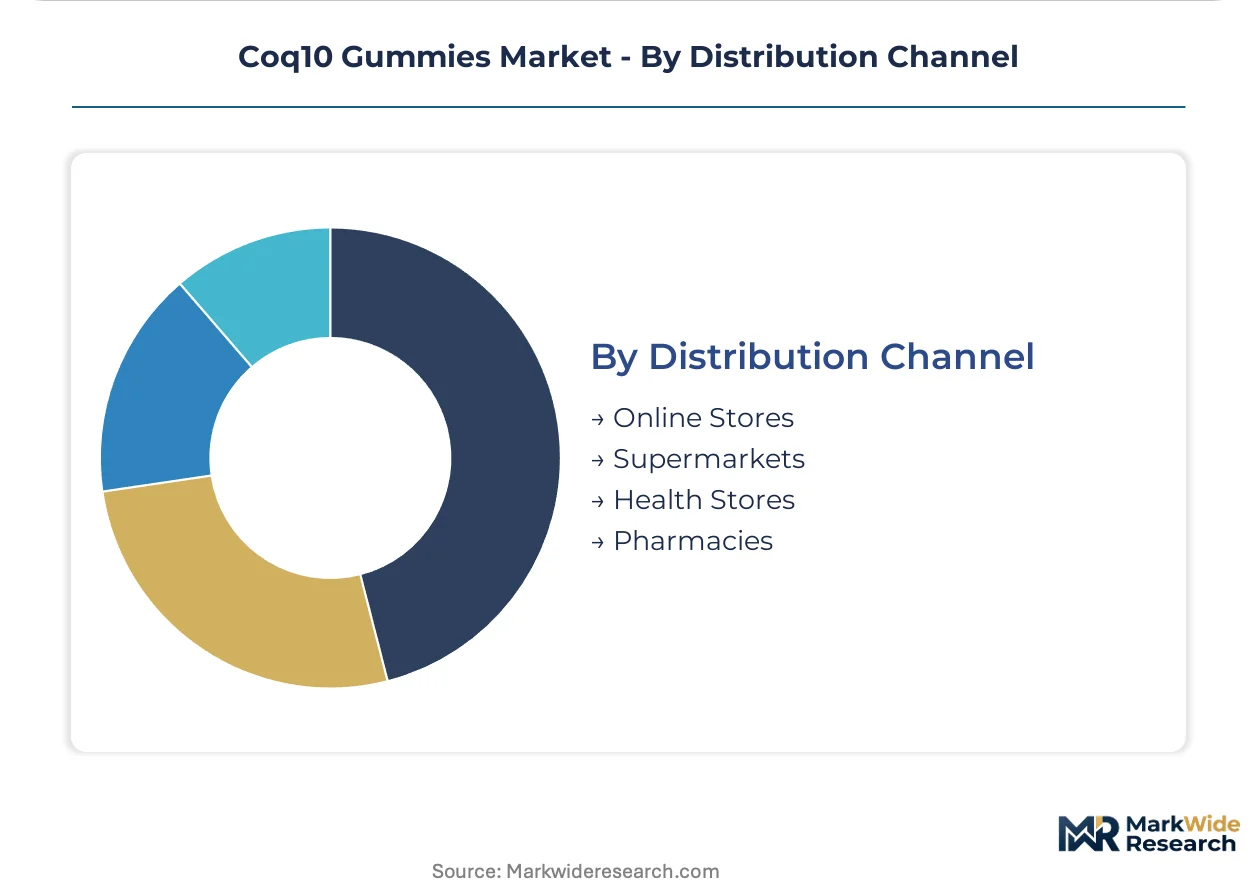
Customer type stratification separates one-time trial from recurring replenishment, with channel selection determining margin architecture and retention analytics investment.
- Online Stores:Direct-to-home models capture recurring revenue pools previously lost to mass retail churn. Subscription infrastructure and retention analytics capabilities reallocate investment from slotting fees toward fulfillment optimization.
- Supermarkets:Mass-retail shelf presence sustains trial-to-repeat conversion at scale through impulse placement and promotional velocity.
- Health Stores:Certification density requirements for USP verification and non-GMO Project status filter assortment in natural retail channels.
- Pharmacies:Healthcare practitioner endorsement channels where lipid-based carrier systems erode historical format-based objections to gummy delivery.
Supermarkets dominate installed base. Online stores are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kaneka's fermented-yeast CoQ10 production in Japan concentrates premium raw material supply, creating pricing power asymmetries that ripple through formulation costs across consumer markets. This single-source dependency shapes competitive positioning in finished gummy manufacturing.
United States
Aging diabetic consumers drive sugar-free gummy adoption through auto-ship subscription models. FDA cGMP enforcement elevates analytical testing burdens for novel delivery formats. New Jersey and California host contract manufacturing clusters where softgel-to-gummy retooling accelerates.
Germany
Preventive cardiology applications expand the consumer base beyond deficiency-driven usage. EFSA health claim substantiation requirements filter non-compliant entrants from retail distribution. Bavaria-based natural retail buyers now mandate pre-submitted compliance dossiers as listing prerequisites.
South Korea
Convenient supplement formats gain traction among aging demographics prioritizing cardiovascular maintenance. MFDS regulatory alignment with international standards facilitates premium positioning. Seoul metropolitan area concentrates e-commerce subscription infrastructure for direct-to-home replenishment.
France
Clean-label preferences accelerate pectin-based vegan formulation cycles in natural retail channels. ANSM oversight of dietary supplement quality documentation advantages fermented-yeast sourcing. Paris-region health stores filter assortment through certification density requirements.
United Kingdom
Post-Brexit regulatory divergence creates dual-track compliance costs for cross-channel distribution. MHRA notification procedures for novel food supplements extend product development timelines. London anchors direct-to-consumer subscription platform development for recurring revenue capture.
Coq10 Gummies Market Competitive Environment
Mass-market retail anchors and specialty health store specialists split the market between trial-to-repeat conversion at scale and certification-driven premium positioning. The vendor base clusters around three strategic archetypes: backward-integrated manufacturers controlling softgel-to-gummy conversion technology, certification-dense brands stacking USP verification with non-GMO Project status, and subscription-native platforms optimizing pouch packaging for shipping-weight economics. Dominant competitive moves include manufacturing technology licensing agreements and direct-to-consumer fulfillment infrastructure buildouts.
Among mass-market retail anchors, Vitafusion and Nature's Bounty exemplify the trial-to-repeat conversion archetype through shelf presence economics, while NOW Foods occupies a position within the certification-dense tier where verification stacking differentiates crowded retail sets. These three companies represent the strategic divergence between scale-driven mass retail and compliance-driven specialty positioning.
| Leading Market Players |
|---|
| Vitafusion |
| Nature's Bounty |
| Nature Made |
| NOW Foods |
| Doctor's Best |
| Jarrow Formulas |
| Nordic Naturals |
| Weber Naturals |
| Jamieson |
| Others |
Value Chain & Pricing Dynamics
Kaneka's fermented-yeast CoQ10 production in Japan concentrates premium raw material supply, anchoring margin pools in finished gummy manufacturing downstream. Pricing power asymmetries ripple through formulation costs as brands compete on certification density and delivery format innovation.
Pricing Analysis
FDA cGMP and EFSA health claim substantiation requirements dictate the pricing tier structure across the CoQ10 gummy market. Three-tier pricing stratifies across premium fermented-yeast formulations, standard synthetic-origin products, and economy private-label alternatives. Price differentiation hinges on USP verification stacking and clean-label certification density. Cost compression in synthetic ubiquinone is intensifying because petrochemical input volatility from Solvay and DSM-Firmenich production economics squeezes mid-tier margins. Mass-market retail buyers show highest price sensitivity, while aging diabetic consumers in subscription channels accept premium positioning for sugar-free pectin matrices.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now structure working capital flows between contract manufacturers and raw material distributors. Raw material sourcing draws from Japan for fermented-yeast CoQ10, China for pectin and gelatin matrices, and India for botanical excipients. Supply chain risk centers on Kaneka's single-source dominance for premium natural-origin ubiquinol. Distribution runs through direct-to-home subscription platforms, mass-retail replenishment networks, and pharmacy channel partnerships with diverging margin architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where EFSA and FDA regulatory entrenchment creates sustainable barriers. Switching costs for certified supply chains and validated health claims documentation protect incumbent positioning.
For Market Incumbents: Entrench through backward integration into softgel-to-gummy manufacturing technology and captive supply agreements with fermented-yeast CoQ10 producers. Smaller brands exiting under FDA cGMP enforcement burdens create acquisition opportunities for compliant capacity. Prioritize USP verification timeline compression to accelerate product development cycles ahead of retail listing deadlines. For New Entrants and Emerging Players: Sugar-free diabetic segments in United States auto-ship channels represent the most penetrable entry point for differentiated erythritol and allulose formulations. EU CSRD supply-chain transparency mandates advantage early compliance investments in fermented-yeast sourcing documentation. Go-to-market through pouch-packaging subscription-native platforms bypasses mass-retail slotting fee barriers. For Investors and Strategic Acquirers: Capital is best deployed toward certification-dense brands with stacked USP verification and non-GMO Project status that filter assortment in natural retail channels. Long-term viability over a multi-year horizon rests on regulatory documentation advantages and direct-to-consumer fulfillment infrastructure. Monitor FDA's evolving New Dietary Ingredient notification posture as the critical inflection signal for novel delivery format platform investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Softgel-to-Gummy Manufacturing | Captures margin pools from contract manufacturing and accelerates SKU refresh cycles. |
| Fermented-Yeast CoQ10 Supply Agreement | Secures premium raw material access ahead of EU CSRD disclosure mandate enforcement. |
| USP Verification Stacking Program | Differentiates retail placement in crowded mass-market and natural channel sets. |
| Pouch Packaging Subscription Platform Launch | Optimizes shipping-weight economics and unboxing experience for diabetic cohort retention. |
| Sugar-Free Formulation Line Extension | Targets ketogenic and glycemic-conscious consumers rejecting traditional sucrose matrices. |
Study Parameters
Operator-level perspectives from brand managers, contract manufacturing plant directors, natural retail category buyers, and pharmacy channel procurement leads anchored the qualitative base. Primary interview data combined with secondary validation from FDA cGMP inspection records, EFSA health claim submission databases, USP verification registries, and customs import documentation for CoQ10 raw materials. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates.
Scenario-bracketing around regulatory enforcement intensity and raw material supply disruption anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging format, flavor profile, and distribution channel with regional regulatory cluster overlays. CAGRs derived from trend-line extrapolation of subscription adoption curves and clean-label SKU turnover rates, cross-referenced against aging demographic cardiovascular supplement penetration benchmarks.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on preventive health or freight and packaging input costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory timeline adherence and fermented-yeast capacity expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Fish Collagen Market
Nutritional Supplements
North America Memory Supplements Market
Nutritional Supplements
Bee Pollen Supplements Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
South America Nutraceuticals Market
Nutritional Supplements
Melatonin Supplements Market
Nutritional Supplements
Global Digestive Enzyme Supplements Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Chaga Mushroom Extract Market
Nutritional Supplements
Isoleucine Market
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market