
 Omega-3 Fish Oils Market | 2026-2036
Omega-3 Fish Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Omega-3 Fish Oils Market Insights
Peruvian anchovy catch cycles is shifting as the dominant supply-side variable for global omega-3 raw material flows. Omega Protein Corporation leverages vertical integration across its Gulf of Mexico menhaden fleet to sustain cost advantages in bulk fish oil supply. Cargill anchors its position through backward integration into aquaculture feed chains, securing dedicated offtake for omega-3 refinement. Croda International Plc differentiates via pharmaceutical-grade ethyl ester capabilities that command premium positioning in regulated drug applications.
Omega-3 fish oils comprise long-chain polyunsaturated fatty acids—primarily eicosapentaenoic acid and docosahexaenoic acid—extracted from marine biomass through molecular distillation or supercritical CO2 processing, then concentrated to therapeutic purity levels for cardiovascular, neurological, and anti-inflammatory applications. The triglyceride form retains natural molecular structure and dominates consumer supplement preference, while ethyl esters capture the pharmaceutical channel where prescription Lovaza and Vascepa equivalents require standardized API-grade inputs. Dietary supplements occupies the largest volume position, though pharmaceutical end-use extracts disproportionate value per kilogram due to regulatory validation burdens.
FDA maintains current Good Manufacturing Practice oversight for omega-3 drug products, while EMA enforces ICH Q3D elemental impurity limits that filter out unqualified suppliers. The EU Green Deal's sustainable fisheries quotas and F-Gas Regulation constraints on extraction solvents are tightening process economics for European refiners. Stakeholders must monitor how stricter maximum residue limits for environmental contaminants reshape sourcing geography and whether algal oil alternatives displace wild-catch dependence in premium positioning.
Market Dynamics
Pharmaceutical-grade purification standards are compressing margins for commodity-grade refiners while rewarding ethyl ester specialists with prescription drug channel access. EMA's tightened ICH Q3D elemental impurity limits and FDA's current Good Manufacturing Practice enforcement are bifurcating the supplier base into qualified API-grade producers and excluded bulk oil traders.
Growth Catalysts
- Cardiometabolic prescription positioning:Vascepa-equivalent therapies in the United States are pulling omega-3 APIs through validated drug channels. Formulators secure reimbursement by meeting FDA purity benchmarks.
- EU Green Deal fisheries reform:Sustainable catch quotas in European waters are redirecting investment toward certified supply chains. Retail buyers now demand Marine Stewardship Council documentation.
- Supercritical CO2 extraction scaling:This solvent-free processing technology is displacing molecular distillation in premium positioning. Clean-label supplement brands adopt it for contaminant-free marketing claims.
Market Restraints
- Anchovy biomass volatility:Peruvian catch cycles swing 30-40% seasonally, concentrating supply risk in Humboldt Current fisheries. Refiners face raw material cost spikes during El Niño disruptions.
- Algal oil substitution economics:Fermentation-derived DHA from Schizochytrium strains is capturing premium vegan positioning. Wild-catch dependence becomes a liability in clean-label channels.
- EMA F-Gas solvent constraints:The regulation limits hydrofluorocarbon use in extraction processes. European refiners absorb retrofit costs or exit pharmaceutical-grade production.
Strategic Opportunities
- India nutraceutical underpenetration:FSSAI's 2022 dietary supplement regulations created compliance clarity. Domestic brands now build omega-3 portfolios for cardiometabolic health positioning.
- Direct-to-consumer subscription models:Freshness-guaranteed delivery is bypassing retail pharmacy markups. US wellness platforms capture recurring revenue through personalized dosing algorithms.
- Pet therapeutic applications:Veterinary cardiometabolic protocols are adopting human-grade EPA/DHA ratios. Premium pet food channels absorb pharmaceutical-grade surplus at reduced specification.
Industry Challenges
- Pharmaceutical validation timelines:Drug Master File preparation for FDA submission requires 18-24 months. API-grade refiners face working capital strain during qualification gaps.
- Cross-contamination control infrastructure:Shared facilities processing both food-grade and pharmaceutical-grade oils require segregated cleanroom investments. Mid-scale operators defer capex and lose prescription channel access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omega-3 Fish Oils Market |
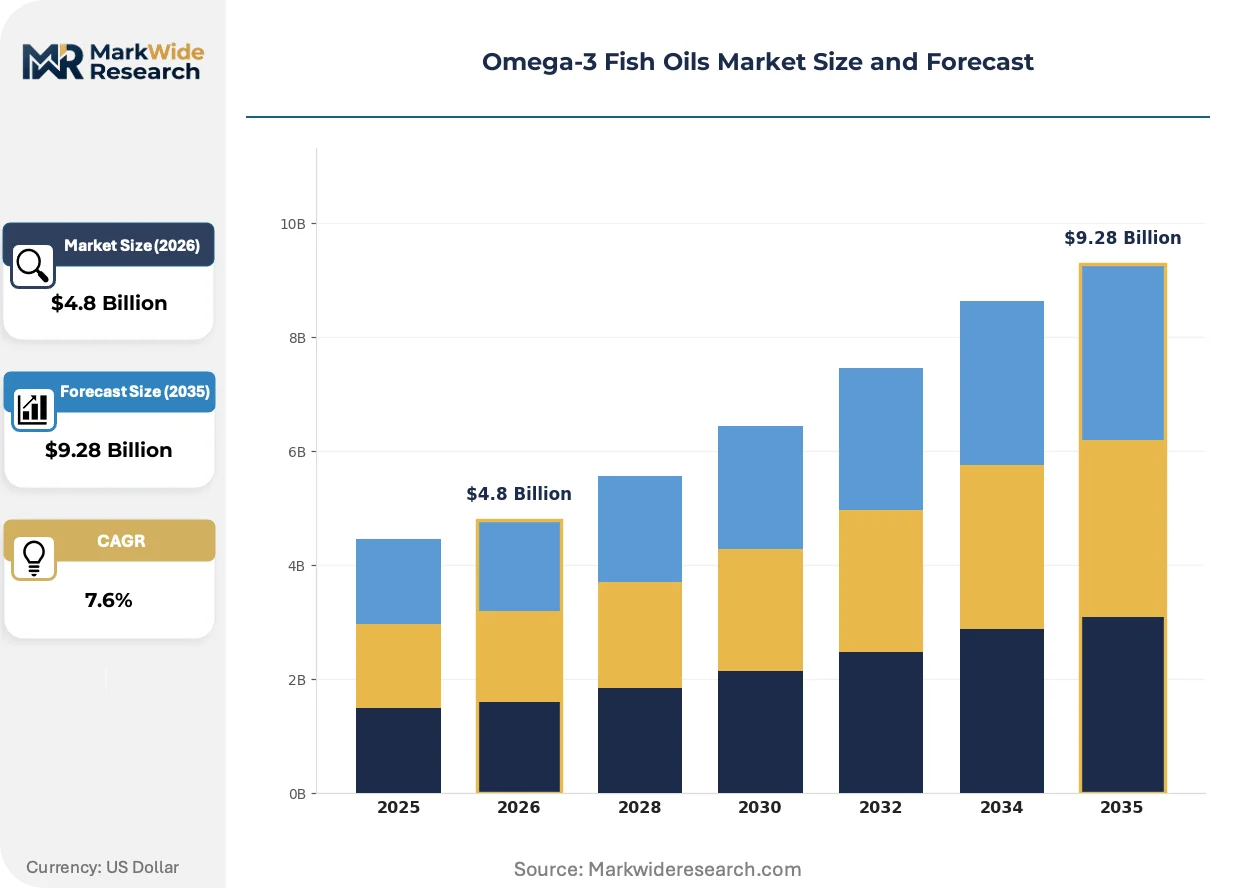
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethyl Esters, Triglycerides, Natural Concentrates, Synthetic Compounds End User: Dietary Supplements, Pharmaceuticals, Food & Beverage, Cosmetics Source: Fish Oil, Algal Oil, Krill Oil, Cod Liver Oil Packaging Type: Capsules, Liquid Bottles, Softgels, Bulk Packaging |
| Companies Covered | Omega Protein Corporation, Cargill, Croda International Plc, GC Rieber Oils, Olvea Fish Oils, Pharma Marine AS, BASF SE, Aker BioMarine Antarctic AS, EPAX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omega-3 Fish Oils Market Trends and Innovations
Extraction technology and regulatory geography are rewriting competitive boundaries. Refiners now compete on molecular specificity rather than volume scale, while channel control shifts toward platforms that verify provenance.
Enzymatic re-esterification is absorbing market share from traditional ethyl ester production. This biotechnology restores triglyceride molecular structure with pharmaceutical-grade purity. Nordic supplement brands adopt it for premium positioning that commands 40% price premiums over standard concentrates. The technology is absorbing volume from commodity bulk oil traders who lack enzymatic capability.
REACH authorization requirements for processing solvents are tightening European refiner economics. ECHA's sunset date scheduling forces substitution of legacy extraction chemicals. German and Dutch facilities absorb compliance costs while Southern European competitors exit API-grade production. The regulation is concentrating pharmaceutical supply among REACH-authorized producers.
Blockchain-enabled provenance verification is displacing paper-based chain-of-custody documentation. Retail pharmacy buyers in Germany and France now require immutable catch-to-capsule tracking. Marine Stewardship Council certification integrates with distributed ledger systems for real-time quota verification. This shift is most visible in Northern European markets where environmental accountability drives purchasing decisions.
Omega-3 Fish Oils Market Segmentation
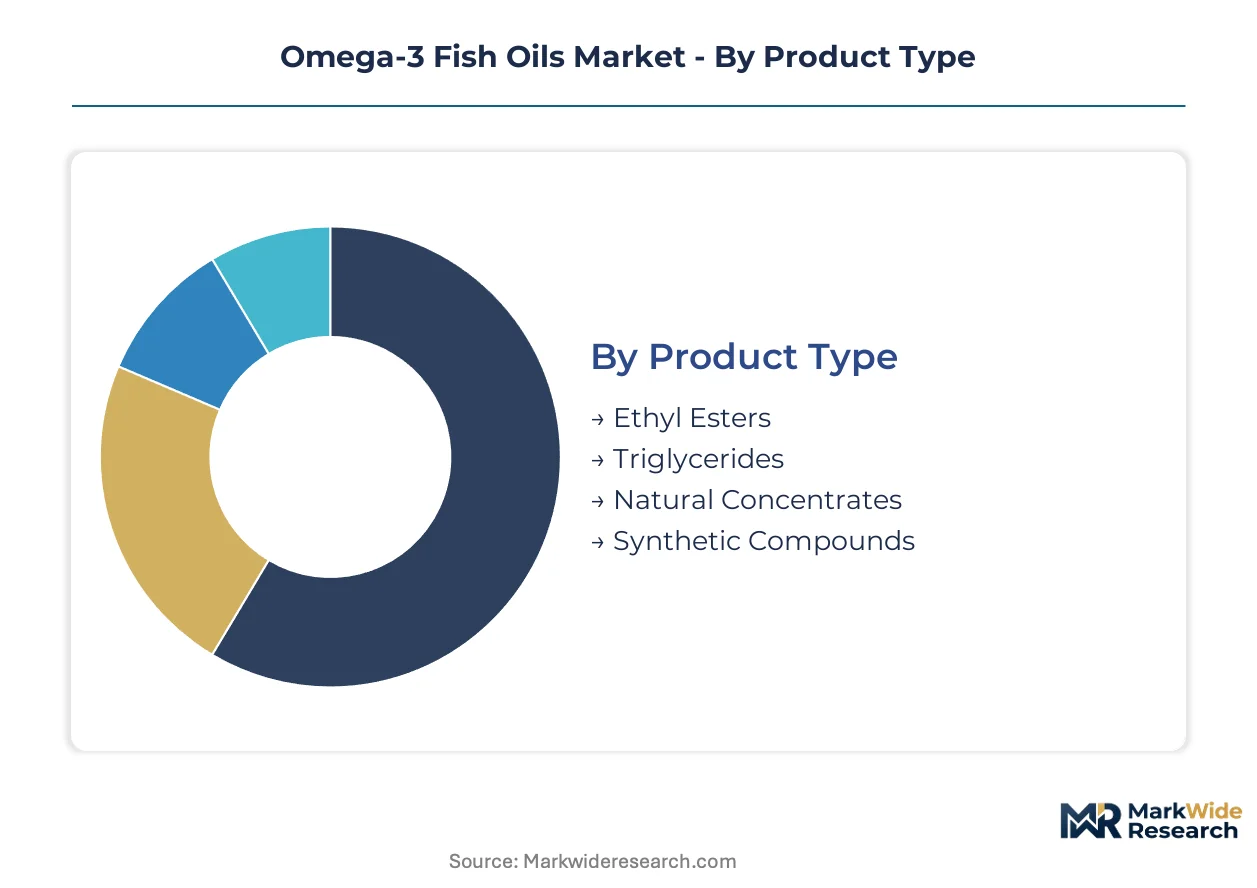
Omega-3 fish oil segmentation reflects divergent purity requirements across prescription drug, supplement, and functional food channels. Formulators select molecular forms and sourcing strategies based on regulatory pathway and end-use specification.
Product Type:
Standardization intensity varies sharply across this category, from tightly specified pharmaceutical APIs to loosely regulated natural concentrates.
- Ethyl Esters:Synthetic molecular form produced by esterification of free fatty acids with ethanol. FDA Drug Master File requirements concentrate demand in United States prescription channels where Vascepa-equivalent therapies require standardized EPA purity above 96%. EMA's ICH Q3D elemental impurity limits filter out unqualified European suppliers.
- Triglycerides:Natural molecular structure retaining glycerol backbone integrity through enzymatic re-esterification. Consumer supplement preference in Germany and France drives premium positioning, with Nordic brands commanding price premiums through contaminant-free supercritical CO2 extraction claims.
- Natural Concentrates:Partially purified fish oil retaining mixed molecular forms.
- Synthetic Compounds:Laboratory-engineered EPA/DHA analogues for specialized therapeutic applications.
Most installed capacity flows through Triglycerides. Expansion is steepest in Ethyl Esters.
End User:
Margin structure follows regulatory burden intensity, with pharmaceutical validation extracting disproportionate value per kilogram.
- Dietary Supplements:Largest volume position serving wellness-positioned consumers. United States cardiometabolic health marketing drives shelf placement, though FDA structure-function claim restrictions limit therapeutic messaging. Direct-to-consumer subscription platforms capture recurring revenue through personalized dosing algorithms.
- Pharmaceuticals:Prescription drug channel requiring API-grade purity and validated manufacturing. Reimbursement-dependent uptake in United States cardiovascular protocols concentrates demand among qualified suppliers with active Drug Master Files.
- Food & Beverage:Functional fortification in dairy, infant formula, and bakery applications.
- Cosmetics:Topical anti-inflammatory positioning in premium skincare formulations.
Pharmaceuticals absorb the highest margin per ton. Dietary Supplements represent the fastest-growing trajectory by absolute volume.
Source:
Supply geography and sustainability certification increasingly determine channel access and pricing power.
- Fish Oil:Dominant raw material extracted from Peruvian anchovy and Gulf of Mexico menhaden through molecular distillation or supercritical CO2 processing. El Niño disruptions in Humboldt Current fisheries concentrate supply risk and drive seasonal cost volatility.
- Algal Oil:Fermentation-derived DHA from Schizochytrium strains capturing vegan-positioned premium channels. Clean-label substitution threat to wild-catch dependence strengthens as biotechnology scales.
- Krill Oil:Antarctic biomass with phospholipid-bound omega-3 structure.
- Cod Liver Oil:Traditional Nordic source with natural vitamin A/D co-occurrence.
Fish Oil retains most installed refining capacity. Algal Oil is climbing the fastest as biotechnology investment accelerates.
Packaging Type:
Channel economics and oxidation sensitivity dictate format selection across retail, institutional, and prescription pathways.
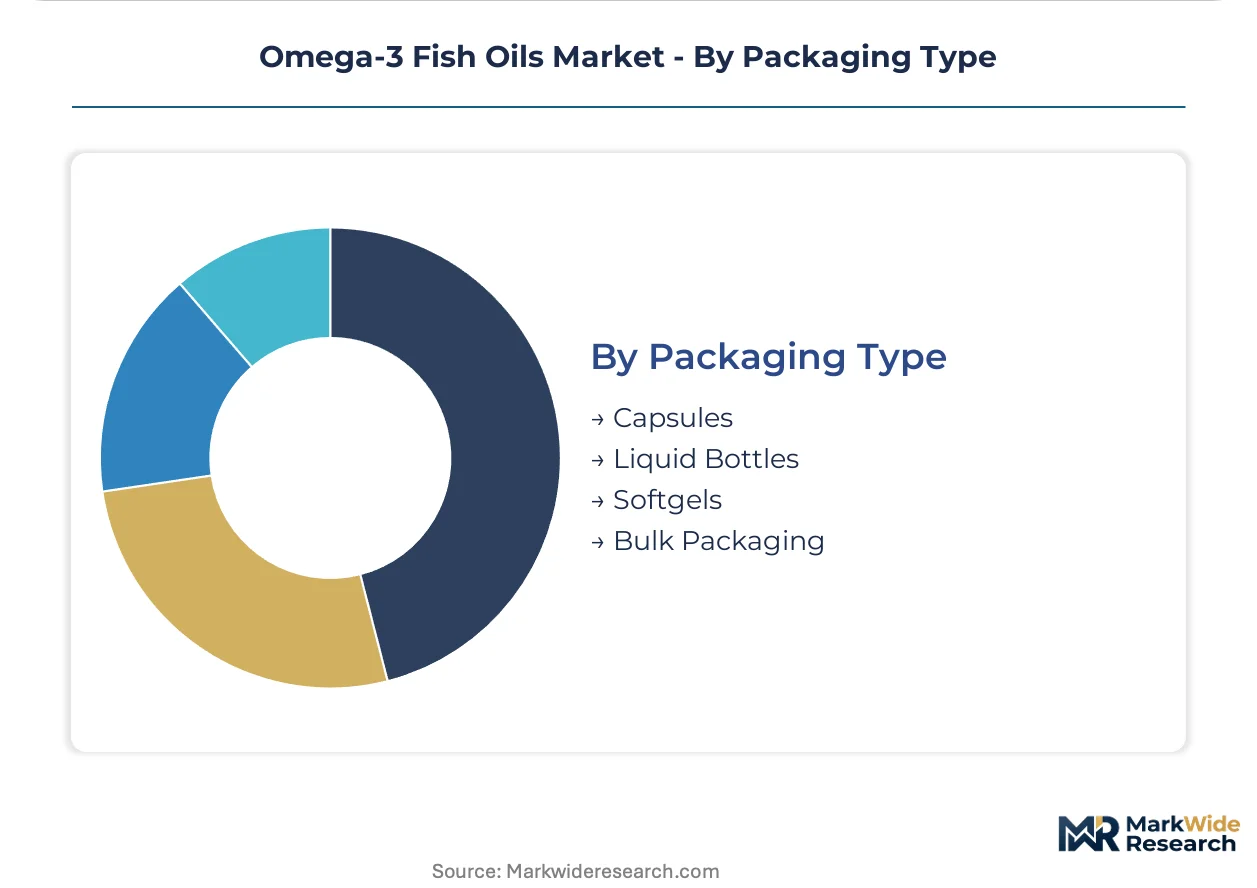
- Softgels:Dominant consumer format with gelatin or plant-based shell protection against oxidative degradation. United States retail pharmacy and wellness platform distribution concentrates demand, with nitrogen-flushed blister packs extending shelf stability claims.
- Capsules:Two-piece hard shell format for powder or oil filling.
- Liquid Bottles:Bulk family sizing and food service applications requiring refrigeration.
- Bulk Packaging:Drums and totes for pharmaceutical API shipment and food manufacturing integration.
Softgels command most consumer-facing volume. Bulk Packaging is gaining share fastest as pharmaceutical API trade intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting omega-3 refining capacity toward jurisdictions with lower compliance burdens. EMA's ICH Q3D limits and REACH solvent restrictions are pushing pharmaceutical-grade production away from European refiners toward North American and Asian facilities with lighter environmental overhead.
United States
FDA's cGMP enforcement for prescription omega-3 therapies concentrates API-grade demand in validated manufacturing corridors. Vascepa-equivalent reimbursement protocols pull ethyl ester volumes through qualified drug channels. The Gulf Coast refining cluster around Houston anchors bulk menhaden processing for domestic supplement and pharmaceutical feedstock supply.
Germany
REACH authorization deadlines for extraction solvents are forcing retrofit investments at Hamburg and Bremen refining facilities. ECHA's sunset date scheduling eliminates unqualified competitors from pharmaceutical-grade production. Marine Stewardship Council certification requirements from retail pharmacy buyers concentrate premium triglyceride supply among REACH-authorized producers in Northern port cities.
China
NMPA's dietary supplement registration reforms are clarifying import pathways for omega-3 finished goods. Domestic brands build cardiometabolic portfolios under streamlined FSSAI-equivalent compliance frameworks. The Yangtze River Delta refining corridor scales supercritical CO2 extraction capacity to serve clean-label export demand from European wellness platforms.
India
FSSAI's 2022 nutraceutical regulations created compliance clarity for domestic omega-3 brand development. Cardiometabolic health marketing drives supplement uptake in urban Maharashtra and Karnataka corridors. Mumbai-based formulators contract with Peruvian anchovy suppliers to bypass European regulatory bottlenecks for standard-grade concentrate imports.
Norway
Marine Stewardship Council integration with blockchain provenance systems concentrates premium positioning among Arctic Circle refiners. Pharma Marine AS and EPAX anchor pharmaceutical-grade ethyl ester output from Bergen-area facilities. Norwegian producers leverage immutable catch-to-capsule tracking to capture German and French retail pharmacy shelf space.
Omega-3 Fish Oils Market Competitive Landscape
North American producers anchor the bulk supply tier; European specialists hold pharmaceutical-grade positioning. The supplier base bifurcates between qualified API-grade producers with active Drug Master Files and excluded commodity traders lacking cleanroom infrastructure. Three archetypes dominate: vertically integrated fishing fleet operators, biotechnology-enabled enzymatic refiners, and algal fermentation specialists. Competitive moves center on backward integration into aquaculture feed chains and supercritical CO2 extraction licensing.
Within the fishing fleet integration tier, Omega Protein Corporation exemplifies captive supply control over Gulf of Mexico menhaden biomass. Among European pharmaceutical specialists, Croda International Plc and GC Rieber Oils occupy positions defined by ethyl ester purity capabilities and REACH-authorized solvent handling. These named entities represent the geographic and regulatory segmentation shaping channel access rather than absolute scale dominance.
| Leading Market Players |
|---|
| Omega Protein Corporation |
| Cargill |
| Croda International Plc |
| GC Rieber Oils |
| Olvea Fish Oils |
| Pharma Marine AS |
| BASF SE |
| Aker BioMarine Antarctic AS |
| EPAX |
| Others |
Pricing and Supply Chain Analysis
Supercritical CO2 extraction specialists concentrated in Norway and Germany command wage premiums that compress margins at standard-grade refiners, widening spreads between pharmaceutical-grade ethyl esters and commodity bulk oils. Labor-cost differentials between REACH-authorized facilities and legacy solvent operators translate directly into three-tier pricing stratification across premium, standard, and economy certification levels.
Pricing Analysis
Distributor margins on pharmaceutical-grade ethyl esters absorb the steepest markups in United States prescription channels where FDA Drug Master File validation creates scarcity value. Price differentiation separates API-grade producers with active regulatory filings from excluded bulk traders lacking cleanroom infrastructure. Cost compression in commodity triglyceride concentrates is intensifying because algal oil substitutes erode wild-catch premium positioning. Direct-to-consumer subscription platforms exhibit the lowest price sensitivity, while institutional food manufacturers purchasing bulk drums drive the hardest volume negotiations.
Supply Chain Analysis
Anchovy biomass supply rests on Peruvian Humboldt Current fisheries, with Gulf of Mexico menhaden and Norwegian Arctic cod liver anchoring secondary raw material flows. Critical inputs span fishing fleet access rights, molecular distillation capacity, and enzymatic re-esterification biotechnology. Single-source vulnerability concentrates in El Niño-disrupted anchovy catch cycles that trigger raw material cost spikes. Distribution runs through pharmaceutical API bulk shipments to drug manufacturers, softgel contract packagers for retail pharmacy, and nitrogen-flushed direct-to-consumer subscription fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA's ICH Q3D elemental impurity limits and REACH solvent restrictions continuously filter supplier qualification, concentrating margin capture among compliant producers.
For Market Incumbents: Anchor pharmaceutical-grade positioning through backward integration into certified fishing fleet operations or captive aquaculture feed chains. Defend against algal oil substitution by securing Marine Stewardship Council documentation integrated with blockchain provenance systems. Prioritize enzymatic re-esterification capacity additions in REACH-authorized geographies to capture Nordic premium supplement demand. For New Entrants and Emerging Players: Wellness platform channel partners offer the most penetrable entry vector for direct-to-consumer subscription models bypassing retail pharmacy markups. Target India's FSSAI-compliant cardiometabolic supplement segment where domestic brand development lags prescription-channel maturation. Pursue veterinary therapeutic applications as a white-space channel absorbing pharmaceutical-grade surplus at reduced specification thresholds. For Investors and Strategic Acquirers: Pharmaceutical formulators with prescription omega-3 portfolios are the most active acquirers in this space, seeking captive API supply security. Long-term viability hinges on regulatory qualification durability rather than volume scale, with five-to-ten year windows favoring ethyl ester specialists over commodity refiners. Watch EMA F-Gas Regulation enforcement timelines as inflection indicators for European refiner exit acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Scale-Up | Clean-label supplement brands in Germany and France adopt solvent-free processing for contaminant-free marketing claims. |
| Enzymatic Re-esterification Licensing | Nordic producers command price premiums by restoring natural triglyceride structure with pharmaceutical-grade purity. |
| Blockchain Provenance Integration | Marine Stewardship Council certification merges with distributed ledgers for real-time quota verification in Northern European retail pharmacy. |
| Direct-to-Consumer Subscription Launch | United States wellness platforms capture recurring revenue through personalized EPA/DHA dosing algorithms. |
| Veterinary Therapeutic Portfolio Extension | Premium pet food channels absorb human-grade surplus at reduced specification while expanding addressable market. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Refinery operations directors, pharmaceutical procurement managers at drug manufacturers, dietary supplement brand managers, and regulatory affairs specialists at API-grade producers provided structured interviews. Secondary sources incorporated FDA Drug Master File databases, EMA ICH Q3D guidance documents, Marine Stewardship Council catch certification records, and REACH authorization status registries. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Rate-of-change decomposition separated volume growth drivers from price-mix effects across molecular form, end-use channel, and source type dimensions. Segmentation modeling captured ethyl ester versus triglyceride demand splits, pharmaceutical versus supplement channel dynamics, and fish oil versus algal oil substitution trajectories. CAGRs derived from fitted trend projections incorporating regulatory milestone impacts and biotechnology adoption curves. Forecast inputs included Peruvian anchovy biomass survey data and supercritical CO2 extraction capacity expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to El Niño frequency intensification, algal oil fermentation cost breakthroughs, and EMA solvent restriction enforcement escalation. Projections reflect documented assumptions regarding regulatory qualification timelines and clean-label substitution elasticity. A small set of named triggers warrants ongoing watch: Peruvian catch cycle disruption, REACH sunset date acceleration, and pharmaceutical-grade refiner consolidation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
South Africa Nutraceuticals Market
Nutritional Supplements
Asia-Pacific Dietary Supplement Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Omega-3 Products Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Cordyceps Product Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
North America Insoluble Dietary Fibers Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
Algae Omega 3 Market
Nutritional Supplements
Electrolyte Powder Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market