
 Mediterranean Citrus Nutricosmetic Complex Market | 2026-2036
Mediterranean Citrus Nutricosmetic Complex Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Citrus Nutricosmetic Complex Market Insights
Wellness centers and dermatology clinics are recalibrating their professional treatment menus toward ingestible beauty protocols, pulling Mediterranean citrus complexes into clinical-grade service offerings. Monteloeder leverages its Spanish extraction heritage to dominate citrus flavonoid supply for Mediterranean spa chains. Euromed anchors its position through controlled sourcing from Italian blood orange cultivars, while dsm-firmenich competes via integrated fragrance-nutrition platforms that bridge cosmetic and nutraceutical channels.
Mediterranean Citrus Nutricosmetic Complex denotes standardized botanical preparations derived from Citrus species native to or cultivated within the Mediterranean basin, typically containing specified polyphenol and flavonoid concentrations achieved through cold-press or supercritical CO2 extraction, formulated for oral or topical delivery to modulate oxidative stress markers in skin and hair matrices. Extracts and capsules command the dominant revenue share due to dosage precision and shelf stability, though beverage formats are gaining fastest among younger demographics seeking functional hydration. Skin brightening and anti-aging applications concentrate margin pools, while UV protection segments remain nascent pending clinical substantiation thresholds.
EMA cosmetic ingredient guidelines, REACH substance registration requirements, and EU Green Deal farm-to-fork traceability mandates collectively shape formulation standards and raw material documentation burdens for Mediterranean suppliers. EFSA health claim authorization processes determine which bioactive descriptors survive on product labels, directly constraining marketing architecture and premium positioning. Stakeholders must monitor evolving substantiation requirements for polyphenol-specific claims and calibrate R&D pipelines toward clinically validated delivery mechanisms rather than commodity extraction.
Market Dynamics
REACH substance registration deadlines and EU Green Deal traceability mandates are compressing supplier qualification timelines while simultaneously rewarding Spanish and Italian extraction clusters with verified cold-chain documentation. This regulatory tightening favors established Mediterranean processors over new entrants lacking multi-year batch records.
Growth Catalysts
- EFSA health claim pathways:Authorized polyphenol descriptors enable premium positioning for Valencia-derived hesperidin complexes in French dermocosmetic channels.
- Wellness center protocol integration:Clinical-grade service menus across Barcelona and Milan spa networks are standardizing ingestible beauty as a treatment modality.
- Supercritical CO2 extraction scale-up:Equipment manufacturers in southern Italy report capacity expansions serving blood orange flavonoid processors.
Market Restraints
- Raw material concentration risk:Valencia citrus belt frost events expose formulation houses to supply interruptions without secondary sourcing.
- REACH registration cost structure:Small-scale Sicilian extractors face documentation burdens that erode margin on sub-tonnage citrus bergamot batches.
- Clinical substantiation thresholds:UV protection claims require photodermatology studies that most Mediterranean suppliers cannot fund independently.
Strategic Opportunities
- Greek citrus underutilization:Peloponnese cultivation zones offer untapped hesperidin feedstock for processors seeking origin diversification beyond Spain and Italy.
- Functional hydration formats:Ready-to-drink delivery systems targeting consumers aged 18-34 present whitespace distinct from capsule-saturated anti-aging segments.
- EU Green Deal farm-to-fork incentives:Carbon footprint certification subsidies reward Sicilian processors adopting renewable-powered extraction infrastructure.
Industry Challenges
- Phytochemistry talent scarcity:Formulation chemists with dual competency in flavonoid stability and cosmetic delivery systems command premiums that strain R&D budgets.
- Multi-jurisdiction label harmonization:Divergent EFSA, ANSM, and Swissmedic claim requirements force parallel packaging runs for cross-border distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mediterranean Citrus Nutricosmetic Complex Market |
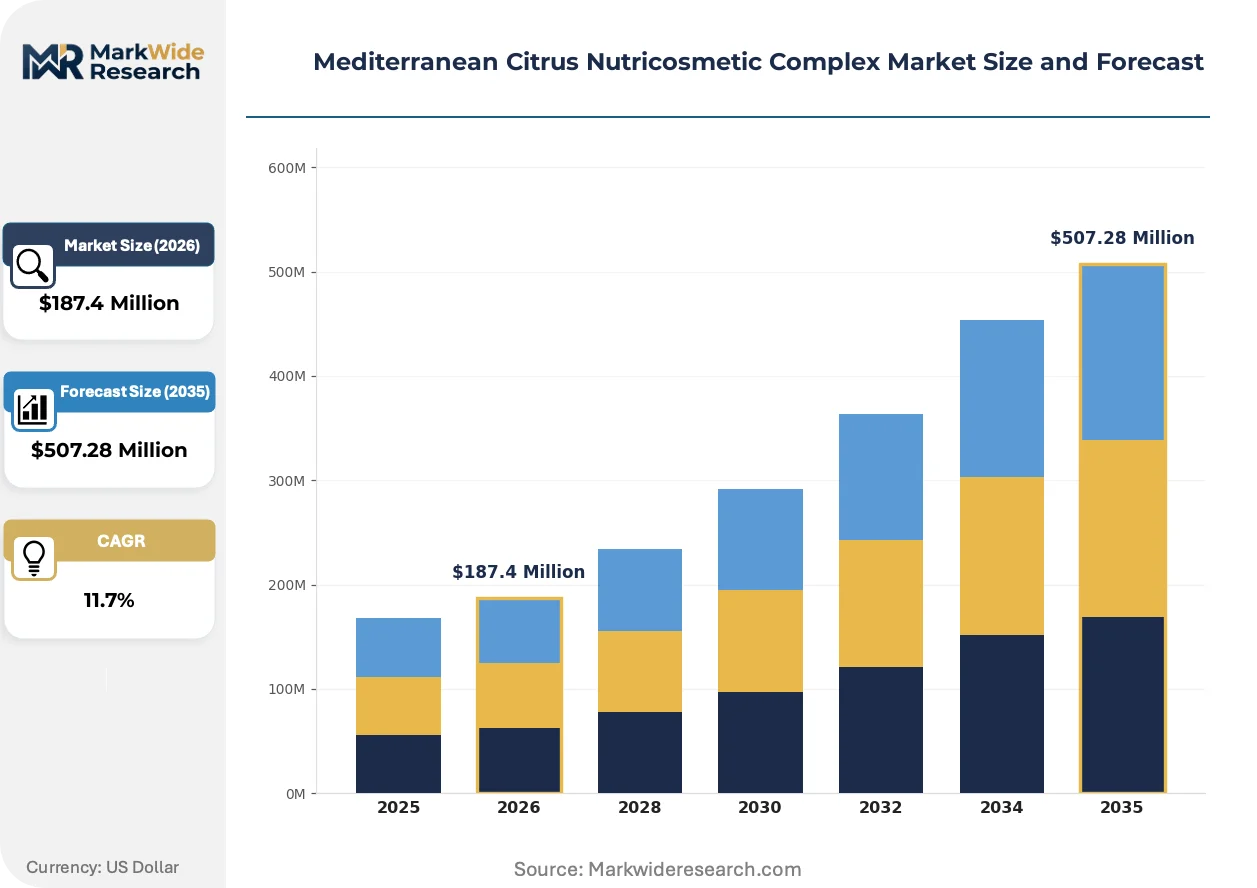
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Capsules, Powders, Beverages, Gels Active Ingredient: Flavonoids, Vitamin C, Essential Oils, Polyphenols, Bioflavonoids Application: Skin Brightening, Anti-Aging, Hair Strengthening, UV Protection, Immune Support End User: Beauty Salons, Wellness Centers, Spas, Dermatologists, Nutritional Clinics |
| Companies Covered | Monteloeder, Bionap, Euromed, Indena, dsm-firmenich, Givaudan, Nektium, Nexira, Sabinsa Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Citrus Nutricosmetic Complex Market Trends and Innovations
Extraction technology maturation and regulatory claim standardization are compressing the gap between commodity citrus processing and clinical-grade nutricosmetic supply. These forces reward capital-intensive operators while marginalizing artisanal extractors.
Supercritical CO2 extraction systems with integrated terpene recovery modules are absorbing market share from traditional cold-press operations. Spanish equipment fabricators report order backlogs from Sicilian processors seeking solvent-free certification for blood orange complexes. This technology shift is absorbing smaller extraction houses into toll-manufacturing relationships with larger Mediterranean compounders.
EU Green Deal farm-to-fork traceability mandates now require geolocation tagging for every citrus batch entering cosmetic supply chains. ECHA documentation portals enforce this through REACH registration updates that reject unverified origin claims. Southern Italian processors are responding by deploying blockchain-anchored harvest records that satisfy both EFSA auditors and French luxury brand procurement teams.
Professional channel buyers at dermatology clinics and medical spas are consolidating supplier relationships around single-source Mediterranean extractors with complete clinical dossiers. This procurement concentration displaces fragmented spot-buying from commodity brokers. The shift is most visible in Paris and Milan aesthetic medicine networks where treatment protocol liability demands documented bioactive standardization.
Mediterranean Citrus Nutricosmetic Complex Market Segmentation
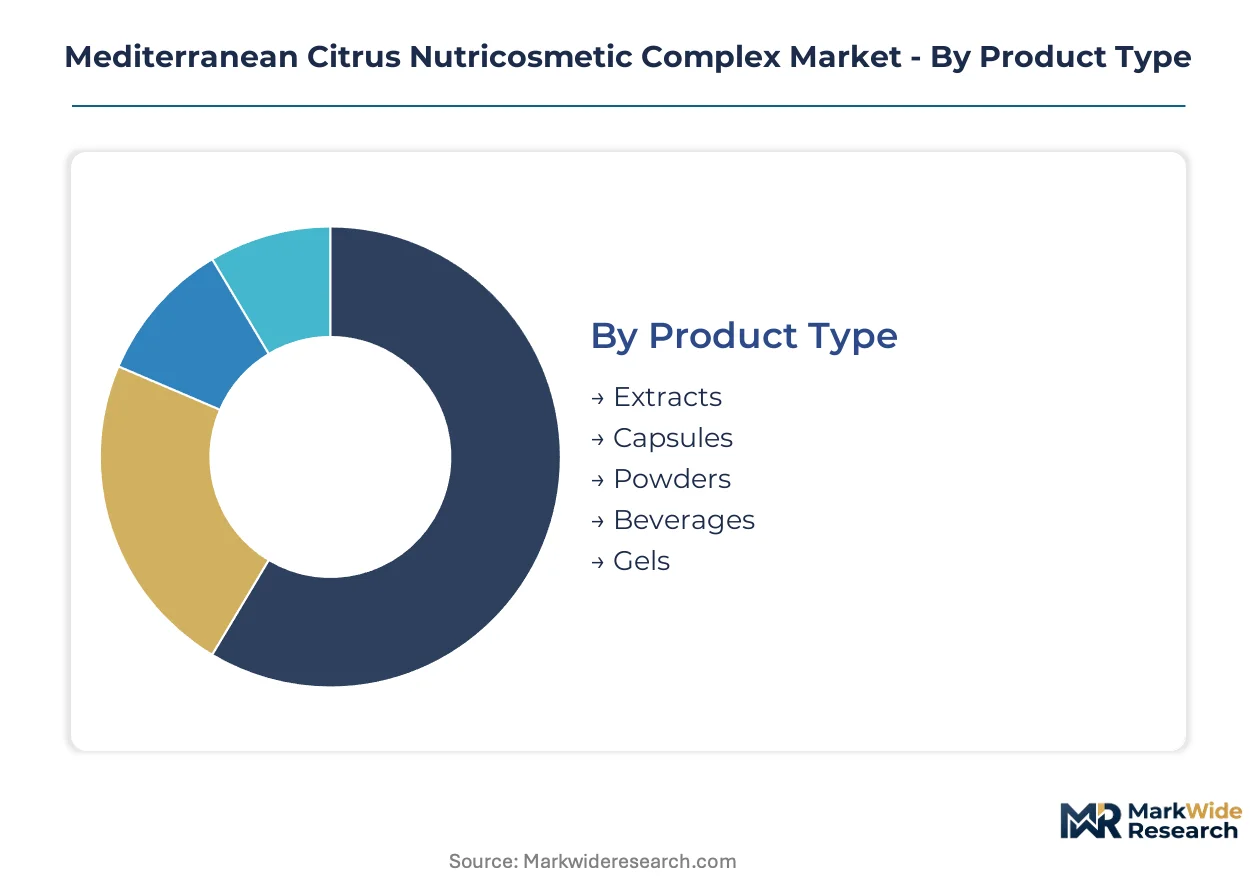
Mediterranean citrus extraction clusters concentrate capacity around specific delivery formats and bioactive specifications. Procurement patterns diverge sharply between clinical-grade service channels and direct-to-consumer retail, forcing suppliers to maintain parallel production certifications.
Product Type:
Valencia and Sicilian processing clusters anchor supply capacity around shelf-stable formats with documented cold-chain integrity.
- Extracts:Standardized liquid preparations containing specified polyphenol concentrations achieved through cold-press or supercritical CO2 methods. French dermocosmetic houses dominate procurement volumes, driven by REACH-compliant documentation requirements for cosmetic ingredient dossiers.
- Capsules:Hard-shell and soft-gel delivery systems offering dosage precision for professional protocol integration. Wellness centers across Barcelona and Milan standardize capsule-based ingestible beauty regimens, constrained by EFSA health claim authorization timelines.
- Powders:Spray-dried citrus bioactive complexes for formulation flexibility in topical preparations. Italian compounders serving cosmetic manufacturers represent the primary demand concentration.
- Beverages:Ready-to-drink functional hydration formats with specified flavonoid content per serving. Younger demographics aged 18-34 in urban Spanish markets drive trial adoption.
- Gels:Semi-solid topical delivery systems combining citrus bioactives with cosmetic base matrices. Regional spa chains incorporate these into treatment protocols for immediate skin application.
Extracts absorb the bulk of installed capacity; Beverages are expanding most quickly.
Active Ingredient:
Raw material sourcing geography dictates which bioactive classes achieve cost-competitive scale in Mediterranean supply chains.
- Flavonoids:Hesperidin and naringenin complexes extracted from blood orange and bitter orange cultivars. Valencia citrus belt frost exposure creates supply volatility that formulation houses hedge through Italian secondary sourcing.
- Vitamin C:Ascorbic acid and ascorbyl derivatives stabilized against oxidation for cosmetic compatibility. Spanish processors dominate through integrated cultivation-extraction operations.
- Essential Oils:Terpene-rich fractions recovered during supercritical CO2 extraction of bergamot and lemon peels. Fragrance-nutrition platforms bridge cosmetic and aromatherapy channels.
- Polyphenols:Broad-spectrum antioxidant complexes standardized for ORAC values. EFSA substantiation requirements constrain label claims to generic antioxidant descriptors.
- Bioflavonoids:Rutin and quercetin glycosides from citrus pith and peel byproducts. Peloponnese cultivation zones offer untapped feedstock for origin diversification.
Flavonoids command the steepest expansion trajectory; Polyphenols retain the broadest installed extraction capacity.
Application:
Margin pools concentrate where clinical substantiation thresholds separate premium positioning from commodity positioning.
- Skin Brightening:Melanin-modulation protocols targeting hyperpigmentation through tyrosinase inhibition. French aesthetic medicine networks demand batch-specific clinical dossiers.
- Anti-Aging:Collagen synthesis support and oxidative stress reduction claims. Dermatology clinics across Paris and Milan consolidate procurement around single-source extractors.
- Hair Strengthening:Keratin matrix support through bioavailable flavonoid delivery. Professional salon channels in Spain drive volume.
- UV Protection:Photodermatology claims requiring substantiation studies most Mediterranean suppliers cannot fund independently. Segment remains nascent pending clinical validation.
- Immune Support:Systemic antioxidant positioning bridging cosmetic and nutraceutical regulatory boundaries. EFSA health claim authorization determines permissible marketing architecture.
Anti-Aging absorbs the bulk of professional channel procurement; Skin Brightening is gaining share fastest.
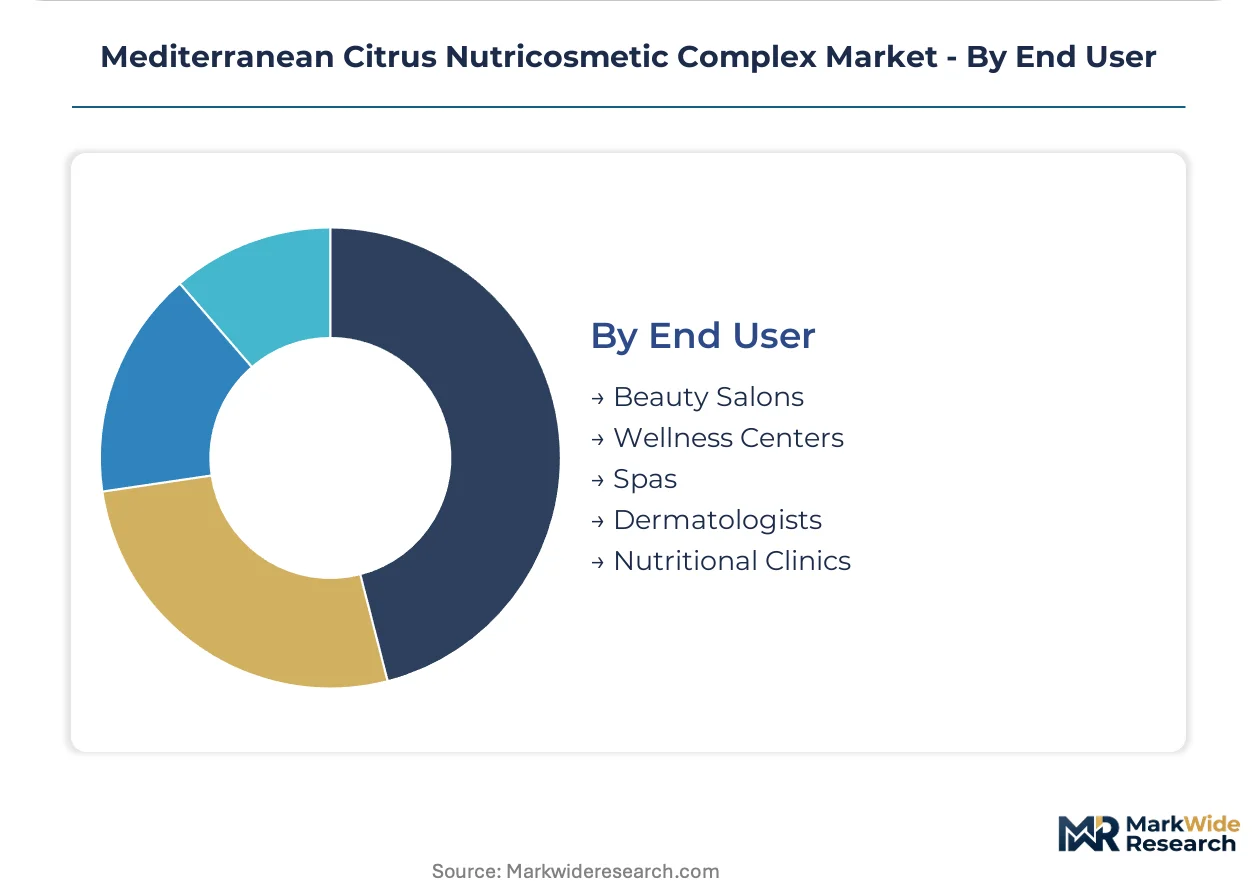
End User:
Channel consolidation around documented bioactive standardization favors established Mediterranean processors over commodity brokers.
- Beauty Salons:Retail-oriented service providers incorporating ingestible beauty as add-on protocols. Procurement remains fragmented across spot-buying relationships.
- Wellness Centers:Clinical-grade facilities standardizing Mediterranean citrus complexes into treatment menus. Barcelona and Milan networks drive demand concentration.
- Spas:Hospitality-integrated wellness operations seeking origin-story differentiation for premium positioning. Blockchain-anchored harvest records satisfy procurement requirements.
- Dermatologists:Medical aesthetic practitioners with liability exposure demanding complete clinical dossiers. Treatment protocol standardization displaces fragmented supplier relationships.
- Nutritional Clinics:Functional medicine practitioners bridging cosmetic and therapeutic applications. EFSA-compliant label claims determine product eligibility.
Dermatologists absorb the bulk of high-margin procurement; Wellness Centers are expanding protocol integration fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish extraction capacity outpaces domestic formulation demand, while French and Italian brands absorb the bulk of high-margin finished goods output. This production-consumption asymmetry funnels Valencia-derived bioactives northward through established supply corridors.
Spain
Valencia's citrus belt anchors supercritical CO2 extraction capacity serving French dermocosmetic houses. EU Green Deal farm-to-fork traceability mandates now require geolocation tagging for every batch entering cosmetic supply chains. Monteloeder leverages its Murcia heritage to dominate flavonoid supply contracts with Barcelona wellness center networks.
Italy
Sicilian blood orange cultivars feed controlled-sourcing agreements with premium skincare formulators in Milan and Paris. EMA cosmetic ingredient guidelines and REACH substance registration requirements compress supplier qualification timelines. Southern Italian equipment fabricators report order backlogs from processors seeking solvent-free certification.
France
Paris aesthetic medicine networks consolidate procurement around single-source Mediterranean extractors with complete clinical dossiers. ANSM claim requirements diverge from EFSA standards, forcing parallel packaging runs for cross-border distribution. Île-de-France formulation houses drive demand for documented bioactive standardization in anti-aging protocols.
Greece
Peloponnese cultivation zones offer untapped hesperidin feedstock for processors seeking origin diversification beyond Spain and Italy. EFSA health claim authorization processes determine permissible marketing architecture for polyphenol descriptors. Emerging extraction clusters near Patras are negotiating toll-manufacturing relationships with established Sicilian compounders.
Switzerland
Swissmedic claim requirements add a third regulatory layer to EFSA and ANSM compliance for cross-border nutricosmetic distribution. Geneva-based fragrance-nutrition platforms bridge cosmetic and nutraceutical channels through integrated bioactive-terpene portfolios. Zurich procurement offices source standardized citrus complexes for luxury brand R&D pipelines.
Mediterranean Citrus Nutricosmetic Complex Market Competitive Landscape
Top-tier vendors anchor clinical-grade supply, while mid-scale extractors compete on origin-story differentiation and toll-manufacturing relationships. Spanish and Italian clusters dominate capacity through cold-chain documentation advantages under REACH and EU Green Deal mandates. Three archetypes define competitive positioning: integrated cultivation-extraction operators, specialized flavonoid standardization houses, and fragrance-nutrition platform conglomerates. Capacity expansion and blockchain-anchored harvest documentation constitute the dominant competitive moves.
Within the integrated operator tier, Monteloeder and Euromed occupy positions that exemplify geographic specialization advantages—Spanish extraction heritage versus Italian controlled-sourcing from blood orange cultivars. dsm-firmenich represents the fragrance-nutrition platform archetype, bridging cosmetic and nutraceutical channels without vertical integration into raw cultivation. These three anchors demonstrate how regulatory documentation burdens and clinical substantiation thresholds favor established Mediterranean processors over new entrants lacking multi-year batch records.
| Leading Market Players |
|---|
| Monteloeder |
| Bionap |
| Euromed |
| Indena |
| dsm-firmenich |
| Givaudan |
| Nektium |
| Nexira |
| Sabinsa Corporation |
| Others |
Pricing and Supply Chain Analysis
French dermocosmetic procurement teams now mandate REACH-compliant batch documentation for every citrus bioactive shipment, forcing Valencia and Sicilian processors to absorb cold-chain verification costs or forfeit contract renewals. This specification tightening stratifies pricing around documentation depth rather than extraction yield alone.
Pricing Analysis
Short lead-time premiums of 15-20% apply to blood orange flavonoid orders placed within 45-day windows, while spot inventory from Valencia processors trades at discounts reflecting frost-exposure risk. Contract-based long-term offtake dominates procurement between Milan formulation houses and established Mediterranean extractors, with price differentiation hinging on EFSA health claim authorization status and blockchain-anchored harvest traceability. Pricing pressure stems from REACH registration cost burdens eroding margins for sub-tonnage Sicilian bergamot batches. Small-scale Peloponnese extractors exhibit highest price sensitivity, while Paris aesthetic medicine networks prioritize bioactive standardization over unit cost.
Supply Chain Analysis
Phytochemistry talent scarcity in Murcia and Catania manufacturing zones constrains supercritical CO2 equipment utilization rates below installed capacity. Raw material sourcing concentrates in Spain's Valencia citrus belt, Italy's Sicilian blood orange cultivars, and Greece's underutilized Peloponnese zones. Essential oil and terpene recovery modules draw from peel byproduct streams, while hesperidin feedstock rests on controlled cultivation agreements. Single-source vulnerability to Valencia frost events exposes formulation houses to supply interruptions without Italian secondary sourcing. Distribution runs through Barcelona and Milan wellness center networks for clinical-grade channels, with direct-to-retail absorption for capsule and beverage formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around documentation-capable processors as REACH deadlines and EU Green Deal traceability mandates eliminate artisanal extractors lacking multi-year batch records. Regulatory compliance burdens function as the primary pressure forcing weaker players toward toll-manufacturing absorption or exit.
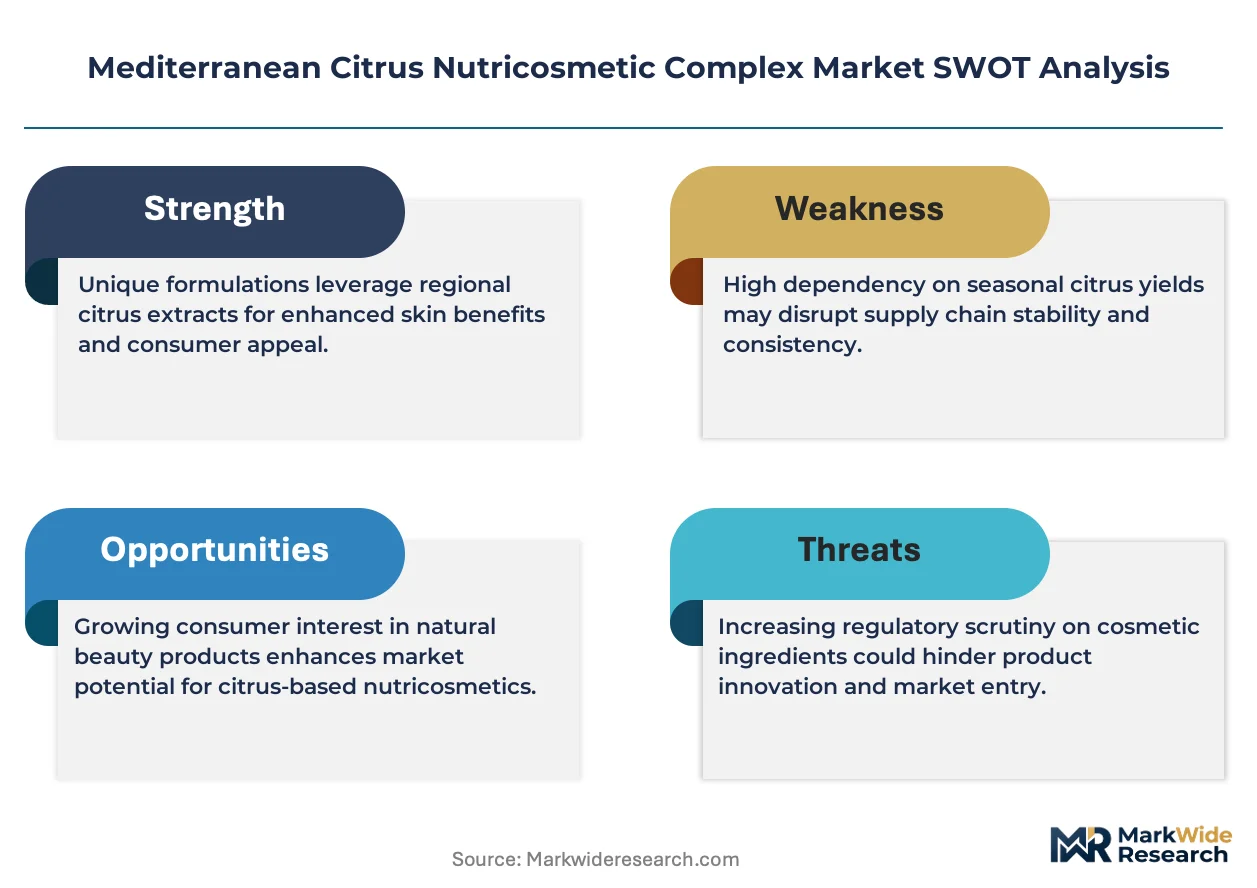
For Market Incumbents: To counter toll-manufacturing absorption by larger compounders, Monteloeder and Euromed should deepen backward integration into blockchain-anchored harvest verification and expand supercritical CO2 capacity in Murcia and Catania. Certification investment in EFSA-authorized polyphenol descriptors preserves premium positioning against commodity extraction rivals. For New Entrants and Emerging Players: Enter via functional hydration formats targeting Spanish urban consumers aged 18-34, where beverage segment penetration remains lowest among delivery systems. Peloponnese origin diversification offers geographic white-space distinct from saturated Valencia and Sicilian supply bases. Partnership with Milan dermocosmetic houses provides regulatory navigation expertise absent from Greek extraction heritage. For Investors and Strategic Acquirers: The window for entry favors integrated cultivation-extraction operators with complete clinical dossiers and existing REACH registrations. Long-term viability hinges on documented bioactive standardization capabilities rather than commodity extraction scale. Watch EFSA health claim authorization timelines for hesperidin complexes as the inflection signal determining which bioactive descriptors survive premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Anchored Harvest Documentation | EU Green Deal traceability mandates now require geolocation tagging for every Valencia and Sicilian batch entering cosmetic supply chains. |
| Supercritical CO2 Capacity Expansion | Southern Italian equipment fabricators report order backlogs from processors seeking solvent-free certification for blood orange complexes. |
| EFSA Health Claim Authorization Investment | Authorized polyphenol descriptors enable premium positioning for Valencia-derived hesperidin in French dermocosmetic channels. |
| Peloponnese Origin Diversification | Greek cultivation zones offer untapped hesperidin feedstock for processors reducing frost-exposure concentration in Valencia supply. |
| Clinical-Grade Service Protocol Integration | Barcelona and Milan wellness networks standardizing ingestible beauty as treatment modality pull Mediterranean citrus complexes into professional channels. |
Research Methodology
EMA cosmetic ingredient guidelines, REACH substance registration databases, and EU Green Deal farm-to-fork traceability protocols formed the secondary backbone for regulatory constraint mapping. Primary interviews with extraction plant managers at Valencia and Sicilian processing clusters, procurement leads at French dermocosmetic houses, wellness center protocol directors in Barcelona and Milan, and EFSA regulatory affairs specialists validated supply chain dynamics and claim authorization timelines. Bottom-up and top-down triangulation reconciled installed extraction capacity against formulation house demand projections.
Bottom-up modeling aggregated segment-level inputs across product type, active ingredient class, application, and end-user channel dimensions. The analytical framework weighted supercritical CO2 equipment utilization rates, EFSA health claim authorization progressions, and wellness center protocol adoption curves throughout the forecast period. CAGRs derived from compound growth logic applied to documented bioactive standardization premiums versus commodity extraction baselines. Frost-event probability distributions and REACH registration cost curves informed scenario branching.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA claim rejection scenarios or extended Valencia frost events. Forecasts reflect assumptions around regulatory timeline adherence and clinical substantiation funding availability. A small set of triggers—EFSA hesperidin descriptor rulings, REACH registration deadline extensions, and Peloponnese cultivation scale-up—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Protein Market
Nutritional Supplements
Organic Protein Powder Market
Nutritional Supplements
Dietary Supplement Cultures Market
Nutritional Supplements
Global Coq10 Supplement Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Middle East and Africa Feed Antioxidants Market
Nutritional Supplements
Europe Feed Prebiotics Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Dysphagia Supplements Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market