
 Sports Food Market | 2026-2036
Sports Food Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Food Market Outlook
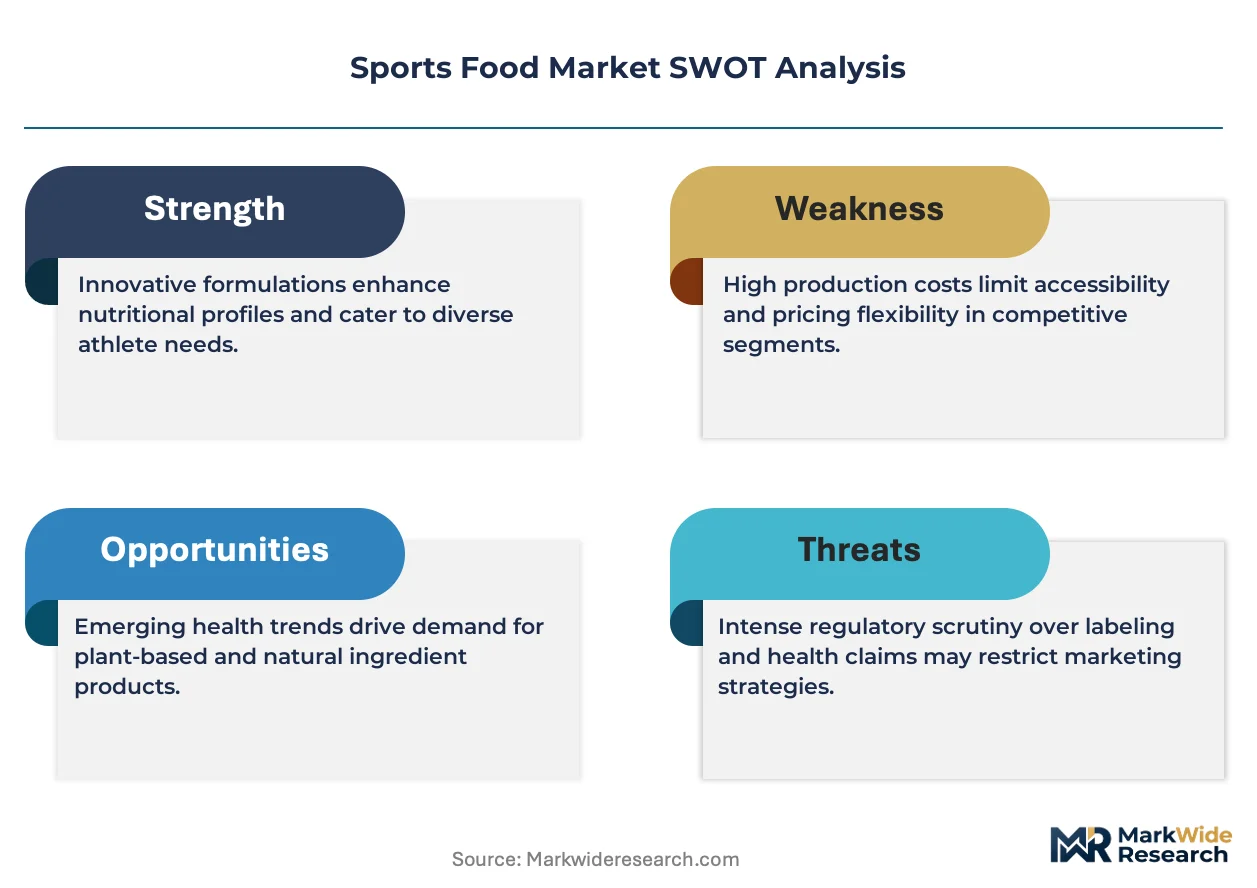
Premium protein formulations is reorganizing competitive dynamics in sports food. Glanbia plc leverages its dairy-derived ingredient dominance to anchor European supply chains. PepsiCo Inc. competes through beverage-to-food extension strategies that control shelf space in mass retail. Abbott Laboratories differentiates via clinical-grade nutritional science that sustains premium positioning in performance segments.
Sports food comprises engineered nutrition products formulated with specified macronutrient profiles, functional additives, and bioactive compounds designed to support athletic performance, recovery, and metabolic efficiency. Manufacturing employs cold-processing, microencapsulation, and spray-drying to preserve protein integrity and bioavailability. Protein bars occupy the largest margin pool due to convenience positioning and higher per-unit pricing, while electrolyte drinks lead volume through hydration occasion frequency across amateur and professional users. Energy gels represent the fastest-expanding category as endurance sports participation broadens the addressable base beyond traditional gym consumers.
FDA nutrition labeling requirements and EFSA health claims regulations constrain formulation messaging and substantiation standards across the United States and European markets. ISO 22000 and HACCP frameworks govern manufacturing quality, with national regulators in China and Japan imposing additional import testing protocols that shape market access timelines. Stakeholders must monitor evolving clean-label enforcement patterns and adaptive certification demands to secure positioning before regulatory divergence fragments compliance costs.
Market Dynamics
Clean-label enforcement under FDA and EFSA frameworks is compressing formulation timelines and forcing manufacturers to rebuild supply chains around unprocessed protein sources and natural stabilizers.
Growth Catalysts
- Endurance Sports Expansion:Marathon and triathlon participation in Germany and China is broadening the addressable consumer base beyond traditional gym users toward specialized fueling products.
- EFSA Health Claims Pathway:Validated performance claims under European regulations enable premium pricing for clinically substantiated recovery formulations targeting professional athletes.
- Microencapsulation Advancement:Cold-processing technologies preserve bioactive compound integrity during manufacturing, extending shelf stability without synthetic preservatives.
Market Restraints
- Whey Protein Concentration:Dairy-derived ingredient supply chains cluster in Ireland and New Zealand, exposing margins to weather-driven input volatility and trade policy shifts.
- Import Testing Protocols:China's SAMR and Japan's PMDA impose extended certification timelines that delay market entry for foreign formulated products by 8-14 months.
- Plant Protein Substitution:Pea and rice protein isolates achieve functional parity in lower-intensity applications, pressuring dairy-premium positioning in amateur segments.
Strategic Opportunities
- India Distribution Infrastructure:Underdeveloped organized retail in tier-2 cities creates first-mover advantage for direct-to-sports-club distribution models bypassing traditional grocery.
- ISO 22000 Certification Arbitrage:Manufacturers achieving integrated food safety management standards capture institutional procurement contracts from collegiate athletic programs and professional team nutritionists.
- Biometric Integration Convergence:Wearable glucose monitors and continuous metabolic sensors enable personalized gel formulations synced to real-time hydration and glycogen depletion data.
Industry Challenges
- Clean-Label Reformulation Talent:Scarcity of food scientists proficient in natural emulsifier substitution and pH-stable natural flavor systems extends R&D cycles.
- HACCP Documentation Burden:Small-batch craft protein bar manufacturers face disproportionate compliance costs relative to revenue when scaling beyond artisanal production volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Food Market |
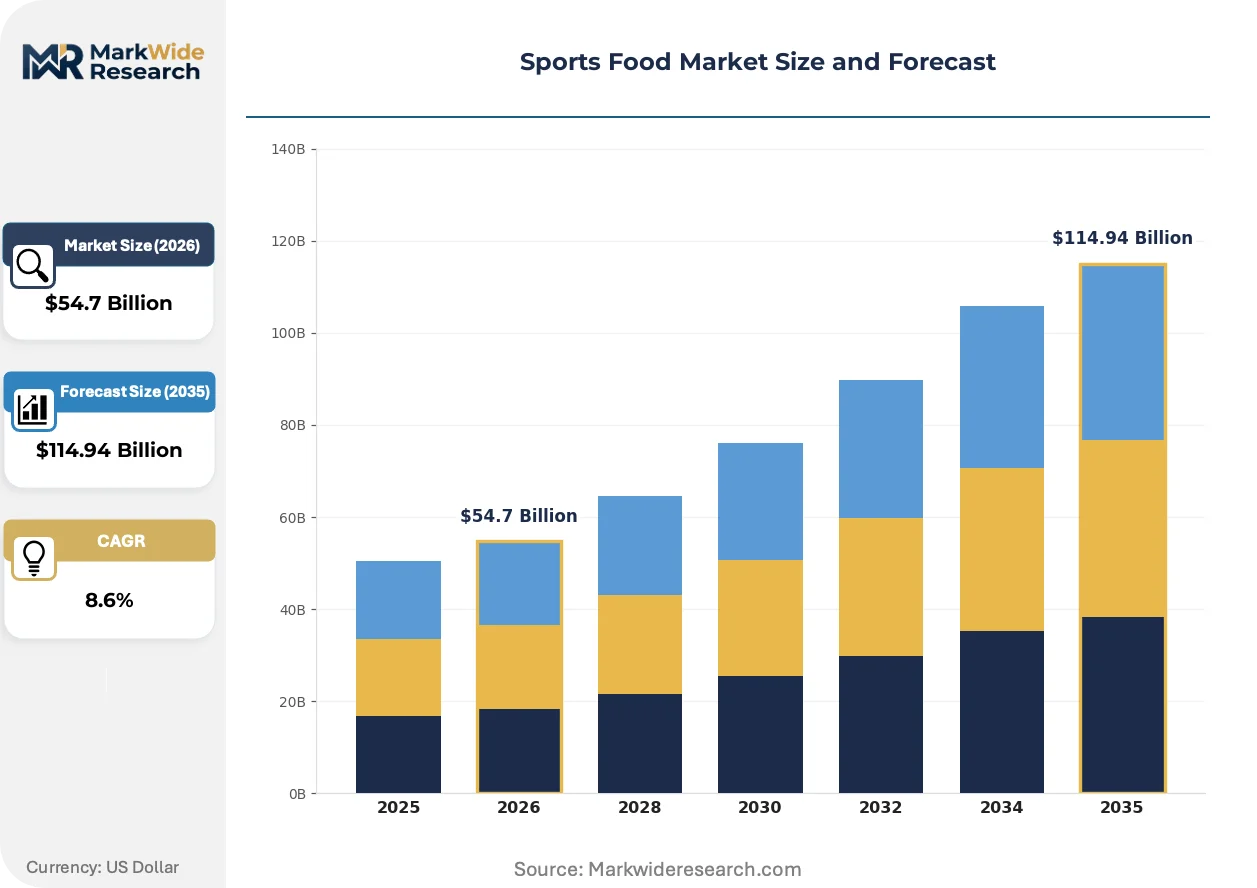
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $114.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Electrolyte Drinks, Energy Gels, Sports Supplements End User: Professional Athletes, Fitness Enthusiasts, Recreational Athletes, Coaches Application: Pre-Workout, Post-Workout, Hydration, Meal Replacement Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Gyms |
| Companies Covered | Glanbia plc, PepsiCo Inc., Abbott Laboratories, The Coca-Cola Company, Quest Nutrition, GNC Holdings Inc., Mondelez International Inc., Clif Bar & Company, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Food Market Strategic Shifts
Processing technology convergence with personalized nutrition platforms is collapsing the gap between mass-manufactured and bespoke performance fueling solutions.
Microencapsulation of bioactive peptides is miniaturizing delivery systems for branched-chain amino acids, enabling sub-gram precision dosing in pocket-sized gel formats. Elite endurance athletes in the United States and Australia are adopting these systems for stage-race carbohydrate periodization. The technology is miniaturizing portion control while preserving gastric tolerance during high-intensity exertion.
EFSA's evolving substantiation requirements for glycemic response claims are forcing manufacturers to commission clinical trials on proprietary carbohydrate blends. This regulatory tightening favors firms with captive research infrastructure over contract-manufactured competitors. Energy gel categories face the steepest compliance cost escalation as endurance positioning demands validated performance messaging.
Subscription-based replenishment models are displacing retail impulse purchases among committed amateur athletes. Direct-to-consumer platforms in Germany and the United Kingdom capture recurring revenue through algorithmic flavor rotation and training-load synced delivery scheduling. This channel shift concentrates customer data ownership with vertically integrated brands while eroding supermarket shelf-space economics for legacy entrants.
Sports Food Market Segmentation
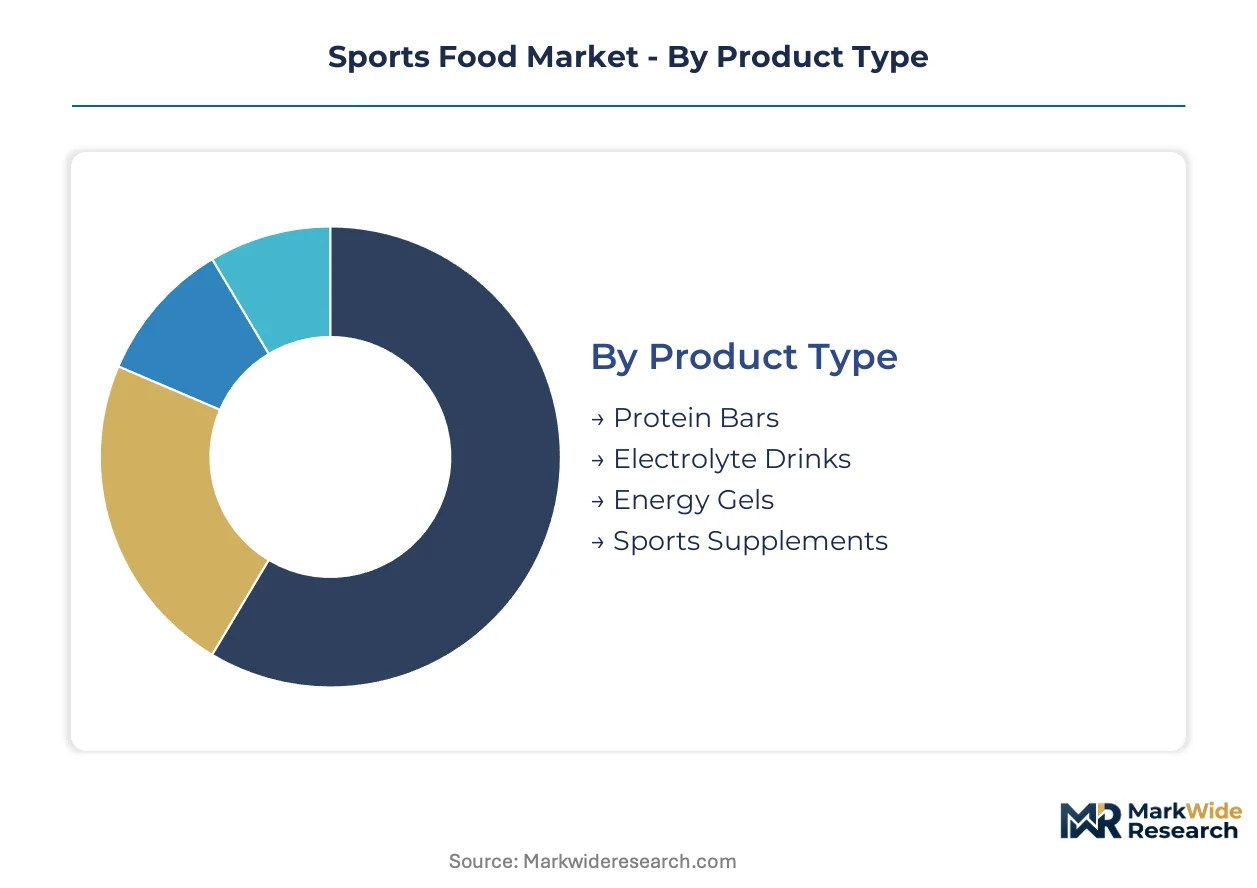
Sports food manufacturers calibrate formulation specifications, packaging formats, and channel economics against distinct usage occasions and buyer sophistication levels. Segmentation discipline separates volume-driven hydration products from margin-rich recovery formulations with divergent supply chain and certification requirements.
Product Type:
Protein bars and energy gels flow through divergent channel mixes—bars dominate supermarket impulse fixtures while gels concentrate in specialty running shops and direct-to-consumer endurance platforms. Electrolyte drinks split between mass retail hydration aisles and gym cooler placements.
- Protein Bars:Cold-processed whey and plant protein matrices deliver 15-25g protein per unit with microencapsulated vitamin fortification. Demand concentrates in the United States and Germany where gym membership penetration supports premium single-serve pricing and clean-label reformulation cycles.
- Energy Gels:Maltodextrin-fructose blends in 30-60g sachets enable rapid gastric emptying during sustained exertion above 75% VO2 max. Marathon and triathlon participation in China and Australia is driving specialized fueling adoption beyond traditional sports nutrition users.
- Electrolyte Drinks:Isotonic formulations with sodium, potassium, and magnesium target hydration occasion frequency across amateur and professional segments.
- Sports Supplements:Powdered creatine, branched-chain amino acids, and pre-workout stimulant blends serve committed training populations through specialty retail and subscription channels.
Protein bars dominate installed base. Energy gels are where expansion concentrates.
End User:
Cost tiers stratify sharply across user sophistication—professional athletes demand batch-tested certification while recreational buyers prioritize flavor novelty and convenience pricing.
- Professional Athletes:NSF Certified for Sport and Informed Sport testing protocols govern procurement decisions for Olympic and professional team nutritionists. Clinical-grade formulations from Abbott Laboratories and Glanbia plc sustain premium positioning through validated recovery claims under EFSA frameworks.
- Fitness Enthusiasts:Regular gym attendance drives subscription replenishment and flavor rotation through direct-to-consumer platforms in Germany and the United Kingdom.
- Recreational Athletes:Occasional marathon and cycling event participation supports impulse purchases at specialty retailers and event expositions.
- Coaches:Institutional procurement for collegiate and club programs emphasizes bulk pricing and ISO 22000 certification for liability protection.
Professional athletes anchor margin structure. Fitness enthusiasts concentrate volume growth.
Application:
Volume distribution varies by metabolic timing—pre-workout stimulant and hydration categories lead transaction frequency while post-workout recovery commands per-unit premium.
- Pre-Workout:Caffeine, beta-alanine, and citrulline formulations target acute performance enhancement with 30-45 minute onset windows. Demand clusters in the United States where gym culture supports stimulant-tolerant formulations with precise dosing transparency.
- Post-Workout:Rapid-absorption protein and carbohydrate matrices exploit the 30-60 minute glycogen resynthesis window after high-intensity training.
- Hydration:Electrolyte replacement during exertion spans endurance sports, team practices, and occupational heat exposure with broad demographic reach.
- Meal Replacement:Complete macronutrient profiles with micronutrient fortification serve time-constrained professionals and weight management protocols.
Hydration dominates transaction frequency. Post-workout recovery concentrates margin expansion.
Distribution Channel:
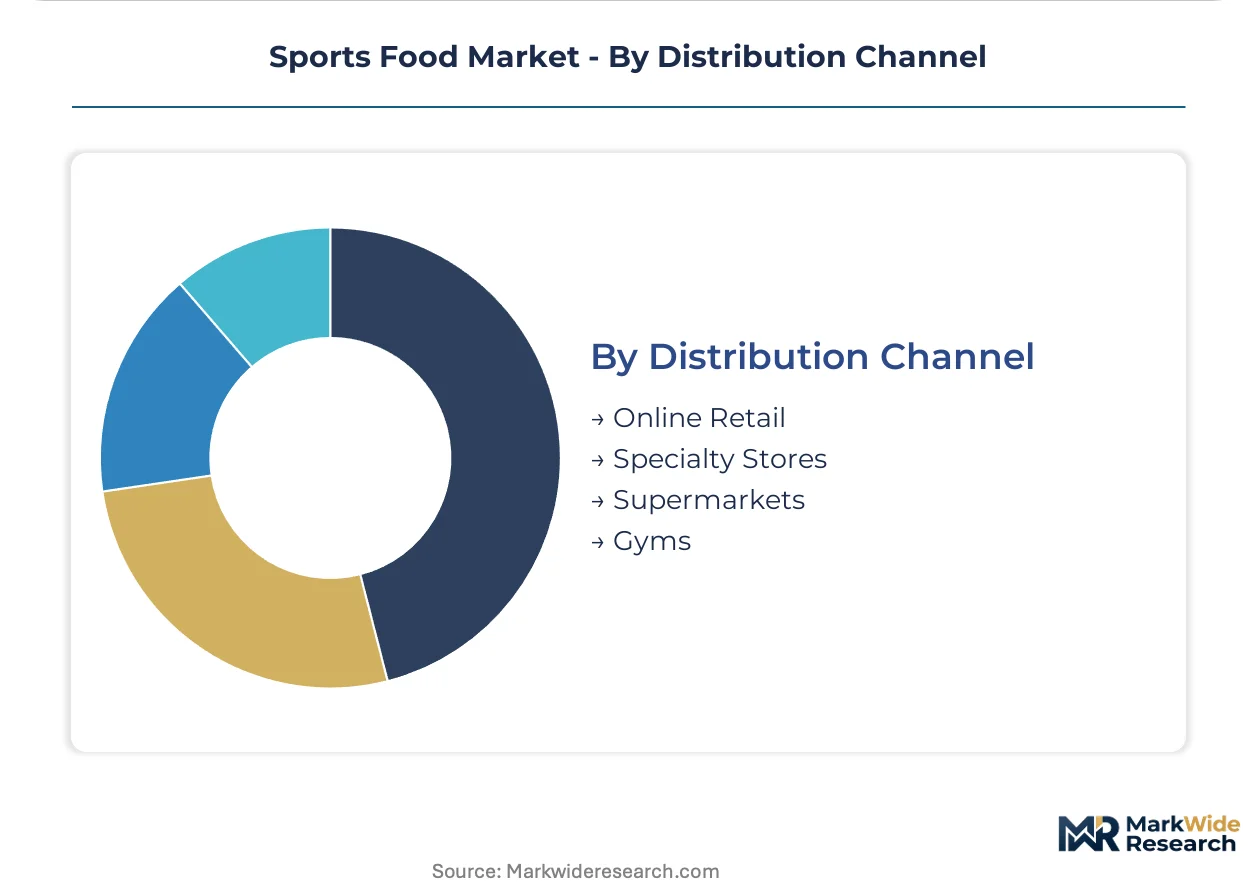
Customer data ownership is shifting from retail intermediaries to vertically integrated brands as subscription models displace impulse purchasing.
- Online Retail:Algorithmic flavor rotation and training-load synced delivery scheduling capture recurring revenue and first-party data. Direct-to-consumer platforms in Germany and the United Kingdom bypass supermarket slotting fees while enabling personalized formulation recommendations.
- Specialty Stores:Running shops and cycling retailers provide educated staff consultation for gel selection and hydration strategy during endurance event preparation.
- Supermarkets:Protein bar placement in checkout aisles and health food sections depends on slotting fee negotiations and velocity-based replenishment algorithms.
- Gyms:Cooler placement and front-desk merchandising exploit immediate post-workout consumption occasions with minimal price sensitivity.
Online retail is gaining share fastest. Gyms sustain highest per-visit conversion rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Amateur athletes in Germany and the United States absorb premium pricing for clean-label certification. Recreational buyers in China and India prioritize unit economics over formulation sophistication.
United States
Marathon participation exceeding 500,000 annual finishers drives gel and electrolyte volume. FDA nutrition labeling requirements constrain health claim messaging for recovery products. Manufacturing clusters in Colorado and Utah specialize in cold-processed protein bar production for boutique and mass-market brands.
Germany
Triathlon federation membership surpasses 250,000 athletes demanding stage-race fueling protocols. EFSA health claims substantiation requirements favor firms with captive clinical research infrastructure. Bavarian dairy processing corridors supply whey protein isolates to European formulation facilities.
China
Fitness club membership growth in tier-1 cities expands addressable base beyond traditional sports nutrition users. SAMR import testing protocols extend foreign product certification timelines by 8-14 months. Shanghai and Shenzhen manufacturing zones develop domestic protein bar capacity to bypass regulatory delays.
Japan
Aging recreational athletes prioritize low-osmolality hydration formulations for gastric tolerance. PMDA novel food ingredient approvals govern probiotic and peptide additive market entry. Osaka-based ingredient suppliers specialize in microencapsulation technologies for amino acid delivery systems.
Australia
Ironman event participation per capita leads global endurance sports engagement. TGA therapeutic goods classifications distinguish sports foods from regulated supplements. Melbourne and Sydney formulation labs serve Asia-Pacific export markets with batch-tested certification protocols.
Sports Food Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Dairy-derived ingredient specialists command premium positioning through bioavailability science. Beverage conglomerates leverage distribution density for mass-market hydration products. Clinical nutrition firms anchor professional athlete segments with certified testing protocols. Consolidation pressure favors M&A activity among mid-cap protein bar specialists and capacity expansion in Asian contract manufacturing.
Within the dairy-derived ingredient tier, Glanbia plc and Abbott Laboratories exemplify divergent strategic positions. Glanbia anchors European supply chains through Irish processing infrastructure. Abbott occupies clinical-grade positioning validated under EFSA frameworks. PepsiCo sits within the mass-market vector, extending beverage distribution into food adjacent categories.
| Leading Market Players |
|---|
| Glanbia plc |
| PepsiCo Inc. |
| Abbott Laboratories |
| The Coca-Cola Company |
| Quest Nutrition |
| GNC Holdings Inc. |
| Mondelez International Inc. |
| Clif Bar & Company |
| Nestlé S.A. |
| Others |
Value Chain & Pricing Dynamics
Plant protein substitution for dairy-derived isolates simultaneously redistributes sourcing geography toward Canadian and Ukrainian pea processing corridors while compressing premium pricing power in amateur-tier formulations. This input shift forces manufacturers to rebuild cost models around agricultural commodity cycles rather than dairy cooperative pricing structures.
Pricing Analysis
Subscription replenishment revenue drives lifetime value as direct-to-consumer platforms capture recurring commitment from fitness enthusiasts. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport formulations from conventional clean-label and private-label alternatives. Price differentiation centers on certification grade and batch-testing documentation. Pricing pressure stems from plant protein functional parity in lower-intensity applications. Recreational athletes exhibit highest price sensitivity; professional team nutritionists show minimal elasticity for validated recovery claims.
Supply Chain Analysis
Irish Sea port congestion periodically chokes whey protein isolate flows from Glanbia's processing infrastructure to European formulation facilities. Geographic supply concentration clusters in Ireland, New Zealand, and the Netherlands for dairy-derived inputs. Raw material dependencies center on whey isolates, maltodextrin blends, and natural emulsifier systems. Supply chain risk rests on weather-driven dairy output volatility and trade policy shifts. Distribution runs through hybrid direct-to-consumer platforms, specialty running retailers, and mass-market supermarket fixtures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation science proficiency gaps constrain clean-label reformulation velocity as manufacturers compete for food scientists skilled in natural stabilizer substitution. This capability scarcity extends R&D timelines and elevates compensation costs for technical talent.
For Market Incumbents: Shield premium positioning through captive clinical research infrastructure that accelerates EFSA health claims substantiation. Deepen backward integration into microencapsulation technology to preserve bioactive compound integrity without synthetic preservatives. Expand ISO 22000 certification coverage to capture institutional procurement contracts from collegiate athletic programs.
For New Entrants and Emerging Players: Anchor in India's tier-2 city sports club distribution networks where organized retail underdevelopment creates first-mover whitespace. Target direct-to-consumer gel formulations synced to wearable biometric data as the most penetrable application. Pursue algorithmic flavor rotation and training-load synced delivery scheduling as the primary go-to-market angle.
For Investors and Strategic Acquirers: EFSA's evolving glycemic response substantiation requirements reshape the acquisition landscape toward firms with integrated clinical trial capabilities. Long-term viability favors vertically integrated brands owning customer data through subscription platforms over retail-dependent legacy entrants. Target mid-cap protein bar specialists with established clean-label supply chains. Watch SAMR import testing protocol harmonization as the signal for foreign formulation market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Natural emulsifier substitution capabilities satisfy FDA and EFSA enforcement patterns. |
| Direct-to-Consumer Platform Launch | Algorithmic replenishment captures recurring revenue from German fitness enthusiasts. |
| ISO 22000 Certification Expansion | Integrated food safety standards unlock collegiate athletic program procurement contracts. |
| Biometric Data Integration Partnership | Wearable glucose monitor connectivity enables personalized gel formulation dosing. |
| Domestic Manufacturing Capacity Buildout | Shanghai and Shenzhen facilities bypass SAMR import certification delays. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with sports nutrition formulators, regulatory affairs specialists, collegiate athletic program nutritionists, and direct-to-consumer platform operators; and secondary validation through FDA nutrition labeling guidance, EFSA health claims registers, SAMR import protocol documentation, and customs trade flow records. Bottom-up product-level volume estimates triangulated against top-down category expenditure benchmarks.
Across the projection horizon, the analytical framework modeled segmentation across product type, end user sophistication tier, metabolic timing application, and distribution channel structure. CAGRs derived from fitted growth curves applied to baseline penetration rates and occasion frequency assumptions. Industry-specific forecast inputs included marathon and triathlon participation trajectories, gym membership density correlations, and clean-label enforcement pattern evolution.
Material uncertainties — regulatory divergence between FDA and EFSA frameworks, weather-driven dairy commodity volatility, and SAMR protocol harmonization timing — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as endurance sports participation rates and biometric integration adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Calcium Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Australia Whey Protein Market
Nutritional Supplements
GLP-1 Diet Food Market
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Fat Powders Market
Nutritional Supplements
South Africa Nutraceuticals Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Europe Beta-Glucan Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Bovine Lactoferrin Market
Nutritional Supplements
North America Dietary Supplements Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Global Egg Protein Powder Market