
 Tile Saw Market | 2026-2036
Tile Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Tile Saw Market Analysis
Commercial flooring contractors is rotating toward higher-capacity wet tile saws as large-format porcelain gains share in retail and hospitality builds. Bosch leverages in-house diamond blade production to control input costs across European supply chains. MK Diamond specializes in bridge saw configurations for stone fabrication shops in North America. Husqvarna anchors its position through rental channel partnerships that reach mid-sized contractors without direct capital expenditure.
A tile saw is a power tool designed to cut ceramic, porcelain, natural stone, and glass tiles using diamond-edged blades with water cooling to suppress dust and prevent thermal fracture of brittle materials. Wet tile saws dominate commercial settings where precision and continuous duty cycles matter, while portable tile saws capture renovation and residential repair work where site mobility determines purchase decisions. Diamond blade technology leads equipment margins due to consumable replacement cycles, whereas laser cut guidance systems represent the fastest-growing attachment category as accuracy specifications tighten in premium installation segments.
OSHA silica exposure limits and EPA National Emission Standards for Hazardous Air Pollutants shape dust suppression requirements, pushing dry saw designs toward integrated vacuum systems or toward wet conversion. CE marking under EU machinery directives enforces blade guard and emergency stop standards that add engineering cost but block non-compliant imports. Stakeholders must monitor how tightening silica regulations in multiple jurisdictions affect the cost structure and competitive viability of dry versus wet platform strategies.
Market Dynamics
Water cooling system redesigns under EPA National Emission Standards for Hazardous Air Pollutants and EU industrial emissions frameworks are compressing equipment margins while forcing closed-loop engineering investments across manufacturing footprints.
Growth Catalysts
- Large-format tile specification:Architects in retail and hospitality projects specify porcelain slabs exceeding 48 inches, requiring wet saws with extended bridge capacities and precision water delivery systems.
- OSHA silica exposure limits:The permissible exposure limit reduction for respirable crystalline silica is accelerating wet saw adoption in commercial flooring contractor fleets nationwide.
- Housing stock aging:Residential renovation contractors across Germany and the United States are replacing equipment as post-war housing enters major refurbishment cycles.
Market Restraints
- Diamond blade input cost volatility:Synthetic diamond prices fluctuate with industrial demand from semiconductor wafer cutting, compressing aftermarket margin stability for consumable suppliers.
- Supply concentration in Guangdong:Motor and pump subassembly production clusters in southern China create single-source vulnerability for European and North American OEMs.
- Dry saw substitution ceiling:Integrated vacuum dry systems face fundamental dust capture physics limits that prevent full functional parity with wet cutting in continuous duty environments.
Strategic Opportunities
- India commercial construction acceleration:Metro rail station fit-outs and airport terminal expansions are creating first-time demand for bridge saw configurations in a market historically served by manual cutters.
- EU Green Deal machinery retrofit incentives:Member state recovery funds are subsidizing water recycling system upgrades for fabrication shops seeking CE marking compliance with tightened effluent standards.
- Rental channel penetration:Equipment-as-a-service models targeting mid-sized contractors without direct capital expenditure capacity are expanding addressable wallet share in secondary metropolitan markets.
Industry Challenges
- Skilled wet saw operator shortage:Precision cutting certification programs lag demand in Texas, Florida, and California construction labor markets, extending project timelines for specialized tile installation.
- Closed-loop system integration complexity:Retrofitting legacy fabrication shops with recirculating water infrastructure requires floor space reconfiguration and electrical load upgrades that delay ROI realization.
- Multi-jurisdiction certification timelines:Simultaneous EPA, OSHA, and CE marking approval processes extend product launch windows by 8-14 months for redesigned platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tile Saw Market |
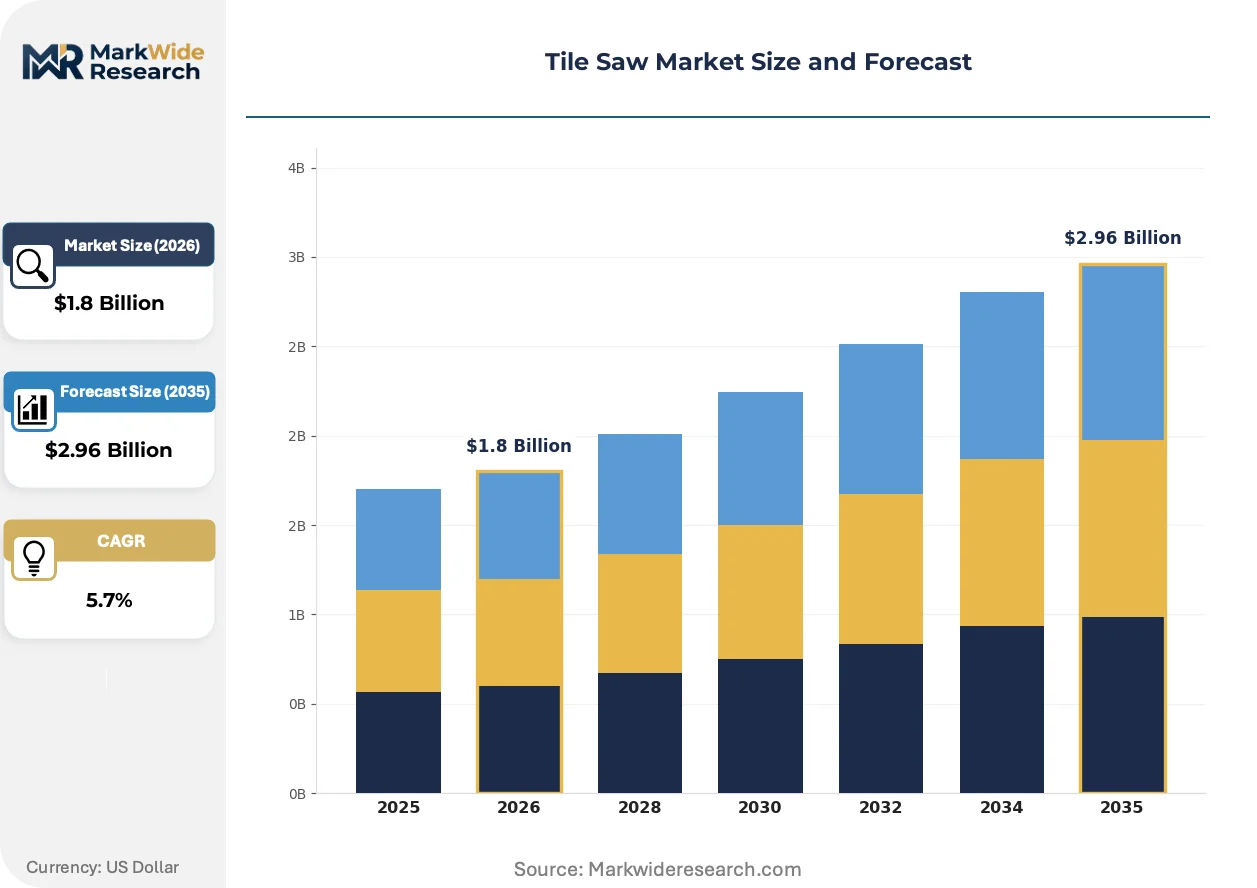
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Tile Saws, Dry Tile Saws, Bridge Saws, Portable Tile Saws Technology: Diamond Blade, Laser Cut, Abrasive Blade, Water Cooling End User: Contractors, DIY Enthusiasts, Construction Firms, Retailers Application: Flooring, Wall Tiles, Stone Cutting, Ceramics |
| Companies Covered | Stanley Black & Decker, Bosch, Makita, Husqvarna, MK Diamond, DeWalt, RIDGID, SKIL, QEP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tile Saw Market Emerging Trajectories
Laser-guided positioning systems and compact wet saw architectures are compressing the boundary between professional and advanced DIY equipment categories. These shifts are redrawing channel relationships and service expectations.
Portable wet tile saw platforms with integrated water containment tanks are miniaturizing to under-15-pound configurations without sacrificing blade diameter or cutting depth. Residential renovation contractors and high-end DIY buyers are adopting these units for bathroom and kitchen refresh projects where site access constraints previously favored manual score-and-snap methods. This miniaturization is collapsing the traditional equipment tier boundary between jobsite-grade and homeowner-grade product lines, forcing distributors to consolidate SKU portfolios.
EPA National Emission Standards for Hazardous Air Pollutants enforcement actions against dry cutting operations are accelerating wet conversion mandates in commercial stone fabrication. Fabrication shops in California, Texas, and New York face inspection priority status, driving capital allocation toward closed-loop wet systems with documented water quality monitoring. The regulatory pressure is most acute in countertop production segments where silica-generating operations concentrate.
Floor-and-decor retailers are unbundling after-sales blade sharpening and alignment services from equipment purchases, shifting toward transactional product-only transactions. Commercial flooring contractors accustomed to bundled service agreements must now source maintenance through independent sharpening shops or invest in in-house grinding equipment. This behavioral shift is most visible in United States suburban markets where big-box home improvement chains dominate contractor supply relationships.
Tile Saw Market Segmentation
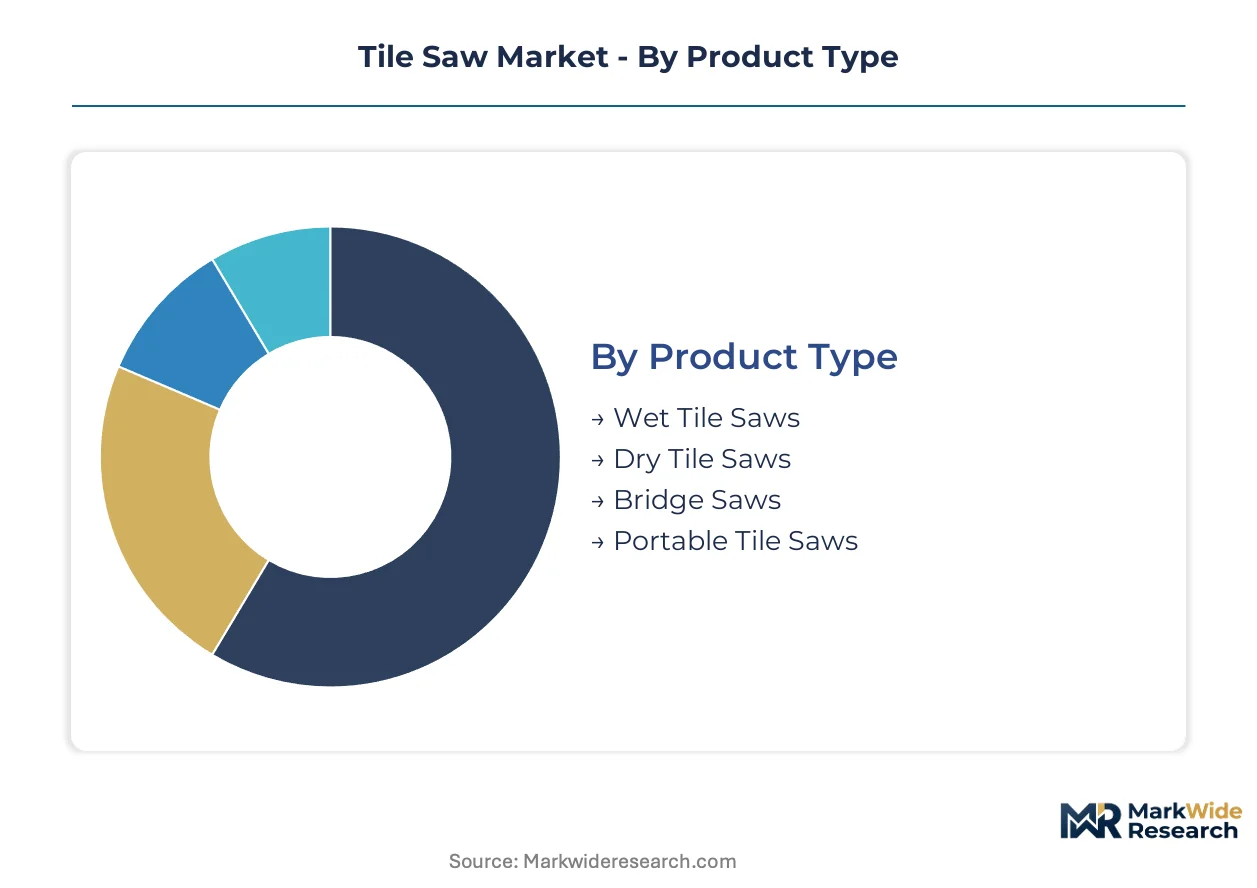
Equipment specification in the tile saw market diverges sharply between commercial fabrication and residential renovation channels. Segmentation reveals how regulatory pressure and application requirements fragment purchasing behavior across wet, dry, and portable platforms.
Product Type:
Wet tile saws concentrate in domestic fabrication markets where OSHA silica enforcement drives fleet conversion. Bridge saws and portable units show stronger export orientation toward emerging construction economies.
- Wet Tile Saws:Closed-loop water cooling systems suppress respirable silica at the point of cut. Demand clusters in California, Texas, and New York fabrication shops facing EPA National Emission Standards for Hazardous Air Pollutants inspection priority.
- Dry Tile Saws:Integrated vacuum extraction attempts dust capture without water infrastructure. Adoption hits a functional ceiling in continuous-duty stone fabrication where physics limits prevent full parity with wet cutting performance.
- Bridge Saws:Extended rail configurations handle porcelain slabs exceeding 48 inches. German and Italian OEMs dominate export supply to Indian metro rail and airport terminal projects.
- Portable Tile Saws:Miniaturized wet platforms under 15 pounds collapse the boundary between jobsite-grade and homeowner-grade equipment. Residential renovation contractors in Florida and Arizona adopt these for bathroom refresh work with site access constraints.
Wet tile saws command the established base. The steepest expansion runs through portable wet configurations.
Technology:
Technology tiers separate by consumable replacement economics versus precision guidance capabilities. Diamond and abrasive blades generate recurring revenue. Laser systems command premium positioning.
- Diamond Blade:Synthetic diamond cutting edges deliver thermal management and extended service life in porcelain and natural stone applications. Bosch leverages in-house production to control input costs across European supply chains.
- Laser Cut:Guided positioning systems enable sub-millimeter accuracy for large-format tile layout. Retail and hospitality architects in Germany and the United States specify laser-equipped units for premium installation segments.
- Abrasive Blade:Lower first-cost consumables target ceramic and soft stone cutting in price-sensitive renovation markets.
- Water Cooling:Recirculating pump and filtration subassemblies enable closed-loop compliance with EU industrial emissions frameworks and EPA effluent standards.
Diamond blade technology anchors equipment margin stability. Laser guidance systems gain share fastest in specification-driven commercial flooring.
End User:
Customer segmentation tracks capital intensity and service bundling expectations. Professional contractors demand durability certification. DIY buyers prioritize portability and retail availability.
- Contractors:Commercial flooring fleets specify wet saw platforms with documented silica exposure compliance. Rental channel partnerships reach mid-sized operators without direct capital expenditure capacity.
- DIY Enthusiasts:Advanced homeowners drive portable wet saw miniaturization. Floor-and-decor retailers unbundle after-sales service, shifting these buyers toward transactional product-only purchases.
- Construction Firms:Large-format porcelain specification in retail and hospitality builds drives bridge saw procurement for new construction projects.
- Retailers:Big-box home improvement chains consolidate SKU portfolios as equipment tiers collapse, favoring multi-purpose platforms with broad appeal.
Contractors represent the revenue foundation. DIY enthusiasts expand the addressable wallet through equipment democratization.
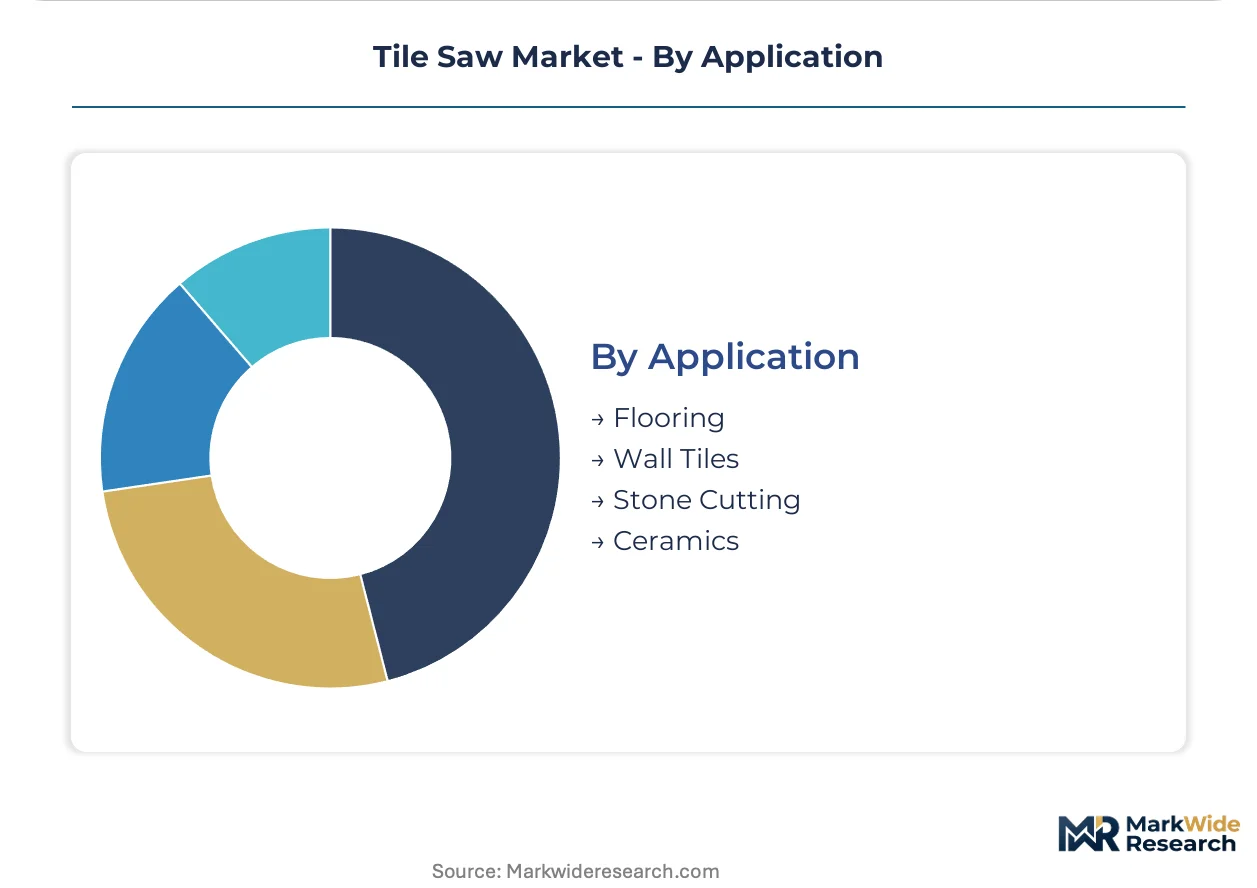
Application:
Application requirements dictate blade specification, water delivery capacity, and precision tolerances. Flooring and stone cutting demand continuous-duty engineering. Wall tile work permits lighter platforms.
- Flooring:Large-format porcelain slab installation requires extended bridge capacities and precision water delivery. German and United States housing stock aging drives replacement cycles in residential renovation.
- Wall Tiles:Vertical cutting applications favor lighter portable configurations with integrated water containment. Bathroom and kitchen refresh projects in suburban United States markets concentrate demand.
- Stone Cutting:Granite and quartz countertop fabrication generates the highest silica exposure, triggering wet conversion mandates under OSHA enforcement.
- Ceramics:Standard ceramic tile cutting permits abrasive blade economics in price-sensitive developing markets.
Flooring applications anchor equipment specification. Stone cutting faces the steepest regulatory-driven technology transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for wet saw imports serving fabrication shops across the continent. Rail links from Guangdong Province feed motor and pump subassemblies through this corridor. United States demand flows through Long Beach and Savannah ports where customs processing prioritizes EPA-compliant equipment.
United States
California fabrication shops face EPA National Emission Standards for Hazardous Air Pollutants inspection priority, driving wet conversion mandates in countertop production. OSHA silica exposure limit enforcement accelerates fleet replacement in Texas and Florida construction labor markets. Los Angeles and Dallas-Fort Worth metro areas concentrate stone fabrication capacity where closed-loop water recycling investments dominate capital allocation.
Germany
Post-war housing stock aging triggers residential renovation contractor equipment purchases across Bavaria and North Rhine-Westphalia. EU Green Deal machinery retrofit incentives subsidize water recycling system upgrades for fabrication shops seeking CE marking compliance. Stuttgart and Munich industrial clusters anchor bridge saw manufacturing for export to Indian infrastructure projects.
China
Guangdong Province motor and pump subassembly production creates supply concentration for European and North American OEMs. MEE industrial emissions frameworks push domestic manufacturers toward closed-loop system redesigns. Shanghai and Beijing construction markets absorb large-format porcelain slab installation equipment for retail and hospitality builds.
India
Metro rail station fit-outs and airport terminal expansions generate first-time demand for bridge saw configurations in Delhi-Mumbai corridors. BIS machinery safety standards enforce blade guard and emergency stop requirements that block non-compliant imports. Gujarat and Maharashtra fabrication clusters adopt wet cutting platforms as commercial construction acceleration outpaces manual cutter capacity.
Tile Saw Market Vendor Landscape
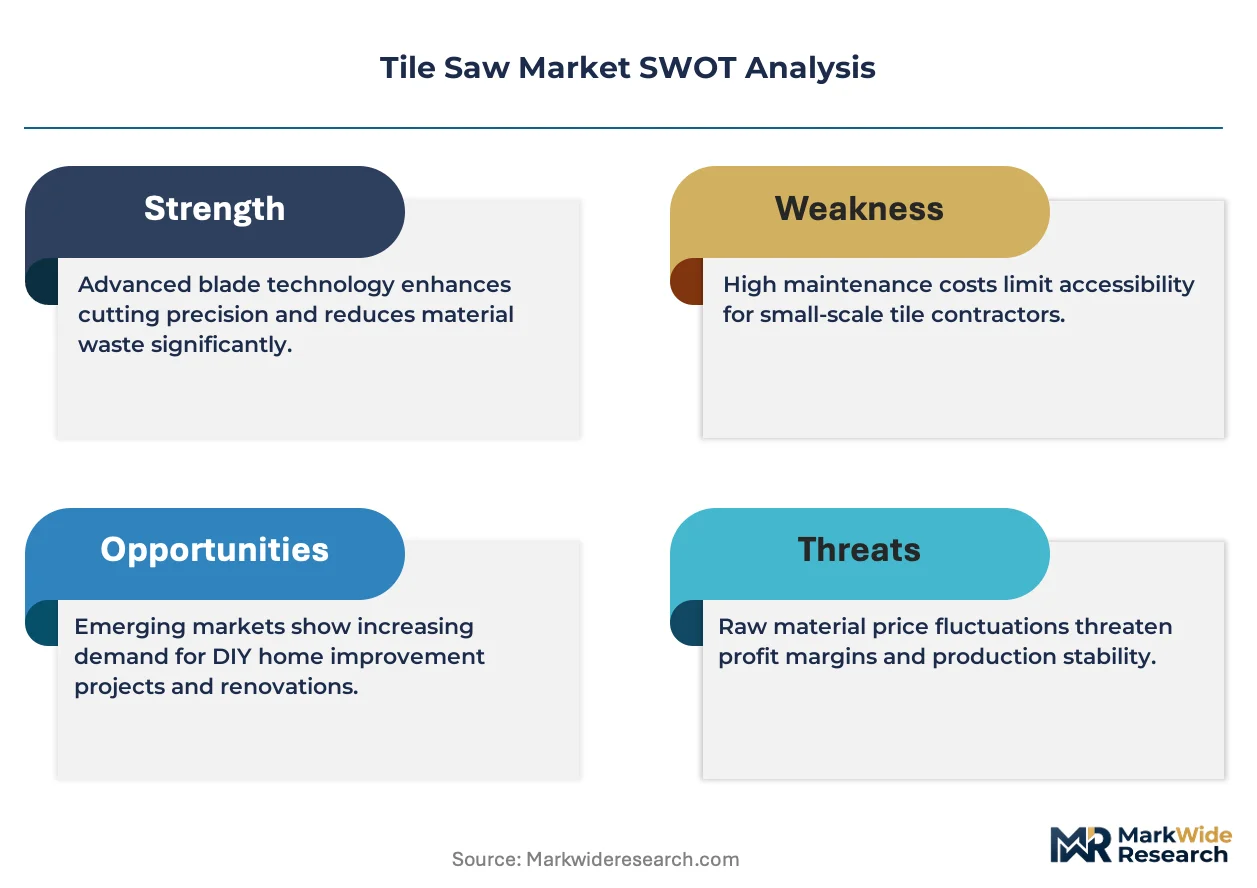
Listed leaders compete with private specialists across capital intensity and channel reach dimensions. The vendor base separates into three tiers: diversified power tool conglomerates, diamond blade specialists, and rental channel partners. Strategic archetypes include integrated blade manufacturers controlling input costs, bridge saw configurators serving stone fabrication, and equipment-as-a-service providers reaching mid-sized contractors. M&A activity concentrates on water cooling technology acquisitions while geographic expansion targets Indian commercial construction acceleration.
Among diversified power tool conglomerates, Stanley Black & Decker and Bosch occupy positions spanning residential and commercial segments. Makita represents Japanese precision engineering archetypes in portable wet platform development. Husqvarna anchors rental channel penetration strategies reaching contractors without direct capital expenditure capacity. MK Diamond exemplifies North American specialists in bridge saw configurations for stone fabrication shops. These five entities represent the competitive core, with DeWalt, RIDGID, SKIL, and QEP sitting within adjacent power tool and specialty equipment tiers.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Bosch |
| Makita |
| Husqvarna |
| MK Diamond |
| DeWalt |
| RIDGID |
| SKIL |
| QEP |
| Others |
Supply Flow & Price Mechanics
CE marking under EU machinery directives gates both supply qualification and price differentiation simultaneously, forcing OEMs to absorb compliance engineering costs that separate certified European suppliers from non-compliant import alternatives. This regulatory threshold compresses margins on economy-tier equipment while enabling premium positioning for manufacturers with documented blade guard and emergency stop certifications.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on certification grade and after-sales service bundling. Commercial flooring contractors with fleet-scale procurement capture price advantages from multi-unit contracts, while independent renovation operators face higher per-unit costs without volume leverage. Cost compression in the economy tier is intensifying because of synthetic diamond input price volatility and Guangdong motor supply concentration. DIY enthusiasts exhibit the highest price sensitivity, whereas stone fabrication shops prioritize silica compliance over first-cost economics.
Supply Chain Analysis
China and Germany anchor motor and pump subassembly production for wet saw platforms serving North American and European assembly operations. Synthetic diamond cutting edges draw from semiconductor wafer fabrication offcuts, creating demand competition with electronics manufacturing. Single-source vulnerability concentrates in Guangdong Province motor clusters, where tariff exposure or logistics disruption would cascade through OEM production schedules. Distribution runs through specialized industrial equipment distributors and rental channel partners rather than direct manufacturer-to-contractor sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tile saw market functions as a defensive-moat story where regulatory entrenchment around OSHA silica limits and EPA effluent standards creates high switching costs for commercial operators. Established certification pathways and documented compliance histories block rapid competitive entry.
For Market Incumbents: Fortify captive supply of diamond blade consumables through backward integration into synthetic diamond sourcing, neutralizing input cost volatility that threatens aftermarket margin stability. Expand rental channel partnerships in secondary United States metropolitan markets to capture mid-sized contractors without direct capital expenditure capacity, defending against emerging equipment-as-a-service entrants.
For New Entrants and Emerging Players: Lead with portable wet saw miniaturization targeting Florida and Arizona residential renovation contractors where site access constraints favor sub-15-pound configurations. Unbundle laser guidance systems as aftermarket attachments rather than integrated platform features, penetrating the specification-driven commercial flooring segment through lower first-cost positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across closed-loop water recycling system manufacturing as EU Green Deal retrofit subsidies accelerate demand. Acquisition targets should exhibit captive blade production technology or established CE marking compliance infrastructure. Monitor OSHA enforcement inspection priority designations in California, Texas, and New York as the signal indicating wet conversion mandate acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Water System Development | EPA NESHAP compliance enables continued operation in California fabrication shops facing inspection priority. |
| Diamond Blade Manufacturing Integration | In-house synthetic diamond production insulates margins from semiconductor wafer cutting demand competition. |
| Rental Channel Partnership Expansion | Husqvarna's equipment-as-a-service model reaches mid-sized contractors without direct capital expenditure. |
| Laser Guidance System Miniaturization | Aftermarket attachment positioning collapses entry cost for premium accuracy specification segments. |
| Indian Bridge Saw Export Configuration | Metro rail and airport terminal demand in Delhi-Mumbai corridors creates first-time mechanized cutting adoption. |
Methodological Framework
Desk research of customs trade records, SEC equipment manufacturer filings, and EPA enforcement databases preceded structured interviews with commercial flooring fleet managers, stone fabrication shop owners, rental channel operators, and diamond blade procurement leads. Primary fieldwork captured fleet replacement cycles, silica compliance investment timelines, and wet versus dry platform adoption drivers. Secondary validation drew from OSHA inspection data, EU machinery directive guidance documents, and construction equipment distributor sales records. Bottom-up equipment shipment analysis triangulated against top-down construction spending allocation models.
Variance-decomposition across product type, technology tier, end-user capital intensity, and application duty cycle shaped the analytical framework throughout the forecast period. CAGRs derived from segmented growth rate reconciliation against macro construction output projections. Industry-specific inputs included large-format porcelain specification rates by architect segment and silica enforcement inspection priority designations by state.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement intensity or continued EU Green Deal machinery retrofit funding would require recalibration. Forecasts reflect assumptions regarding synthetic diamond supply continuity and Guangdong motor cluster operational stability. Recalibration cycles align with material shifts in EPA NESHAP enforcement patterns or EU industrial emissions framework amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Rivet Gun Market
Tools
Global DC Torque Tool Market
Tools
Dumpy Level Market
Tools
GCC Machine Tools Market
Tools
Crimping Tool Market
Tools
Reamer Market
Tools
CNC Leather Cutting Machine Market
Tools
China Power Tools Market
Tools
Coil Thread Insert Market
Tools
Global Protractor Market
Tools
Concrete Saw Market
Tools
Wire Cutters Market
Tools
United States Machine Tools Market
Tools
Digital Levels Market
Tools
Hydraulic Torque Wrench Market
Tools
End Mill Holder Market