
 Drug Testing Systems Market | 2026-2036
Drug Testing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Testing Systems Market Foresight
Buyer concentration among workplace testing programs is expanding as large logistics chains and national employers consolidate vendor contracts under single-source agreements. Quest Diagnostics leverages its national laboratory footprint to serve these consolidated accounts. Thermo Fisher Scientific sustains technology leadership through mass spectrometry platforms that reduce false-positive rates. Abbott Laboratories competes on point-of-care speed, anchoring its position in rapid-response workplace and clinical settings.
Drug testing systems comprise analytical instruments, consumables, and software platforms designed to detect controlled substances, prescription medications, and illicit drugs in biological specimens with detection thresholds measured in nanograms per milliliter. These systems serve employers, criminal justice agencies, sports organizations, and healthcare providers seeking objective substance-use verification. Urine testing dominates current volume due to established protocols and lower per-test cost, though mass spectrometry-based confirmatory methods command premium positioning in forensic and clinical segments. Immunoassay screening retains structural importance as a frontline filter, while liquid chromatography paired with tandem mass spectrometry captures margin pools in high-stakes legal and elite sports applications.
The U.S. Department of Transportation mandates specific testing protocols under 49 CFR Part 40, while the FDA regulates the analytical performance of in vitro diagnostic devices used in clinical drug testing. The Substance Abuse and Mental Health Services Administration sets cutoff concentrations that directly determine instrument sensitivity requirements and product design specifications. Stakeholders must monitor evolving state-level cannabis legalization frameworks, which create compliance friction between federal mandates and local employment law.
Market Dynamics
Workplace testing programs are consolidating vendor relationships under single-source agreements, compressing procurement cycles and forcing analytical instrument suppliers to bundle consumables, software, and service into unified contracts that lock out fragmented competitors.
Growth Catalysts
- 49 CFR Part 40:The U.S. Department of Transportation's updated federal testing guidelines are tightening compliance windows for employers, mandating more frequent screening across logistics and transportation sectors.
- Mass spectrometry platforms:Advanced detection technologies are reducing false-positive rates in confirmatory testing, expanding adoption in forensic and elite sports applications where legal defensibility is paramount.
- Private-sector wellness programs:Large national employers are integrating substance-use monitoring into broader occupational health frameworks, creating parallel demand streams alongside federally mandated protocols.
Market Restraints
- Helium supply volatility:Gas chromatography-mass spectrometry systems depend on helium as a carrier gas, and price spikes in this input disrupt laboratory operating budgets and instrument utilization rates.
- State-federal cannabis friction:Evolving state-level cannabis legalization frameworks in the United States create compliance conflicts between federal DOT mandates and local employment law protections.
- Immunoassay cross-reactivity:Frontline screening technologies face inherent technical limitations in distinguishing structurally similar compounds, necessitating costly confirmatory testing workflows.
Strategic Opportunities
- Oral fluid testing expansion:Underpenetrated adoption of saliva-based collection methods offers reduced chain-of-custody complexity and observer-privacy advantages over urine protocols.
- AI-assisted result interpretation:Machine learning algorithms are converging with chromatographic data systems to accelerate forensic review timelines and reduce analyst labor intensity.
- Remote collection networks:Third-party specimen collection sites are emerging as a distribution innovation, enabling decentralized workplace programs without on-site medical infrastructure.
Industry Challenges
- Forensic toxicologist shortage:Specialized certification requirements for result verification are creating talent bottlenecks that extend turnaround times for high-stakes legal cases.
- Laboratory information system integration:Legacy hospital and employer IT architectures require costly middleware development to connect with modern cloud-based testing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Testing Systems Market |
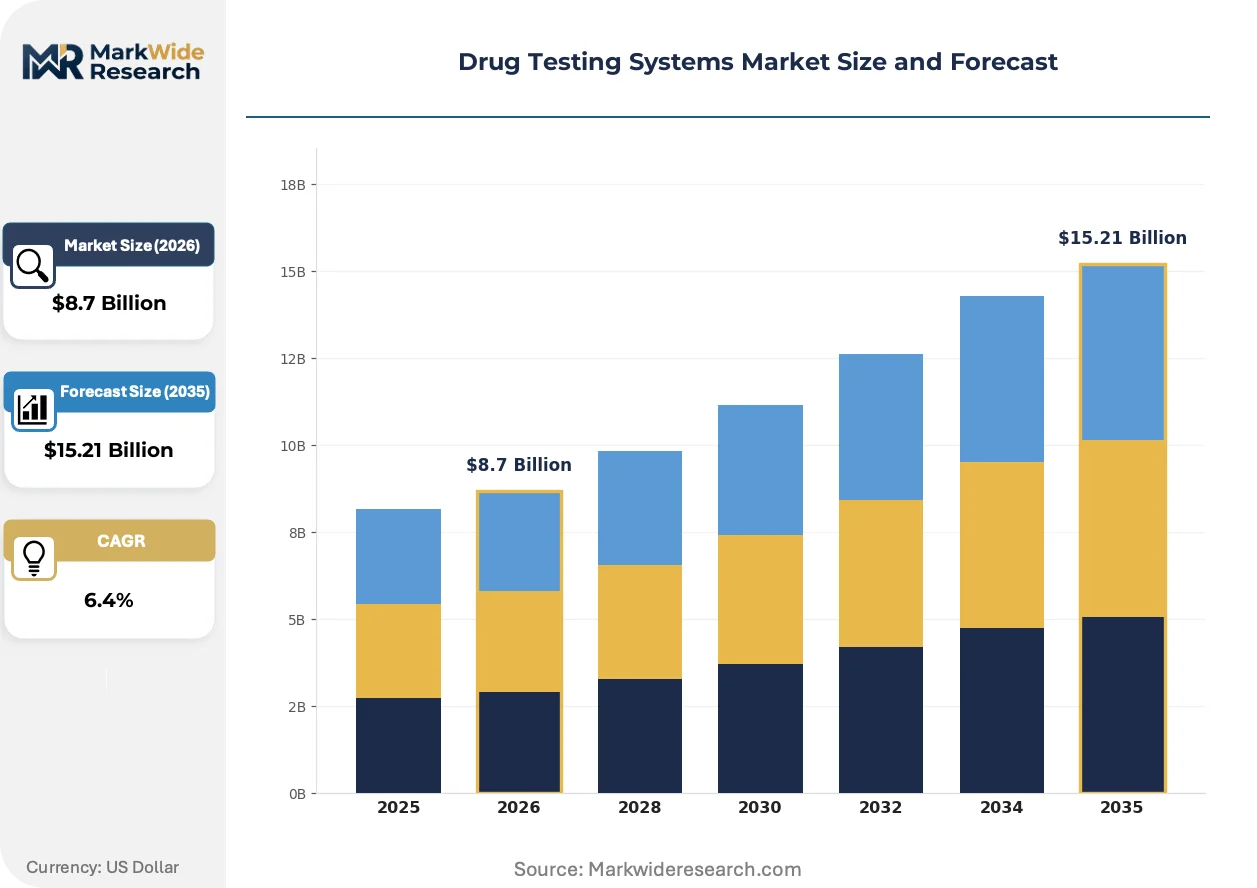
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine Test, Saliva Test, Hair Test, Blood Test Technology: Immunoassay, Gas Chromatography, Liquid Chromatography, Mass Spectrometry End User: Hospitals, Clinics, Rehabilitation Centers, Forensic Laboratories Application: Workplace Testing, Sports Testing, Law Enforcement, Clinical Testing |
| Companies Covered | Quest Diagnostics, Thermo Fisher Scientific, LabCorp, Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, OraSure Technologies, Danaher Corporation, Alfa Scientific Designs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Testing Systems Market Shifts & Advancements
Liquid chromatography-tandem mass spectrometry is displacing older confirmatory methods as the analytical backbone of high-stakes testing, while point-of-care immunoassay devices compress result timelines for rapid workplace decisions. These shifts are redrawing competitive boundaries between laboratory-centric and distributed testing models.
High-resolution mass spectrometry is integrating into forensic toxicology workflows, enabling retrospective data mining for novel psychoactive substances without reanalysis. State crime laboratories and elite sports anti-doping agencies are adopting these platforms aggressively. The technology is integrating previously separate screening and confirmation steps into unified analytical sequences that reduce sample volume requirements and labor costs.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in analytical instrumentation cooling systems, forcing manufacturers to redesign thermal management architectures for chromatography platforms. Laboratory equipment suppliers serving the European Union must now certify compliance with refrigerant quotas. Gas chromatography-mass spectrometry product lines face the steepest redesign timelines, with 2027 deadlines accelerating R&D resource allocation toward alternative cooling chemistries.
Employer procurement departments are unbundling after-sales service contracts from instrument purchases, negotiating separate multi-vendor maintenance agreements that prioritize uptime guarantees over manufacturer loyalty. Third-party service providers are capturing calibration and preventive maintenance revenue that previously flowed to original equipment manufacturers. This pattern is most visible among Fortune 500 logistics chains with national testing footprints spanning multiple laboratory vendor relationships.
Drug Testing Systems Market Segmentation
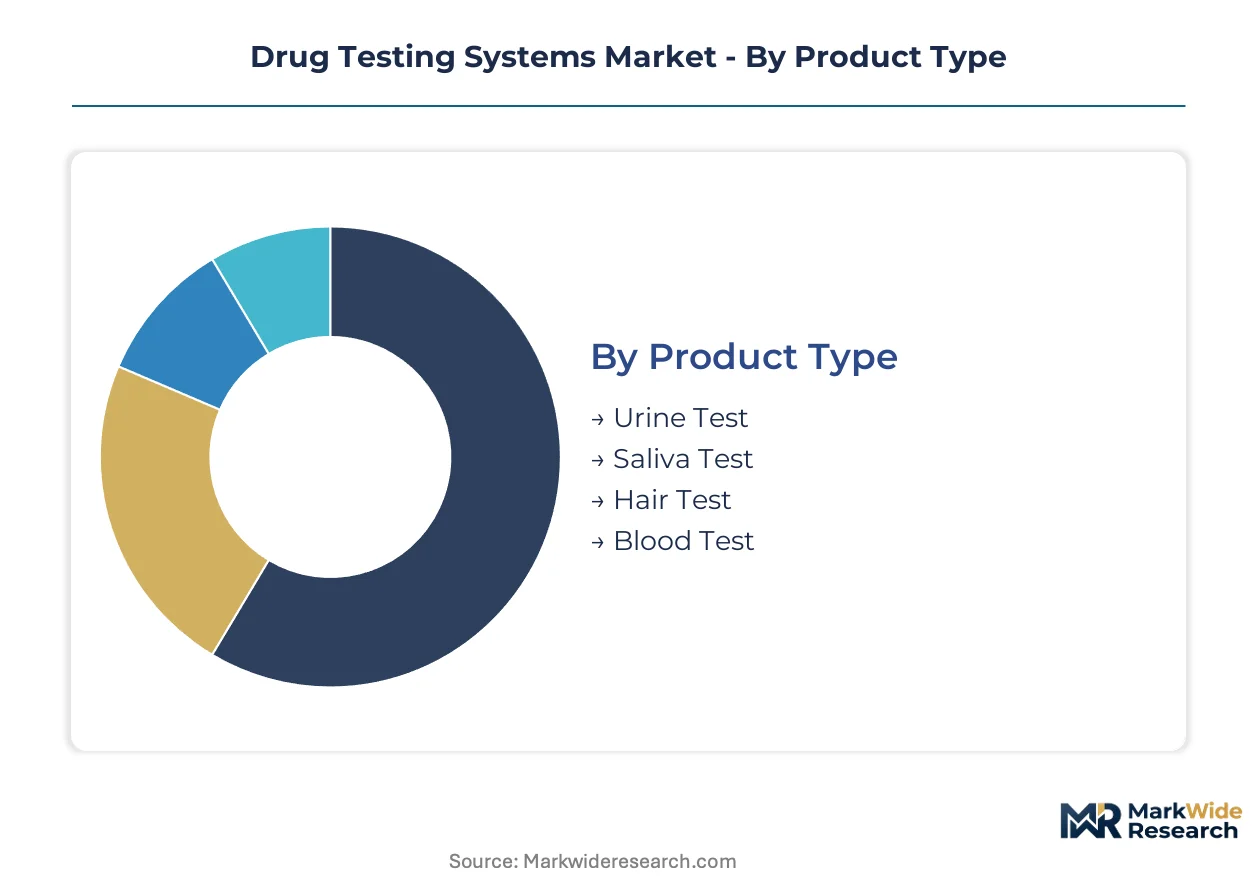
Drug testing systems fragment across specimen types, analytical platforms, and institutional end-uses. Procurement patterns diverge sharply between high-volume workplace screening and low-volume forensic confirmation, creating tiered investment profiles across segments.
Product Type:
Capital intensity peaks in blood testing infrastructure, where phlebotomy networks and cold-chain logistics multiply fixed costs beyond benchtop instrumentation alone.
- Urine Test:Dipstick immunoassay strips and cup-based collection vessels dominate procurement volumes. Logistics chains and transportation employers in the United States anchor demand through federally mandated DOT protocols under 49 CFR Part 40.
- Saliva Test:Oral fluid collection devices eliminate bathroom privacy requirements and reduce chain-of-custody documentation. Workplace wellness programs and decentralized employer networks are adopting these kits to bypass on-site medical infrastructure.
- Hair Test:Extended detection windows spanning months rather than days serve forensic casework and pre-employment screening for safety-sensitive positions.
- Blood Test:Direct serum analysis delivers the shortest detection windows and highest analytical certainty for clinical toxicology and impaired-driving investigations.
Most installed capacity flows through Urine Test segments. Expansion is steepest in Saliva Test adoption.
Technology:
Margin capture concentrates in confirmatory platforms, where instrument depreciation and specialized operator labor create defensible pricing power.
- Mass Spectrometry:LC-MS/MS and GC-MS platforms deliver sub-nanogram-per-milliliter sensitivity with structural specificity that eliminates cross-reactivity. Elite sports anti-doping agencies and state crime laboratories in the United States prioritize these systems for legal defensibility.
- Immunoassay:Competitive and sandwich immunoassay formats provide rapid qualitative screening at the point of collection. Workplace testing programs deploy these as frontline filters to triage specimens for expensive confirmation.
- Gas Chromatography:Volatile compound separation paired with mass detection serves post-mortem toxicology and forensic alcohol analysis. Helium supply constraints are forcing laboratories to evaluate hydrogen carrier alternatives.
- Liquid Chromatography:Reverse-phase separation of polar and non-polar analytes precedes mass spectrometric detection in high-throughput clinical laboratories.
Revenue concentration sits with Mass Spectrometry. Volume leadership belongs to Immunoassay.
End User:
Procurement sophistication varies by institutional scale, with national laboratory networks extracting bundled pricing that fragments regional competitors.
- Forensic Laboratories:State and local crime laboratories demand ISO 17025-compliant confirmation platforms with full chain-of-custody documentation. Caseload backlogs in the United States are driving automation investments.
- Hospitals:Emergency departments and clinical toxicology services require rapid turnaround for overdose management and therapeutic drug monitoring. Integration with electronic health record systems shapes vendor selection.
- Rehabilitation Centers:Substance abuse treatment facilities combine point-of-care screening with laboratory confirmation for patient compliance monitoring.
- Clinics:Occupational health and primary care clinics serve employer contracts with mixed rapid and send-out testing workflows.
Instrument specification complexity peaks at Forensic Laboratories. Patient volume scale concentrates at Hospitals.
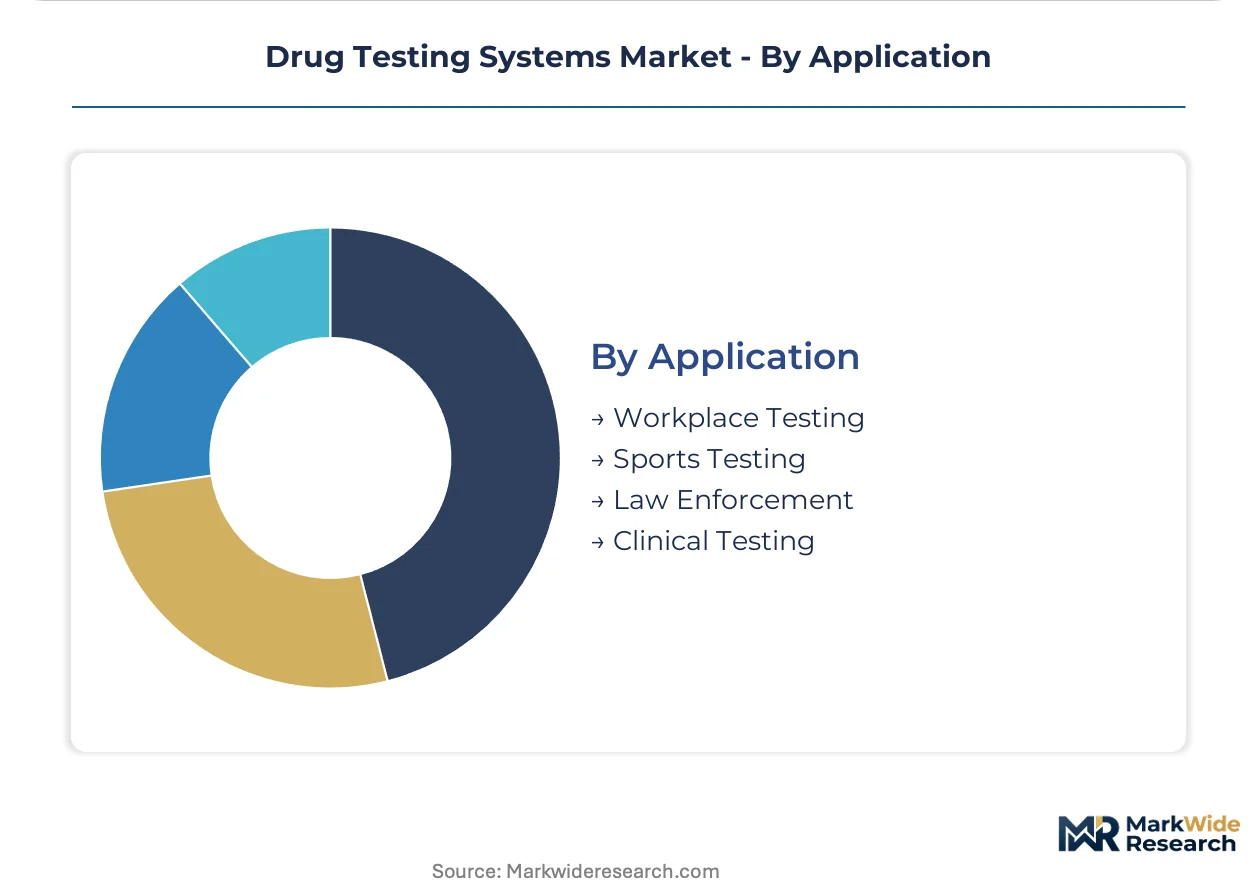
Application:
Regulatory mandate density determines contract stability, with federally required testing programs offering predictable replacement cycles.
- Workplace Testing:Federally mandated safety-sensitive positions and private employer wellness programs generate recurring screening volume. DOT guideline updates are tightening compliance windows for logistics operators.
- Law Enforcement:DUID investigations, probation monitoring, and correctional facility screening demand legally defensible confirmation methods. State-level cannabis legalization in the United States creates evidentiary complexity.
- Sports Testing:Anti-doping agencies and collegiate athletic programs require WADA-compliant detection of performance-enhancing substances and masking agents.
- Clinical Testing:Pain management compliance and medication adherence monitoring serve prescriber liability reduction and patient safety objectives.
Contract value stability characterizes Workplace Testing. Technical specification intensity dominates Sports Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workplace toxicologists and forensic chemists cluster in jurisdictions with dense transportation networks and stringent occupational safety mandates. Talent pools concentrate where federal testing protocols intersect with high-volume logistics employment.
United States
The DOT's 49 CFR Part 40 mandates create sustained instrument demand across trucking fleets and aviation operators. OSHA workplace safety inspections reinforce employer compliance investments. Houston and Memphis logistics hubs anchor high-throughput screening laboratory networks serving cross-border freight corridors.
Germany
Chemical industry employers and automotive manufacturers drive workplace testing program expansion. The F-Gas Regulation forces chromatography equipment redesigns for EU market access. Bavarian industrial clusters around Munich host specialized toxicology service providers serving DAX-listed employers.
China
Express delivery and e-commerce logistics employers scale workforce screening programs. NMPA regulates in vitro diagnostic device registration for clinical toxicology applications. Yangtze River Delta pharmaceutical manufacturing centers generate demand for raw material purity verification systems.
United Kingdom
Railway and maritime safety regulations mandate substance testing for transport workers. The MHRA oversees analytical performance standards for forensic toxicology devices. London's financial services sector funds occupational health programs extending testing to white-collar compliance frameworks.
Japan
Metropolitan police departments and professional sports leagues sustain forensic laboratory investments. METI industrial safety guidelines shape employer testing protocols. Osaka-Kobe pharmaceutical manufacturing corridor demands contamination detection systems with sub-nanogram sensitivity.
Drug Testing Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument, consumable, and service segments. Market structure tilts toward consolidation as national laboratory networks extract bundled pricing from fragmented regional competitors. Three archetypes dominate: integrated diagnostic conglomerates with multi-modal platforms, pure-play toxicology specialists with forensic certification depth, and point-of-care device manufacturers emphasizing speed over sensitivity. M&A activity concentrates in consumables and software layers, while strategic partnerships link instrument makers with third-party collection networks.
Among diversified diagnostic conglomerates, Quest Diagnostics and Thermo Fisher Scientific exemplify scale-driven positions spanning laboratory services and analytical instrumentation. Abbott Laboratories occupies a distinct rapid-testing tier. These three anchors represent divergent strategic bets: service integration versus technology leadership versus point-of-care speed.
| Leading Market Players |
|---|
| Quest Diagnostics |
| Thermo Fisher Scientific |
| LabCorp |
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| OraSure Technologies |
| Danaher Corporation |
| Alfa Scientific Designs |
| Others |
Supply & Pricing Matrix
Workplace testing program consolidation under single-source vendor agreements is compressing procurement leverage and forcing instrument suppliers to absorb margin erosion through bundled service concessions. This demand-side concentration reshapes supply economics as manufacturers trade upfront instrument margins for locked-in consumable streams.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for immunoassay consumables and benchtop analyzers. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales bundling intensity. Cost compression in rapid screening tiers is intensifying because logistics employers unbundle service contracts and pit third-party maintenance providers against OEMs. Forensic laboratories exhibit least price sensitivity due to ISO 17025 compliance requirements, while decentralized workplace programs show highest elasticity.
Supply Chain Analysis
ISO 17025 and FDA 510(k) certification gating constrains supplier qualification timelines and limits rapid supplier switching for high-stakes applications. Manufacturing concentrates in the United States, Germany, and China, with precision mass spectrometry components drawing from specialized optics suppliers in Japan and Switzerland. Helium carrier gas sourcing and rare-earth magnet supply for ion trap assemblies constitute critical input dependencies. Single-source vulnerability runs through specialized electron multiplier tube suppliers. Distribution runs through national laboratory networks and third-party collection site franchises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by federally mandated testing protocols that resist cyclical downturns. DOT guideline enforcement creates predictable replacement demand for compliant instrumentation.
For Market Incumbents: Acquire remote collection network assets to capture decentralized workplace testing growth outside traditional laboratory infrastructure. Consolidate forensic toxicologist training pipelines to defend against talent bottlenecks extending turnaround times. Lock in multi-year consumable offtake agreements with national logistics chains before third-party service providers capture calibration revenue.
For New Entrants and Emerging Players: Capture oral fluid testing adoption curves among employers seeking to bypass on-site medical infrastructure and chain-of-custody complexity. Target mid-sized occupational health clinics with hybrid rapid-send-out workflows as the most penetrable segment. Lead with AI-assisted chromatographic data interpretation to reduce analyst labor intensity and accelerate forensic review timelines.
For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play toxicology specialists possessing forensic certification depth and state crime laboratory relationships. Five-to-ten year viability hinges on regulatory mandate durability rather than discretionary employer spending. Watch for state-federal cannabis policy harmonization as inflection indicator for workplace testing demand stabilization.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Result Interpretation | Machine learning integration with LC-MS/MS platforms reduces forensic toxicologist labor intensity at state crime laboratories. |
| Oral Fluid Testing Expansion | Saliva-based collection methods bypass chain-of-custody documentation requirements for decentralized employer networks. |
| Helium Supply Diversification | Hydrogen carrier gas transition mitigates price volatility exposure for GC-MS-dependent forensic alcohol analysis. |
| Third-Party Collection Network Buildout | Franchised specimen collection sites extend workplace program reach without employer on-site medical infrastructure. |
| F-Gas Regulation Compliance Redesign | Alternative cooling chemistry certification maintains EU market access for chromatography platform manufacturers. |
Research Methodology
Direct dialogue with forensic laboratory directors, workplace toxicologists, occupational health procurement managers, and diagnostic instrument R&D heads grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, DOT compliance bulletins, SAMHSA cutoff concentration updates, and SEC 10-K instrument revenue disclosures. Bottom-up instrument installation counts and top-down laboratory services market sizing were triangulated against trade association membership data.
Segment-level value outputs across the analysis window reflect modeled deployment rates by specimen type, technology platform, and end-user institutional scale. CAGRs were derived from instrument replacement cycle analysis and consumable pull-through assumptions tied to testing volume elasticity. Helium supply disruption scenarios and state-level cannabis legalization progression were incorporated as scenario-weighted inputs.
Underlying measurement precision varies by segment; mass spectrometry platform revenue carries tighter precision than rapid immunoassay consumable estimates. Forecasts reflect documented assumptions regarding DOT guideline enforcement intensity and forensic laboratory automation investment pacing. A model refresh is warranted upon material change in federal cannabis rescheduling or F-Gas Regulation phase-down acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Syphilis Testing Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Apoptosis Testing Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Vials Leak Testing Market
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
Global C-Reactive Protein Testing Market
Testing Services
In-Vitro Diagnostic Services Market
Testing Services
Home Care Testing Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Global Endocrine Testing Market
Testing Services
Adiponectin Testing Market
Testing Services
Infusion Toxicology Services Market