
 Global Creatinine Assay Kits Market | 2026-2036
Global Creatinine Assay Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Global Creatinine Assay Kits Market Foresight
China is reshaping competitive dynamics in creatinine assay manufacturing through expanded biotech production corridors in Suzhou and Shanghai. Thermo Fisher Scientific leverages its reagent supply chain to anchor North American hospital laboratory contracts. Merck KGaA sustains European market presence through ISO-certified enzymatic kit production in Darmstadt. Abbott Laboratories competes on integrated analyzer-and-reagent systems that reduce calibration drift in high-throughput settings.
Creatinine assay kits are biochemical reagent systems that quantify creatinine concentration in biological specimens through enzymatic conversion or picric acid complexation, typically achieving detection sensitivities in the micromolar range for clinical diagnostic applications. These kits serve nephrologists, drug developers, and veterinary clinicians who require standardized renal function biomarker quantification across serum, plasma, and urine matrices. Enzymatic kits now lead product type revenue due to superior specificity over Jaffe-based methods in lipemic and hemolyzed samples. Automated assay kits are displacing manual workflows in diagnostic centers where labor cost reduction and throughput standardization drive purchasing decisions. Photometric technology dominates installed instrument bases, though fluorometric methods are gaining share in research laboratories pursuing multiplexed analyte panels.
The FDA enforces analytical accuracy thresholds for creatinine assays used in estimated glomerular filtration rate calculations under Clinical Laboratory Improvement Amendments guidelines. The European Medicines Agency and Notified Bodies under IVDR now require expanded clinical evidence for Class B and C in vitro diagnostic reagents, extending certification timelines for kit manufacturers. China's National Medical Products Administration aligns domestic creatinine assay registrations with international reference material traceability standards. Stakeholders must monitor evolving harmonization between FDA and NMPA performance criteria to anticipate dual-market registration requirements.
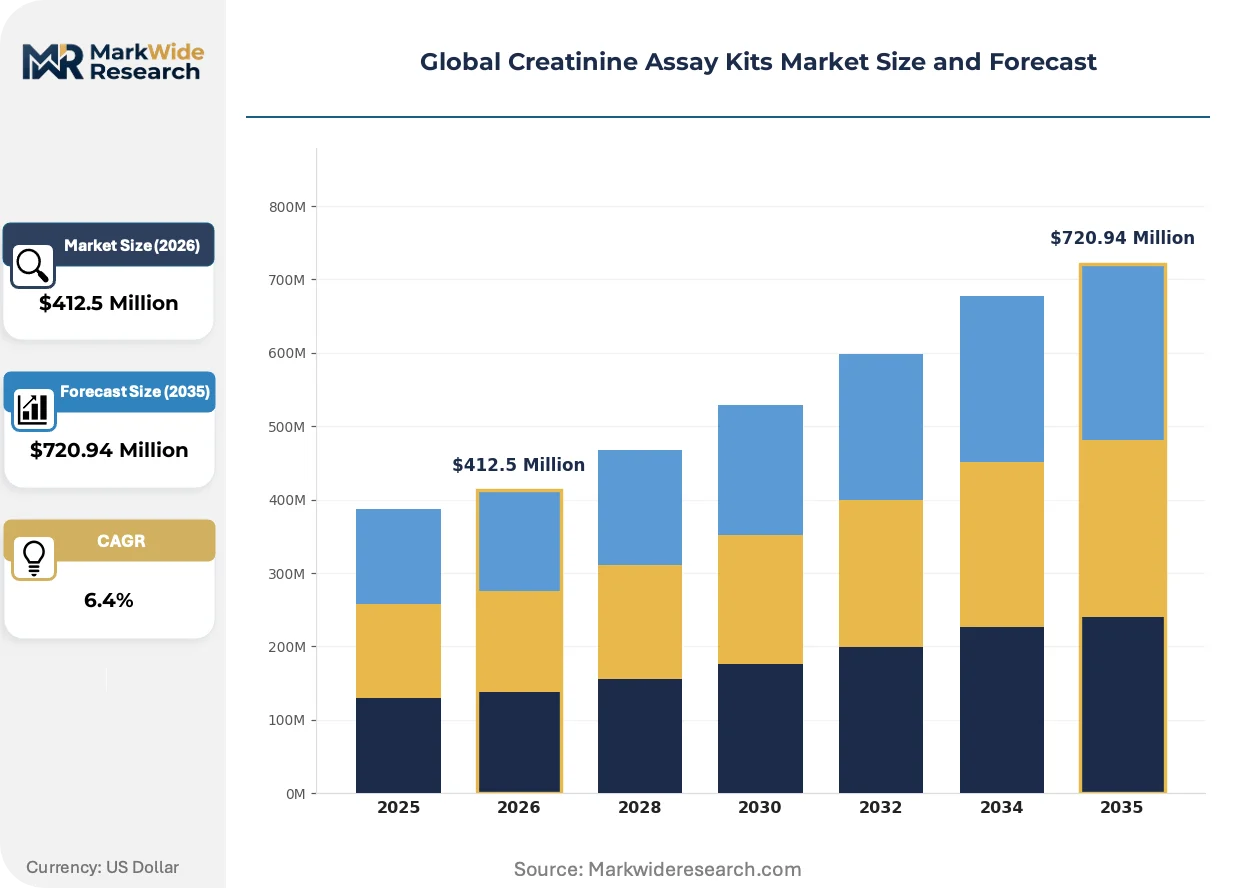
Market Dynamics
Enzymatic assay platforms are displacing legacy Jaffe methods as the dominant technology architecture, driven by tighter FDA and IVDR accuracy mandates for estimated glomerular filtration rate calculations in chronic kidney disease screening programs.
Growth Catalysts
- IVDR Certification Requirements:The European Union's In Vitro Diagnostic Regulation mandates expanded clinical evidence for Class B and C reagents, accelerating hospital laboratory upgrades to compliant enzymatic platforms.
- Point-of-Care Expansion:Diagnostic centers in India and Brazil are procuring automated assay systems to reduce calibration drift and labor costs in high-throughput renal function testing.
- Chronic Kidney Disease Screening:National health programs in China and the United States are widening access to standardized creatinine measurement for early-stage nephrology intervention.
Market Restraints
- Reference Material Volatility:International standard traceability requirements for creatinine calibrators are increasing reagent production costs and supplier qualification timelines.
- Supply Concentration Risk:Enzyme manufacturing for assay kits concentrates among specialized biochemical suppliers in Germany and Japan, creating vulnerability to geographic disruption.
- Photometric Instrument Lock-In:Existing installed bases of photometric analyzers in clinical laboratories delay fluorometric method adoption despite superior multiplexing capability.
Strategic Opportunities
- Veterinary Diagnostics:Standardized renal biomarker quantification for companion animal nephrology remains underpenetrated across North American and European veterinary clinic networks.
- Multiplexed Research Panels:Fluorometric creatinine assays are converging with cytokine and metabolic biomarker detection for integrated drug development screening workflows.
- Dual-Market Registration:Manufacturers aligning FDA and NMPA performance criteria can capture parallel commercialization pathways in the United States and China.
Industry Challenges
- IVDR Timeline Compression:Notified Body backlogs for Class C in vitro diagnostic certification are extending product launch schedules by 12-18 months for European market entry.
- Legacy System Integration:Automated assay platforms require middleware adaptation for hospital laboratory information systems, increasing implementation complexity and training burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Creatinine Assay Kits Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymatic Kits, Jaffe Method Kits, Calorimetric Kits, Automated Assay Kits Application: Clinical Diagnostics, Drug Development, Veterinary Testing, Sports Medicine End User: Research Laboratories, Diagnostic Centers, Pharmaceutical Companies, Academic Institutes Technology: Photometric, Electrochemical, Fluorometric, Mass Spectrometry |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, Merck KGaA, Quidel Corporation, Cell Biolabs, Inc, Abcam, Enzo Life Sciences, Genway Biotech, Cayman Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Creatinine Assay Kits Market Shifts & Advancements
Digital integration of assay workflows with laboratory information systems is compressing turnaround times and enabling real-time quality monitoring across distributed diagnostic networks.
Artificial intelligence-enabled result validation is digitizing creatinine assay interpretation by flagging hemolyzed or lipemic sample interference before manual review. Mid-sized hospital laboratories in Germany and Japan are piloting these systems at accelerated procurement cycles. This technology is digitizing error detection workflows and reducing repeat testing rates in high-volume clinical chemistry departments.
The FDA's updated Clinical Laboratory Improvement Amendments guidance enforces stricter analytical accuracy thresholds for creatinine assays used in estimated glomerular filtration rate calculations. Manufacturers must now demonstrate traceability to certified reference materials through expanded validation studies. Enzymatic kit producers targeting United States hospital contracts are responding by reformulating reagent compositions to meet bias specification limits.
Consolidated procurement through group purchasing organizations is concentrating buying power among integrated health networks and displacing individual laboratory purchasing autonomy. Diagnostic reagent distributors in the United States are restructuring commission structures to retain contract access. This shift is most visible in multi-hospital systems standardizing on single-vendor analyzer-and-reagent platforms to reduce calibration variability across satellite clinics.
Global Creatinine Assay Kits Market Segmentation
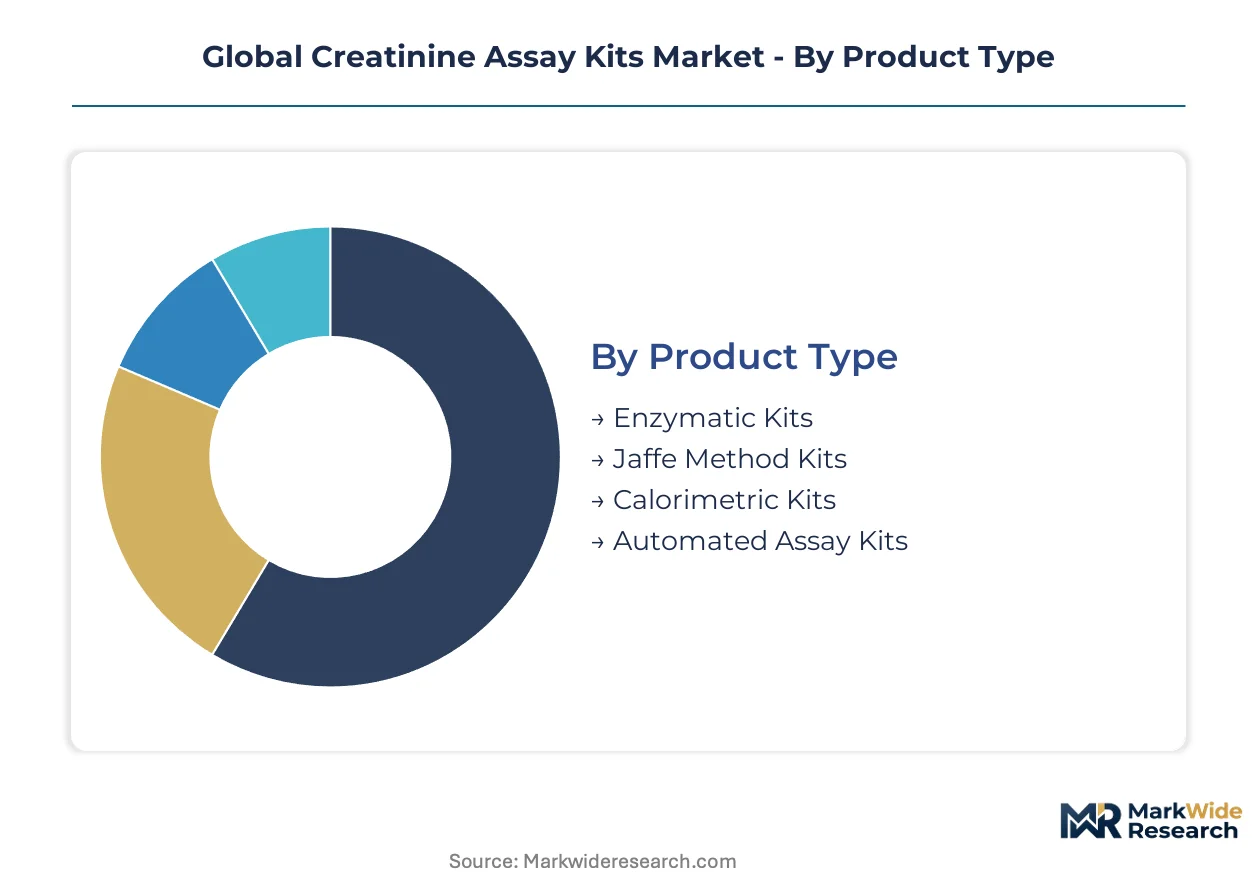
Creatinine assay kit segmentation reveals divergent procurement cycles across product architectures and end-use environments. Clinical laboratories rotate enzymatic reagent inventories quarterly while research institutions maintain fluorometric assay stocks for extended validation protocols.
Product Type:
Enzymatic kits turn over fastest in hospital laboratories seeking IVDR-compliant reagent freshness, while Jaffe method stocks linger in cost-constrained settings with legacy analyzer commitments.
- Enzymatic Kits:These reagent systems deploy creatininase-creatinase-sarcosine oxidase cascades to eliminate bilirubin and hemoglobin interference. Diagnostic centers in Germany and Japan are standardizing procurement on these platforms to meet EMA analytical accuracy mandates for estimated glomerular filtration rate reporting.
- Automated Assay Kits:Pre-calibrated reagent cartridges integrate with closed-system analyzers to reduce manual pipetting error. High-throughput hospital networks in the United States are consolidating contracts around single-vendor automated platforms to compress turnaround times across satellite laboratories.
- Jaffe Method Kits:Picric acid alkaline complexation chemistry persists in price-sensitive markets with older photometric instrument bases.
- Calorimetric Kits:Heat-based detection methods serve specialized research applications requiring simplified workflow integration.
Enzymatic kits anchor the volume base while automated assay platforms gain share at the steepest rate.
Application:
Clinical diagnostics commands the largest procurement budgets, though veterinary and sports medicine segments present divergent margin structures and regulatory exposure profiles.
- Clinical Diagnostics:Serum and urine creatinine quantification for chronic kidney disease staging drives reagent consumption across hospital chemistry departments. China's national screening programs are expanding point-of-care access in provincial health systems.
- Drug Development:Pharmacokinetic studies require standardized renal clearance biomarkers across Phase I-III trials. Contract research organizations in the United States and India are integrating multiplexed creatinine panels into integrated metabolic profiling workflows.
- Veterinary Testing:Companion animal nephrology applications remain fragmented across North American and European clinic networks.
- Sports Medicine:Athlete renal function monitoring supports dehydration and supplement safety protocols in professional team settings.
Clinical diagnostics absorbs the majority of reagent volumes even as drug development applications expand most quickly.
End User:
Diagnostic centers concentrate purchasing power through group procurement organizations, while research laboratories maintain fragmented buying patterns across grant-funded principal investigators.
- Diagnostic Centers:High-throughput clinical chemistry departments process thousands of creatinine determinations daily. Automated platform standardization is reducing calibration drift across multi-site health networks in Brazil and India.
- Research Laboratories:Academic and institutional investigators prioritize assay flexibility over throughput for mechanistic nephrology studies. Fluorometric method adoption is climbing fastest in these settings for multiplexed biomarker integration.
- Pharmaceutical Companies:In-house bioanalytical groups support regulatory submission requirements for renal safety pharmacology.
- Academic Institutes:Teaching hospital laboratories balance educational mission requirements with clinical service obligations.
Diagnostic centers dominate absolute consumption while research laboratories drive technology transition toward advanced detection methods.
Technology:
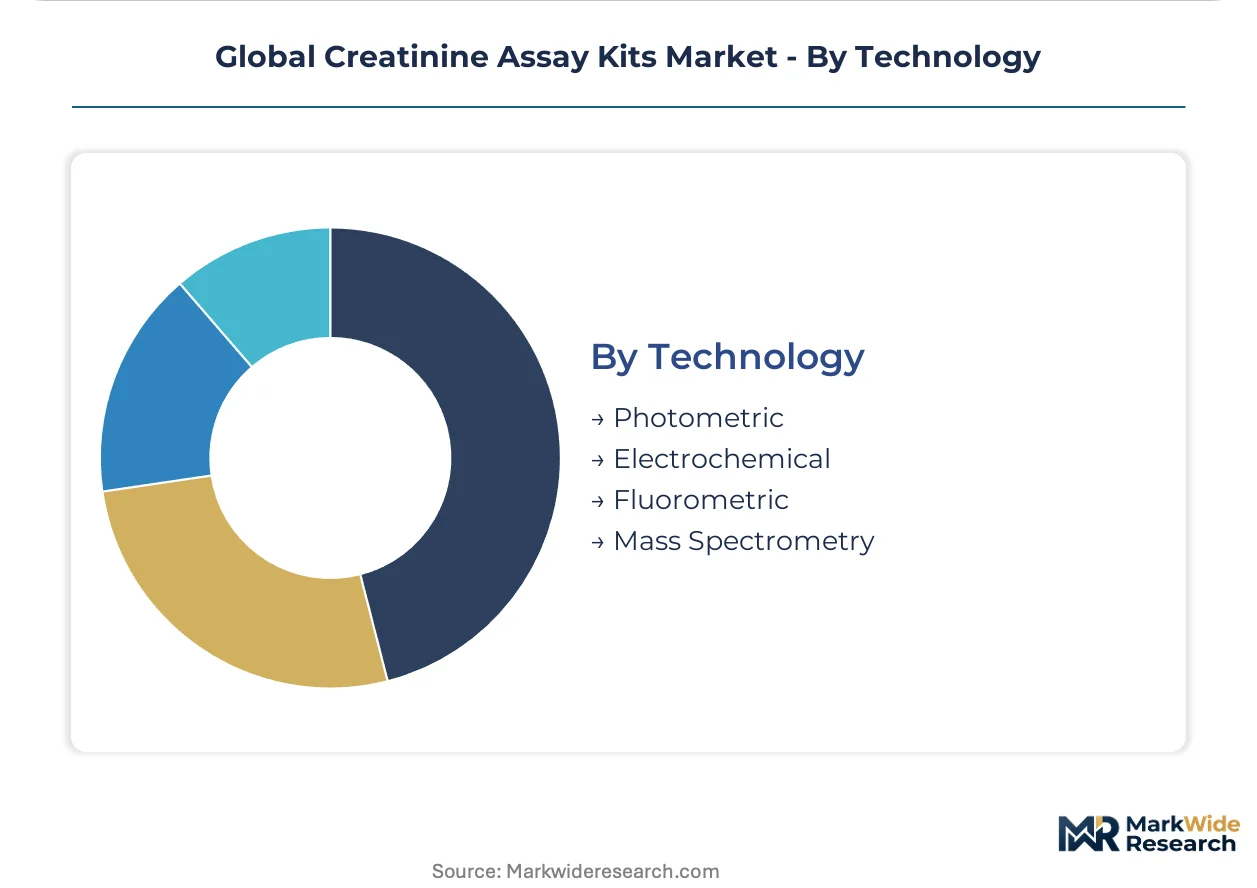
Photometric detection retains installed base dominance, though fluorometric and mass spectrometry platforms are capturing premium positioning in specialized applications.
- Photometric:Absorbance-based measurement at 500-550 nm wavelengths powers the majority of clinical chemistry analyzers. Existing instrument depreciation cycles in United States hospital laboratories are delaying displacement despite fluorometric performance advantages.
- Fluorometric:Excitation-emission detection achieves superior sensitivity for low-volume sample analysis. Research institutions in Germany and Japan are piloting these systems for cytokine-creatinine multiplexed panels in drug development screening.
- Electrochemical:Biosensor-based approaches serve point-of-care and wearable diagnostic prototypes.
- Mass Spectrometry:LC-MS/MS methods provide reference-grade accuracy for calibrator validation and disputed clinical results.
Photometric technology maintains volume leadership while fluorometric methods climb the fastest in research-intensive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA analytical accuracy mandates under Clinical Laboratory Improvement Amendments guidelines anchor procurement patterns in the United States, while IVDR certification timelines reshape European laboratory upgrade cycles. National screening programs in China and India are expanding point-of-care access to enzymatic assay platforms.
United States
Hospital networks in the United States are consolidating contracts around single-vendor automated analyzer platforms to reduce calibration drift across satellite laboratories. FDA enforcement of stricter bias specification limits for estimated glomerular filtration rate calculations is forcing reagent reformulation among kit manufacturers targeting hospital contracts. Group purchasing organizations in the Midwest and Southeast are concentrating buying power among integrated health systems.
Germany
Diagnostic centers across Germany are standardizing procurement on enzymatic platforms to meet EMA analytical accuracy mandates for renal function reporting. IVDR certification requirements for Class B and C reagents are extending product launch schedules by 12-18 months for European market entry. The Darmstadt production corridor sustains ISO-certified enzymatic kit manufacturing for continental supply.
China
Provincial health systems in China are widening access to point-of-care renal function testing through national chronic kidney disease screening programs. NMPA alignment of domestic creatinine assay registrations with international reference material traceability standards is tightening supplier qualification timelines. Biotech production corridors in Suzhou and Shanghai are expanding enzymatic reagent manufacturing capacity.
Japan
Clinical diagnostics laboratories in Japan are accelerating procurement of automated assay platforms to reduce labor costs in high-throughput settings. PMDA oversight of in vitro diagnostic reagent quality standards is elevating documentation requirements for enzymatic kit registrations. The Nagoya and Osaka metropolitan clusters concentrate specialized biochemical enzyme suppliers for assay manufacturing.
Brazil
Diagnostic centers in Brazil are procuring automated assay systems to compress turnaround times across multi-site health networks. ANVISA regulatory pathways for imported diagnostic reagents are extending distribution qualification timelines for international kit manufacturers. São Paulo and Rio de Janeiro anchor procurement concentration for Southeast Asian laboratory supply chains.
Global Creatinine Assay Kits Market Competitive Landscape
Integrated life science conglomerates and specialized diagnostic reagent manufacturers split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: full-platform integrators bundling analyzers with captive reagent supply, pure-play biochemical reagent specialists, and research-grade assay developers serving pharmaceutical contract research. Competitive moves center on dual-market registration alignment for FDA and NMPA parallel commercialization, plus middleware adaptation for hospital laboratory information system integration.
Among integrated platform providers, Abbott Laboratories and Thermo Fisher Scientific exemplify the full-system bundling archetype that reduces calibration variability across satellite clinic networks. Merck KGaA occupies a position within the European-centered enzymatic reagent specialist tier, leveraging ISO-certified production infrastructure for continental supply security. These three entities represent contrasting geographic anchoring strategies—North American hospital network penetration, diversified reagent supply chain scale, and European regulatory compliance manufacturing—rather than direct product competition.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Merck KGaA |
| Quidel Corporation |
| Cell Biolabs, Inc |
| Abcam |
| Enzo Life Sciences |
| Genway Biotech |
| Cayman Chemical |
| Others |
Supply & Pricing Matrix
Darmstadt's ISO-certified enzymatic reagent production corridor anchors continental European supply, translating manufacturing scale into pricing leverage for IVDR-compliant kit manufacturers serving hospital laboratory networks.
Pricing Analysis
Geographic price spreads between North American hospital contracts and Asian diagnostic center procurement run 15-25 percent for equivalent enzymatic platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated reference-grade kits from CE-marked clinical tiers and unregistered research-use products. Price differentiation hinges on certification tier and volume scale, with GPO-negotiated contracts compressing margins for mid-tier suppliers. Cost compression in economy-tier Jaffe method stocks is intensifying because legacy analyzer depreciation cycles extend replacement demand.
Supply Chain Analysis
Contract manufacturing for assay enzymes concentrates with specialized biochemical suppliers in Nagoya, Osaka, and Darmstadt, with limited qualified alternatives for creatininase-creatinase-sarcosine oxidase cascades. Raw material dependencies center on porcine-derived enzymes, stabilized cofactor reagents, and NIST-traceable calibrator materials. Single-source vulnerability in Japanese enzyme fermentation capacity creates exposure to geographic disruption. Distribution runs through diagnostic reagent distributors restructuring commission structures to retain integrated health network access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic platform displacement of Jaffe methods under tightening FDA and IVDR accuracy mandates creates a high-growth disruption window for repositioned supply chains and consolidated procurement channels.
For Market Incumbents: Harden IVDR certification timelines by pre-submission engagement with Notified Bodies, compressing 12-18 month approval windows. Defend against emerging pure-play reagent specialists by backward integration into captive enzyme fermentation capacity in the Darmstadt or Nagoya clusters. Anchor hospital contracts through middleware adaptation for laboratory information system integration.
For New Entrants and Emerging Players: Brazilian diagnostic center networks present the most penetrable white-space target, with ANVISA regulatory pathways creating qualification barriers that favor prepared entrants. Veterinary companion animal nephrology across North American clinic networks offers second-tier expansion potential. Pursue automated platform bundling with reagent supply contracts to bypass standalone analyzer procurement cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because IVDR and FDA timeline extensions concentrate market share among capitalized incumbents capable of sustained certification investment. Target acquisition profiles center on mid-cap enzymatic reagent specialists with ISO-certified production and existing Notified Body relationships. Monitor Notified Body backlog clearance rates as the primary inflection signal for European market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Certification Pre-Submission | Notified Body engagement reduces European market entry timelines for Class C reagents. |
| Enzyme Fermentation Capacity Expansion | Captive supply of creatininase reduces dependency on Nagoya and Osaka specialized suppliers. |
| Middleware LIS Integration Development | Hospital laboratory information system adaptation accelerates automated platform adoption. |
| Veterinary Diagnostics Portfolio Extension | Companion animal nephrology applications remain fragmented across North American clinic networks. |
| Dual-Market FDA-NMPA Registration Alignment | Parallel commercialization pathways capture United States and China procurement cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across nephrology department heads, hospital laboratory managers, diagnostic reagent procurement specialists, and regulatory affairs leads at kit manufacturers. Secondary validation drew from FDA 510(k) filings, EMA IVDR technical documentation summaries, NMPA registration databases, and CMS clinical laboratory fee schedules. Bottom-up reagent consumption modeling triangulated against top-down diagnostic procedure volume estimates.
Calibration against historical procurement cycles and regulatory milestone timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, detection technology, end-user facility type, and regional regulatory cluster. CAGRs were derived from instrument replacement cycle analysis and screening program expansion trajectories. Forecast inputs incorporated IVDR certification backlog projections and chronic kidney disease prevalence modeling.
Practitioners should monitor Notified Body capacity expansion and NMPA reference material traceability enforcement for early signals of supply constraint or registration delay. Forecasts reflect assumptions regarding regulatory timeline stability and enzyme supplier geographic concentration. Quarterly review of certification backlog indicators and calibrator material qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Home Blood Testing Devices Market
Testing Services
Nipah Virus Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Global Urinalysis Test Market
Testing Services
Chromatin Immunoprecipitation Testing Market
Testing Services
Drug Testing Equipment Market
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Europe Esoteric Testing Market
Testing Services
Global Bioburden Testing Market
Testing Services
Urodynamic Testing Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Antimicrobial Susceptibility Testing Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Hbsag Testing Market