
 Brazil Methanol Market | 2026-2036
Brazil Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Methanol Market Insights
The price spread between fuel-grade and pharmaceutical-grade methanol is hardening as certification requirements diverge. Methanex Corporation leverages its integrated production network to sustain cost advantages across Atlantic basin supply routes. BASF SE anchors its Brazilian position through specialized chemical-grade distribution tied to downstream formaldehyde operations. Celanese Corporation differentiates via technology leadership in acetic acid derivatives that consume high-purity feedstock.
Methanol is a light, volatile alcohol (CH₃OH) produced primarily via steam methane reforming or coal gasification, with specifications varying by water content, acidity, and trace contaminant thresholds. Fuel-grade supply dominates Brazilian volume flows, reflecting RenovaBio-linked blending mandates and industrial boiler applications. Chemical-grade methanol captures concentrated margin pools, as formaldehyde and acetic acid producers in the São Paulo petrochemical cluster demand consistent purity. Energy Production applications show structural momentum, with methanol-to-hydrogen pathways gaining traction among distributed power developers.
ANVISA governs pharmaceutical-grade standards, while the National Petroleum Agency regulates fuel-specification compliance and blending ratios. The Brazilian Institute of Metrology, Standardization and Industrial Quality enforces purity benchmarks that shape import acceptance criteria. Stakeholders must monitor RenovaBio credit pricing mechanics and potential adjustments to industrial natural gas tariffs that alter domestic production economics.
Market Dynamics
RenovaBio credit mechanics are restructuring methanol demand economics in Brazil by linking biofuel blending volumes to tradable carbon credits. This policy architecture is pulling industrial consumers toward certified fuel-grade supply while compressing margins for uncertified imports.
Growth Catalysts
- RenovaBio Program:ANVISA-aligned certification pathways for biofuel-grade methanol create compliance-linked demand pools that reward verified low-carbon production.
- São Paulo Petrochemical Cluster:Formaldehyde and acetic acid producers in this southeastern corridor anchor steady chemical-grade consumption with stringent purity requirements.
- Methanol-to-Hydrogen Pathways:Distributed power developers are piloting fuel cell integrations that position methanol as a hydrogen carrier for off-grid energy systems.
Market Restraints
- Natural Gas Tariff Volatility:Petrobras pricing adjustments for industrial gas feedstock directly compress domestic methanol production margins.
- Import Concentration Risk:Atlantic basin supply dependence exposes Brazilian buyers to freight rate swings and currency mismatch exposure.
- Pharmaceutical-Grade Certification Friction:ANVISA inspection timelines and documentation requirements extend qualification cycles for new supply sources.
Strategic Opportunities
- Northeast Industrial Corridor:Bahia and Pernambuco states host underdeveloped methanol demand from textile and resin manufacturers seeking localized supply.
- Maritime Fuel Blending:IMO 2020 sulfur regulations are opening vessel fuel formulations that incorporate methanol as a marine bunker component.
- Carbon Capture Integration:Biogenic CO₂ capture at sugar-ethanol mills converges with methanol synthesis to produce negative-carbon fuel molecules.
Industry Challenges
- Specialized Process Engineering Talent:Catalyst optimization and reactor design expertise for high-purity methanol production remains concentrated among a limited pool of technical specialists.
- Legacy Terminal Infrastructure:Coastal storage and blending facilities require capital-intensive retrofits to handle simultaneous fuel-grade and chemical-grade segregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Methanol Market |
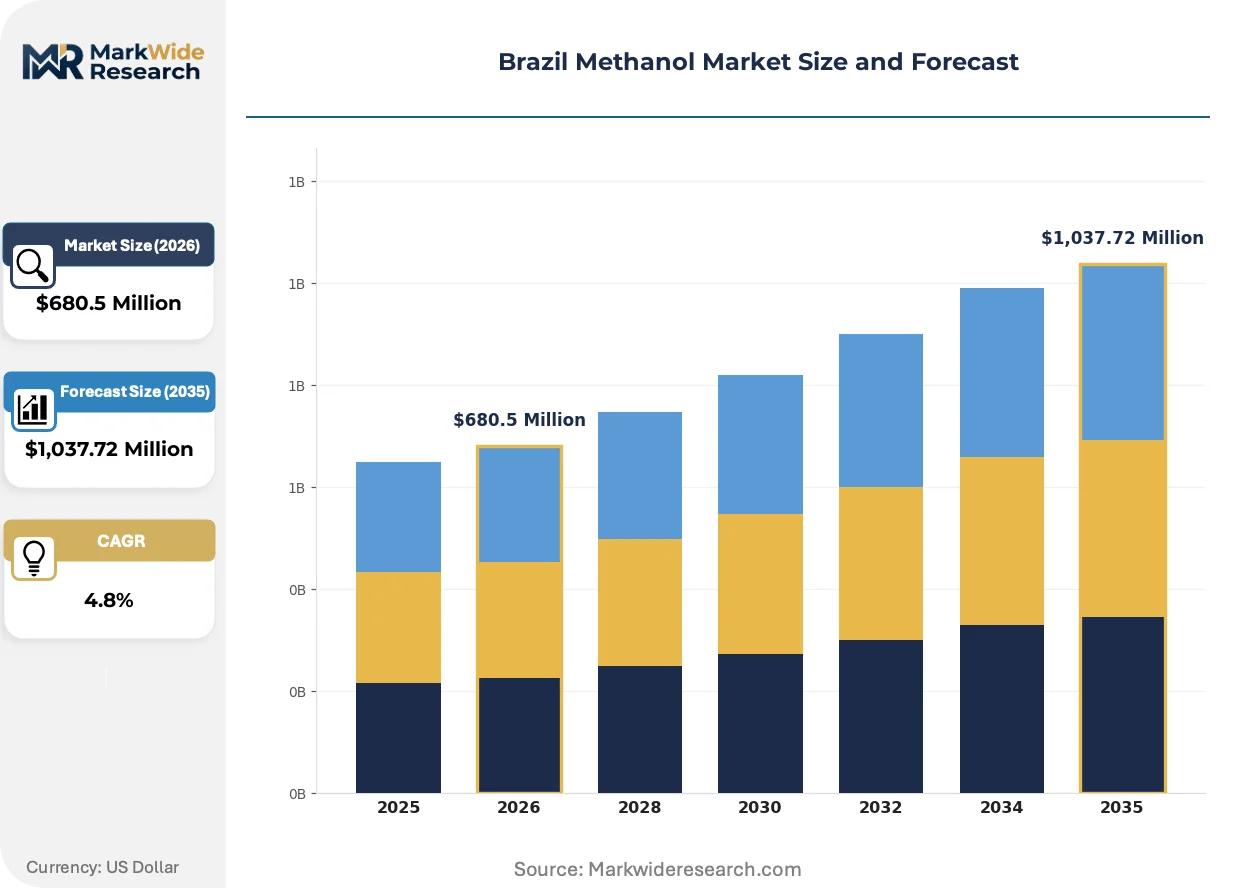
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $1,037.72 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Grade, Chemical Grade, Industrial Grade, Pharmaceutical Grade End User: Automotive, Chemical Industry, Construction, Energy Sector Application: Solvent, Antifreeze, Feedstock, Energy Production Distribution Channel: Direct Sales, Retail, Wholesale, Online Platforms |
| Companies Covered | Methanex Corporation, Saudi Methanol Company, BASF SE, China National Petroleum Corporation, LyondellBasell Industries N.V., Celanese Corporation, OCI N.V., Yara International ASA, Mitsubishi Gas Chemical Company, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Methanol Market Trends and Innovations
Three distinct vectors are restructuring how methanol flows through Brazilian industrial channels. Technology substitution in production pathways, regulatory recalibration of carbon accounting, and buyer-side contracting evolution are each compressing legacy operating models.
Small-scale modular reforming units are overtaking centralized steam methane reforming for distributed hydrogen production. Industrial estates in Minas Gerais are deploying containerized methanol crackers that bypass pipeline gas dependency. This technology is overtaking conventional supply arrangements by enabling on-site fuel generation that sidesteps import logistics and tariff exposure.
ANVISA is tightening trace contaminant thresholds for pharmaceutical-grade methanol to align with USP and EP harmonization initiatives. Laboratory and diagnostic reagent manufacturers face reformulation costs to meet tightened heavy metal and residual solvent specifications. São Paulo-based distributors are consolidating testing capabilities in-house to compress certification turnaround times.
Long-term offtake agreements with fixed-price escalators are displacing spot market procurement among formaldehyde producers. Chemical manufacturers in the ABC Paulista industrial belt are locking in three-to-five-year supply contracts that transfer price volatility risk upstream. This contracting evolution is most visible among acetic acid derivatives producers seeking feedstock cost predictability for export-competitive operations.
Brazil Methanol Market Segmentation
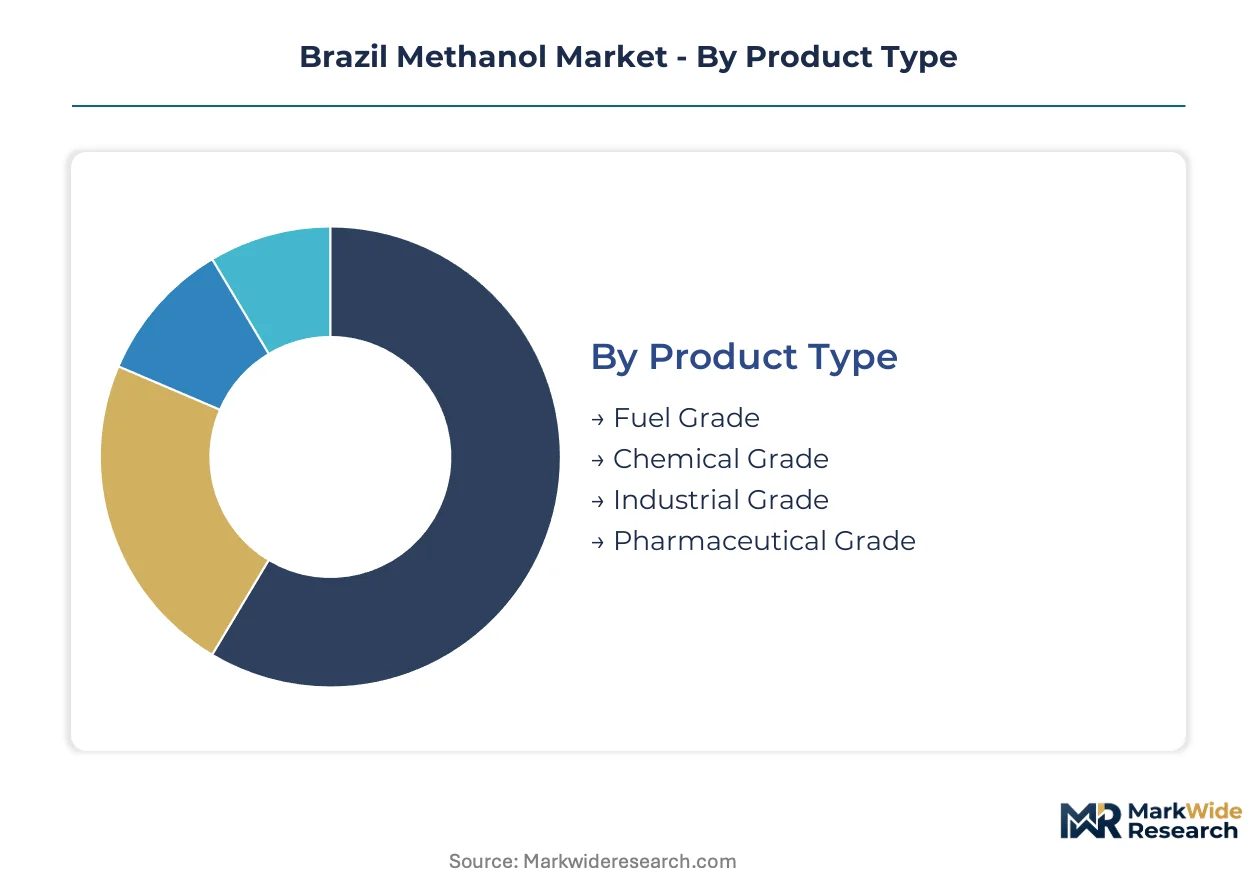
Methanol specifications diverge sharply across Brazilian industrial applications, with ANVISA pharmaceutical standards, RenovaBio fuel certification, and petrochemical purity requirements creating distinct procurement channels. Each segment carries unique margin structures and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Fuel-grade and chemical-grade specifications anchor Brazilian volume flows, while pharmaceutical and industrial grades capture concentrated margin pools through certification barriers.
- Fuel Grade:Specifications center on water content below 0.1% and acidity thresholds compatible with RenovaBio blending mandates. Demand concentrates in São Paulo state's industrial boiler networks and biofuel distributors seeking carbon credit eligibility under ANP regulations.
- Chemical Grade:High-purity methanol with controlled trace contaminant profiles serves formaldehyde and acetic acid synthesis. The São Paulo petrochemical cluster anchors consumption, where Celanese and BASF operations demand consistent feedstock quality for export-competitive derivative production.
- Industrial Grade:Moderate-purity supply for solvent and cleaning applications across textile and metal finishing operations.
- Pharmaceutical Grade:ANVISA-enforced USP/EP alignment with tightened heavy metal and residual solvent specifications for laboratory reagent and diagnostic manufacturing.
Mature deployment sits with Fuel Grade. Newer deployment is concentrated in Pharmaceutical Grade as diagnostic reagent manufacturers face reformulation pressures.
End User:
Customer concentration patterns reflect Brazil's industrial geography, with chemical manufacturing and energy infrastructure driving procurement scale.
- Chemical Industry:Formaldehyde, acetic acid, and methyl methacrylate producers in the ABC Paulista belt consume high-purity feedstock through long-term offtake agreements with fixed-price escalators.
- Energy Sector:Distributed power developers pilot methanol-to-hydrogen fuel cell integrations for off-grid installations in Minas Gerais industrial estates, bypassing pipeline gas dependency through containerized reforming units.
- Automotive:Fleet operators and biofuel blenders purchasing certified supply for RenovaBio credit generation.
- Construction:Resin and adhesive manufacturers in Bahia and Pernambuco seeking localized supply for wood panel and coating applications.
Procurement scale concentrates with Chemical Industry. Procurement velocity is expanding most quickly in Energy Sector distributed generation pilots.
Application:
Functional use cases separate commodity solvent demand from high-value feedstock and emerging energy carrier applications.
- Feedstock:Derivative synthesis for formaldehyde, acetic acid, and methyl tert-butyl ether commands premium pricing tied to export market competitiveness. São Paulo-based producers lock in three-to-five-year supply contracts to transfer price volatility risk upstream.
- Energy Production:Methanol-to-hydrogen pathways and direct fuel cell applications are gaining traction among off-grid power developers seeking alternatives to diesel generation in remote industrial zones.
- Solvent:Paint, coating, and adhesive formulation across automotive and furniture manufacturing.
- Antifreeze:Engine coolant and de-icing formulations for commercial vehicle and aviation ground support equipment.
Contract maturity sits with Feedstock. Technology transition is accelerating fastest in Energy Production as modular reforming units displace centralized supply arrangements.
Distribution Channel:
Channel selection reflects buyer scale, certification requirements, and geographic concentration of demand clusters.
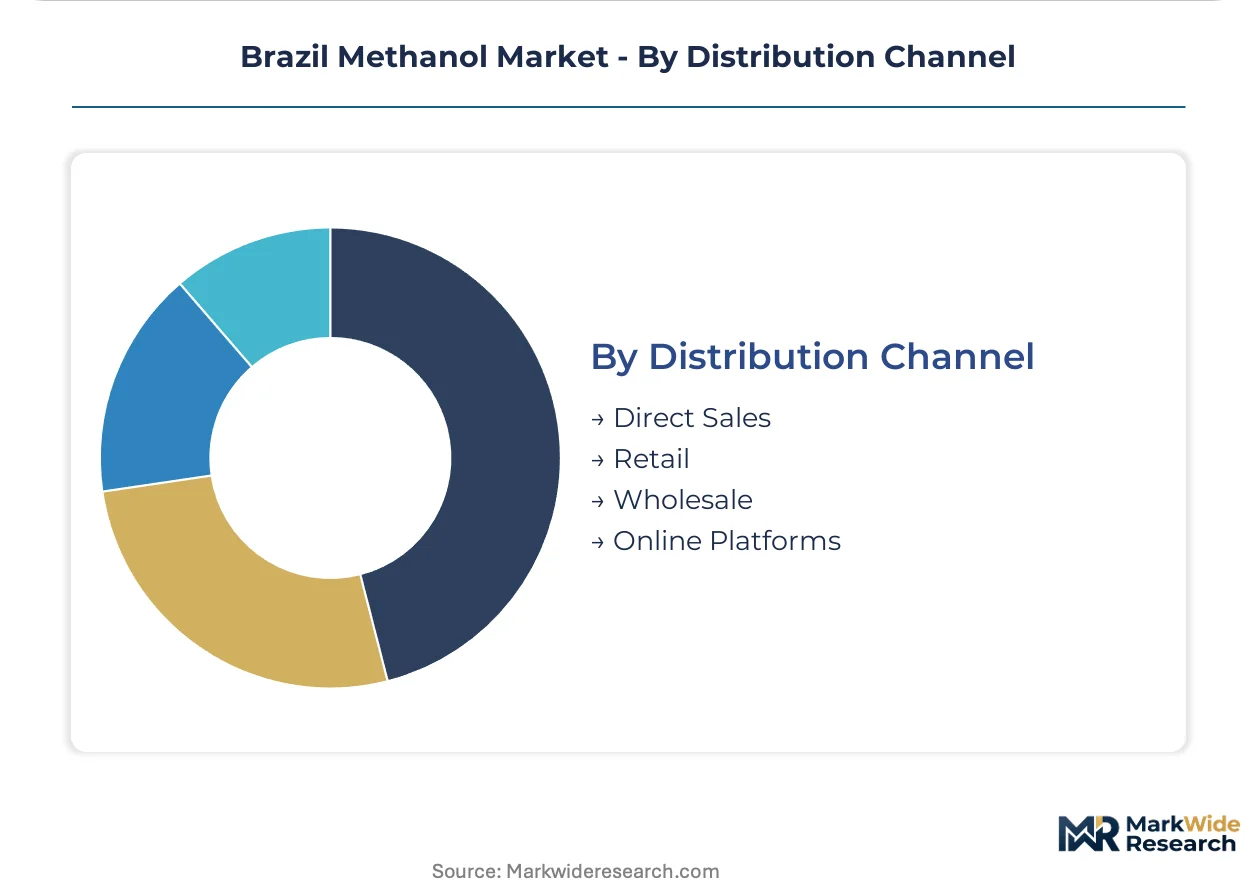
- Direct Sales:Large-volume chemical and energy sector buyers negotiate dedicated supply agreements with integrated producers like Methanex, bypassing intermediary margins for certified fuel-grade and chemical-grade volumes.
- Wholesale:Regional distributors consolidate pharmaceutical-grade and industrial-grade supply for fragmented manufacturing bases in Northeast and Central-West states.
- Retail:Small-volume solvent and antifreeze sales through industrial chemical suppliers.
- Online Platforms:Emerging procurement channel for standardized industrial-grade specifications with documented certificates of analysis.
Volume concentration sits with Direct Sales. Channel development is advancing most rapidly in Online Platforms as remote buyers seek transparent certification documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The São Paulo petrochemical corridor anchors Brazilian methanol consumption, with the ABC Paulista industrial belt hosting formaldehyde and acetic acid synthesis operations that command high-purity feedstock volumes. This southeastern concentration shapes national distribution patterns and pricing benchmarks.
São Paulo
Formaldehyde producers and methyl methacrylate manufacturers in the Cubatão-Santos industrial complex drive chemical-grade procurement through long-term supply contracts. ANVISA pharmaceutical certification requirements pull diagnostic reagent manufacturers toward verified supply sources. The metropolitan port of Santos handles bulk import volumes for both fuel-grade and chemical-grade distribution.
Minas Gerais
Distributed power developers in Belo Horizonte industrial estates pilot containerized methanol-to-hydrogen reforming units for off-grid energy systems. RenovaBio credit mechanics incentivize certified fuel-grade purchases among fleet operators. The state's steel and mining equipment manufacturers consume industrial-grade methanol for solvent and cleaning applications.
Rio Grande do Sul
Leather tanning and textile finishing operations in Porto Alegre and Caxias do Sul generate moderate-purity solvent demand. Petrobras natural gas tariff adjustments directly affect regional production economics for any future methanol synthesis capacity. The state's automotive component suppliers represent emerging chemical-grade consumers for adhesive and coating formulations.
Bahia
Sugar-ethanol mills near Camaçari explore biogenic CO₂ capture integration with methanol synthesis to produce negative-carbon fuel molecules. The Camaçari Petrochemical Complex anchors industrial-grade consumption for resin and coating manufacturers. ANP fuel-specification compliance requirements shape import acceptance criteria for regional distributors.
Rio de Janeiro
Maritime fuel blending operations at the Sepetiba port complex test methanol incorporation into vessel bunker formulations under IMO 2020 sulfur regulations. The state's offshore oil services sector consumes industrial-grade methanol for pipeline maintenance and de-icing applications. Petrobras research facilities evaluate methanol-to-hydrogen pathways for remote platform power generation.
Brazil Methanol Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and purity-tier dimensions, with ANVISA pharmaceutical compliance and RenovaBio fuel certification creating separable margin pools. The market structure concentrates around integrated Atlantic basin producers with dedicated Brazilian distribution infrastructure and specialized chemical-grade distributors serving the São Paulo petrochemical cluster. Three archetypes dominate: integrated global producers with captive shipping logistics, regional distributors with in-house testing and certification capabilities, and specialty chemical companies with backward integration into high-purity feedstock supply. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with players securing long-term offtake agreements to lock in volume commitments.
Within the integrated producer tier, Methanex Corporation and Saudi Methanol Company exemplify scale-driven positioning through Atlantic basin supply route control. BASF SE anchors the specialty chemical archetype, occupying a position that ties distribution to downstream formaldehyde operations. Celanese Corporation represents technology-led differentiation, sitting within the high-purity feedstock segment serving acetic acid derivative production.
| Leading Market Players |
|---|
| Methanex Corporation |
| Saudi Methanol Company |
| BASF SE |
| China National Petroleum Corporation |
| LyondellBasell Industries N.V. |
| Celanese Corporation |
| OCI N.V. |
| Yara International ASA |
| Mitsubishi Gas Chemical Company, Inc. |
| Others |
Pricing and Supply Chain Analysis
Industrial natural gas tariffs from Petrobras cascade through Brazilian methanol production economics, compressing margins for domestic steam methane reforming operations while amplifying the appeal of Atlantic basin import alternatives. This cost component splits the market into three pricing tiers: certified fuel-grade supply commanding RenovaBio-linked premiums, high-purity chemical-grade feedstock tied to formaldehyde and acetic acid yield performance, and uncertified industrial-grade volumes competing on landed cost alone.
Pricing Analysis
Yield-linked value pricing anchors chemical-grade methanol contracts in the São Paulo petrochemical cluster, where formaldehyde producers tie feedstock costs to derivative output quality. Price differentiation separates ANVISA-certified pharmaceutical grades from fuel-grade volumes eligible for RenovaBio carbon credits, with uncertified imports occupying the economy tier. Cost compression in fuel-grade supply is intensifying because RenovaBio credit mechanics reward verified low-carbon production pathways. Fleet operators and biofuel blenders exhibit highest price sensitivity, while acetic acid derivatives manufacturers prioritize purity consistency over unit cost.
Supply Chain Analysis
Specialized catalyst optimization expertise concentrates in the US Gulf Coast, Germany's Ruhr industrial region, and Japan's Chiba chemical corridor, creating workforce bottlenecks for high-purity methanol production scaling. Atlantic basin supply draws from Trinidad, Chile, and US Gulf Coast methanol complexes, with feedstock dependency on regional natural gas pricing and sulfur content specifications. Single-source vulnerability runs through the Santos port complex for bulk chemical-grade imports. Distribution runs through integrated producer direct sales for large-volume buyers and regional distributors with in-house ANVISA testing capabilities for pharmaceutical-grade fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's methanol market functions as a cost-of-compliance arena where ANVISA pharmaceutical certification and RenovaBio fuel-grade verification erect formidable barrier-to-entry moats. Players lacking in-house testing infrastructure or carbon credit eligibility face structural margin compression.
For Market Incumbents: Anticipate RenovaBio credit pricing volatility by locking long-term offtake agreements with fixed-price escalators that transfer carbon market exposure upstream. Defend against modular methanol-to-hydrogen technology substitution by securing exclusive supply relationships with distributed power developers in Minas Gerais industrial estates. Prioritize certification investment in ANVISA-aligned testing capabilities to compress qualification cycles for diagnostic reagent manufacturers. For New Entrants and Emerging Players: Launch via wholesale distribution partnerships targeting pharmaceutical-grade fragmentation in Northeast Brazil's Bahia and Pernambuco states, where textile and resin manufacturers seek localized supply. The most penetrable segment sits with industrial-grade solvent applications in leather tanning and metal finishing operations underserved by chemical-grade-focused incumbents. Pursue a go-to-market angle anchored on documented certificates of analysis delivered through emerging online procurement platforms. For Investors and Strategic Acquirers: RenovaBio credit price floor adjustments are the leading indicator that certified fuel-grade methanol demand will structurally outpace uncertified import volumes. Long-term viability across the projection horizon favors integrated Atlantic basin producers with captive shipping logistics and backward integration into low-carbon feedstock sourcing. Target acquisition archetypes include regional distributors with consolidated in-house ANVISA testing capabilities and exclusive relationships with São Paulo diagnostic reagent manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks volume commitments from Celanese and BASF formaldehyde operations in the ABC Paulista belt. |
| Backward Integration | Captures biogenic CO₂ from Camaçari sugar-ethanol mills for negative-carbon fuel molecule production. |
| Green Certification Program | Secures ANVISA pharmaceutical alignment and RenovaBio carbon credit eligibility simultaneously. |
| Capacity Expansion | Adds modular reforming units in Minas Gerais industrial estates for distributed hydrogen production. |
| Joint Venture | Combines Petrobras natural gas access with foreign catalyst technology for high-purity methanol synthesis. |
Research Methodology
Trade flow databases, ANVISA regulatory filings, and Petrobras natural gas tariff disclosures formed the secondary backbone, cross-referenced with SEC 10-K filings from integrated methanol producers. Primary interviews with plant managers at São Paulo petrochemical complexes, procurement leads at formaldehyde derivatives manufacturers, distribution channel partners in the Northeast corridor, and technical R&D directors at catalyst suppliers validated demand assumptions. Bottom-up and top-down triangulation reconciled volume estimates across grade-tier and end-use dimensions.
Bottom-up modeling built consumption estimates from individual facility throughput and certification requirements, while top-down analysis anchored aggregate demand to national chemical production indices and RenovaBio credit generation data. Segmentation dimensions included product grade tier, end-use industry concentration, and regional production hub economics. CAGRs were derived from regression analysis against industrial natural gas pricing and carbon credit market trajectories. Forecast inputs incorporated catalyst efficiency improvements and modular reforming unit deployment rates.
The model assumes a particular technology adoption path; alternative pathways for methanol-to-hydrogen fuel cell integration would alter the outlook for distributed power applications. Forecasts reflect assumptions about ANVISA inspection timeline stability and Petrobras tariff policy continuity. Regulatory recalibration of RenovaBio credit mechanics, Atlantic basin freight rate volatility, and pharmaceutical-grade certification friction warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Ferric Chloride Market
Chemicals
Resorcinol Market
Chemicals
Sulfuric Acid Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Global Waterproofing Chemicals Market
Chemicals
Calcium Borate Market
Chemicals
United Kingdom Methanol Market
Chemicals
Aromatic Polyamine Market
Chemicals
Global Butanediol Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Selenium Sulfide Market
Chemicals
Antiozonant Market
Chemicals
Diphenylamine (DPA) Market
Chemicals
Naturally Derived Fatty Alcohol Market
Chemicals
Lauryl Dimethyl Amine Oxide Market
Chemicals
P-Ethylphenol Market