
 Global Design Thinking Market | 2026-2036
Global Design Thinking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Design Thinking Market Foresight
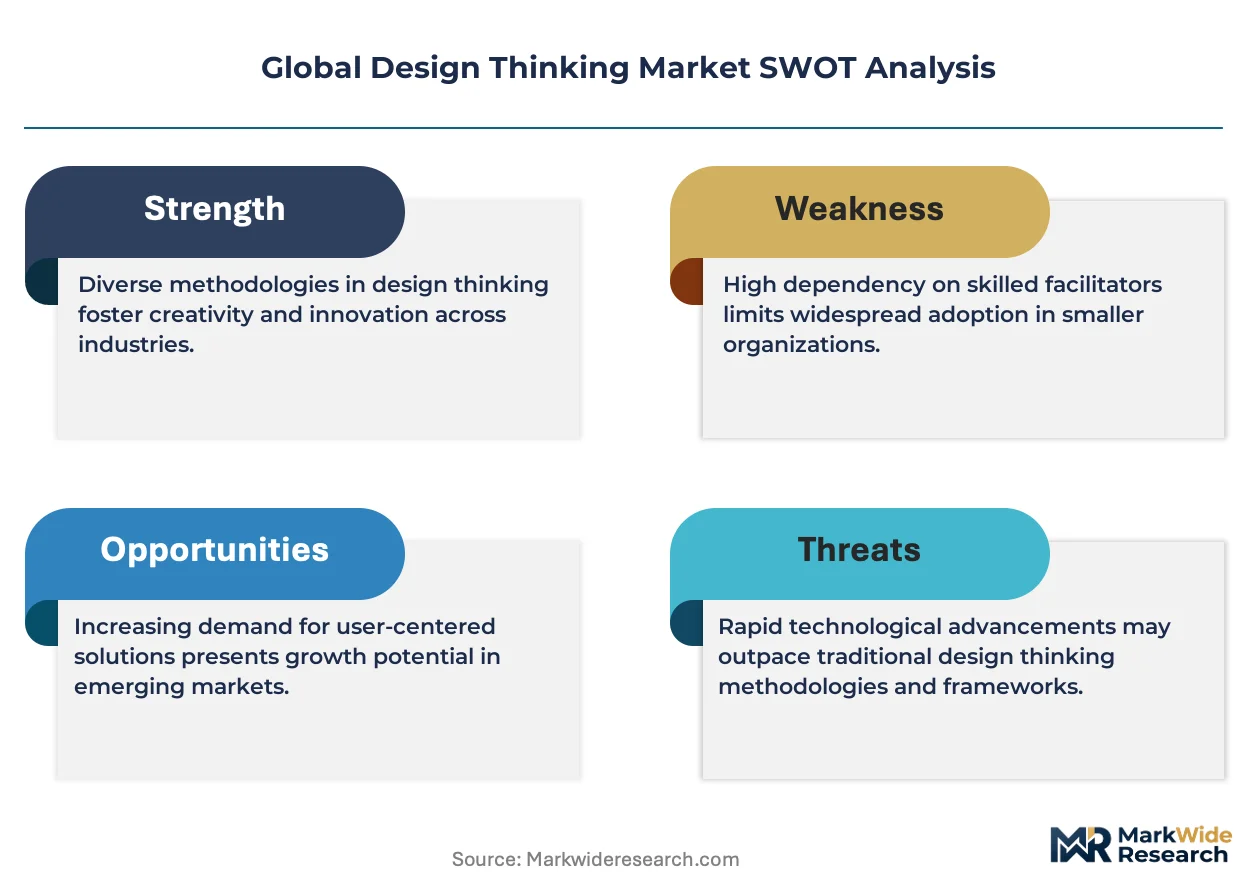
Germany's industrial belt is fragmenting as design thinking capacity spreads beyond traditional creative agencies into manufacturing consultancies and engineering firms. IDEO sustains its early-mover advantage through deep integration with Silicon Valley technology ecosystems and institutional design education partnerships. Accenture leverages its global delivery network to embed design thinking into enterprise digital transformation contracts at scale. IBM competes by combining its Watson AI infrastructure with proprietary design thinking methodologies for data-driven user research.
Design thinking constitutes an iterative problem-solving methodology centered on empathic user research, rapid prototyping, and cross-functional collaboration cycles typically spanning five phases from discovery to testing. The framework employs qualitative ethnographic techniques, low-fidelity mockups, and structured feedback loops to de-risk innovation investments before full-scale production commitment. Cloud-based deployment models are capturing the fastest expansion as distributed teams demand real-time collaboration tools and virtual workshop facilitation platforms. Customer experience solutions occupy the deepest margin pools, while product innovation services face commoditization pressure from template-driven consultancies. Process improvement offerings remain mature in manufacturing verticals but show renewal potential through AI-augmented journey mapping capabilities.
The EU AI Act and GDPR establish mandatory human oversight and transparency requirements that directly shape design thinking demand for ethical framework development and bias mitigation protocols. Germany's KBA and France's CNIL enforce sector-specific accountability standards that elevate design documentation and traceability to contractual prerequisites. ISO standards for human-centered design provide baseline certification pathways that influence procurement criteria across European public sector tenders. Stakeholders must monitor how emerging algorithmic accountability legislation in multiple jurisdictions will redefine the technical competencies and liability structures embedded in design thinking service contracts.
Market Dynamics
The EU AI Act's mandatory human oversight requirements are forcing enterprises to rebuild digital product development workflows around ethical design frameworks, compressing procurement timelines for bias mitigation and transparency documentation services.
Growth Catalysts
- GDPR Article 22:Automated decision-making restrictions in Europe drive demand for human-centered design documentation and algorithmic accountability protocols in financial services and healthcare applications.
- Industry 4.0 integration:German automotive and industrial equipment manufacturers embed design thinking into smart factory transformation programs to accelerate operator workflow optimization.
- Cloud-based collaboration platforms:Distributed engineering teams across US technology clusters adopt virtual whiteboarding and real-time prototyping tools to sustain iteration velocity without physical co-location.
Market Restraints
- Certification timeline compression:ISO 9241-210 human-centered design certification cycles extend 8-14 months, delaying contract eligibility for consultancies serving European public sector tenders.
- Talent concentration risk:Senior design thinking practitioners cluster in San Francisco, London, and Berlin, creating 40-60% cost premiums for engagements requiring on-site facilitation outside these hubs.
- Template commoditization:Low-code journey mapping and persona generation tools displace entry-level design research services, compressing margins for standardized discovery phases.
Strategic Opportunities
- India's PLI scheme:Manufacturing-linked incentives for electronics and automotive sectors create design thinking demand for operator experience transformation in Chennai and Pune industrial corridors.
- AI-augmented research convergence:Synthetic user simulation and generative interview analysis reduce ethnographic fieldwork costs by 30-50% for healthcare and fintech user studies.
- Saudi Vision 2030:Giga-project developments in NEOM and Riyadh mandate human-centered service design for smart city infrastructure and tourism experience platforms.
Industry Challenges
- Legacy system integration friction:Design thinking sprints generate user insights that clash with SAP and Oracle ERP workflow constraints, requiring parallel change management contracts.
- Cross-functional facilitation expertise gap:Practitioners fluent in both technical architecture and behavioral psychology command 2.5x base rates, creating staffing bottlenecks for scaled engagements.
- Intellectual property ambiguity:Co-created prototypes and user research data generate unresolved ownership disputes between client enterprises and design consultancy partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Design Thinking Market |
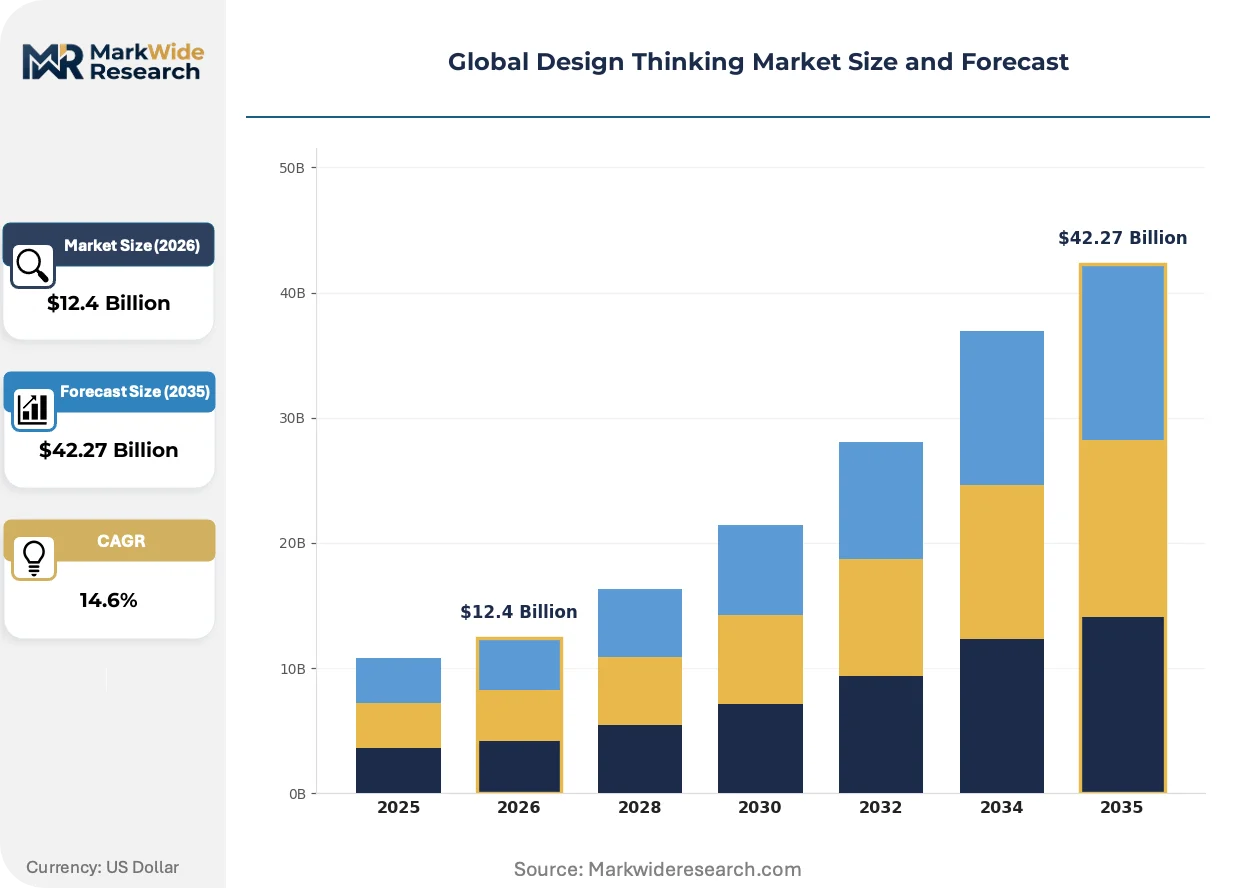
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $42.27 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Offering: Process Improvement, Customer Experience, Product Innovation, Organizational Change, Leadership Development Application: New Product Development, Service Design, User Interface, Market Research, Strategy Planning End User: Startups, Consulting Firms, Technology Providers, Educational Institutions, Nonprofit Organizations |
| Companies Covered | IBM, IDEO, Frog Design, Accenture, Deloitte, Capgemini, Cognizant, Designit, Tendril, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Design Thinking Market Shifts & Advancements
Generative AI capabilities are collapsing traditional research timelines while regulatory pressure rewrites service delivery specifications across European and North American procurement channels.
Real-time synthetic user simulation is rendering obsolete week-long ethnographic field studies for digital product validation. Fintech and healthtech product teams in Singapore and Stockholm now deploy AI-generated persona responses to compress concept testing from fourteen days to forty-eight hours. This compression is eliminating budget line items for travel-intensive qualitative research in favor of continuous virtual feedback loops.
The EU AI Act's risk classification system mandates human oversight documentation for high-risk AI applications including credit scoring and medical diagnostics. Enterprises serving European markets must embed design thinking practitioners into technical teams to build explainability interfaces and bias audit trails. Healthcare providers in France and Germany now require design documentation as contractual deliverables alongside algorithmic performance metrics.
Enterprise procurement of design thinking services is fragmenting from single-source transformation contracts toward modular sprint-based purchasing. Fortune 500 technology and consumer goods buyers in the United States now source discovery, prototyping, and testing phases from separate specialized vendors rather than integrated agencies. This unbundling is most advanced in California's enterprise software cluster, where in-house design operations teams orchestrate external specialist capacity on demand.
Global Design Thinking Market Segmentation
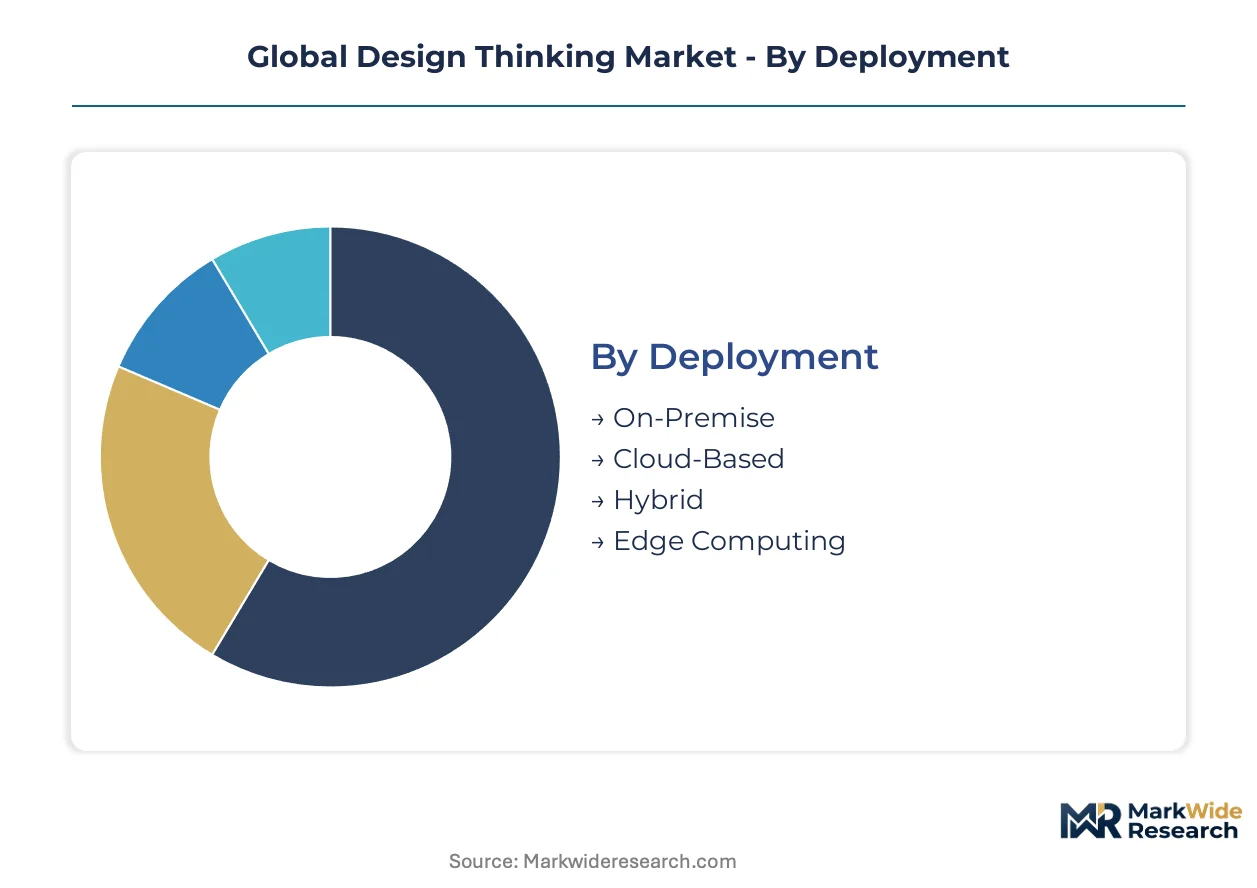
Design thinking procurement patterns diverge sharply by deployment model and buyer sophistication. Solution packaging and application focus determine contract value and renewal rates across enterprise segments.
Deployment:
Cloud-based platforms turn over fastest with quarterly feature releases, while on-premise installations cycle through 18-36 month enterprise agreements.
- Cloud-Based:SaaS delivery enables real-time virtual whiteboarding and distributed sprint facilitation. Healthcare systems in the United States and fintech clusters in Singapore drive demand for browser-native collaboration tools that eliminate infrastructure overhead.
- On-Premise:Air-gapped installations serve defense contractors and financial institutions with data sovereignty requirements. German automotive manufacturers and French healthcare networks mandate local hosting for GDPR-sensitive user research databases.
- Hybrid:Split architectures synchronize sensitive discovery phases on local servers with cloud prototyping tools.
- Edge Computing:Factory-floor deployments support smart manufacturing workflow optimization with sub-50ms latency requirements.
On-Premise anchors the volume base while Cloud-Based gains share at the steepest rate.
Solution Offering:
Customer experience commands premium pricing, while process improvement operates at mature margin structures with renewal-dependent revenue.
- Customer Experience:Journey mapping and service blueprinting for patient pathways and digital banking interfaces. EU AI Act compliance requirements in France and Germany elevate documentation to contractual deliverables alongside design outputs.
- Product Innovation:Rapid prototyping sprints for hardware-software convergence in medical devices and industrial equipment. Template-driven consultancies compress margins for standardized discovery phases.
- Process Improvement:Operator workflow optimization for Industry 4.0 transformation programs.
- Organizational Change:Cross-functional capability building and design ops infrastructure deployment.
- Leadership Development:Executive immersion programs and design thinking certification curricula.
Process Improvement dominates renewal revenue while Customer Experience climbs fastest on compliance-driven procurement.
Application:
New product development absorbs the largest project budgets, though service design contracts multiply faster across public sector and healthcare verticals.
- New Product Development:End-to-end innovation sprints from ethnographic discovery through manufacturing handoff. Medical device manufacturers in Germany and consumer electronics producers in South Korea embed design thinking into stage-gate processes.
- Service Design:Touchpoint orchestration for smart city infrastructure and healthcare patient pathways. Saudi Vision 2030 giga-projects mandate human-centered specifications for NEOM and Riyadh tourism platforms.
- User Interface:Digital product interaction design for mobile and web applications.
- Market Research:Qualitative exploration and synthetic user simulation for concept validation.
- Strategy Planning:Scenario modeling and futures workshops for executive leadership teams.
New Product Development anchors enterprise spending while Service Design expands most quickly on public infrastructure mandates.
End User:
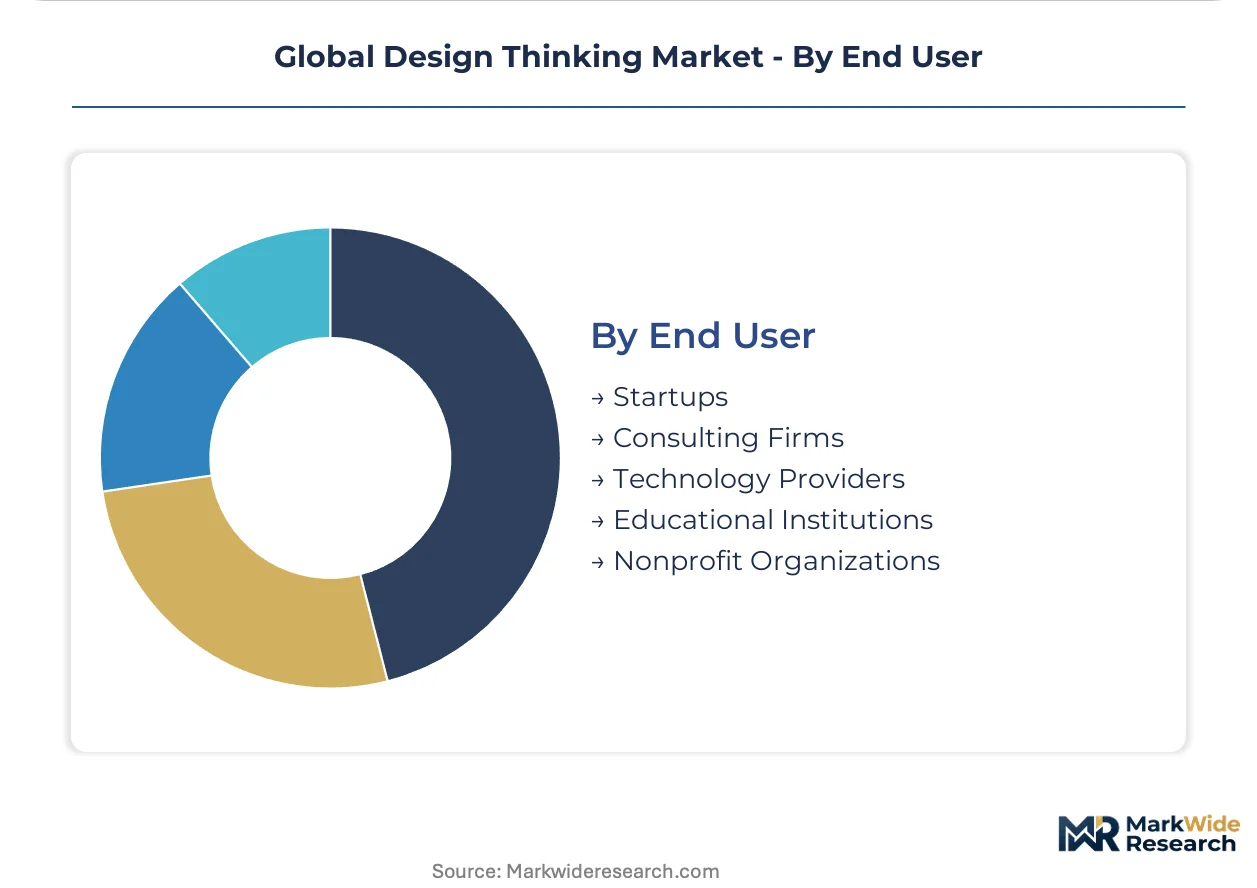
Consulting firms concentrate specialized expertise, whereas technology providers integrate design thinking into captive product development organizations.
- Consulting Firms:Strategy and operations advisors embedding design thinking into transformation contracts. Accenture and McKinsey deploy global delivery networks to serve Fortune 500 digital transformation programs at scale.
- Technology Providers:Enterprise software and hardware vendors building in-house design operations. IBM combines Watson AI infrastructure with proprietary methodologies for data-driven user research.
- Startups:Venture-backed companies purchasing sprint-based capacity without permanent design hires.
- Educational Institutions:Universities and business schools integrating design thinking into curriculum and executive education.
- Nonprofit Organizations:Social sector entities applying human-centered methods to public service delivery challenges.
Consulting Firms anchor external service demand while Technology Providers deepen in-house capabilities fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform integrators cluster in mature technology corridors while component specialists spread across emerging industrial zones. Germany's industrial engineering belt and the United States' enterprise software corridor anchor service delivery capacity. Regulatory complexity in the EU and procurement scale in Asia-Pacific drive geographic expansion strategies.
United States
Healthcare systems and enterprise software vendors drive design thinking procurement for patient experience transformation and digital product development. HIPAA compliance requirements shape documentation protocols for healthtech applications. Silicon Valley technology clusters and Boston's healthcare innovation corridor concentrate practitioner talent and institutional partnerships.
Germany
Automotive and industrial equipment manufacturers embed human-centered methodologies into Industry 4.0 transformation programs. The KBA enforces sector-specific accountability standards that elevate design documentation to contractual prerequisites. Munich and Stuttgart engineering clusters integrate design thinking into smart factory workflow optimization and operator experience design.
France
Healthcare providers and financial services firms procure ethical design frameworks for AI governance and patient pathway redesign. The CNIL mandates algorithmic transparency documentation that compresses procurement timelines for bias mitigation services. Paris-based consulting networks and Lyon healthtech clusters concentrate compliance-oriented design capacity.
India
Electronics and automotive manufacturers under the PLI scheme demand operator experience transformation for new production facilities. RBI guidelines on digital lending transparency shape fintech design documentation requirements. Chennai and Pune industrial corridors attract design thinking capacity for manufacturing-linked incentive programs.
Saudi Arabia
Giga-project developments in NEOM and Riyadh mandate human-centered service design for smart city infrastructure and tourism platforms. SFDA regulations on medical device usability elevate design documentation in healthcare procurement. Riyadh and the Eastern Province concentrate design capacity for Vision 2030 infrastructure delivery.
Global Design Thinking Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in methodology licensing and training delivery. The vendor base separates into three functional layers: global consultancies embedding design thinking into transformation contracts, boutique studios selling sprint-based capacity, and technology vendors building captive design operations. Consolidation pressure concentrates in the middle tier as template-driven tools commoditize standardized discovery phases. Geographic expansion and AI-augmented research capabilities represent the dominant competitive vectors.
Among established methodology originators, IDEO and Frog Design exemplify the boutique studio archetype with deep institutional education partnerships and Silicon Valley technology ecosystem integration. IBM occupies a position combining proprietary design frameworks with Watson AI infrastructure for data-driven user research. These three entities represent contrasting strategic postures: pure-play methodology licensing, technology-augmented service delivery, and captive enterprise product development integration.
| Leading Market Players |
|---|
| IBM |
| IDEO |
| Frog Design |
| Accenture |
| Deloitte |
| Capgemini |
| Cognizant |
| Designit |
| Tendril |
| Others |
Supply & Pricing Matrix
Silicon Valley technology clusters concentrate senior design thinking practitioner talent, anchoring premium service tiers in patient experience transformation and AI governance documentation while compressing margins for template-driven discovery phases delivered through distributed delivery networks.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European procurement channels, elevating human oversight documentation and bias audit trails to contractual deliverables that command premium positioning. Three-tier pricing stratifies across certified enterprise transformation contracts, modular sprint-based engagements, and commoditized template-driven discovery services. Price differentiation rests on ISO 9241-210 certification status and geographic delivery concentration, with on-site facilitation in San Francisco, London, and Berlin carrying 40-60% cost premiums. Cost compression in standardized persona generation and journey mapping is intensifying as low-code tools displace entry-level research services. Technology providers with captive design operations exhibit lowest price sensitivity, while venture-backed startups purchasing sprint-based capacity without permanent hires demonstrate highest sensitivity to per-engagement rates.
Supply Chain Analysis
Accenture, IBM, and Capgemini hold dominant contract-manufacturing capacity for enterprise-scale design thinking delivery, embedding methodologies into digital transformation agreements across Fortune 500 technology and healthcare accounts. Supply concentration spans the United States, Germany, and India, with delivery networks drawing from Chennai and Pune industrial corridors for manufacturing-linked operator experience programs. Raw material dependencies include cloud infrastructure subscriptions, synthetic user simulation platforms, and virtual whiteboarding software licenses. Single-source vulnerability concentrates in senior practitioner availability, with cross-functional talent fluent in both technical architecture and behavioral psychology creating staffing bottlenecks. Distribution runs through direct enterprise sales organizations, channel partner networks, and modular procurement platforms that unbundle discovery, prototyping, and testing phases across specialized vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise technology spending cycles are recovering from prior compression, with healthcare systems and industrial manufacturers renewing deferred patient experience and smart factory transformation programs.
For Market Incumbents: Insulate core enterprise relationships by embedding design thinking practitioners into technical teams for EU AI Act compliance documentation, while acquiring synthetic user simulation capabilities to defend against AI-augmented research commoditization. Deepen certification investment in ISO 9241-210 pathways to maintain eligibility for European public sector tenders. Prioritize backward integration into virtual workshop facilitation platforms to capture cloud-based collaboration growth and reduce third-party software dependency. For New Entrants and Emerging Players: Establish a beachhead in Saudi Vision 2030 giga-project developments, where NEOM and Riyadh infrastructure mandates create greenfield demand for human-centered service design without entrenched incumbent relationships. Target India's PLI scheme manufacturing corridors in Chennai and Pune, where electronics and automotive producers lack embedded design operations. Pursue a channel partnership route with systems integrators serving mid-market healthcare providers in the United States, leveraging HIPAA compliance expertise as a differentiated entry credential. For Investors and Strategic Acquirers: Capital is best deployed toward boutique studios with deep institutional education partnerships and proprietary methodology IP, positioned for consolidation as template-driven tools commoditize the middle tier. Long-term viability favors entities combining ethnographic research heritage with AI-augmented capabilities that compress fieldwork timelines without sacrificing regulatory documentation rigor. Monitor procurement unbundling velocity in California's enterprise software cluster as an inflection indicator for modular sprint-based purchasing adoption across broader Fortune 500 accounts.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Research Capability Acquisition | Synthetic user simulation reduces ethnographic fieldwork costs by 30-50% for healthcare and fintech studies. |
| ISO 9241-210 Certification Investment | Mandatory for European public sector tender eligibility despite 8-14 month timeline compression risks. |
| Cloud-Based Collaboration Platform Integration | Browser-native virtual whiteboarding eliminates infrastructure overhead for distributed healthcare and fintech teams. |
| EU AI Act Compliance Documentation Service Launch | Human oversight and transparency requirements elevate design documentation to contractual deliverables in France and Germany. |
| Geographic Expansion into Saudi Vision 2030 Giga-Projects | NEOM and Riyadh infrastructure mandates create captive demand for human-centered service design specifications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with design thinking program directors at healthcare systems, digital transformation leads at automotive manufacturers, procurement officers at management consultancies, and platform engineers at cloud collaboration vendors. Secondary validation drew from SEC 10-K filings, EU AI Act regulatory documentation, ISO standard certification databases, and hospital procurement records. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from enterprise software and professional services expenditure patterns.
Calibration against historical adoption curves in adjacent professional services categories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution packaging, application focus, and end-user organization type, with additional granularity on regulatory compliance intensity tiers. CAGRs were derived from elasticity-adjusted penetration modeling against addressable digital transformation budgets. Industry-specific forecast inputs incorporated PLI scheme manufacturing incentive timelines and EU AI Act enforcement phase transitions.
Macroeconomic conditions sit as an overlay; deviation in enterprise technology capex cycles and healthcare IT spending would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and practitioner talent supply elasticity. Quarterly review of ISO certification pipeline volumes and virtual collaboration platform adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Australia and New Zealand Digital Transformation Market
Digital Transformation
South Korea Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
Indonesia Digital Transformation Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
Japan Digital Transformation Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Global Network Transformation Market
Digital Transformation
France Digital Transformation Market
Digital Transformation
Digital Transformation in Supply Chain Market