
 Department Stores Market | 2026-2036
Department Stores Market Size, Share, and Industry Trends Forecast 2026-2036
Department Stores Market Intelligence
Flagship real estate in Manhattan and London is shifting toward mixed-use hospitality-retail hybrids as anchor tenants renegotiate lease structures. Macy's Inc. leverages its Herald Square footprint to sustain tourism-dependent revenue streams, while El Corte Inglés anchors Iberian market presence through vertically controlled private-label apparel. Marks & Spencer Group competes on food hall integration, a format that differentiates its British high-street positioning from pure general-merchandise rivals.
A department store operates as a large-scale retail establishment merchandising multiple product categories—typically exceeding ten thousand stock-keeping units—under one roof, with centralized checkout, shared staffing, and coordinated seasonal buying cycles. Clothing and home goods represent mature margin pools where private-label penetration reaches highest levels, while electronics functions as a traffic-building category with compressed profitability. Online sales channels capture the fastest structural expansion, though mobile app integration now determines conversion rates for in-store footfall generated through digital discovery.
Consumer product safety frameworks including REACH in Europe and CPSIA in the United States impose chemical disclosure and testing burdens on textile and children's home goods assortments. The EU Green Deal's extended producer responsibility rules force inventory planning changes, as unsold merchandise carries escalating disposal liability. Stakeholders must monitor how circular economy mandates alter supplier financing terms and markdown risk allocation between retailers and wholesale brand partners.
Market Dynamics
Experiential retail formats are absorbing capital allocation as department stores compete with direct-to-consumer brands for digitally native shoppers. The EU Green Deal's extended producer responsibility rules are forcing inventory model changes that reshape supplier relationships.
Growth Catalysts
- EU Green Deal circular economy mandates:Extended producer responsibility rules create competitive differentiation for retailers with advanced reverse logistics and resale infrastructure.
- Young adult experiential consumption:Digitally native consumers prioritize in-store events and immersive displays over transactional shopping, driving foot traffic to flagship locations.
- Mobile app integration:Unified commerce platforms linking digital discovery to in-store fulfillment are compressing conversion cycles and lifting basket values.
Market Restraints
- Commercial real estate cost structures:Urban flagship rents in Manhattan and London consume disproportionate revenue shares, constraining reinvestment flexibility.
- Electronics category margin compression:Price transparency from online marketplaces eliminates traditional department store markup pools on consumer technology.
- REACH chemical compliance burdens:European textile testing and disclosure requirements add fixed costs to apparel sourcing that squeeze private-label profitability.
Strategic Opportunities
- Suburban mall redevelopment zones:Mixed-use hospitality-retail hybrids in secondary United States metro areas offer lower entry costs than urban flagships.
- Food hall format expansion:Grocery-anchored traffic builders differentiate positioning against pure general-merchandise competitors.
- Resale and rental platform integration:Circular business models align with EU regulatory tailwinds while capturing margin from pre-owned inventory.
Industry Challenges
- Unified commerce talent scarcity:Retailers struggle to hire engineers capable of integrating legacy point-of-sale systems with real-time inventory visibility.
- Markdown risk reallocation:Unsold merchandise disposal liability under circular economy rules complicates supplier financing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Department Stores Market |
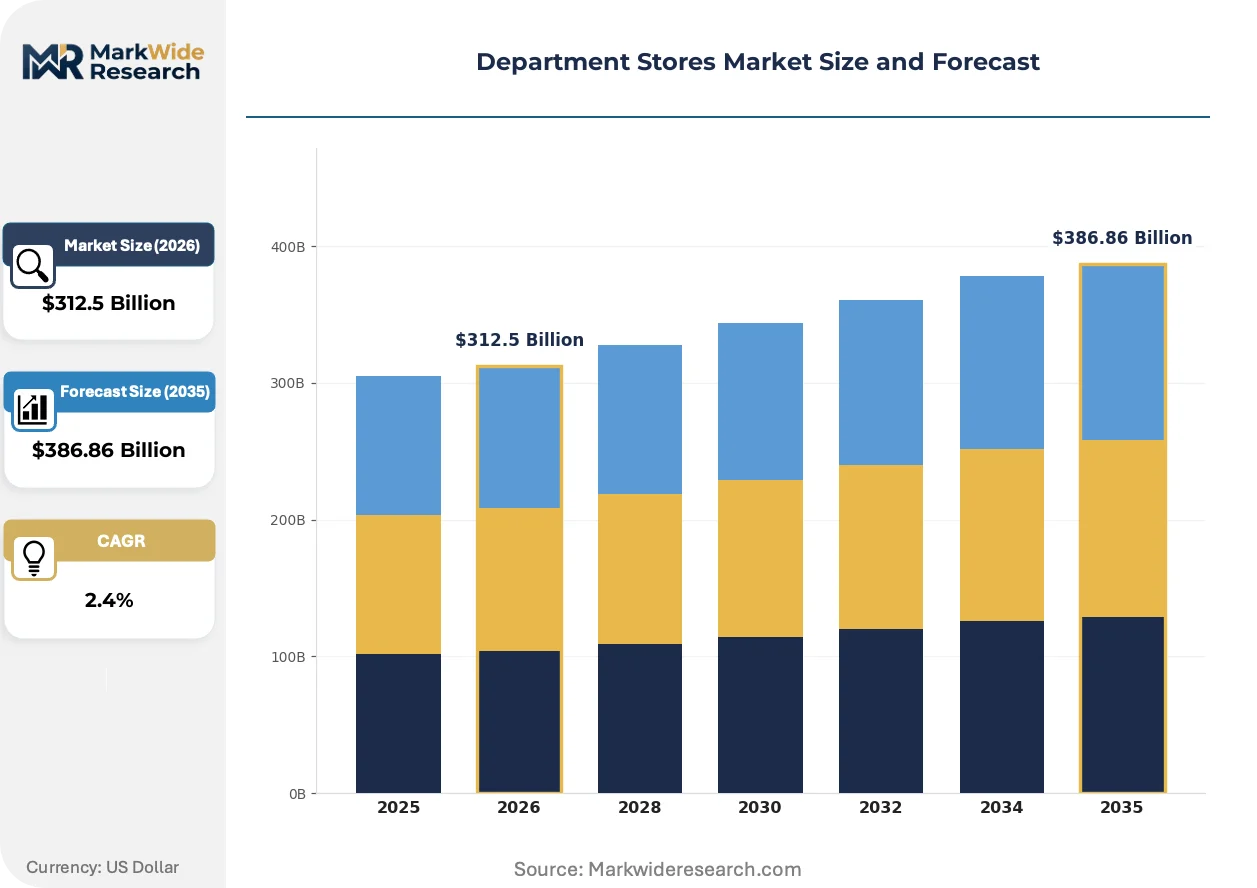
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $386.86 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Footwear, Home Goods, Electronics Customer Type: Families, Young Adults, Seniors, Professionals Brand Positioning: Luxury, Mid-range, Budget, Discount Sales Channel: Online, In-store, Mobile App, Direct Sales |
| Companies Covered | Macy's Inc., El Corte Inglés, Walmart Inc., Aeon Co. Ltd., Marks & Spencer Group, Costco Wholesale Corporation, Nordstrom Inc., Falabella S.A., Target Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Department Stores Market Strategic Shifts & Innovations
Physical retail is absorbing digital-native capabilities that blur discovery, transaction, and fulfillment boundaries. Three forces are restructuring how department stores capture and convert consumer attention.
RFID-enabled inventory tracking is absorbing operational complexity across apparel and home goods floors. Mid-tier chains are deploying item-level tagging to enable buy-online-pickup-in-store and endless-aisle fulfillment. The technology is absorbing labor hours previously dedicated to cycle counts and stock checks, redirecting staff toward clienteling.
REACH chemical disclosure expansions are tightening textile sourcing requirements across European assortments. ECHA is broadening restricted substance lists faster than testing infrastructure can scale. Apparel buyers are responding by consolidating supplier bases to reduce compliance audit burden.
Young adult shoppers are compressing purchase consideration cycles through social media discovery. TikTok and Instagram storefronts are displacing traditional catalog and email channels for trend-driven categories. This behavioral shift concentrates in United States and United Kingdom urban flagships where tourism and local traffic overlap.
Department Stores Market Segmentation
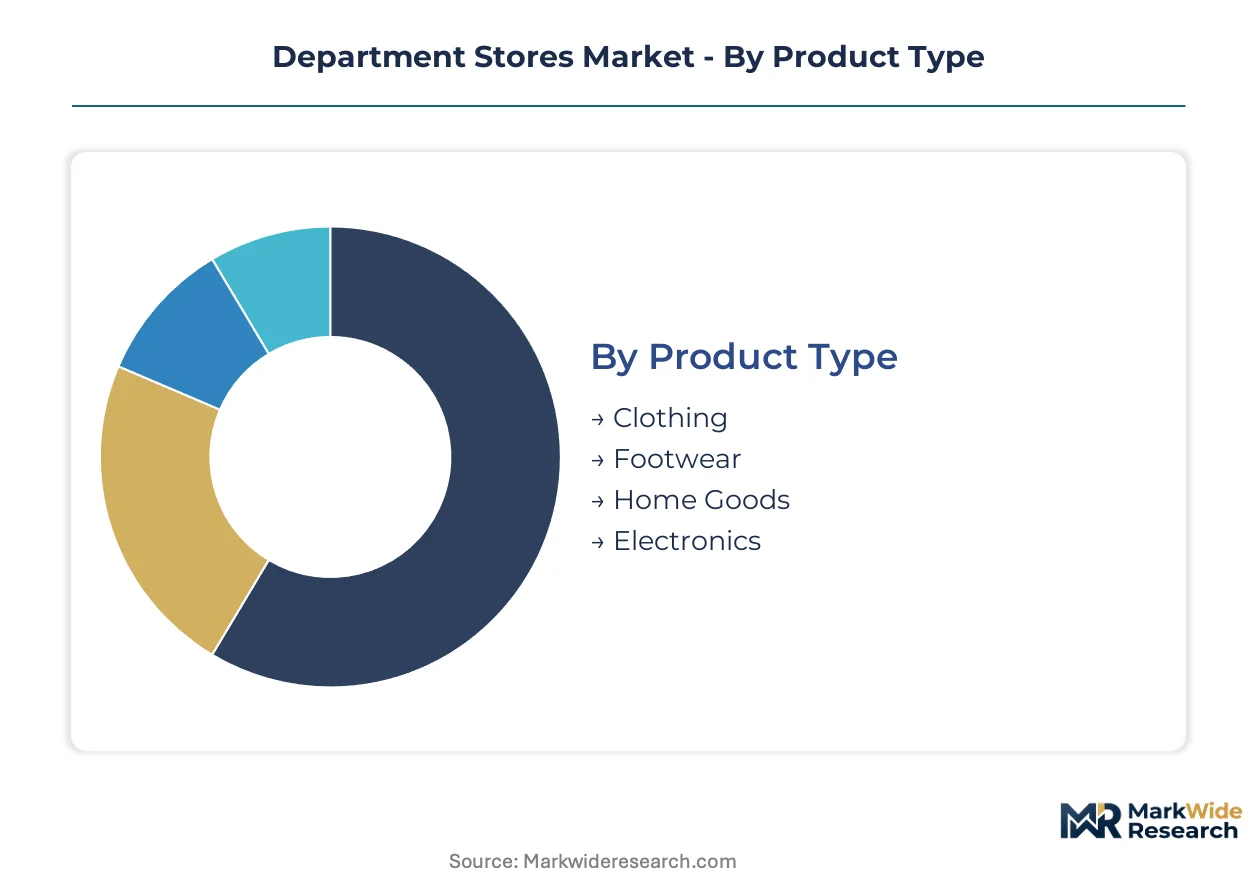
Department stores compete across overlapping demand profiles where product mix, customer life stage, and channel preference determine margin architecture. Segmentation reveals where capital allocation generates sustainable returns versus structural pressure.
Product Type:
Standalone categories operate as destination drivers with independent supply chains, while embedded assortments rely on cross-selling economics to justify floor space.
- Clothing:Private-label penetration reaches maximum depth here, with vertically controlled sourcing enabling margin defense against fast-fashion competitors. Demand concentrates in United States suburban mall redevelopment zones where families seek one-stop wardrobe solutions. REACH chemical disclosure requirements from ECHA compress profitability on European-sourced textiles.
- Home Goods:Soft furnishings and kitchenware generate repeat traffic through seasonal refresh cycles, anchoring suburban location economics. United Kingdom high-street flagships leverage food hall adjacencies to lift home goods basket values. Extended producer responsibility rules under the EU Green Deal impose unsold inventory disposal liability that reshapes buying calendars.
- Footwear:Size-intensive inventory requirements favor chains with advanced RFID-enabled stock visibility.
- Electronics:Price transparency from online marketplaces eliminates traditional markup pools, relegating this category to traffic-building status.
Clothing leads volumes today; home goods is gaining share fastest as circular economy infrastructure matures.
Customer Type:
Margin profiles diverge sharply between transaction-frequency segments and basket-size segments, with acquisition costs determining viable marketing spend.
- Families:Multi-generational purchase authority spreads across apparel, home goods, and electronics in single visits, justifying larger format footprints. United States Midwest and Southern suburban clusters concentrate this demand where department stores anchor regional mall tenancy. Back-to-school and holiday windows capture disproportionate annual revenue.
- Young Adults:Digitally native shoppers compress consideration cycles through TikTok and Instagram discovery, requiring mobile app integration for conversion. Experiential retail formats in Manhattan and London flagships attract this segment through immersive displays and in-store events. Social commerce storefronts displace traditional catalog channels for trend-driven categories.
- Seniors:Service-oriented shopping preferences sustain full-service floor staffing models in established metropolitan locations.
- Professionals:Time-constrained purchasing favors buy-online-pickup-in-store fulfillment with minimal friction.
Families anchor revenue stability; young adults show the steepest expansion trajectory as experiential formats mature.
Brand Positioning:
Price architecture separates segments that compete on scarcity and service from those competing on inventory velocity and operational efficiency.
- Luxury:Concession-based beauty and accessories halls generate fixed rent income with minimal inventory risk, concentrating in Manhattan, London, and Paris flagship corridors. Tourism-dependent revenue streams require hospitality-retail hybrid formats to sustain footfall. Personal shopping services and exclusive access events defend price integrity.
- Mid-range:Private-label apparel penetration peaks here, with vertically controlled sourcing enabling margin capture from brand-conscious but price-sensitive shoppers. Iberian market presence through vertically integrated private-label operations demonstrates format durability. Food hall integration in United Kingdom positioning differentiates against pure general-merchandise rivals.
- Budget:High inventory turnover requirements favor centralized distribution centers with rapid replenishment cycles.
- Discount:Off-price merchandise acquisition depends on opportunistic relationships with wholesale brand partners facing excess inventory.
Mid-range positioning commands the broadest geographic footprint; luxury formats are expanding most quickly through concession model replication.
Sales Channel:
Channel economics reflect capital intensity gradients, with fixed-cost physical infrastructure competing against variable-cost digital fulfillment.
- Online:Unified commerce platforms linking digital discovery to in-store fulfillment compress conversion cycles and lift basket values. Mobile-responsive interfaces determine whether footfall generated through digital discovery converts to transaction. Endless-aisle capabilities extend assortment depth without inventory carrying cost.
- In-store:Flagship urban locations in Manhattan and London absorb disproportionate capital allocation as anchor tenants renegotiate lease structures toward mixed-use hospitality-retail hybrids. Suburban mall redevelopment zones offer lower entry costs with comparable traffic potential. RFID-enabled inventory tracking redirects staff hours from cycle counts toward clienteling.
- Mobile App:Push notification personalization and loyalty program integration drive repeat purchase frequency.
- Direct Sales:Corporate and institutional relationships provide predictable volume with negotiated terms.
In-store retains the largest revenue share; online is climbing the fastest as unified commerce infrastructure deploys.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between the EU Green Deal's circular economy mandates and lighter compliance regimes elsewhere is redirecting capital toward markets with lower extended producer responsibility burdens. Department store operators are reallocating inventory and logistics investment to jurisdictions where reverse logistics infrastructure costs remain manageable.
United States
Suburban mall redevelopment zones in Texas and Florida concentrate new-format investment as experiential retail formats absorb tenant improvement allowances. The FTC's Green Guides enforcement on environmental marketing claims constrains how retailers label private-label sustainability credentials. Manhattan flagship corridors anchor tourism-dependent revenue streams through mixed-use hospitality-retail hybrids at Herald Square and Fifth Avenue.
Germany
REACH chemical disclosure expansions from ECHA tighten textile sourcing requirements for apparel-heavy assortments, compressing private-label profitability. The national packaging law (VerpackG) imposes registration and recycling quota obligations that reshape supplier financing terms. Berlin and Munich flagships serve as circular economy pilot locations where resale platform integration tests consumer acceptance.
United Kingdom
Food hall integration differentiates high-street positioning against pure general-merchandise competitors, driving foot traffic to Oxford Street and regional mall anchors. The UK's extended producer responsibility for packaging regulations phases in reporting obligations that alter markdown risk allocation. London's West End concentrates luxury concession-based beauty and accessories halls generating fixed rent income.
Japan
Aeon Co. Ltd.'s domestic network demonstrates format durability through grocery-anchored traffic builders in Greater Tokyo and Osaka metro areas. METI's resource circulation policy roadmap accelerates retailer investment in reverse logistics infrastructure. Fukuoka and Sapporo regional flagships test RFID-enabled inventory tracking for buy-online-pickup-in-store fulfillment.
Spain
El Corte Inglés anchors Iberian market presence through vertically controlled private-label apparel operations concentrated in Madrid and Barcelona corridors. The national waste framework law transposes EU extended producer responsibility into domestic enforcement mechanisms. Valencia and Seville suburban locations absorb capital allocation as urban flagship rents consume disproportionate revenue shares.
Department Stores Market Key Industry Players
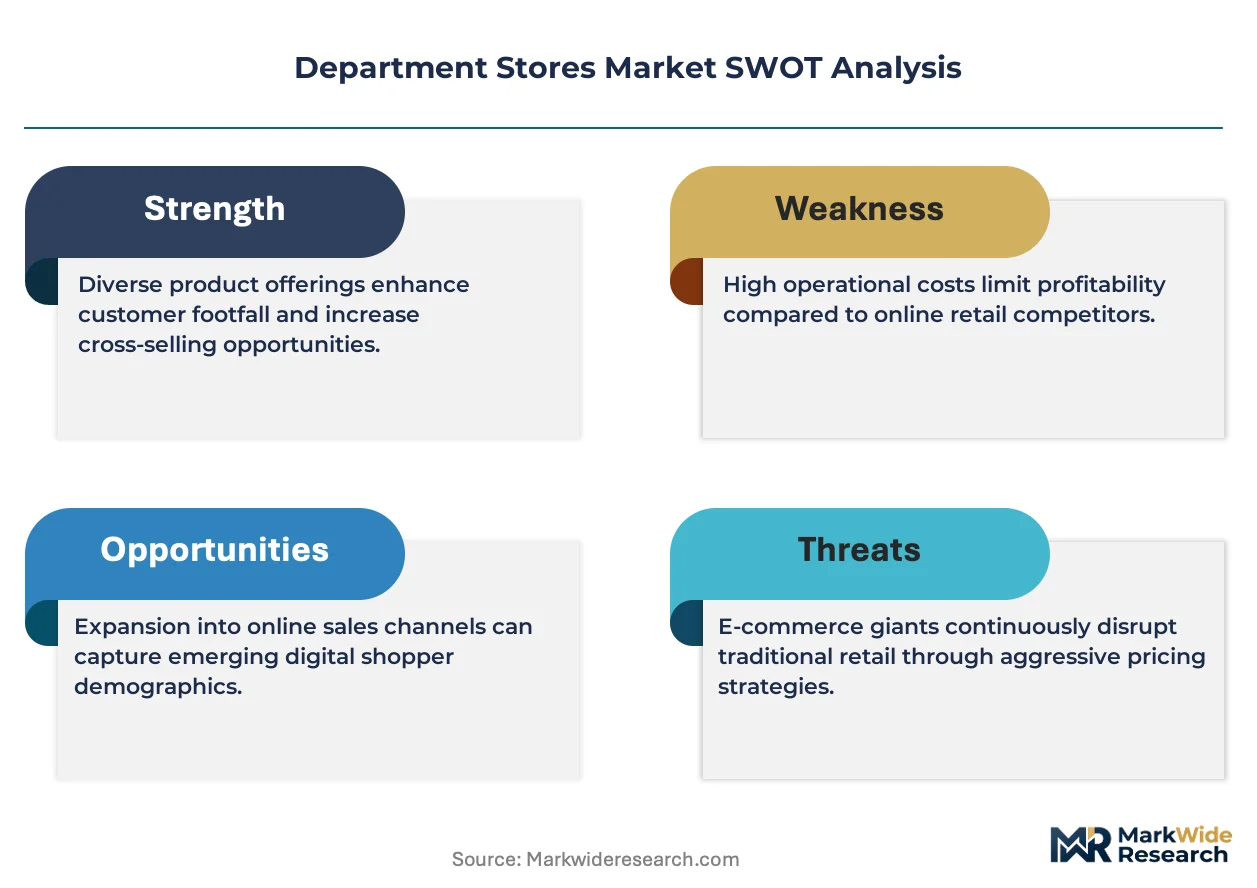
United States operators anchor the scale-driven tier; European specialists hold differentiated positioning through format innovation and private-label depth. Market structure tilts toward consolidated national champions with regional subscale competitors exiting through lease renegotiation or format conversion. Three archetypes dominate: experiential flagship operators, vertically integrated private-label houses, and unified commerce platforms. Competitive moves concentrate on suburban mall redevelopment partnerships and circular economy infrastructure buildout.
Within the vertically integrated tier, El Corte Inglés exemplifies Iberian market control through captive sourcing and format diversification. Macy's Inc. occupies a position as the archetypal tourism-dependent flagship operator with concentrated real estate exposure in Manhattan. Marks & Spencer Group represents food hall integration as a defensive differentiation strategy against pure general-merchandise rivals. These three anchors illustrate how geographic origin and structural choices shape competitive positioning without guaranteeing outcome.
| Leading Market Players |
|---|
| Macy's Inc. |
| El Corte Inglés |
| Walmart Inc. |
| Aeon Co. Ltd. |
| Marks & Spencer Group |
| Costco Wholesale Corporation |
| Nordstrom Inc. |
| Falabella S.A. |
| Target Corporation |
| Others |
Cost & Logistics Intelligence
Textile input costs originating in Bangladesh and Vietnam flow through tiered margin structures that separate luxury concessions from private-label apparel tiers, with REACH compliance burdens in Europe compressing profitability on European-sourced goods relative to Asian supply chains.
Pricing Analysis
Retailer markup layers stratify across premium, standard, and economy tiers, with luxury concession operators capturing fixed rent income while mid-range private-label houses compete on vertically controlled sourcing. Price differentiation rests on brand heritage and after-sales service bundling. Pricing pressure intensifies in electronics categories where online marketplace transparency eliminates traditional markup pools. Young adult shoppers exhibit highest price sensitivity, while family segments prioritize one-stop convenience over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with China-dominant textile finishing and dyeing operations that feed apparel assortments across multiple positioning tiers. Raw material dependencies center on cotton futures, synthetic fiber feedstocks, and RFID chip components. Tariff exposure on finished goods imports from Southeast Asia poses structural risk to margin architecture. Distribution runs through centralized regional distribution centers with rapid replenishment cycles to suburban mall anchors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Department Stores Market functions as a stable compounder where experiential retail investments sustain foot traffic against digital-native competitors, generating predictable cash flows from suburban family segments and tourism-dependent urban flagships.
For Market Incumbents: Acquire resale platform capabilities to capture circular economy margin pools before EU Green Deal disposal liabilities reshape supplier negotiations. Consolidate supplier bases to reduce REACH compliance audit burdens. Redirect capital toward RFID-enabled inventory tracking that redirects labor hours from cycle counts toward clienteling services. For New Entrants and Emerging Players: Launch via food hall-anchored suburban formats in Texas and Florida redevelopment zones where tenant improvement allowances lower entry costs. Target young adult segments through TikTok storefront integration and immersive flagship experiences. Pursue private-label apparel partnerships with vertically controlled Iberian or Asian manufacturers to bypass established wholesale brand gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where subscale regional operators face lease renegotiation cliffs without format conversion capital. Long-term viability favors unified commerce platforms with demonstrated mobile app conversion capabilities. Monitor circular economy infrastructure buildout as the signal indicating which operators can reallocate markdown risk to suppliers under extended producer responsibility rules.| Strategic Initiative | Industry Significance |
|---|---|
| Resale Platform Integration | Captures margin from pre-owned inventory while aligning with EU Green Deal regulatory tailwinds. |
| Food Hall Format Expansion | Differentiates suburban positioning against pure general-merchandise competitors through grocery-anchored traffic. |
| RFID-Enabled Inventory Tracking | Enables buy-online-pickup-in-store fulfillment while redirecting staff hours toward clienteling. |
| Suburban Mall Redevelopment Partnerships | Secures lower entry costs than urban flagships in Texas and Florida metro corridors. |
| Private-Label Sourcing Consolidation | Reduces REACH compliance audit burden across European textile assortments. |
Research Approach
Coverage spans the United States, Germany, the United Kingdom, Japan, and Spain, with primary inputs from each market informing demand calibration. The approach combines interviews with category buyers, supply chain planners, store operations directors, and digital commerce leads with secondary validation from customs records, Nielsen retail audit data, SEC filings, and EU regulatory filings. Bottom-up store-level modeling triangulates against top-down national retail sales aggregates.
Granularity extends to product type, customer life stage, brand positioning tier, and sales channel across the projection horizon. Segment-level CAGRs derive from historical trajectory analysis adjusted for regulatory phase-in schedules and technology adoption curves. Forecast inputs incorporate circular economy infrastructure buildout timelines, mobile app conversion benchmarks, and suburban redevelopment pipeline data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal enforcement or commercial real estate distress in Manhattan and London flagship corridors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Clothing Retail Market
Retailing
Retail Display Racks Market
Retailing
Australia Retail Bags Market
Retailing
European Discount Retail Market
Retailing
North America Retail Vending Machine Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Floor Mat Rental Service Market
Retailing
Furniture Rental Service Market
Retailing
Floor Displays Market
Retailing
Consumer Products and Retail Market
Retailing
In Store Signage Market
Retailing
Global Food and Non-Food Retail Market
Retailing
Subscription Box Market
Retailing
United States Hardware Stores Retail Market
Retailing
Qatar Retail Market
Retailing
Thailand Retail Market