
 Subscription Box Market | 2026-2036
Subscription Box Market Size, Share, and Industry Trends Forecast 2026-2036
Subscription Box Market Intelligence
Single-source fulfillment from captive warehouses is decoupling from multi-node distribution networks across the subscription box industry. Amazon.com Inc. controls end-to-end logistics infrastructure that compresses delivery windows for recurring shipments. Stitch Fix specializes in data-driven apparel curation that reduces return rates through algorithmic matching. BarkBox dominates pet-focused verticals with themed monthly assortments that build predictable replenishment cycles.
A subscription box constitutes a recurring physical delivery service where curated products ship to subscribers at fixed intervals, typically involving automated billing, inventory pre-allocation, and last-mile coordination through postal or courier networks. The primary commercial purpose centers on converting episodic retail purchases into contracted revenue streams while reducing customer acquisition costs through retention mechanics. Food and Beverage subscriptions carry high churn exposure due to perishability constraints and taste variability, whereas Beauty and Personal Care boxes sustain stronger margins through sample-to-full-size conversion pathways. Monthly billing models anchor cash flow predictability, though Annual commitments capture working capital advantages and lower effective cancellation rates.
The US Federal Trade Commission enforces auto-renewal disclosure rules under the Restore Online Shoppers' Confidence Act, compelling transparent cancellation mechanisms that affect subscriber retention engineering. The EU Consumer Rights Directive mandates fourteen-day cooling-off periods for distance contracts, shaping refund liability structures for cross-border European subscription services. California's Automatic Renewal Law imposes explicit consent requirements that filter into national compliance templates. Stakeholders must monitor evolving state-level auto-renewal legislation and platform liability frameworks as regulatory fragmentation intensifies operational complexity.
Market Dynamics
AI-driven personalization engines are absorbing customer data streams to pre-allocate inventory before orders finalize, compressing fulfillment cycles from weeks to days across curated commerce networks.
Growth Catalysts
- Restore Online Shoppers' Confidence Act:The FTC's auto-renewal disclosure mandate forces transparent cancellation flows that paradoxically build subscriber trust and reduce involuntary churn.
- Millennial curation demand:Beauty and personal care subscriptions convert sample-to-full-size pathways into predictable revenue streams with stronger margin retention than episodic retail.
- E-commerce logistics automation:Warehouse robotics and predictive picking systems reduce per-unit handling costs for recurring shipment profiles.
Market Restraints
- Perishability constraints:Food and beverage subscriptions face elevated churn exposure from taste variability and spoilage risk that compresses inventory turns.
- California Automatic Renewal Law:Explicit consent requirements add friction to subscriber acquisition funnels and inflate compliance overhead for national operators.
- Last-mile postal concentration:Dependence on USPS and courier duopolies limits pricing leverage for recurring delivery contracts.
Strategic Opportunities
- Annual commitment structures:Prepaid yearly billing captures working capital advantages and lowers effective cancellation rates versus monthly models.
- Pet vertical expansion:Themed monthly assortments in animal care build predictable replenishment cycles with lower return incidence than apparel.
- EU Consumer Rights Directive adaptation:Fourteen-day cooling-off period compliance creates standardized refund frameworks for cross-border European scaling.
Industry Challenges
- Data science talent scarcity:Algorithmic matching capabilities for curation quality require specialized machine learning expertise that outpaces supply.
- Multi-node inventory coordination:Decoupling from single-source captive warehouses demands real-time visibility across distributed fulfillment networks.
- Platform liability fragmentation:Evolving state-level auto-renewal legislation intensifies operational complexity as regulatory templates diverge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subscription Box Market |
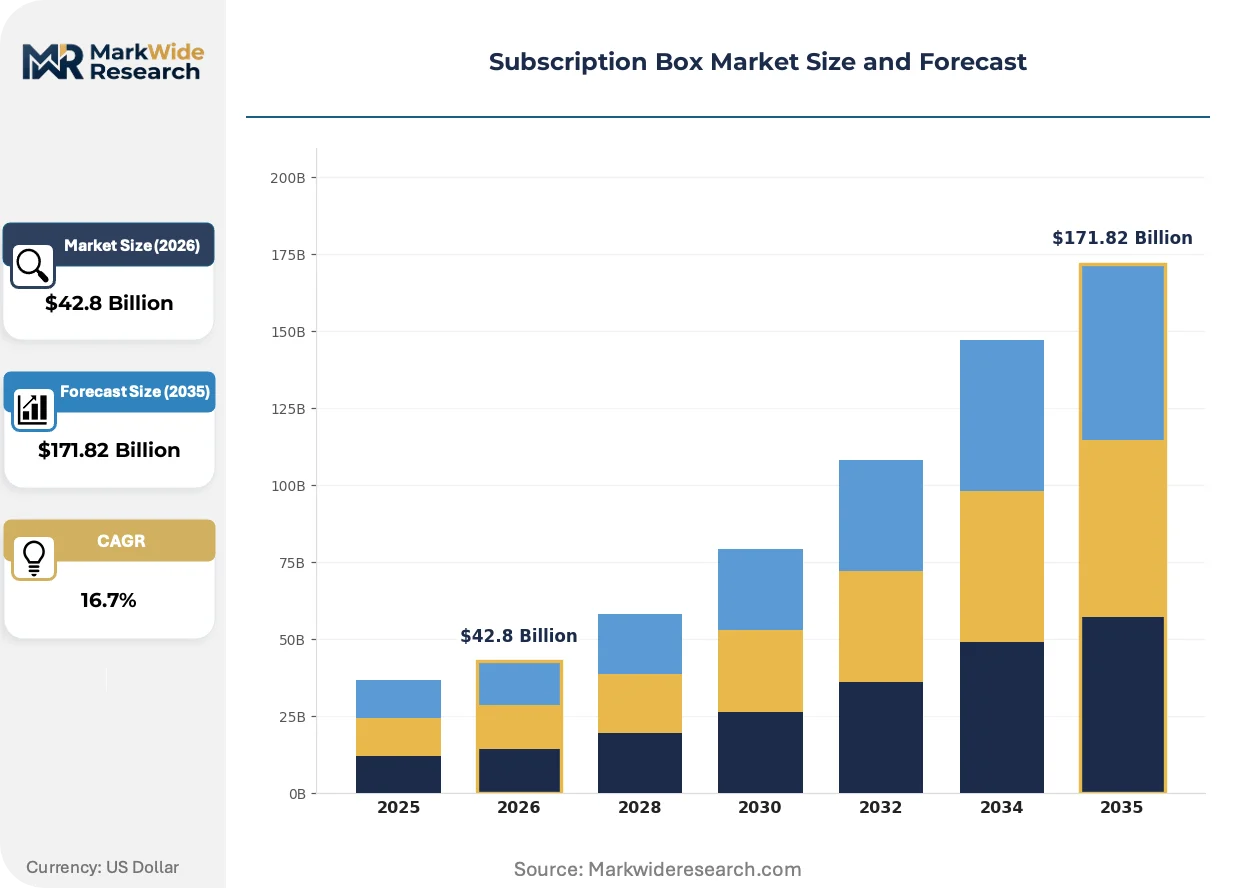
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $171.82 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food & Beverage, Beauty & Personal Care, Clothing & Accessories, Books Subscription Model: Monthly, Quarterly, Annual, One-Time Purchase Target Audience: Families, Young Adults, Students, Professionals Delivery Channel: Direct Mail, Online Marketplace, Retail Store, Subscription Website |
| Companies Covered | Blue Apron Holdings Inc., FabFitFun, Amazon.com Inc., Daily Harvest, Grove Collaborative, BarkBox, Dollar Shave Club, Stitch Fix, Birchbox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subscription Box Market Strategic Shifts & Innovations
Subscription commerce is absorbing predictive analytics into core operations, shifting competitive advantage from product sourcing to anticipatory fulfillment orchestration.
Machine learning recommendation systems are absorbing behavioral signals from browsing history, return patterns, and demographic overlays to curate assortments before subscriber input. Beauty and personal care adopters deploy these tools at scale to reduce sample waste and improve conversion to full-size purchases. The structural consequence is absorbing traditional retail discovery into automated replenishment loops that lock in contracted revenue.
The EU Consumer Rights Directive mandates fourteen-day cooling-off periods that reshape refund liability structures for cross-border subscription services. Operators must maintain dual accounting for recognition timing and cash flow hedging. Beauty verticals with higher margin buffers adapt faster than food categories where perishability compresses restocking windows.
Buyer procurement of subscription services is fragmenting across vertical-specific platforms rather than consolidating through generalist marketplaces. Pet care and wellness categories displace department store discovery with direct-to-consumer thematic boxes. This rotation concentrates in the United States, United Kingdom, and China where mature subscription ecosystems support niche specialization.
Subscription Box Market Segmentation
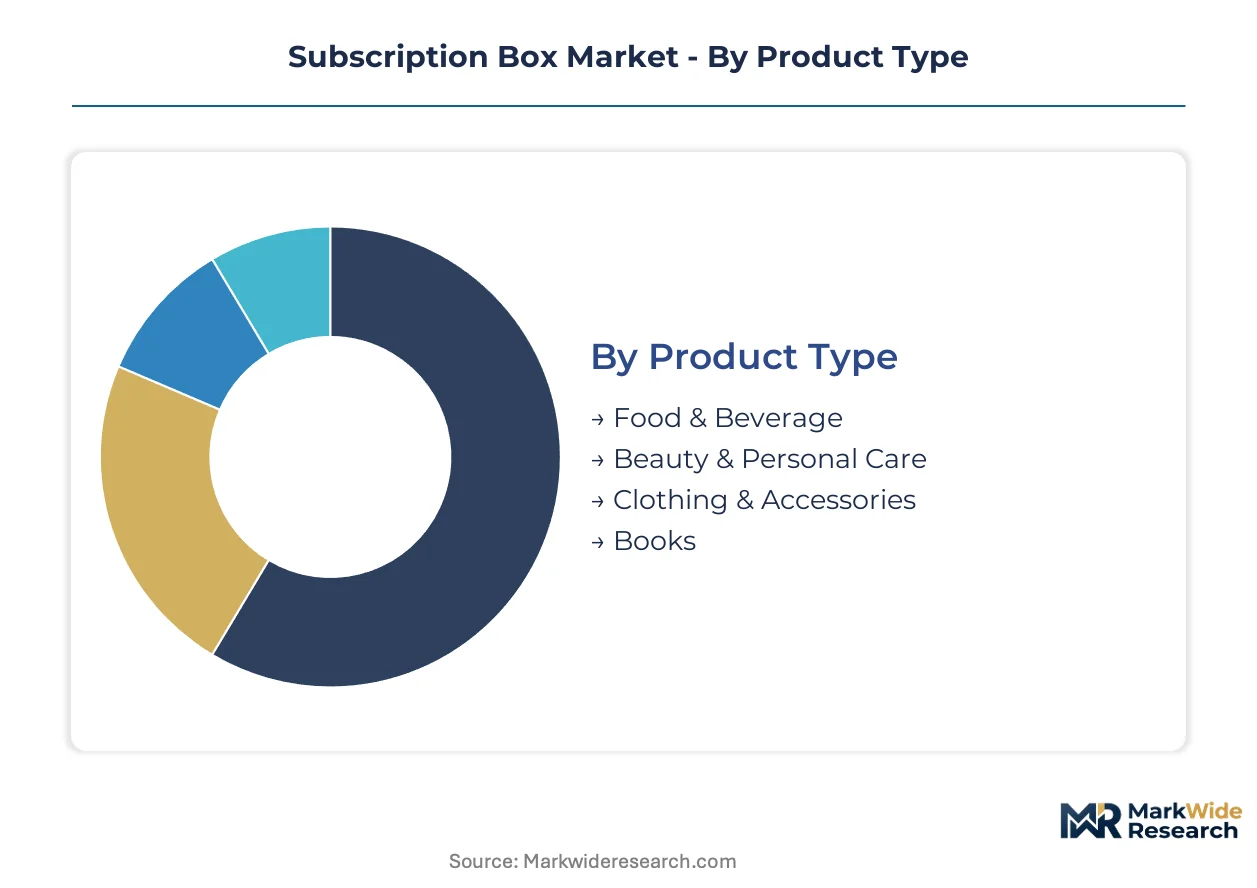
Subscription box operators segment offerings across product verticals, billing cadences, and audience profiles to match inventory pre-allocation with predictable demand signals. Each segmentation dimension carries distinct margin profiles and churn mechanics that shape fulfillment economics.
Product Type:
Buyer loyalty patterns diverge sharply across verticals, with perishability and sampling conversion rates determining lifetime value engineering.
- Food & Beverage:Curated consumable assortments face spoilage risk and taste variability that compress inventory turns. Operators in the United States battle elevated churn from dietary preference shifts and seasonal menu fatigue.
- Beauty & Personal Care:Sample-to-full-size conversion pathways generate contracted revenue streams with stronger margin retention than episodic retail. AI-driven personalization engines pre-allocate inventory based on skin type profiles and purchase history.
- Clothing & Accessories:Apparel curation relies on algorithmic size matching to reduce return incidence, though fit uncertainty sustains higher logistics overhead than non-wearable categories.
- Books:Themed literary selections build predictable replenishment cycles with minimal perishability constraints and lower handling costs per unit shipped.
Beauty & Personal Care leads on scale; Food & Beverage leads on momentum as wellness positioning displaces pure convenience marketing.
Subscription Model:
Billing cadence selection directly shapes working capital capture and cancellation exposure across subscriber cohorts.
- Monthly:Recurring billing anchors cash flow predictability for operators while preserving subscriber flexibility that elevates churn risk relative to longer commitments.
- Quarterly:Seasonal shipment intervals align with apparel refresh cycles and limited-edition product drops, reducing fulfillment frequency overhead.
- Annual:Prepaid yearly commitments capture working capital advantages and lower effective cancellation rates through sunk-cost psychology, though upfront price points filter price-sensitive entrants.
- One-Time Purchase:Gift-oriented or trial boxes convert episodic buyers without subscription commitment, serving as acquisition funnels toward recurring models.
Monthly billing dominates volume; Annual contracts expand most quickly as operators prioritize retention economics over top-line growth.
Target Audience:
Demographic targeting determines curation sophistication requirements and price elasticity boundaries.
- Families:Multi-person household boxes aggregate preferences across age cohorts, demanding broader SKU variety and higher per-shipment value thresholds to justify shipping costs.
- Young Adults:Digital-native subscribers in the United Kingdom and China drive adoption of discovery-oriented boxes with social media unboxing potential.
- Students:Budget-constrained segments favor lower price points and flexible pause mechanisms, compressing operator margins while building brand loyalty for post-graduation upgrade paths.
- Professionals:Time-scarce subscribers prioritize convenience and premium positioning, accepting higher per-box costs for curated efficiency and reduced decision fatigue.
Families anchor revenue scale; Young Adults gain share fastest as social commerce integration deepens.
Delivery Channel:
Channel selection shapes customer acquisition economics and data ownership tradeoffs.
- Direct Mail:Physical catalog and invitation-driven subscriptions retain higher lifetime value in the United States through reduced platform dependency.
- Online Marketplace:Third-party platform listings accelerate discovery but surrender margin to marketplace fees and limit first-party data capture for personalization engines.
- Retail Store:Brick-and-mortar pickup points and in-store subscription signups bridge physical discovery with recurring fulfillment, particularly in China's integrated retail ecosystems.
- Subscription Website:Owned-channel operations maximize data sovereignty and margin retention, requiring dedicated marketing spend to drive traffic against platform competition.
Subscription Website leads on profitability per subscriber; Online Marketplace leads on acquisition velocity.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping subscription box fulfillment footprints as operators migrate toward jurisdictions with streamlined auto-renewal compliance and lower last-mile delivery costs. The United States, China, and United Kingdom concentrate mature subscription ecosystems, while emerging markets attract testing of lighter-weight operational models.
United States
Millennial and Gen Z consumers drive beauty and personal care curation demand across coastal metropolitan corridors. The FTC enforces auto-renewal disclosure rules under the Restore Online Shoppers' Confidence Act, compelling transparent cancellation mechanisms that affect retention engineering. California's Automatic Renewal Law imposes explicit consent requirements that filter into national compliance templates, with Los Angeles and New York City anchoring fulfillment network design.
China
Integrated retail ecosystems in Shanghai and Beijing accelerate subscription adoption through super-app payment integration and social commerce unboxing culture. SAMR oversees consumer protection frameworks that shape cross-border subscription liability structures. The Yangtze River Delta concentrates warehouse automation investments as operators deploy predictive inventory pre-allocation systems.
United Kingdom
Digital-native young adults in London and Manchester embrace discovery-oriented boxes with social media amplification potential. The EU Consumer Rights Directive mandates fourteen-day cooling-off periods for distance contracts, reshaping refund liability frameworks for European scaling. The Southeast England logistics corridor hosts multi-node distribution networks decoupling from single-source captive warehouses.
Germany
Professional demographic segments in Berlin and Munich prioritize convenience-oriented premium positioning with reduced decision fatigue. GDPR compliance requirements impose data governance overhead on personalization engine operations. The Rhine-Ruhr metropolitan region anchors automated fulfillment investments serving cross-border EU subscription flows.
Japan
Time-scarce urban subscribers in Tokyo and Osaka sustain demand for curated efficiency models with high per-box cost tolerance. METI oversees e-commerce standardization initiatives that affect subscription platform interoperability. The Kanto region concentrates last-mile innovation partnerships between operators and courier networks.
Subscription Box Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue vertical specialization and AI-driven personalization differentiation. The market structure stratifies across three tiers: mass-market generalists with captive logistics infrastructure, data-native curation specialists, and niche vertical operators with thematic replenishment expertise. Dominant competitive moves include warehouse automation investments and annual commitment pricing structures that capture working capital advantages.
Within the mass-market infrastructure tier, Amazon.com Inc. and Blue Apron Holdings Inc. exemplify divergent fulfillment economics—one leveraging end-to-end logistics compression, the other navigating perishability constraints in food verticals. Stitch Fix occupies a position among data-native specialists, representing algorithmic matching capabilities that reduce return incidence in apparel curation. BarkBox anchors the niche vertical archetype, sitting within pet-focused thematic assortment strategies that build predictable replenishment cycles with lower churn exposure than consumable categories.
| Leading Market Players |
|---|
| Blue Apron Holdings Inc. |
| FabFitFun |
| Amazon.com Inc. |
| Daily Harvest |
| Grove Collaborative |
| BarkBox |
| Dollar Shave Club |
| Stitch Fix |
| Birchbox |
| Others |
Cost & Logistics Intelligence
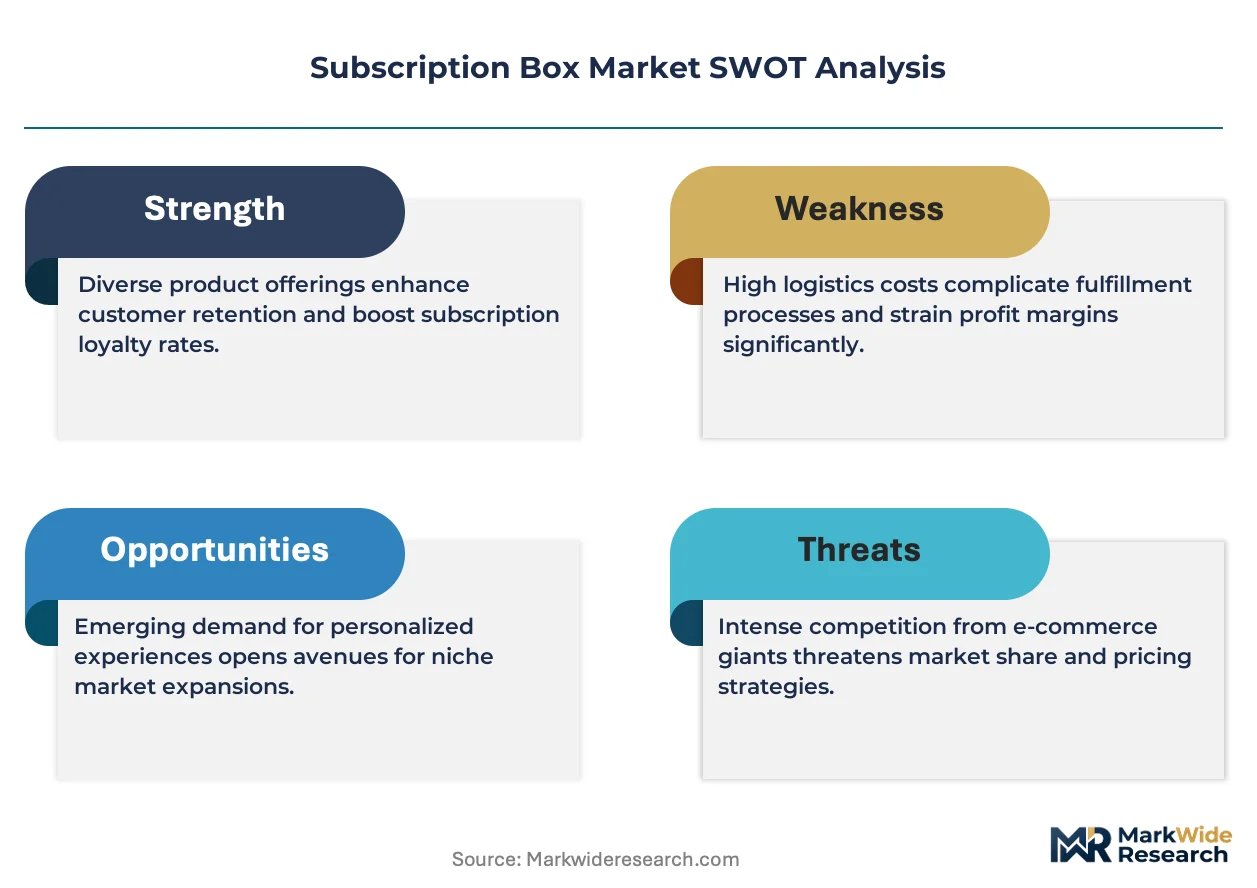
Last-mile postal rates in the United States absorb margin compression before reaching subscriber billing tiers, with USPS and courier duopolies passing fuel surcharges through to monthly box economics. This cost cascade stratifies pricing across premium curation services and economy discovery boxes.
Pricing Analysis
Input-cost pass-through from packaging materials and freight surcharges compresses margins for monthly billing models while annual commitments capture working capital buffers. Three-tier pricing structure across premium, standard, and economy levels separates algorithmic personalization services from basic assortment boxes. Pricing pressure stems from California's Automatic Renewal Law compliance overhead and platform fee inflation. Students and budget-constrained segments exhibit highest price sensitivity; professionals tolerate premium positioning for convenience.
Supply Chain Analysis
Single-source vulnerability sits with China-dependent packaging manufacturers and United States-based last-mile postal networks. Inventory pre-allocation draws from Chinese component suppliers, United States captive warehouses, and United Kingdom multi-node distribution hubs. Raw material dependencies center on corrugated packaging, protective fillers, and thermal insulation for perishable verticals. Tariff exposure on imported packaging materials threatens margin stability. Distribution runs through direct-to-consumer postal injection and courier partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription box economics function as stable compounders where contracted revenue streams and retention mechanics generate predictable cash flows. Recurring billing models anchor this stability against episodic retail volatility.
For Market Incumbents: Hedge against churn acceleration by deepening algorithmic personalization capabilities that reduce sample waste and improve conversion pathways. Acquire specialized machine learning talent before data science scarcity worsens. Extend annual commitment penetration to lock in working capital advantages against monthly billing attrition.
For New Entrants and Emerging Players: Begin with pet vertical thematic assortments where replenishment cycles build lower churn exposure than food categories. Target wellness-positioned consumables in United Kingdom and Chinese markets where social commerce integration accelerates discovery. Deploy direct-to-consumer subscription websites to preserve data sovereignty for personalization engine training.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented niche operators lack warehouse automation scale to match captive logistics infrastructure. Five-to-ten year viability favors data-native curation specialists with algorithmic matching capabilities over pure product sourcing plays. Monitor FTC auto-renewal enforcement intensity as signal for compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Personalization Engine Deployment | Algorithmic inventory pre-allocation compresses fulfillment cycles from weeks to days for curated commerce networks. |
| Annual Commitment Conversion | Prepaid yearly billing captures working capital advantages and lowers effective cancellation rates versus monthly models. |
| Multi-Node Distribution Expansion | Decoupling from single-source captive warehouses demands real-time visibility across distributed fulfillment networks. |
| Vertical Integration into Packaging | In-house production of corrugated materials insulates margin from tariff exposure on imported inputs. |
| Cross-Border EU Scaling | Fourteen-day cooling-off period compliance under EU Consumer Rights Directive creates standardized refund frameworks. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with subscription box operators, warehouse automation vendors, postal logistics managers, and beauty brand procurement leads with secondary validation from SEC filings, USPS rate case dockets, EU regulatory registers, and e-commerce trade association reports. Bottom-up subscriber cohort modeling and top-down market sizing triangulated volume estimates.
Segment-weighting across product verticals, billing cadences, and regional regulatory clusters shaped the analytical framework over the projection horizon. Modeled dimensions included beauty versus food perishability profiles, monthly versus annual commitment structures, and FTC versus EU Consumer Rights Directive compliance boundaries. CAGRs derived from cohort retention curves and inventory turn assumptions specific to curated commerce economics.
Several conditions sit outside the modeled scope, including black-swan regulatory shifts, postal network disruption, and AI personalization capability breakthroughs. Forecasts reflect documented assumptions about subscriber acquisition cost trajectories and churn rate stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Qatar Retail Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Gift Baskets Market
Retailing
Retail Vending Machine Market
Retailing
Singapore Gifting Market
Retailing
Home Shopping Market
Retailing
Australia Retail Bags Market
Retailing
Floor Displays Market
Retailing
Retail Display Racks Market
Retailing
China Retail Market
Retailing
Floor Mat Rental Service Market
Retailing
European Discount Retail Market
Retailing
North America Retail Vending Machine Market
Retailing
Consumer Products and Retail Market
Retailing
Out Store Signage Market
Retailing
Department Stores Market