
 Floor Mat Rental Service Market | 2026-2036
Floor Mat Rental Service Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Mat Rental Service Market Insights
Asset-light leasing and route-based service financing is narrowing the capital barrier for mid-scale operators seeking national coverage. Cintas Corporation leverages its uniform-rental infrastructure to cross-sell mat programs at scale. UniFirst Corporation anchors its competitive stance through integrated facility service bundles that reduce client procurement overhead. Aramark Corporation specializes in healthcare and education verticals where contract duration and compliance documentation carry premium value.
Floor mat rental service encompasses the commercial provision of industrial and institutional matting on a subscription basis, with products engineered from nylon, rubber, vinyl, or polyester substrates to achieve specified coefficient-of-friction ratings and soil-retention capacities; the service model shifts capital burden from buyers to providers while ensuring scheduled sanitization, replacement, and regulatory documentation. Entrance mats command the largest revenue share due to universal deployment across client types, while anti-fatigue mats generate superior margins in manufacturing and healthcare settings where ergonomic litigation risk elevates specification standards. Long-term contracts dominate service-type revenue stability, though on-demand rental is gaining traction among seasonal retail operators seeking inventory flexibility without fixed obligations.
OSHA workplace safety standards, EPA wastewater discharge rules affecting industrial laundering facilities, and state-level building codes in California and New York govern mat performance specifications and service documentation requirements. These frameworks elevate compliance costs for smaller operators while creating certification-based differentiation for established providers. Stakeholders must monitor evolving slip-resistance test protocols and regional water-use restrictions that could reshape laundering economics and route density requirements.
Market Dynamics
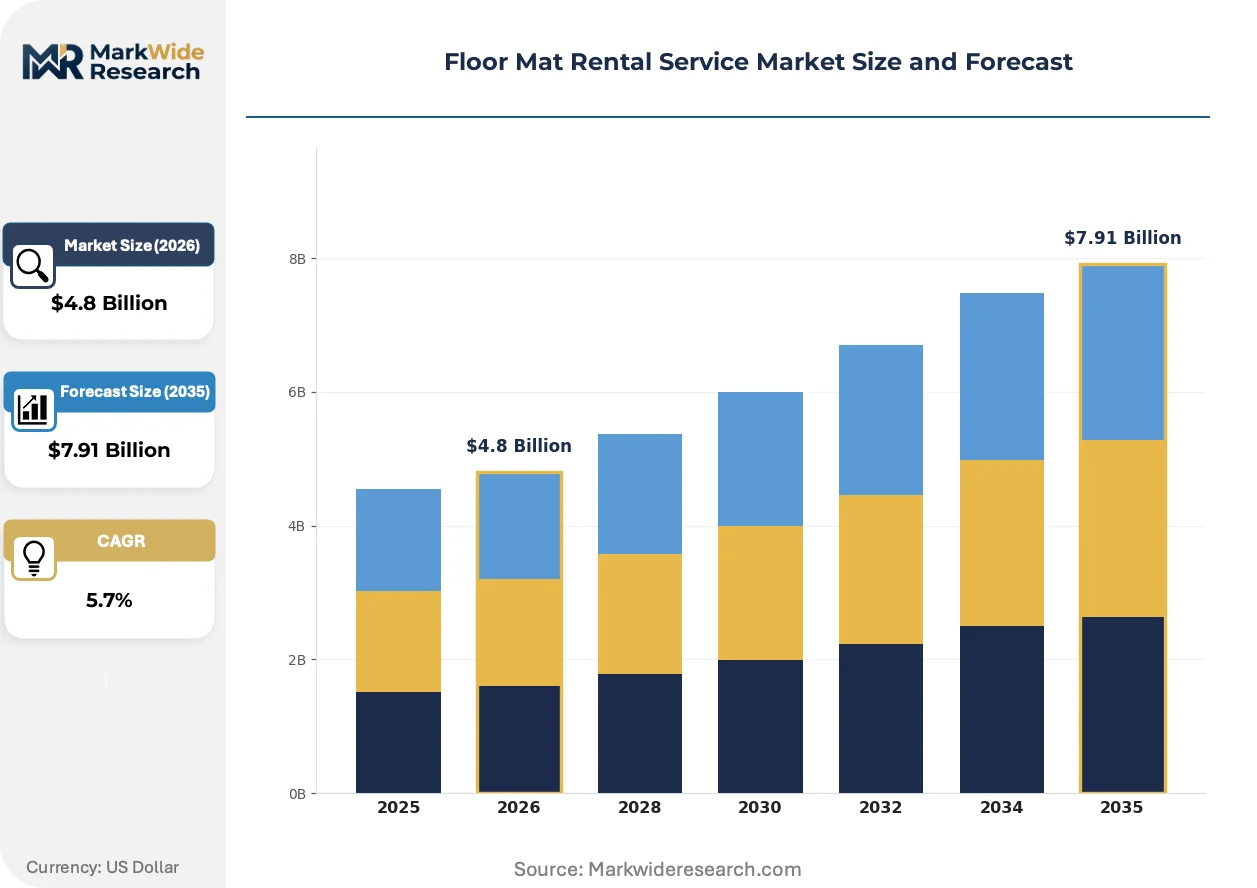
Route density economics and EPA wastewater discharge compliance are compressing margins for small operators while favoring multi-service platforms with captive laundering infrastructure. The capital barrier to national coverage has shifted from fleet acquisition to environmental permitting and compliance documentation systems.
Growth Catalysts
- OSHA slip-resistance mandates:Federal workplace safety standards tighten specification requirements for commercial entrance matting, forcing facility managers toward certified rental programs with documented coefficient-of-friction testing.
- Healthcare construction clusters:Hospital expansions in Texas, California, and Florida accelerate contract uptake as Joint Commission cleanliness protocols require scheduled sanitization with audit trails.
- Polyester substrate advances:New fiber blends improve soil retention capacity while reducing laundering cycle times, lowering per-route service costs for high-frequency replacement schedules.
Market Restraints
- Petroleum-based input volatility:Nylon and rubber mat production remains exposed to crude oil price swings, compressing margin stability for providers without long-term polymer supply agreements.
- Regional laundering concentration:Industrial wash facilities cluster near major metropolitan corridors, creating route inefficiencies for rural and exurban client acquisition.
- Direct purchase substitution:Big-box retail distributors offer low-cost disposable matting that displaces rental subscriptions among price-sensitive small commercial accounts.
Strategic Opportunities
- Seasonal retail on-demand models:Q4 holiday pop-up operators seek inventory flexibility without fixed obligations, creating white space for short-term rental platforms with rapid deployment logistics.
- Anti-fatigue ergonomic specification:Manufacturing and healthcare settings face rising workers' compensation litigation, elevating demand for certified ergonomic matting with documented injury-prevention credentials.
- State-level water reuse incentives:California and New York regulations reward closed-loop laundering systems, offering compliance cost offsets for providers investing in wastewater recycling infrastructure.
Industry Challenges
- Route technician retention:High-frequency pickup and delivery operations require specialized drivers with hazardous materials handling credentials, creating wage pressure in tight labor markets.
- Multi-site client integration:Enterprise accounts demand centralized billing and uniform service standards across dispersed locations, forcing providers to retrofit legacy route management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Mat Rental Service Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Entrance Mats, Logo Mats, Anti-Fatigue Mats, Safety Mats Client Type: Retail Stores, Offices, Hospitals, Educational Institutions Service Type: Monthly Rental, Weekly Rental, On-Demand Rental, Long-Term Contracts Material: Nylon, Rubber, Vinyl, Polyester |
| Companies Covered | Cintas Corporation, UniFirst Corporation, Aramark Corporation, Alsco Inc., Vestis Corporation, Crown Matting Technologies, Milliken & Company, Lindström, Walk-On Dust Control, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Mat Rental Service Market Trends and Innovations
Digital tracking systems and sensor-enabled matting are compressing service intervals while regulatory documentation requirements reshape competitive differentiation around compliance automation rather than price alone.
RFID-embedded matting is digitizing inventory tracking and soil-load monitoring across rental fleets. Healthcare systems and large retail chains deploy these tagged products to automate replacement triggers and generate audit-ready usage documentation. The technology is digitizing route optimization by feeding real-time wear data directly into logistics planning systems, reducing unnecessary service calls.
EPA wastewater discharge rules for industrial laundering facilities tighten effluent monitoring and reporting obligations. These standards elevate capital requirements for wash facility upgrades while creating certification-based barriers for undercapitalized regional operators. Smaller providers face facility consolidation pressure as compliance costs outpace route revenue in low-density service territories.
Facility managers increasingly bundle mat rental within integrated workplace service contracts rather than procuring standalone programs. This purchasing consolidation favors multi-service vendors with uniform, hygiene, and floor care capabilities under single-source agreements. The shift is most pronounced among hospital systems and national retail chains seeking procurement overhead reduction through vendor consolidation.
Floor Mat Rental Service Market Segmentation
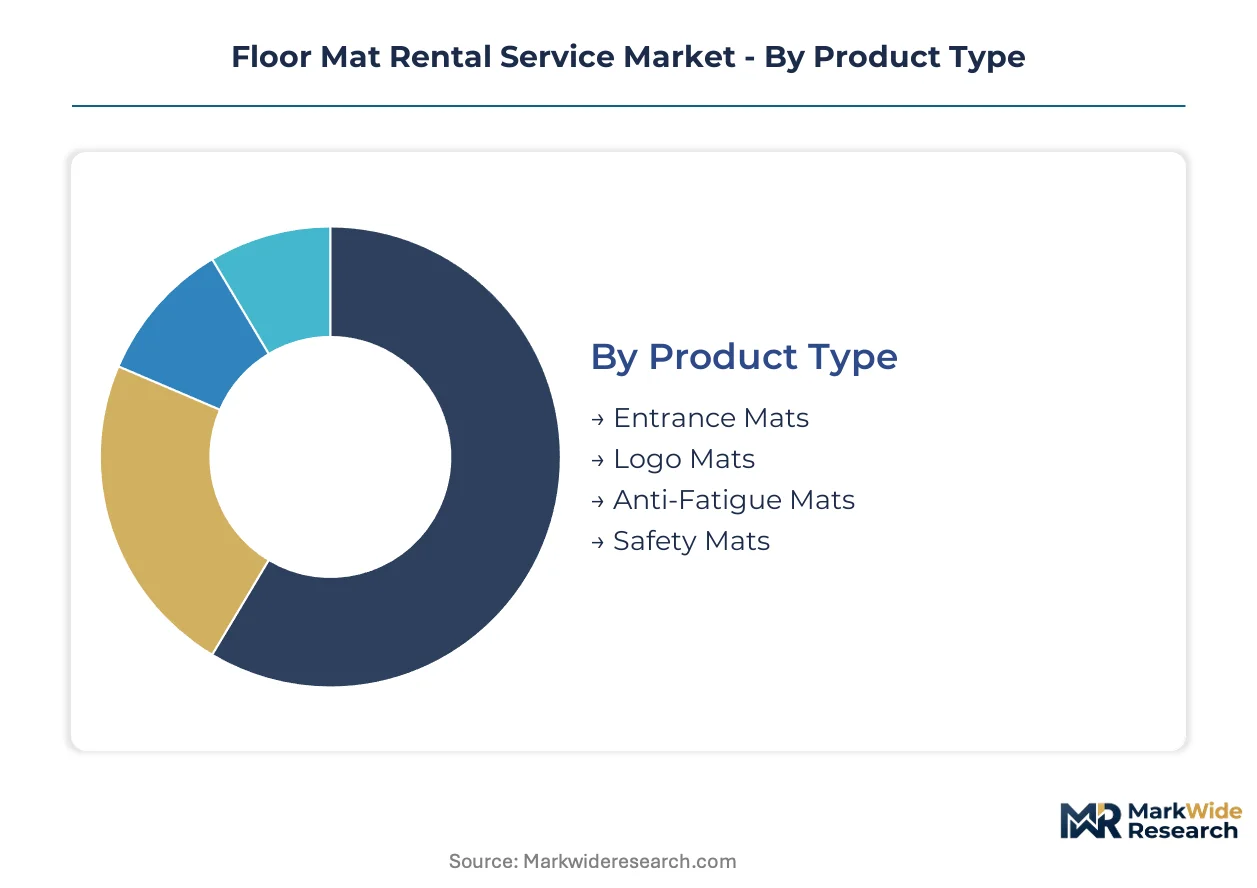
Floor mat rental service segmentation reveals distinct margin profiles and compliance requirements across substrate technologies and client procurement patterns. Understanding these dimensions helps providers align route density investments with the highest-yield contract structures.
Product Type:
Application-specific performance specifications differentiate mat categories by coefficient-of-friction ratings, soil-retention capacity, and ergonomic certification requirements.
- Entrance Mats:Engineered from nylon or polyester blends with high-density pile construction to trap moisture and particulate at facility thresholds. Demand concentrates in retail and healthcare settings across Texas, California, and Florida where high foot traffic and Joint Commission protocols mandate scheduled replacement with documented sanitization trails.
- Anti-Fatigue Mats:Constructed from closed-cell rubber or vinyl composites with graduated density layers to reduce musculoskeletal strain during prolonged standing. Manufacturing facilities and hospital surgical suites in OSHA-regulated environments drive specification, with workers' compensation litigation risk elevating demand for certified ergonomic documentation.
- Logo Mats:Custom-printed nylon or polyester surface bonded to rubber backing for brand visibility at entry points. Corporate headquarters and retail chains deploy these for customer experience differentiation.
- Safety Mats:High-visibility rubber or vinyl formulations with textured surfaces for wet-area slip prevention. Industrial kitchens and food processing plants specify these for compliance with workplace safety mandates.
Entrance mats command the established base. The steepest expansion runs through anti-fatigue ergonomic specification.
Client Type:
Customer procurement scale and compliance documentation intensity shape service margin structures and contract duration patterns.
- Hospitals:Multi-facility health systems require audit-ready sanitization documentation under Joint Commission protocols, with scheduled replacement cycles tied to infection control budgets. California, Texas, and Florida hospital expansions accelerate contract uptake.
- Retail Stores:National chains seek centralized billing and uniform service standards across dispersed locations, favoring providers with integrated facility service capabilities and route density in metropolitan corridors.
- Offices:Corporate campuses prioritize entrance aesthetics and seasonal flexibility, with procurement consolidating into multi-service vendor relationships.
- Educational Institutions:Universities and K-12 districts balance budget constraints with liability concerns, often extending contract terms to secure volume pricing.
Hospitals anchor premium pricing through compliance documentation requirements. Retail chains are climbing the fastest as procurement consolidation accelerates.
Service Type:
Contract duration and replacement frequency determine provider working capital intensity and route optimization economics.
- Long-Term Contracts:Multi-year agreements with fixed replacement schedules generate predictable revenue streams and maximize route density efficiency. Healthcare systems and national retail chains favor these for budget certainty and vendor relationship consolidation.
- Monthly Rental:Standard replacement cycles align with commercial facility maintenance budgets, representing the mainstream service tier across offices and educational institutions.
- On-Demand Rental:Flexible deployment without fixed obligations serves seasonal retail operators and event-driven facilities seeking inventory agility. Q4 holiday pop-up demand is expanding this segment.
- Weekly Rental:High-frequency service for contamination-critical environments including hospital surgical suites and food processing clean rooms.
Long-term contracts lock in the revenue base. On-demand rental is gaining share fastest among seasonal operators.
Material:
Substrate selection governs laundering economics, slip-resistance certification, and exposure to petroleum-based input volatility.
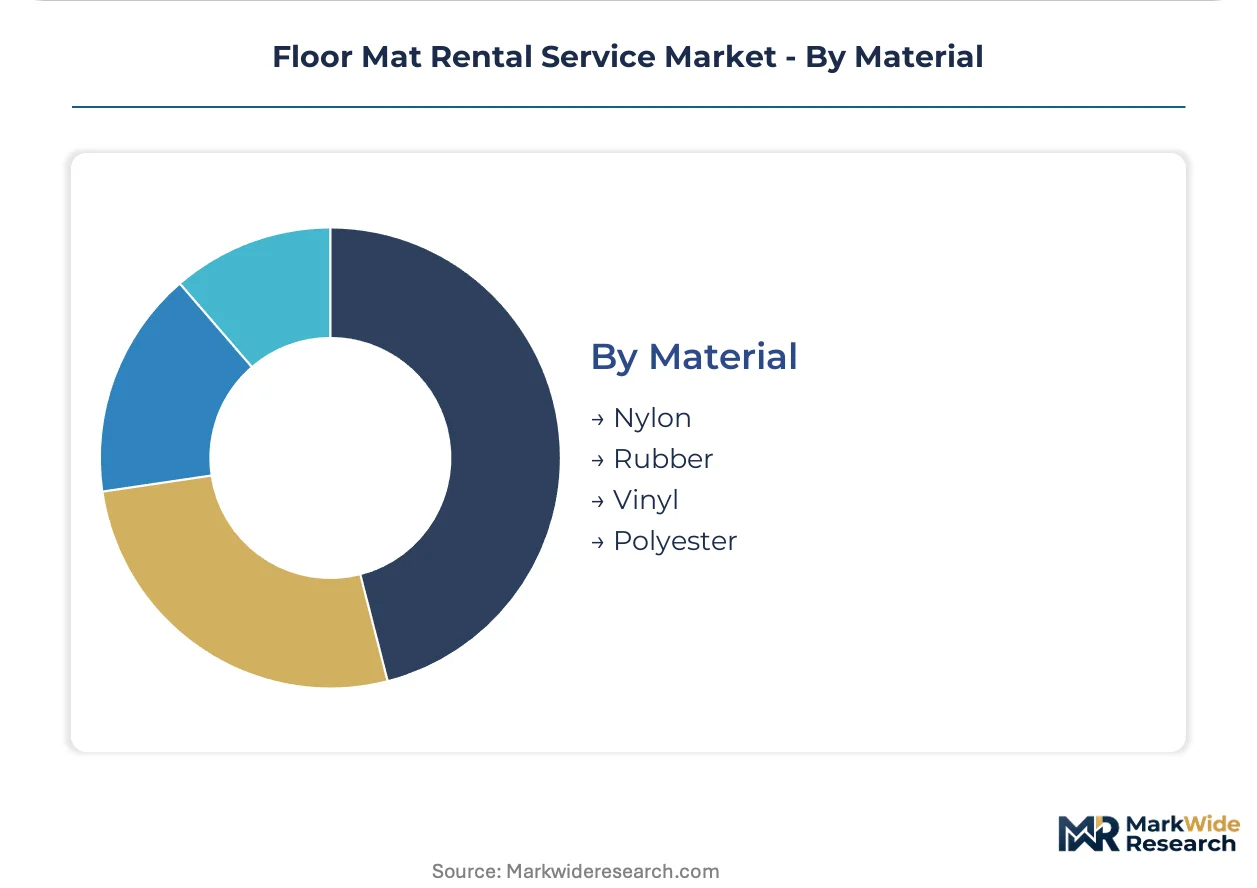
- Nylon:High-durability synthetic fiber with superior soil retention and rapid drying characteristics. Entrance and logo mat applications dominate, though crude oil price exposure compresses margin stability without long-term polymer supply agreements.
- Polyester:Advanced fiber blends improve soil retention capacity while reducing laundering cycle times, lowering per-route service costs for high-frequency replacement schedules in healthcare and retail settings.
- Rubber:Natural and synthetic rubber compounds deliver slip resistance and ergonomic cushioning for safety and anti-fatigue applications. Petroleum price volatility creates input cost pressure.
- Vinyl:PVC-based formulations offer chemical resistance and ease of sanitization for industrial and food service environments. EPA wastewater discharge rules elevate compliance costs for laundering facilities processing vinyl substrates.
Nylon holds the established volume position. Polyester is climbing the fastest on laundering efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA slip-resistance mandates and state-level water reuse incentives are reshaping service economics across major economies, with facility managers prioritizing certified rental programs that bundle compliance documentation with scheduled maintenance.
United States
Hospital construction clusters in Texas, California, and Florida are accelerating contract uptake as Joint Commission cleanliness protocols require audit-ready sanitization trails. OSHA workplace safety standards tighten specification requirements for commercial entrance matting, forcing facility managers toward certified rental programs. The Texas Medical Center in Houston and Florida's Orlando Health expansion exemplify this demand concentration.
Germany
Industrial manufacturing facilities prioritize anti-fatigue ergonomic matting to mitigate workers' compensation exposure under REACH chemical safety frameworks. The country's national workplace safety regulator enforces strict slip-resistance certification for commercial floor coverings. The Ruhr industrial corridor and Bavarian automotive clusters anchor demand for high-specification rental services with documented ergonomic credentials.
China
Rapid commercial construction in Yangtze River Delta and Pearl River Delta metro corridors expands entrance mat deployment across retail and office segments. GB standards for commercial building safety govern mat performance specifications in public facilities. Shanghai and Shenzhen construction booms concentrate service demand where facility managers seek bundled maintenance solutions.
Japan
Aging workforce demographics elevate ergonomic specification standards in manufacturing and healthcare settings under METI industrial safety guidelines. JIS standards for slip resistance and soil retention shape procurement requirements for institutional matting. The Kanto and Kansai manufacturing belts drive premium-tier rental adoption where injury prevention documentation carries litigation defense value.
United Kingdom
Corporate campus consolidations in London and Southeast England favor integrated facility service contracts over standalone mat procurement. The Health and Safety Executive enforces workplace slip-prevention mandates that elevate certified rental program adoption. Canary Wharf and Thames Valley business parks exemplify procurement consolidation toward multi-service vendors.
Floor Mat Rental Service Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where route density and captive laundering infrastructure determine margin sustainability. The market consolidates around multi-service platforms with uniform-rental cross-selling capabilities, regional specialists with vertical compliance expertise, and asset-light operators leveraging third-party logistics. Dominant competitive moves include geographic expansion through route acquisition and portfolio diversification into adjacent facility services.
Within the integrated service tier, Cintas Corporation and UniFirst Corporation exemplify the multi-platform archetype, leveraging uniform-rental infrastructure to cross-sell mat programs at scale. Aramark Corporation occupies a position among vertical specialists, anchoring competitive stance through healthcare and education sector concentration where contract duration and compliance documentation carry premium value.
| Leading Market Players |
|---|
| Cintas Corporation |
| UniFirst Corporation |
| Aramark Corporation |
| Alsco Inc. |
| Vestis Corporation |
| Crown Matting Technologies |
| Milliken & Company |
| Lindström |
| Walk-On Dust Control |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in industrial laundering facilities across the Midwest and Northeast compresses route economics while simultaneously elevating pricing power for operators with captive wash infrastructure and EPA-compliant discharge permits. Facility managers facing OSHA slip-resistance mandates absorb premium pricing for certified rental programs that bundle documented coefficient-of-friction testing with scheduled sanitization.
Pricing Analysis
Certification level creates the primary spread between service tiers, with Joint Commission-compliant documentation packages commanding substantial premiums over basic rental subscriptions. Three-tier pricing structure separates enterprise healthcare contracts with audit-ready trails from standard commercial accounts and economy-tier small business programs. Cost compression in the economy tier intensifies because big-box retail distributors displace rental subscriptions with low-cost disposable matting. Hospitals and multi-facility health systems exhibit lowest price sensitivity due to litigation defense requirements, while seasonal retail operators and small commercial accounts demonstrate highest sensitivity to subscription costs.
Supply Chain Analysis
Petroleum price volatility between crude oil producers and synthetic fiber manufacturers dominates input cost instability for nylon and rubber mat production. Manufacturing concentration rests on China, the United States, and Germany for industrial matting substrates and laundering equipment. Raw material dependencies draw from petroleum-based polymers, natural rubber compounds, and high-tenacity polyester fibers. Single-source vulnerability concentrates in specialized EPA-compliant wash facility infrastructure. Distribution runs through route-based service networks with captive logistics rather than third-party freight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
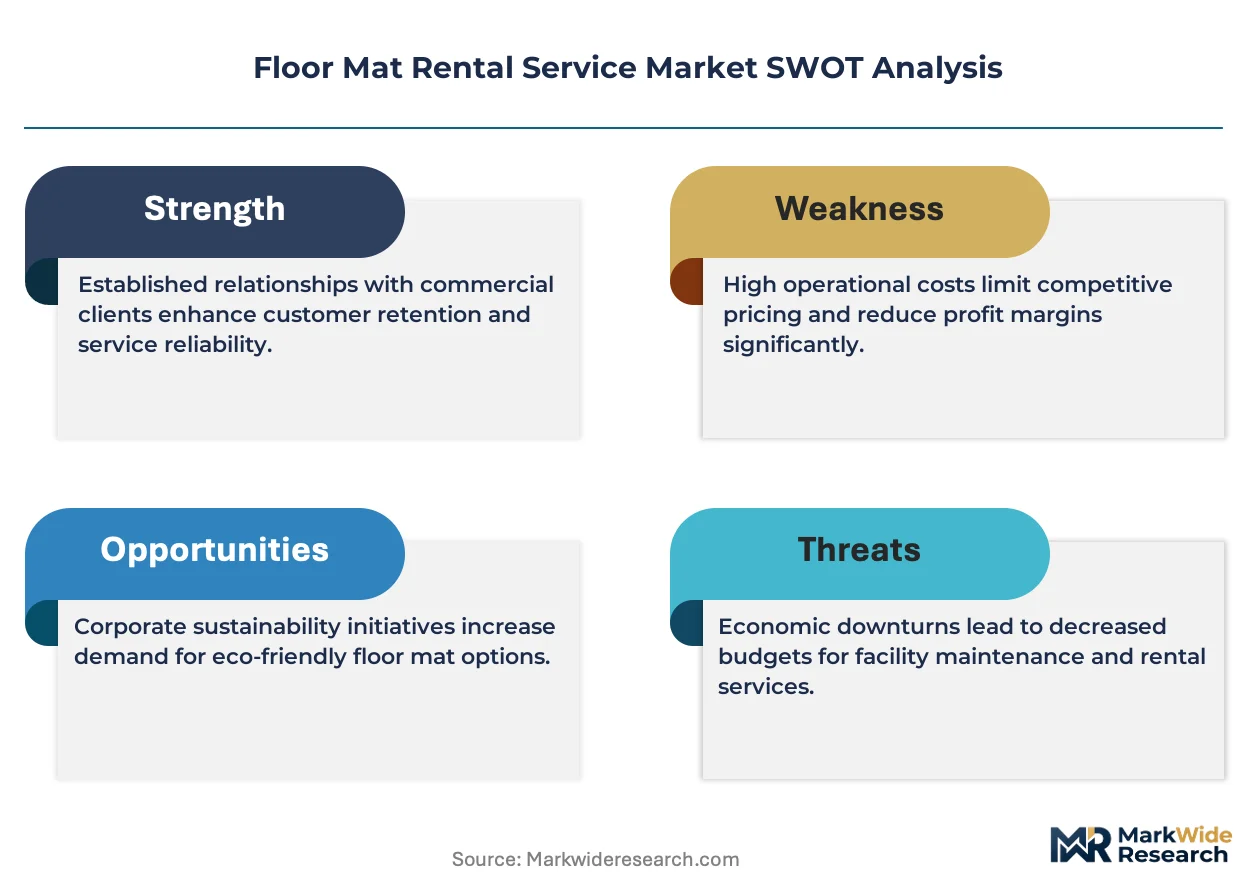
Floor mat rental services represent a compelling service-attach opportunity as compliance documentation and scheduled sanitization layers expand faster than hardware mat sales. Recurring revenue from audit-ready replacement cycles generates superior margin stability compared to one-time direct purchases.
For Market Incumbents: Harden route density in Texas, California, and Florida hospital construction corridors to defend against regional specialists capturing Joint Commission-compliant contracts. Invest in RFID-enabled inventory tracking to automate replacement triggers and deepen compliance automation capabilities that justify premium pricing. Vertical integration into captive laundering infrastructure with closed-loop water recycling protects margin position against EPA discharge rule tightening.
For New Entrants and Emerging Players: Pursue seasonal retail on-demand rental models serving Q4 holiday pop-up operators seeking inventory flexibility without fixed obligations. Target exurban and rural territories where route inefficiencies have discouraged established multi-service platforms. Deploy rapid deployment logistics with short-term contract structures as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EPA-compliant wash facility infrastructure as discharge monitoring and reporting obligations tighten. Long-term viability favors platforms with integrated uniform-rental cross-selling capabilities and healthcare vertical concentration. Acquisition target archetype includes regional specialists with vertical compliance expertise and established hospital system relationships. Monitor state-level water reuse incentive expansion as the signal indicating which providers will capture compliance cost offsets.
| Strategic Initiative | Industry Significance |
|---|---|
| Route Density Expansion | Cintas and UniFirst leverage uniform infrastructure to cross-sell mat programs at scale. |
| RFID-Enabled Inventory Tracking | Healthcare systems deploy tagged products to automate replacement triggers and audit documentation. |
| Closed-Loop Water Recycling | California and New York regulations reward wastewater recycling with compliance cost offsets. |
| Anti-Fatigue Ergonomic Certification | Manufacturing facilities specify certified matting to mitigate workers' compensation litigation exposure. |
| On-Demand Rental Platform | Seasonal retail operators seek Q4 deployment flexibility without fixed subscription obligations. |
Research Methodology
Desk research of trade association publications, EPA enforcement records, and OSHA technical guidance preceded structured interviews with route operations managers, healthcare facility directors, and commercial real estate procurement leads. Primary fieldwork with industrial laundering facility operators and uniform-rental service executives combined with secondary validation against company filings and state regulatory databases. Bottom-up contract value analysis triangulated against top-down market sizing from construction permit data and hospital expansion announcements.
Assumptions held fixed include OSHA slip-resistance mandate continuity and Joint Commission protocol stability, while petroleum input costs and regional water reuse incentive expansion were varied across sensitivity scenarios. Segmentation modeling incorporated product type, client vertical, service contract duration, and substrate material dimensions. CAGRs derived from route density economics and replacement frequency patterns across healthcare, retail, and industrial end-uses. Forecast inputs included hospital construction permit velocity and seasonal retail floor space expansion indices.
Sensitivities concentrate around crude oil price volatility affecting nylon and rubber substrate costs, EPA wastewater discharge rule amendments, and state-level workplace safety mandate expansion. Forecasts reflect documented assumptions regarding route optimization technology adoption and compliance documentation automation penetration. Macroeconomic contraction reducing commercial construction, regulatory deviation relaxing sanitization requirements, or technological substitution displacing physical matting would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Department Stores Market
Retailing
Consumer Shopping Cart Market
Retailing
Australia Retail Bags Market
Retailing
Retail Vending Machine Market
Retailing
Vietnam Retail Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Consumer Products and Retail Market
Retailing
European Discount Retail Market
Retailing
Clothing Retail Market
Retailing
Home Shopping Market
Retailing
Retail Display Racks Market
Retailing
United States Hardware Stores Retail Market
Retailing
In Store Signage Market
Retailing
Floor Displays Market
Retailing
Philippines Retail Industry Market
Retailing
Retail Signage Market