
 United States Hardware Stores Retail Market | 2026-2036
United States Hardware Stores Retail Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hardware Stores Retail Market Insights
The gap between premium-grade tool lines and commodity hardware assortments is repositioning how retailers allocate floor space and inventory capital. Home Depot leverages its captive supply chain for professional-grade power tools to dominate contractor loyalty. Lowe's anchors its growth in suburban DIY homeowners through curated home improvement ecosystems. Ace Hardware competes via localized inventory depth and neighborhood convenience that national boxes cannot replicate.
United States hardware stores retail encompasses the sale of tools, fasteners, building materials, and home improvement supplies through dedicated physical and digital storefronts, typically featuring SKUs ranging from 30,000 to 100,000 items with specialized logistics for bulky, hazardous, and seasonal merchandise. These retailers serve as critical intermediaries between manufacturers and end-users, bridging specification-heavy professional procurement with impulse-driven consumer purchases. Power tools command premium margin pools as battery-platform ecosystems lock users into branded accessory ecosystems. Hand tools and fasteners represent mature, high-velocity categories where private-label penetration squeezes branded suppliers. Tool rental and repair services emerge as the fastest-growing service type, converting transactional hardware purchases into recurring revenue relationships.
OSHA workplace safety mandates and EPA hazardous material disposal rules directly shape product assortments, training investments, and vendor compliance costs for US hardware retailers. The FTC's Green Guides constrain environmental marketing claims on sustainable building products sold through these channels. State-level building codes in California and Florida create fragmented regulatory overlays that demand localized inventory planning. Stakeholders must monitor how evolving lithium-ion battery transportation regulations and right-to-repair legislation reshape service-type profitability and supplier liability structures.
Market Dynamics
Professional contractor procurement consolidation is compressing inventory turns and forcing hardware retailers to reconfigure floor space toward high-velocity power tool platforms and specialized fastening systems. This buyer-side concentration rewards scale operators with captive supply chains while squeezing independents on working capital efficiency.
Growth Catalysts
- OSHA Silica Exposure Standards:The 2023 respirable crystalline silica rule for construction mandates dust-collection systems on power tools, accelerating replacement cycles for compliant equipment across Texas and Florida job sites.
- Battery Platform Ecosystems:Lithium-ion tool systems from Milwaukee and DeWalt lock contractors into branded accessory purchases, creating recurring revenue streams that stabilize seasonal demand fluctuations.
- Metro Corridor Construction Velocity:Residential permit issuance in Houston, Dallas, Miami, and Los Angeles outpaces national baselines, concentrating inventory investment in Sun Belt distribution nodes.
Market Restraints
- Lumber and Steel Input Volatility:Framing lumber and structural steel price swings compress gross margins on building materials, forcing hedging costs that smaller independents cannot absorb.
- Asian Power Tool Manufacturing Concentration:Dependence on Chinese and Taiwanese OEMs for cordless tool assembly creates tariff exposure and extended lead times during ocean freight disruptions.
- Big-Box Scale Economics:Home Depot and Lowe's captive logistics networks and private-label penetration in fasteners and hand tools structurally disadvantage neighborhood competitors on price.
Strategic Opportunities
- Tool Rental and Repair Services:Converting transactional purchases into recurring revenue relationships captures contractor loyalty while generating 40-60% gross margins on depreciation schedules.
- EPA Lead-Safe Renovation Certification:The RRP rule mandates certified renovators for pre-1978 housing, creating demand for HEPA vacuums, containment systems, and training services in legacy urban markets.
- Pro-Customer Digital Integration:Mobile-optimized job site ordering with will-call fulfillment and delivery logistics addresses contractor time constraints that national boxes serve poorly.
Industry Challenges
- Skilled Trade Labor Scarcity:Retiring electricians, plumbers, and carpenters outpace apprenticeship completions, shrinking the addressable market for professional-grade tool sales in Midwest manufacturing corridors.
- Multi-Channel Inventory Synchronization:Real-time stock visibility across physical stores, dark stores, and direct-to-pro delivery networks demands capital-intensive warehouse management system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hardware Stores Retail Market |
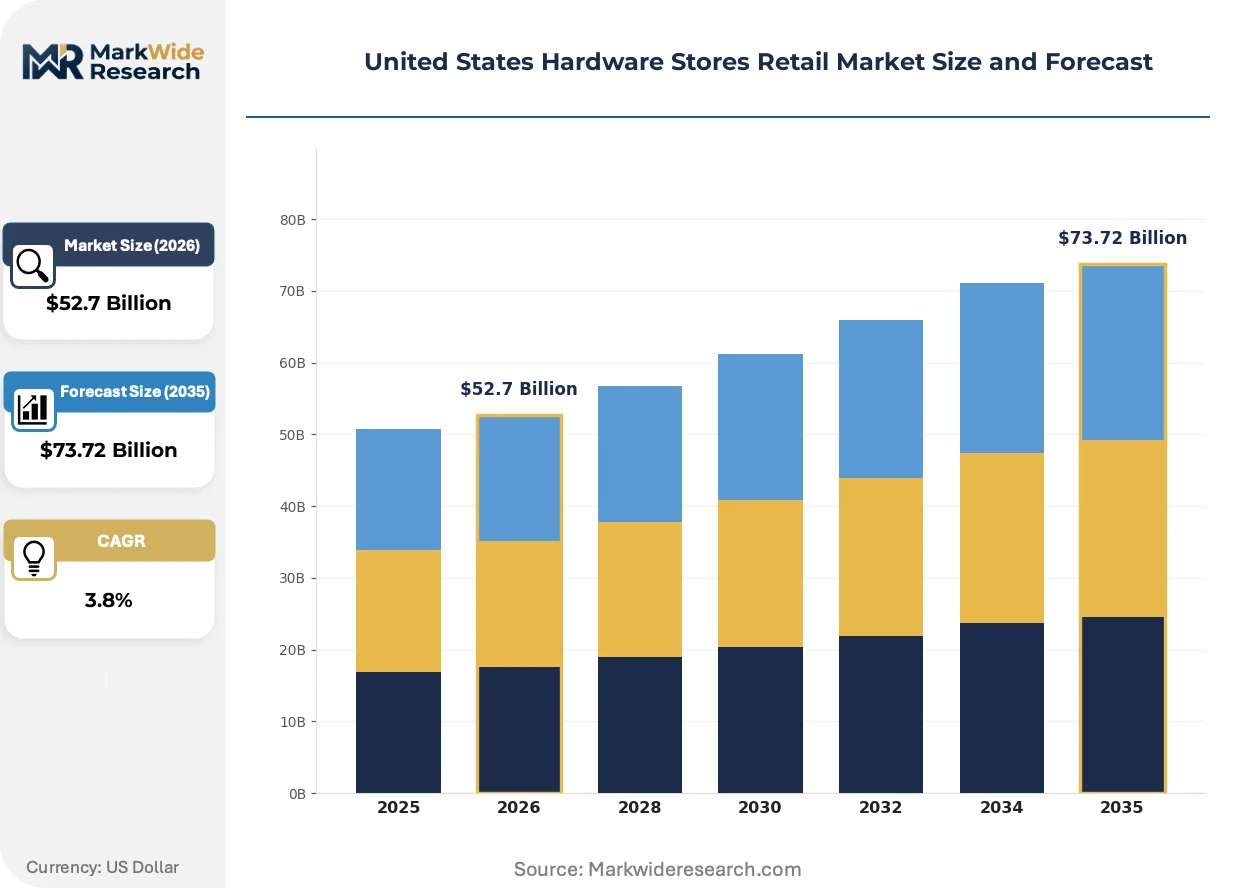
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $73.72 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Tools, Power Tools, Fasteners, Hardware Accessories Customer Type: DIY Enthusiasts, Contractors, Building Professionals, Homeowners Sales Channel: Online Retail, Brick-and-Mortar, Wholesale, Distribution Service Type: Tool Rental, Repair Services, Delivery, Consultation |
| Companies Covered | Home Depot, Lowe's Companies, Ace Hardware, Menards, True Value, Harbor Freight Tools, Tractor Supply, Do it Best, CNRG Hardware, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hardware Stores Retail Market Trends and Innovations
Battery chemistry advancement and regulatory compliance mandates are converging to reshape product assortments and service architectures. Retailers must now manage hazardous material logistics alongside traditional inventory velocity optimization.
Cordless power tool battery architecture is modularizing around interchangeable voltage platforms that span drills, saws, and outdoor equipment. Professional contractors in Texas and Florida metro corridors are consolidating purchases around single-brand ecosystems to reduce charger redundancy and simplify job site logistics. This standardization is modularizing supplier relationships, compressing SKU counts while deepening volume commitments to preferred OEM partners.
EPA hazardous material disposal rules for lithium-ion batteries and lead-acid power tool batteries are tightening reverse logistics requirements. Retailers now face manifest documentation obligations and certified recycler partnerships that add per-unit handling costs. California's DTSC universal waste regulations extend these burdens to consumer returns, forcing statewide compliance investments that smaller operators defer.
Pro-customers are unbundling after-sales service from product purchases, demanding standalone repair diagnostics and preventive maintenance contracts. Independent hardware cooperatives in the Northeast are responding with mobile technician fleets that national boxes cannot replicate. This service fragmentation is most visible in Boston and Philadelphia corridors where aging housing stock sustains renovation demand independent of new construction cycles.
United States Hardware Stores Retail Market Segmentation
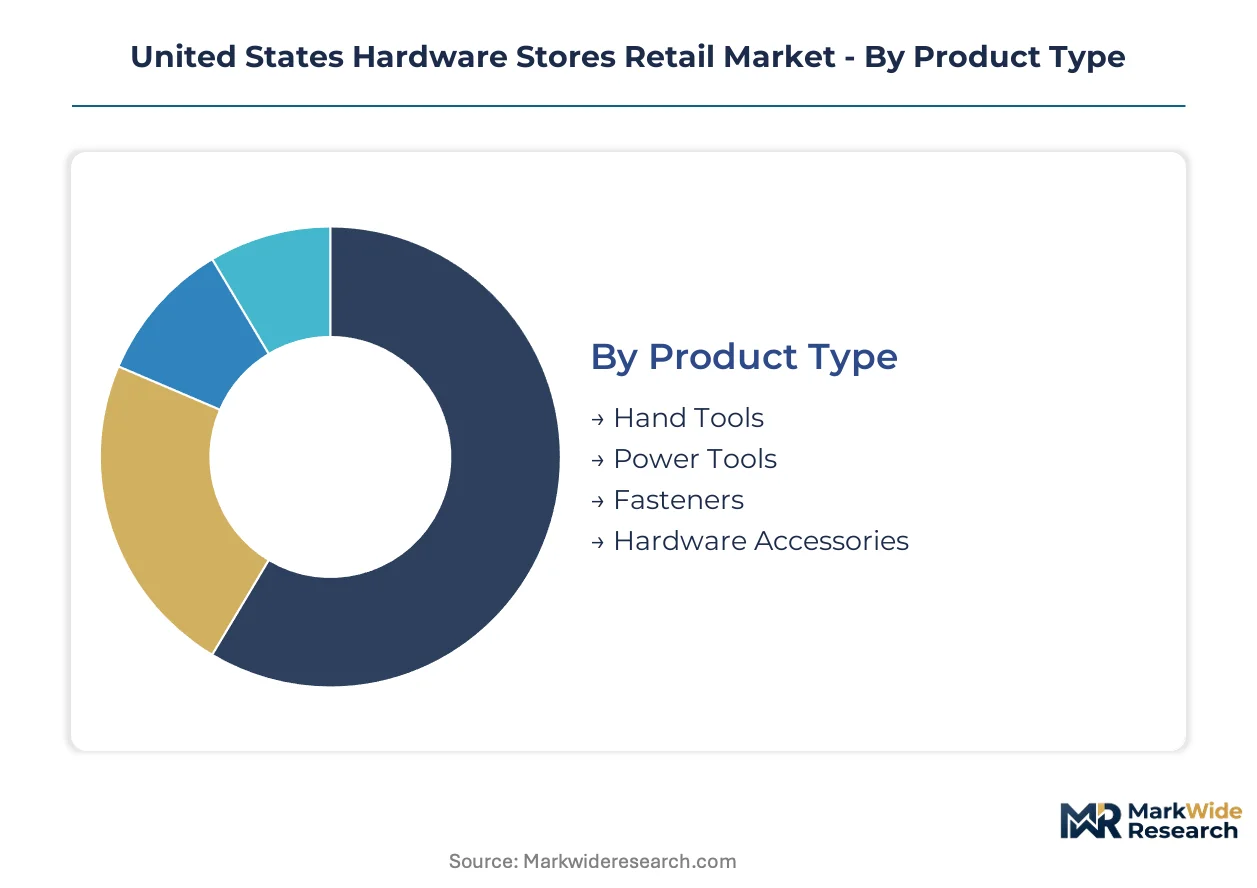
Segmentation in United States hardware retail reveals how certification burdens, procurement scale, and channel economics fragment revenue pools. Retailers must align inventory depth and service architecture to distinct buyer workflows and compliance requirements.
Product Type:
OSHA silica exposure standards and EPA lead-safe renovation rules impose divergent certification requirements across product lines, reshaping margin structures and supplier liability.
- Hand Tools:Wrenches, pliers, and screwdrivers manufactured to ANSI specifications face minimal regulatory burden. Demand concentrates among DIY homeowners in suburban markets where impulse purchases drive basket economics and private-label penetration squeezes branded margins.
- Power Tools:Cordless drills, saws, and grinders must comply with OSHA dust-collection mandates and lithium-ion battery transportation regulations. Contractor procurement in Texas and Florida metro corridors locks into Milwaukee and DeWalt battery-platform ecosystems, creating recurring accessory revenue.
- Fasteners:Structural bolts, screws, and anchors graded to ASTM standards serve high-velocity replenishment cycles. Building professionals in California seismic zones drive demand for code-compliant structural hardware.
- Hardware Accessories:Hinges, locks, and cabinet pulls complete project workflows. Homeowners completing kitchen and bath renovations in Sun Belt markets sustain seasonal demand patterns.
Leading the category by volume: Fasteners. Growing fastest: Power Tools.
Customer Type:
Procurement scale and specification intensity separate price-sensitive consumers from compliance-heavy professional buyers, forcing tiered service architectures.
- DIY Enthusiasts:Hobbyist renovators prioritize project guidance and curated assortments over technical specifications. Suburban markets around Atlanta and Phoenix sustain big-box traffic through weekend workshop programming.
- Contractors:Licensed tradespeople demand will-call fulfillment, volume pricing, and certified tool repair. EPA RRP certification requirements for pre-1978 housing renovation concentrate demand for HEPA vacuums and containment systems in legacy urban markets.
- Building Professionals:Architects and engineers specify grade-marked structural hardware for commercial projects. Multi-family construction velocity in Miami and Los Angeles drives specification-heavy procurement.
- Homeowners:Reactive repair purchasers respond to weather events and seasonal maintenance cycles. Hurricane preparation in Florida and wildfire mitigation in California create surge demand for generators and safety equipment.
Highest specification burden: Contractors. Expanding most quickly: Building Professionals.
Sales Channel:
Capital intensity and inventory velocity requirements concentrate power tool sales in scaled formats while fragmented demand sustains localized alternatives.
- Online Retail:Mobile-optimized ordering with job site delivery addresses contractor time constraints. Pro-customer digital integration captures share from national boxes in secondary markets.
- Brick-and-Mortar:Physical showrooms enable tool demonstration and immediate fulfillment. Neighborhood independents in Northeast corridors compete via repair services national boxes cannot replicate.
- Wholesale:Direct procurement by multi-location contractors bypasses retail markup. Volume commitments stabilize seasonal demand fluctuations for distributors.
- Distribution:Third-party logistics networks extend reach to rural construction markets. Dark store fulfillment models reduce last-mile costs for bulky merchandise.
Dominant by revenue: Brick-and-Mortar. Gaining share fastest: Online Retail.
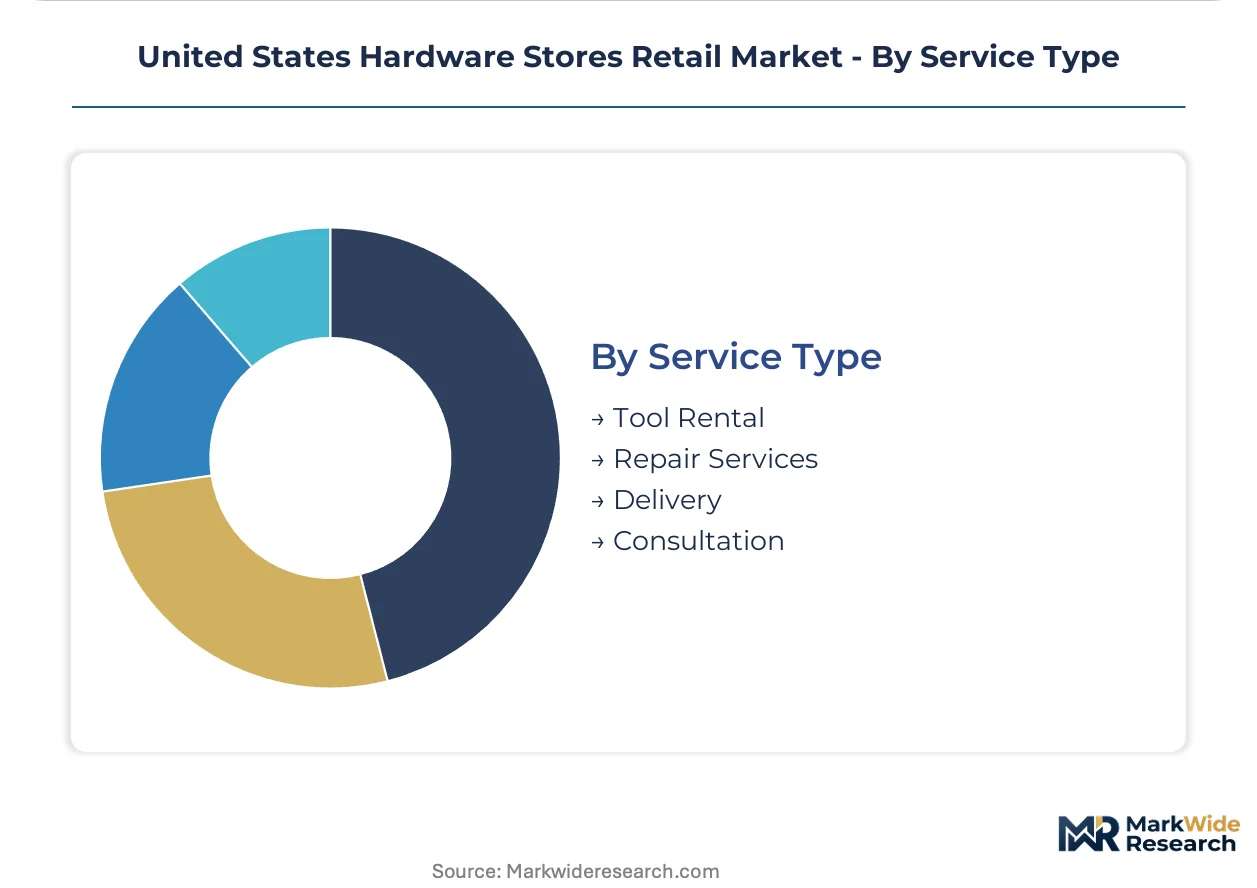
Service Type:
Recurring revenue potential and margin structure separate transactional add-ons from relationship-building service lines.
- Tool Rental:Depreciation-based revenue models capture contractor loyalty for specialized equipment. Mobile technician fleets in Boston and Philadelphia corridors address aging housing stock independent of new construction cycles.
- Repair Services:Preventive maintenance contracts and diagnostics convert product sales into recurring relationships. Independent cooperatives exploit capability gaps left by national box service limitations.
- Delivery:Job site logistics address contractor time constraints and bulky merchandise handling. Will-call fulfillment with route optimization reduces downtime for building professionals.
- Consultation:Project planning and code compliance guidance differentiate neighborhood retailers. EPA lead-safe certification training creates sticky relationships with renovators in legacy housing markets.
Highest margin profile: Tool Rental. Steepest expansion trajectory: Repair Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston and Dallas anchor hardware demand velocity through residential construction corridors that outpace national permit issuance baselines. EPA regional enforcement offices in these metros coordinate silica exposure compliance inspections across active job sites.
Texas
Professional contractors in Houston and Dallas drive power tool replacement cycles tied to OSHA silica dust-collection mandates. TCEQ air quality regulations intersect with federal standards to create dual-layer compliance requirements. Permian Basin energy construction sustains demand for specialized fastening systems in Midland-Odessa corridors.
Florida
Miami and Tampa metro areas concentrate hurricane preparation demand for generators and safety equipment ahead of seasonal storm cycles. Florida Building Code wind-load requirements shape structural hardware specifications for coastal construction. Orlando's renovation market generates EPA lead-safe RRP certification demand for pre-1978 housing stock.
California
Los Angeles and San Francisco Bay Area multi-family construction drives specification-grade structural hardware procurement. DTSC universal waste regulations impose lithium-ion battery reverse logistics burdens that extend to consumer returns. Wildfire mitigation programs in Sacramento corridors sustain seasonal demand for safety equipment and containment systems.
Southeast
Atlanta and Charlotte suburban expansion sustains DIY homeowner traffic through weekend workshop programming. State-level building code variations between Georgia and North Carolina create fragmented inventory planning requirements. Charleston's historic preservation market generates specialized restoration hardware demand independent of new construction cycles.
Northeast
Boston and Philadelphia aging housing stock sustains renovation demand through independent hardware cooperatives with mobile repair fleets. State RRP enforcement in Massachusetts and Pennsylvania exceeds federal baselines, concentrating certified renovator training demand. Brooklyn's brownstone restoration market generates specialized fastener and hardware accessory requirements.
United States Hardware Stores Retail Market Competitive Landscape
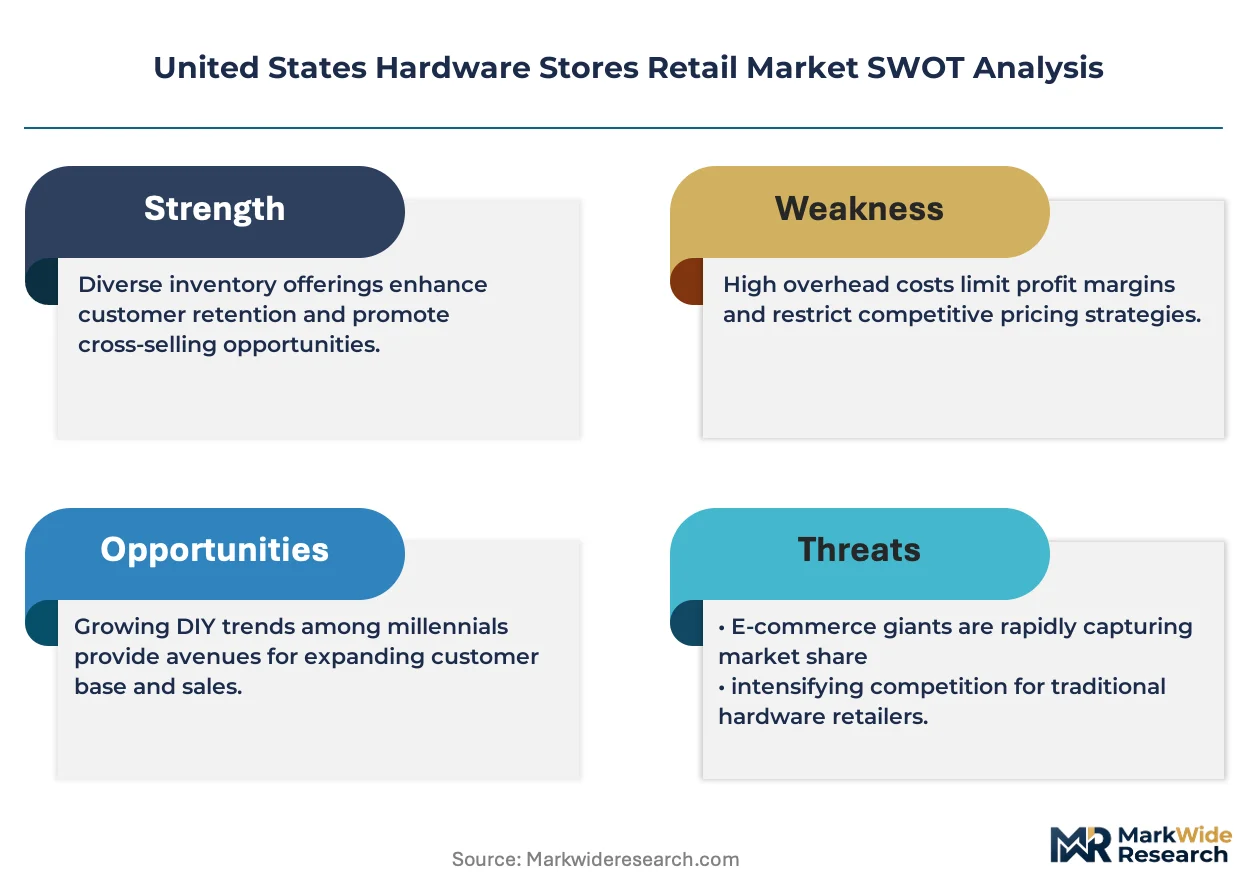
Premium-margin players sit above commodity-margin players across battery-platform ecosystem control and captive supply chain integration. The market structure consolidates around national boxes with logistics scale while fragmenting into neighborhood independents with service depth. Two strategic archetypes dominate: ecosystem-locked power tool platforms and localized repair-service specialists. Competitive moves center on private-label penetration in fasteners and dark-store fulfillment expansion for pro-customer delivery.
Among national-scale retailers, Home Depot, Lowe's Companies, and Ace Hardware occupy distinct positioning vectors. Home Depot exemplifies the captive supply chain archetype through professional-grade power tool dominance. Lowe's Companies represents suburban DIY ecosystem curation with home improvement project anchoring. Ace Hardware anchors the neighborhood convenience tier through localized inventory depth that national logistics networks cannot replicate.
| Leading Market Players |
|---|
| Home Depot |
| Lowe's Companies |
| Ace Hardware |
| Menards |
| True Value |
| Harbor Freight Tools |
| Tractor Supply |
| Do it Best |
| CNRG Hardware |
| Others |
Pricing and Supply Chain Analysis
EPA lithium-ion battery transportation regulations gate qualified supply and premium-tier pricing access for power tool retailers, forcing compliance investments that only scaled operators can absorb while squeezing independents into commodity-margin tiers.
Pricing Analysis
Job-site uptime value anchors contractor willingness to pay for Milwaukee and DeWalt battery-platform ecosystems. Three-tier pricing structure across professional-grade, prosumer, and DIY levels separates certified dust-collection power tools from standard cordless equipment and private-label hand tools. Cost compression in lumber and structural steel categories is intensifying because of futures market volatility, pressuring building materials margins. DIY homeowners in suburban Atlanta and Phoenix corridors exhibit highest price sensitivity, while licensed contractors in Houston and Dallas lock into volume pricing agreements with lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Taiwanese OEMs for cordless tool assembly and lithium-ion battery cell production. Manufacturing concentration in China, Taiwan, and South Korea draws from rare earth mineral processing and semiconductor-grade battery management systems. Tariff exposure on finished power tools and extended ocean freight lead times create inventory risk for seasonal demand spikes. Distribution runs through Home Depot and Lowe's captive logistics networks, with dark-store fulfillment models extending reach to secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified recycler capacity for lithium-ion battery reverse logistics props pricing power, as EPA manifest documentation requirements constrain how many retailers can offer trade-in programs.
For Market Incumbents: Anchor defensive positioning through backward integration into certified battery recycling infrastructure and HEPA vacuum rental fleets. Consolidate neighborhood independents in Northeast corridors to capture mobile repair capabilities that national boxes cannot replicate. Vertical integration into captive supply chains for professional-grade power tools locks contractor loyalty against Harbor Freight price aggression. For New Entrants and Emerging Players: Capture white-space in EPA lead-safe RRP certification training services for Orlando and Brooklyn renovation markets. Exploit underpenetrated tool rental demand in Boston and Philadelphia corridors where aging housing stock sustains renovation cycles independent of new construction. Lead with mobile-optimized job site ordering paired with will-call fulfillment to address contractor time constraints. For Investors and Strategic Acquirers: OSHA silica enforcement acceleration in Texas and Florida is the leading indicator that dust-collection-compliant power tool replacement cycles will deepen. Target independent hardware cooperatives with established mobile technician fleets and certified renovator training relationships. Watch lithium-ion battery transportation regulation tightening as the signal for recycler partnership valuations to reset upward.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Ecosystem Lock-In | Milwaukee and DeWalt accessory recurring revenue stabilizes seasonal contractor demand fluctuations. |
| Tool Rental Fleet Expansion | Depreciation-based revenue models in Boston and Philadelphia capture 40-60% gross margins. |
| EPA RRP Certification Training | Sticky renovator relationships in Orlando and Brooklyn generate repeat containment system purchases. |
| Dark Store Fulfillment Network | Last-mile cost reduction for bulky merchandise extends pro-customer delivery to secondary markets. |
| Mobile Repair Technician Fleet | Preventive maintenance contracts convert transactional sales into recurring revenue relationships. |
Research Methodology
Multi-period observation of residential permit issuance, power tool replacement cycles, and EPA enforcement patterns anchored the trend analysis, supplemented by interviews with hardware store owners, contractor procurement managers, battery OEM supply chain directors, and certified renovator training providers. Secondary validation drew from OSHA regulatory filings, EPA regional enforcement data, customs import records, and SEC 10-K disclosures from listed retailers. Bottom-up store-level revenue modeling and top-down construction spending allocation triangulated market sizing.
Segment-weighting across product type, customer archetype, sales channel, and service category informed volume and value outputs across the projection horizon. Modeled dimensions included battery-platform ecosystem loyalty, silica compliance replacement intensity, and metro corridor construction velocity. CAGRs derived from trend extrapolation of permit issuance data and historical tool replacement patterns, with lithium-ion battery chemistry advancement and right-to-repair legislative momentum as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to trade policy shifts, ocean freight rate volatility, and apprenticeship completion rates affecting skilled trade labor supply. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Out Store Signage Market
Retailing
Australia Retail Bags Market
Retailing
Out-Door Signage Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Global Food and Non-Food Retail Market
Retailing
Department Stores Market
Retailing
European Discount Retail Market
Retailing
Gift Baskets Market
Retailing
Philippines Retail Industry Market
Retailing
Thailand Retail Market
Retailing
Consumer Shopping Cart Market
Retailing
Singapore Gifting Market
Retailing
Clothing Retail Market
Retailing
Floor Displays Market
Retailing
China Retail Market
Retailing
Subscription Box Market