
 Global Food and Non-Food Retail Market | 2026-2036
Global Food and Non-Food Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food and Non-Food Retail Market Analysis
Premium private-label quality tiers is bifurcating the Global Food and Non-Food Retail Market into value-conscious and experience-seeking shopper bases. Costco leverages its Kirkland Signature line to sustain margin premiums on groceries and personal care. Walmart anchors North American volume through backward integration into distribution networks and supplier financing. Schwarz Group dominates European discount positioning via Lidl and Kaufland banners.
Food and non-food retail encompasses the commercial distribution of consumable goods and durable household merchandise through physical and digital storefronts, with inventory turnover rates, cold-chain integrity for perishables, and SKU density serving as core operational parameters. The sector exists to match manufactured output with fragmented household and institutional demand at localized points of sale. Groceries and beverages anchor the product-type revenue base while carrying thin margins offset by high purchase frequency. Online stores represent the fastest-growing distribution channel as logistics networks compress last-mile delivery windows. Premium and organic pricing tiers capture disproportionate margin pools as certification standards and provenance claims justify shelf-price elevation.
The EU Green Deal and its Packaging and Packaging Waste Regulation reshape product standards for cleaning products and personal care items sold across France, Germany, and Italy. The FDA and USDA maintain separate but overlapping jurisdiction over food safety labeling and agricultural sourcing claims in the United States, creating compliance complexity for multinational retailers. India's FSSAI enforces packaged food standards that determine market access for both domestic chains and foreign entrants. Stakeholders must monitor divergence between EU packaging mandates and US state-level plastic bans as this regulatory fragmentation threatens unified procurement and private-label development strategies.
Market Dynamics
Organized retail formats are displacing traditional independent stores across emerging economies, compressing procurement timelines and forcing distributors to consolidate supplier relationships under centralized category management systems.
Growth Catalysts
- Quick-service restaurant procurement:Chain restaurants are expanding pre-packaged grocery sourcing through retail channels, creating dedicated wholesale tiers within existing store networks.
- EU Green Deal packaging rules:The Packaging and Packaging Waste Regulation mandates recycled content minimums for consumer goods, accelerating retailer investment in sustainable private-label development.
- Urban household concentration:Indian metro migration patterns concentrate demand in organized retail catchments, reducing last-mile logistics costs for perishable inventory.
Market Restraints
- Perishable cold-chain costs:Refrigerated transport and storage infrastructure requires sustained energy expenditure that thin grocery margins cannot fully absorb.
- Supplier consolidation risk:Reliance on concentrated agricultural regions for fresh produce creates vulnerability to climate-driven harvest volatility.
- Regulatory fragmentation:Divergent EU packaging mandates and US state-level plastic bans complicate unified private-label sourcing strategies.
Strategic Opportunities
- Tier-two Indian cities:Nascent organized retail penetration in Lucknow, Indore, and Kochi offers first-mover positioning before saturation.
- Quick-commerce integration:Dark-store micro-fulfillment networks enable sub-30-minute delivery windows for urban convenience categories.
- US Inflation Reduction Act incentives:Clean energy tax credits support retailer investment in solar-powered distribution centers and electric last-mile fleets.
Industry Challenges
- Inventory optimization talent:Shortage of data scientists capable of deploying demand-forecasting algorithms across high-SKU grocery environments.
- Legacy system integration:ERP migration friction slows real-time visibility between warehouse management and point-of-sale systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food and Non-Food Retail Market |
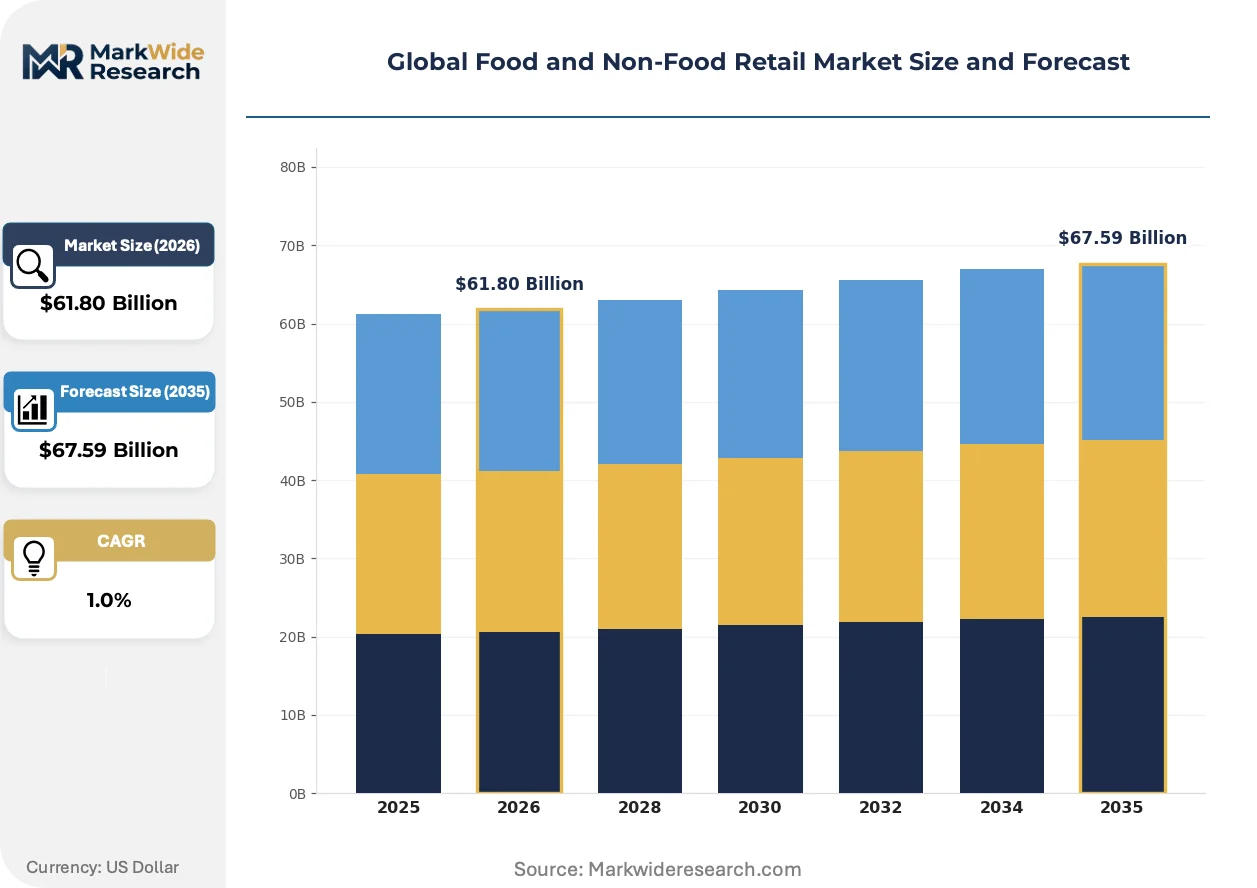
| Market Size in 2026 | $61.80 Billion |
| Market Size in 2035 | $67.59 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Groceries, Beverages, Personal Care, Cleaning Products Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Specialty Shops Customer Type: Households, Restaurants, Cafes, Institutions Pricing Tier: Premium, Mid-Range, Budget, Organic |
| Companies Covered | Costco, Aldi, Walmart, Home Depot, Carrefour, Amazon, Kroger, Ahold Delhaize, Schwarz Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food and Non-Food Retail Market Emerging Trajectories
Artificial intelligence applications are rewiring how retailers predict demand, position inventory, and personalize pricing across fragmented shopper segments.
Computer vision shelf-monitoring systems are fragmenting traditional stock-count labor models. Mass merchandisers deploy ceiling-mounted cameras to track real-time SKU availability and planogram compliance. This technology compresses restock response times while reducing manual audit headcount.
The EU Green Deal's packaging waste regulation tightens material specifications for cleaning products and personal care items sold across France, Germany, and Italy. Retailers must reformulate private-label goods or source compliant alternatives. Personal care aisles face the steepest compliance timeline pressure.
Urban Indian households are rotating weekly shopping from neighborhood kirana stores toward hypermarket destinations. Modern trade captures pantry-stocking trips previously fragmented across multiple independent vendors. This concentration concentrates category spending power in fewer retail banners.
Global Food and Non-Food Retail Market Segmentation
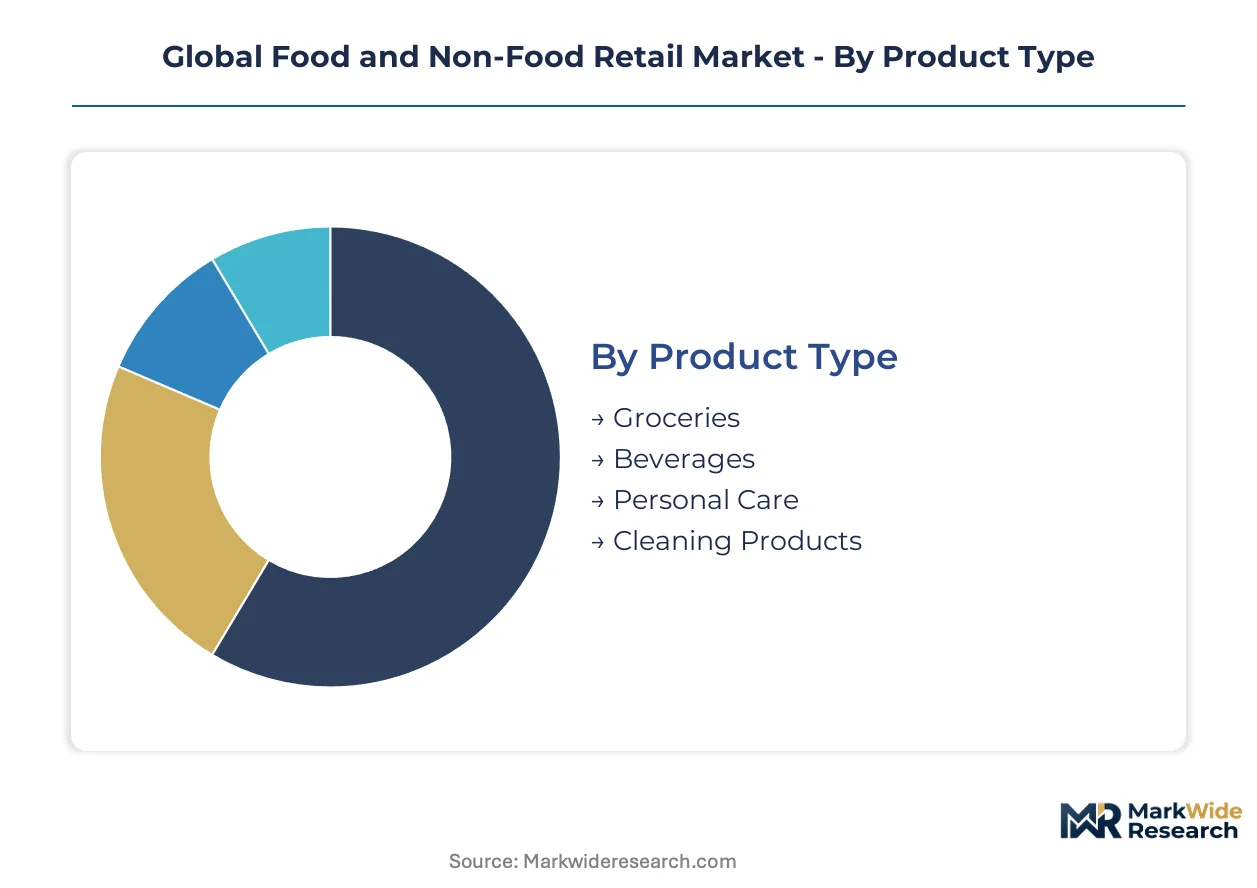
Segmentation in food and non-food retail determines procurement strategies, margin architecture, and regulatory exposure across fragmented demand pools. Each dimension carries distinct operational requirements from cold-chain intensity to private-label development timelines.
Product Type:
FDA and USDA jurisdiction over food safety labeling creates divergent compliance burdens across consumable versus durable merchandise categories. EU Green Deal packaging mandates apply asymmetrically to cleaning products and personal care relative to unprocessed groceries.
- Groceries:Fresh produce, meat, dairy, and packaged staples dominate purchase frequency and foot traffic generation. Indian urban households shifting from kirana stores to hypermarkets concentrate demand in modern trade formats with centralized cold-chain infrastructure.
- Beverages:Alcoholic and non-alcoholic liquids require specialized logistics for weight-to-value ratios and temperature sensitivity. Quick-service restaurant procurement through retail wholesale tiers is expanding volume concentration in fountain syrups and bottled formats.
- Personal Care:Cosmetics, skincare, and hygiene products face the steepest EU Green Deal packaging compliance timeline pressure. Reformulation costs for recycled content minimums compress margin pools for private-label developers.
- Cleaning Products:Detergents, disinfectants, and household chemicals carry concentrated chemical regulatory exposure under REACH and state-level disclosure mandates. Concentrated refill formats are gaining shelf space as retailers respond to plastic reduction targets.
Established volume favors Groceries; emerging adoption favors Personal Care as sustainability premiums justify price elevation.
Distribution Channel:
Cost-to-serve economics fragment across real estate intensity, labor models, and last-mile logistics configuration. Each channel demands distinct inventory turnover velocities and supplier payment terms.
- Supermarkets:Full-service food retail with extended SKU density and fresh perimeter departments anchors weekly household shopping missions. Schwarz Group's Lidl and Kaufland banners demonstrate European discount positioning through limited-assortment supermarket formats.
- Online Stores:Digital storefronts with home delivery or click-and-collect fulfillment compress delivery windows through dark-store micro-fulfillment networks. Sub-30-minute convenience delivery is climbing the fastest in dense urban catchments.
- Convenience Stores:Small-footprint proximity retail captures immediate consumption and top-up purchases with premium price acceptance. Franchise-operated networks in Japan and South Korea achieve supply chain density through centralized distribution.
- Specialty Shops:Category-dedicated retailers in organic foods, ethnic ingredients, or premium beverages command assortment authority and staff expertise. Certification standards and provenance claims support margin premiums unavailable in mass channels.
Supermarkets retain the largest absolute transaction value; Online Stores are gaining share fastest through logistics network densification.
Customer Type:
Volume concentration and purchase predictability vary sharply across fragmented household demand versus consolidated institutional procurement.
- Households:Individual and family units drive purchase frequency through small-basket, high-trip behaviors. Urban Indian metro migration patterns concentrate spending power in organized retail catchments with parking and one-stop assortment.
- Restaurants:Foodservice operators source pre-packaged groceries through retail wholesale tiers with dedicated pricing and case-lot configurations. Chain restaurant procurement standardization creates volume concentration for approved supplier programs.
- Cafes:Coffee-focused establishments demand specialized beverage, dairy alternative, and grab-and-go food assortments with consistent quality specifications. Independent operators lack procurement scale relative to chain restaurants.
- Institutions:Schools, hospitals, and corporate cafeterias purchase through contract foodservice distributors with stringent safety certification and traceability requirements. FSSAI enforcement in India determines market access for institutional suppliers.
Households generate the highest trip frequency; Restaurants are expanding most quickly as quick-service chains deepen retail channel penetration.
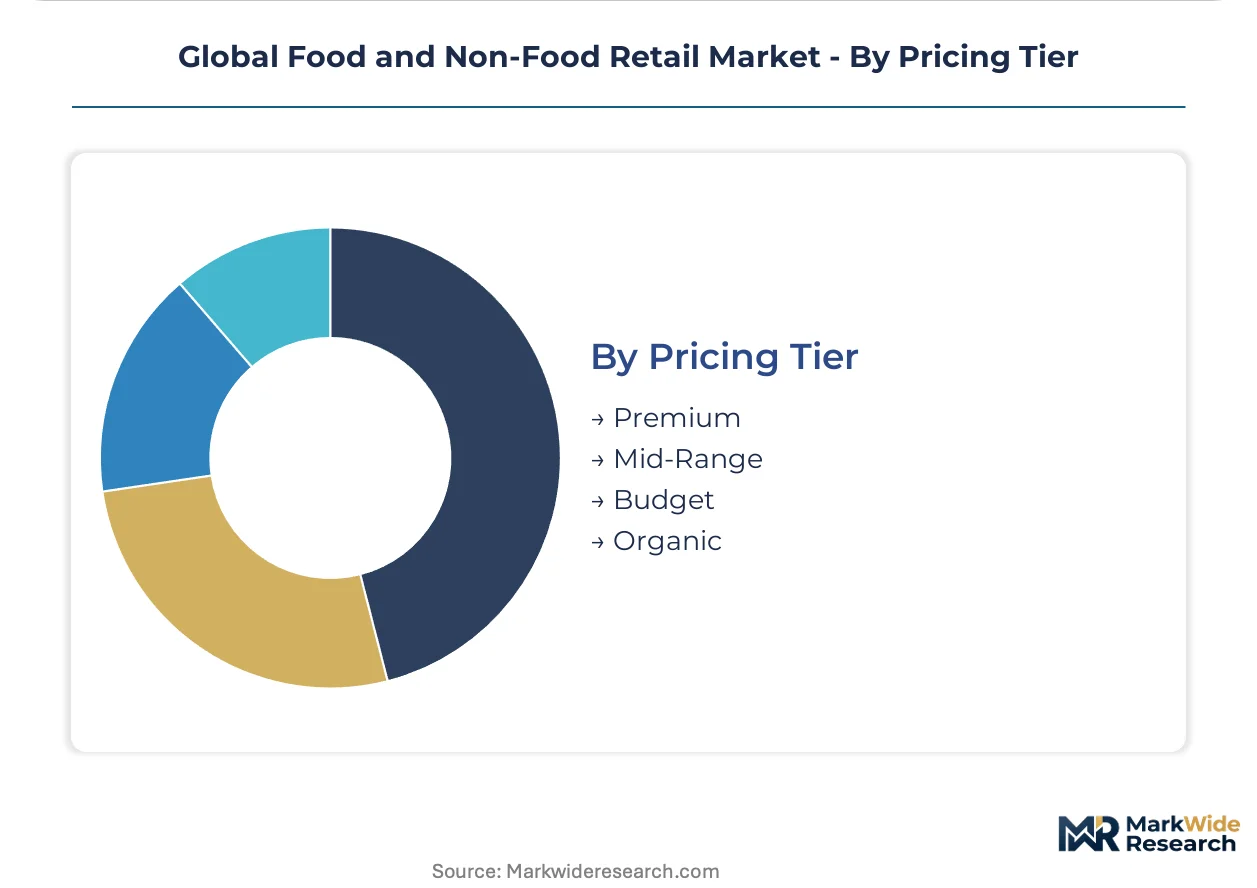
Pricing Tier:
Margin architecture stratifies across certification intensity, ingredient sourcing, and brand equity rather than functional performance alone.
- Premium:Positioning through proprietary formulations, heritage claims, or exclusive distribution supports price multiples over standard tiers. Costco's Kirkland Signature line sustains margin premiums through quality parity with national brands.
- Mid-Range:Balanced value propositions targeting mainstream shoppers with acceptable quality and competitive pricing dominate volume share. Walmart anchors North American volume through backward integration into distribution networks at this tier.
- Budget:Price-focused positioning with minimized packaging, limited assortment, and operational cost discipline captures value-conscious segments. Hard discounters in Germany and Eastern Europe prove sustainability of this model.
- Organic:Certification-driven premiums for pesticide-free, non-GMO, or regenerative production methods command shelf-price elevation. EU organic labeling standards and USDA Organic create compliance complexity for multinational private-label development.
Mid-Range commands absolute volume; Organic is gaining share fastest as certification standards proliferate across geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Distribution networks for food and non-food retail cluster in countries with dense urban corridors and mature cold-chain infrastructure. Retailers in these markets deploy centralized procurement systems to manage perishable inventory turnover. Regulatory divergence across major economies complicates unified private-label sourcing strategies.
United States
Quick-service restaurant chains are expanding pre-packaged grocery procurement through retail wholesale tiers, concentrating volume in fountain syrups and case-lot configurations. The FDA and USDA maintain overlapping jurisdiction over food safety labeling and agricultural sourcing claims, creating compliance complexity for multinational banners. The Greater Chicago and Dallas-Fort Worth corridors anchor national distribution with automated fulfillment centers serving multi-state catchments.
Germany
Hard discount formats capture value-conscious household segments through limited-assortment supermarket positioning with operational cost discipline. The EU Green Deal's Packaging and Packaging Waste Regulation mandates recycled content minimums for cleaning products and personal care items sold across German retail networks. The Rhine-Ruhr metropolitan region concentrates retail headquarters and supplier financing operations for European market coordination.
India
Urban metro migration patterns concentrate demand in organized retail catchments as households shift weekly shopping from neighborhood kirana stores toward hypermarket destinations. The FSSAI enforces packaged food standards that determine market access for both domestic chains and foreign entrants. The Mumbai-Pune and Delhi-NCR corridors host the densest modern trade penetration with centralized cold-chain infrastructure for perishable inventory.
France
Specialty retailers in organic foods and premium beverages command assortment authority through certification standards and provenance claims that justify shelf-price elevation. ANSM and CNIL oversight intersects with EU Green Deal packaging mandates for personal care items sold across French retail networks. The Île-de-France region anchors national procurement with hypermarket banners serving dense urban catchments.
Japan
Franchise-operated convenience store networks achieve supply chain density through centralized distribution systems capturing immediate consumption and top-up purchases. METI standards and JIS certification requirements shape product specifications for household merchandise categories. The Kanto corridor surrounding Tokyo concentrates retail innovation in dark-store micro-fulfillment networks for sub-30-minute delivery windows.
Global Food and Non-Food Retail Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the food and non-food retail sector. Mass merchandisers with backward integration into distribution networks anchor volume share in North America and Europe, while hard discounters sustain margin discipline through limited-assortment formats. Three archetypes dominate: scale-driven procurement specialists, private-label quality tier developers, and quick-commerce logistics innovators. Competitive moves center on M&A consolidation of regional banners and strategic partnerships with dark-store operators for last-mile compression.
Among scale-driven mass merchandisers, Walmart and Costco exemplify divergent paths within North American retail. Walmart anchors volume through supplier financing and distribution network control, while Costco sustains margin premiums through its Kirkland Signature private-label tier. Schwarz Group occupies a position within European discount positioning via its Lidl and Kaufland banners, demonstrating the sustainability of operational cost discipline across multiple national markets.
| Leading Market Players |
|---|
| Costco |
| Aldi |
| Walmart |
| Home Depot |
| Carrefour |
| Amazon |
| Kroger |
| Ahold Delhaize |
| Schwarz Group |
| Others |
Supply Flow & Price Mechanics
Hypermarket scale economies in India and Germany compress unit procurement costs while establishing price floors that independent kirana stores and discount banners struggle to match. The EU Green Deal's recycled content mandates add compliance premiums to personal care tiers, bifurcating margin structures between regulated and unregulated product categories.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across European retail networks, compelling reformulation investments that concentrate margin pressure in personal care and cleaning product lines. Three-tier pricing structure across premium, standard, and economy levels captures divergent shopper missions, with Costco's Kirkland Signature demonstrating how quality parity sustains premium positioning against national brands. Price differentiation rests on certification intensity and volume scale, with organic tiers commanding shelf-price elevation through USDA and EU organic labeling compliance. Cost compression in budget tiers intensifies as Schwarz Group's operational discipline forces margin compression across limited-assortment competitors. Households in urban Indian catchments exhibit highest price sensitivity, while quick-service restaurant procurement through wholesale tiers shows lowest sensitivity due to standardized supplier programs.
Supply Chain Analysis
Inventory velocity for perishable groceries demands sub-48-hour farm-to-shelf lead times that concentrate cold-chain investment in the Mumbai-Pune and Delhi-NCR corridors. Geographic supply concentration centers on India for fresh produce procurement, Germany for private-label manufacturing equipment, and the United States for automated fulfillment systems. Raw material dependencies hinge on agricultural inputs from concentrated growing regions, petroleum-derived packaging substrates, and lithium-ion battery cells for electric last-mile fleets. Single-source vulnerability in fresh produce creates exposure to climate-driven harvest volatility across Mediterranean and South Asian supplier bases. Distribution runs through centralized category management systems that consolidate supplier relationships under banner-specific quality protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organized retail penetration in tier-two Indian cities represents an early-cycle expansion story, with urban household migration from kirana stores to hypermarket catchments accelerating adoption velocity.
For Market Incumbents: Compound defensive positioning through backward integration into cold-chain infrastructure and captive private-label development capabilities. Schwarz Group's Lidl and Kaufland banners demonstrate how operational cost discipline defends margin structure against hard discount challengers. Threats from quick-commerce dark-store operators demand channel control investments in micro-fulfillment networks. Certification investment in EU Green Deal compliance creates supplier financing leverage over smaller competitors lacking reformulation scale. For New Entrants and Emerging Players: Lead with white-space targeting in Lucknow, Indore, and Kochi before organized retail saturation compresses first-mover returns. Tier-two Indian cities offer the most penetrable geography, with nascent modern trade penetration and concentrated urban household formation. Direct-to-institutional procurement through FSSAI-compliant supply chains provides a go-to-market angle bypassing established retail banner relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors logistics innovators with dark-store micro-fulfillment capabilities over traditional real estate-heavy retail formats. Long-term viability over a 5-10 year window rests on automation density and last-mile compression rather than store count expansion. Acquisition target archetype: regional banners with established cold-chain infrastructure in underpenetrated Indian corridors. The signal to watch is quick-service restaurant procurement standardization creating volume concentration for approved supplier programs.| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Micro-Fulfillment Network Expansion | Sub-30-minute delivery windows in Tokyo and Mumbai corridors compress last-mile cost structures. |
| EU Green Deal Compliance Repositioning | Recycled content minimums in personal care lines force competitor margin compression ahead of deadlines. |
| Backward Integration into Cold-Chain Infrastructure | Captive refrigeration assets in India reduce perishable spoilage rates below distributor-dependent rivals. |
| Quick-Service Restaurant Wholesale Tier Development | Case-lot configurations for chain restaurant procurement standardize volume concentration. |
| Private-Label Quality Tier Elevation | Kirkland Signature parity positioning sustains margin premiums against national brand competitors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with category buyers at mass merchandisers, supply chain directors at quick-service restaurant chains, cold-chain logistics operators, and private-label development managers. Secondary validation drew from FSSAI enforcement records, EU Green Deal regulatory filings, Nielsen retail audit data, and customs trade statistics for agricultural inputs. Bottom-up store-level demand estimation triangulated against top-down macroeconomic consumption indicators.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type, distribution channel, customer type, and pricing tier alongside regional regulatory cluster variations. CAGRs were derived from trend extrapolation moderated by penetration ceiling assumptions and infrastructure investment trajectories. Forecast inputs incorporated urban household migration patterns in Indian metro corridors and EU packaging mandate compliance timelines.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain infrastructure investment or regulatory enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding organized retail displacement velocity and quick-commerce adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Thailand Retail Market
Retailing
China Retail Market
Retailing
Qatar Retail Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Australia Retail Bags Market
Retailing
European Discount Retail Market
Retailing
Consumer Products and Retail Market
Retailing
Gift Baskets Market
Retailing
Floor Displays Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
United States Hardware Stores Retail Market
Retailing
Home Shopping Market
Retailing
Retail Vending Machine Market
Retailing
North America Retail Vending Machine Market
Retailing
Singapore Gifting Market
Retailing
Consumer Shopping Cart Market