
 Retail Display Racks Market | 2026-2036
Retail Display Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Display Racks Market Analytics
Modular lightweighting and digital integration in fixture design is tilting production priorities across the supply base. Lozier Corporation leverages its domestic manufacturing footprint to sustain rapid-turn custom programs for national grocery chains. Madix Inc. anchors its competitive stance through vertical control over wire-forming and powder-coating operations. Eisho Co., Ltd. differentiates by specializing in precision-engineered tabletop units for cosmetics and electronics showrooms.
Retail display racks are engineered steel, aluminum, wood, or polymer structures designed to present merchandise at optimal sightlines and accessibility heights, typically rated for loads between 50 and 500 kilograms per shelf tier depending on gauge and bracing configuration. Their primary commercial purpose is to maximize product facings per square meter of selling floor while enabling rapid planogram reconfiguration. Floor standing units dominate volume shipments owing to their versatility across supermarket aisle and perimeter applications, where metal construction commands preference for durability and fire-code compliance. Customized sizing represents the fastest-expanding dimension as retailers pursue fixture programs tailored to store-specific footprints and seasonal campaign requirements.
The U.S. EPA oversees volatile organic compound emissions from powder-coating and finishing operations, while OSHA mandates load-safety standards for warehouse and floor-stacked rack assemblies; the EU's REACH framework restricts certain chromate treatments and mandates material disclosure for metal substrates sold into member states. These regulatory layers elevate compliance costs for smaller fabricators and favor suppliers with in-house testing and certification capabilities. Stakeholders must monitor evolving extended-producer-responsibility proposals in Europe and California that could impose end-of-life recovery obligations on fixture manufacturers.
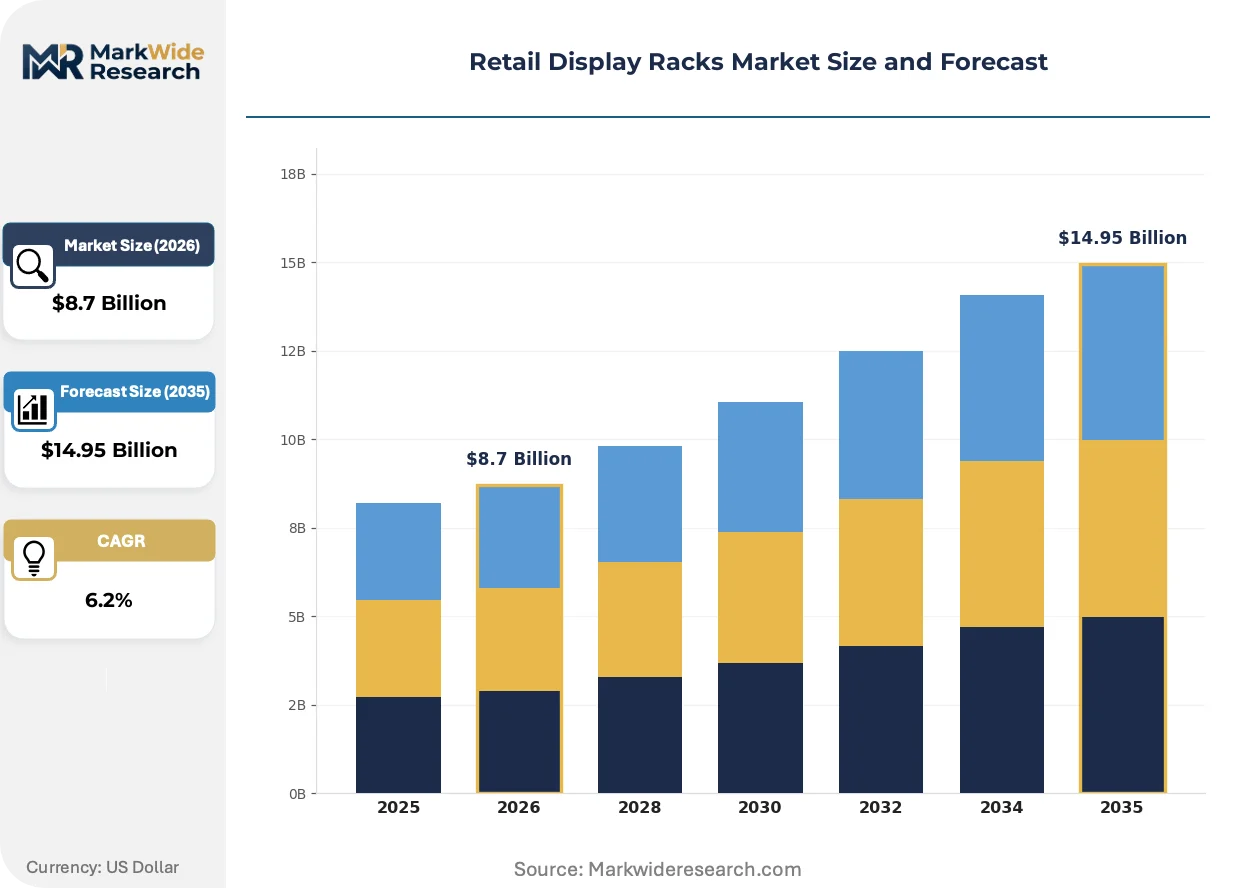
Market Dynamics
Supermarket chains are consolidating fixture procurement under centralized category-management offices, compressing supplier margins while demanding faster program turnaround and digital-ready rack specifications.
Growth Catalysts
- REACH material-disclosure mandates:European retailers now require full substrate documentation, favoring suppliers with pre-certified aluminum and steel alloys that streamline compliance documentation.
- Private-label shelf-space expansion:Grocery chains in the United States are dedicating 15-25% more linear footage to house-brand merchandise, requiring customized rack configurations with enhanced visibility features.
- Recyclable alloy formulations:Advances in low-carbon steel production and post-consumer aluminum recovery are enabling closed-loop manufacturing programs that satisfy circular-economy procurement criteria.
Market Restraints
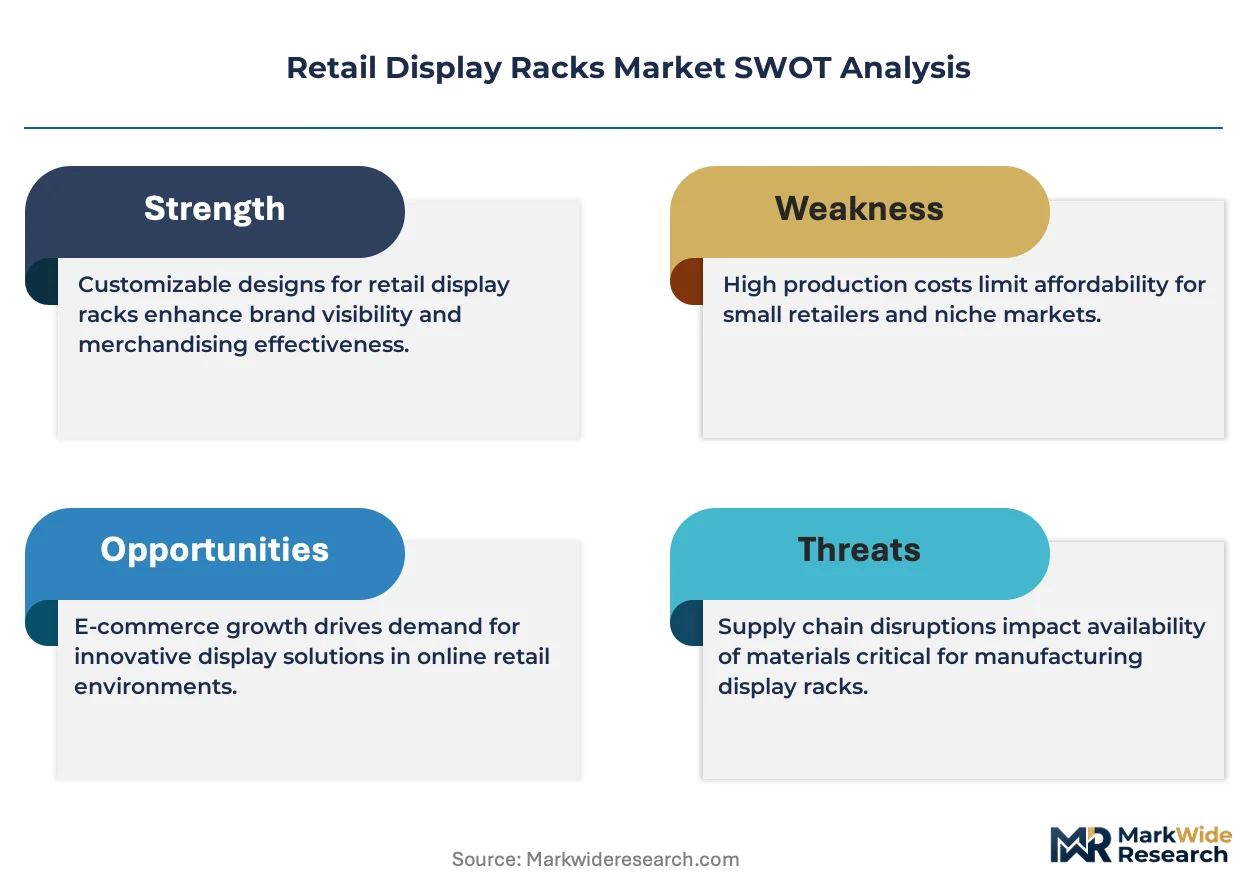
- Steel price volatility:Cold-rolled coil and galvanized sheet inputs fluctuate with energy costs and trade policy, squeezing fabricator margins on fixed-price annual contracts.
- Powder-coating VOC compliance:EPA emission limits in the United States and parallel state-level rules in California force capital investment in thermal-oxidizer or waterborne-coating systems.
- Structural substitution risk:Permanent digital signage and interactive kiosks in electronics and cosmetics showrooms reduce reliance on physical product-facing racks.
Strategic Opportunities
- India organized retail buildout:Reliance Retail and Avenue Supermarts are expanding formats that specify modular, reconfigurable metal fixtures for rapid seasonal resets.
- EU Green Deal procurement incentives:Member-state public tenders now weight embodied-carbon metrics, creating preference for domestic European fabricators with verified low-carbon supply chains.
- RFID-integrated rack systems:Convergence of inventory-tracking sensors with standard shelving enables real-time stock monitoring, attracting grocery and pharmacy chains.
Industry Challenges
- Fire-code certification timelines:UL 263 and ASTM E119 testing for load-bearing metal assemblies adds 8-14 weeks to new product launches, delaying revenue recognition.
- Legacy ERP integration:Custom fixture configurators must interface with retailer-specific planogram software, requiring bespoke middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Display Racks Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Floor Standing, Wall Mounted, Tabletop, Freestanding Material: Metal, Wood, Plastic, Glass Application: Supermarkets, Retail Stores, Trade Shows, Showrooms Size: Small, Medium, Large, Customized |
| Companies Covered | iYubo, Storflex, Lozier Corporation, Supermarket Equipment Etc., Inc., Trion Industries, Madix Inc., RUMIS, Econoco, Eisho Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Display Racks Market Evolving Landscape
Fixture engineering is pivoting from static metal structures to intelligent, sensor-enabled platforms that synchronize physical presentation with digital inventory systems and dynamic pricing.
Embedded weight-sensing shelves and edge-computing modules are collapsing the distinction between storage infrastructure and real-time data capture. Mass-merchandise retailers in Germany and France are piloting these systems for automated replenishment alerts. The technology is collapsing traditional fixture procurement into broader store-automation capital budgets, marginalizing standalone rack suppliers without IoT partnerships.
The EU's F-Gas Regulation and parallel EPA SNAP program are accelerating phase-out of hydrofluorocarbon-based foam insulation in refrigerated display cases, indirectly pressuring adjacent rack manufacturers to certify thermal-break compatibility. Fabricators serving supermarket perimeter departments must now validate gasket and frame interfaces against new refrigerant chemistries. German engineering offices and Italian metalworkers are absorbing the bulk of redesign costs to maintain access to EU-27 retail chains.
Buyer consolidation among dollar-store and off-price banners is compressing specification cycles from annual to quarterly refresh rates. Procurement teams at TJX Companies and Dollar General now demand 6-week turnaround on custom sizing, displacing traditional 16-week program schedules. This compression is most visible in the southeastern United States, where rapid format expansion is concentrating demand among regional fabricators with captive powder-coating and wire-forming capacity.
Retail Display Racks Market Segmentation
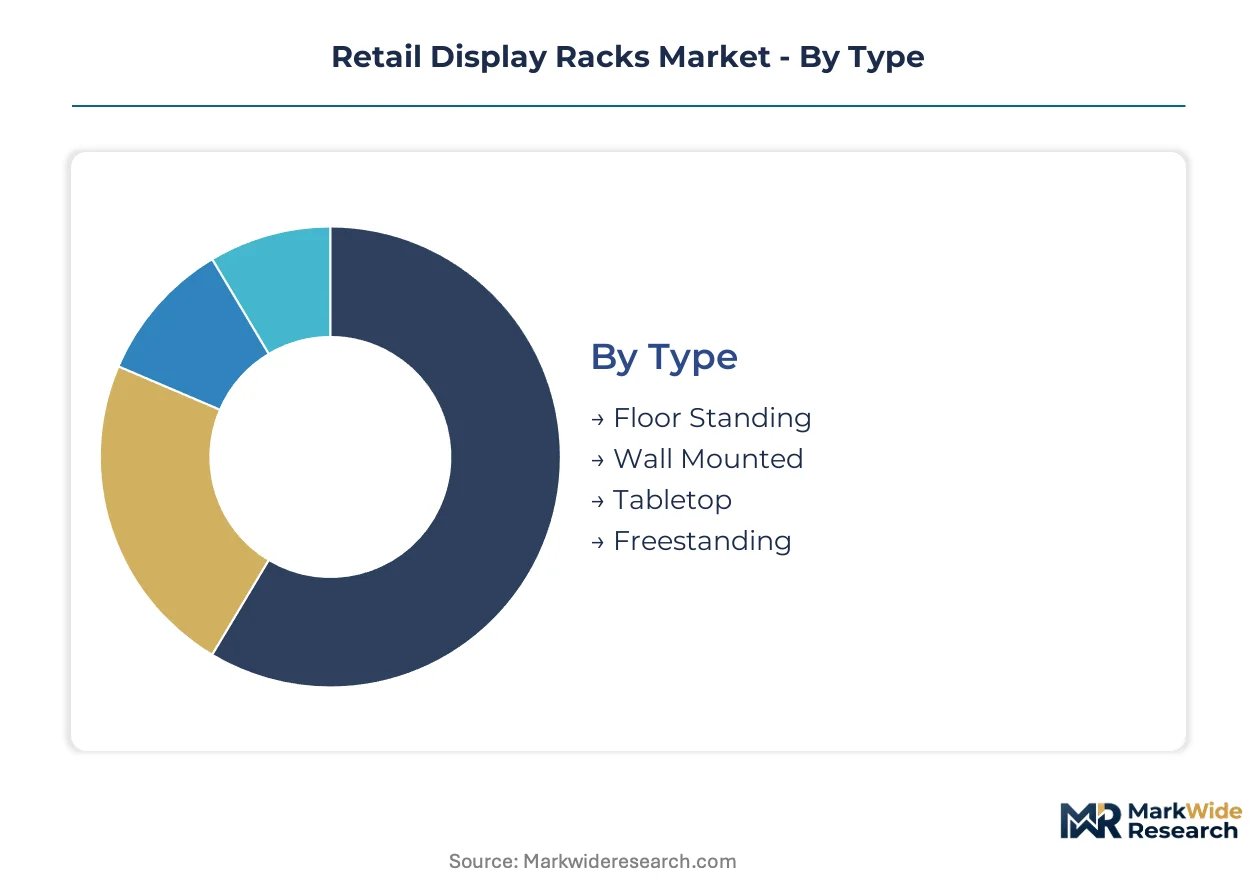
Fixture procurement cycles vary dramatically across segment boundaries. Supermarket category managers reset floor-standing metal systems on 3-5 year horizons while tabletop cosmetic displays rotate quarterly. Understanding these velocity differentials sharpens inventory positioning and capacity planning for fabricators.
Type:
Floor-standing units turn over slowest due to capital intensity and fire-code recertification burdens, while tabletop displays refresh fastest to chase seasonal merchandising calendars.
- Floor Standing:Steel and aluminum assemblies rated for 200-500 kg per tier anchor supermarket aisle and perimeter layouts. Grocery chains in the United States specify these for private-label expansion zones requiring maximum product facings and structural longevity under daily restocking cycles.
- Wall Mounted:Vertical track systems and slatwall-compatible brackets optimize selling floor density in constrained urban formats. German mass-merchandisers favor these for automated replenishment pilots where embedded weight sensors demand rigid structural anchoring.
- Tabletop:Precision-engineered units for cosmetics and electronics showrooms enable rapid planogram resets.
- Freestanding:Modular island configurations support seasonal campaign flexibility without permanent installation.
Floor Standing anchors the volume base while Tabletop gains share at the steepest rate.
Material:
Cost tiers separate commodity inputs from certified alloys carrying embodied-carbon documentation for EU Green Deal compliance.
- Metal:Cold-rolled steel and aluminum alloys dominate supermarket and big-box specifications for load-bearing capacity and fire-code compliance. REACH material-disclosure mandates favor suppliers with pre-certified substrate documentation, compressing margins for fabricators lacking in-house testing capabilities.
- Wood:Plywood and hardwood finishes serve specialty retail and showroom applications requiring warmth and brand customization.
- Plastic:Polymer injection-molded units address temporary promotional and trade-show deployment.
- Glass:Tempered shelving elevates premium cosmetic and electronics presentation.
Metal commands the installed base while Glass climbs fastest among experience-focused retail formats.
Application:
Customer concentration patterns concentrate procurement leverage among centralized category-management offices.
- Supermarkets:High-volume fixture programs with standardized sizing and rapid-turn custom capabilities. Chains in India specify modular metal systems for format expansion, while U.S. operators dedicate expanded linear footage to private-label visibility.
- Retail Stores:Department and specialty banners demand configurable systems supporting frequent seasonal resets.
- Trade Shows:Lightweight, collapsible structures prioritize transport efficiency and tool-free assembly.
- Showrooms:Permanent installations for automotive, furniture, and electronics presentation emphasize durability and aesthetic integration.
Supermarkets anchor the volume base while Showrooms expand most quickly on experience-investment trends.
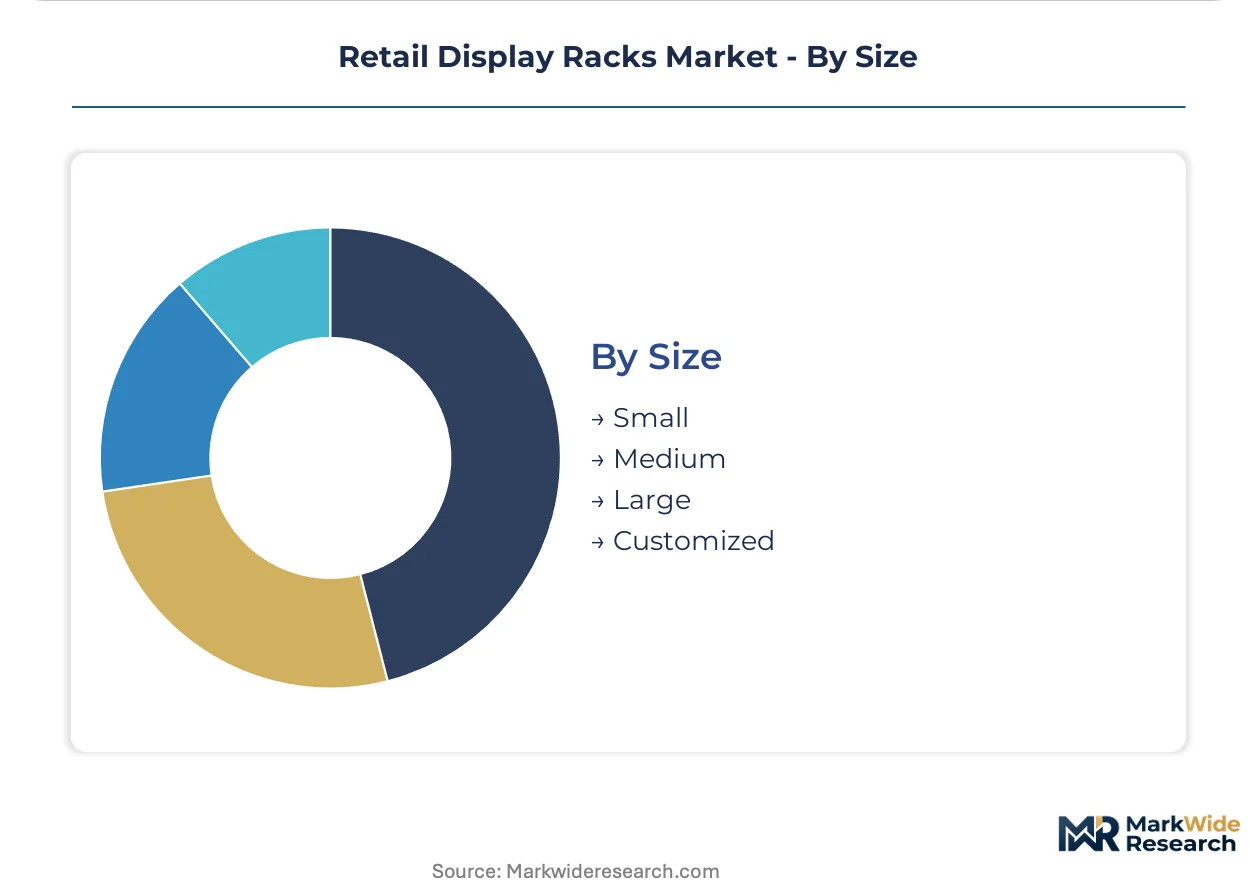
Size:
Specification granularity separates stock programs from engineered-to-order workflows with divergent margin profiles.
- Small:Countertop and end-cap units for impulse merchandise and checkout adjacencies. Dollar-store procurement consolidation in the southeastern United States compresses turnaround demands to six-week cycles.
- Medium:Standard gondola and four-way fixture dimensions matching planogram software libraries.
- Large:Perimeter wall systems and promotional stacks for high-volume categories.
- Customized:Store-specific dimensions tailored to footprint constraints and seasonal campaign requirements represent the fastest-expanding dimension as retailers pursue fixture programs rejecting one-size-fits-all approaches.
Medium sizes anchor the volume base while Customized gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fabricators export standardized metal rack systems to supermarket chains across Southeast Asia and the Middle East, while German engineering offices supply precision-engineered fixtures to EU-27 retailers under Green Deal procurement criteria.
United States
Big-box retailers in Texas and the Southeast are modernizing store formats with rapid-turn custom fixture programs. EPA volatile organic compound emission limits from powder-coating operations elevate compliance costs for smaller fabricators. Regional fabricators in Georgia and North Carolina concentrate captive wire-forming and powder-coating capacity to serve dollar-store procurement consolidation.
Germany
Mass-merchandisers pilot automated replenishment systems using weight-sensing shelf modules in Frankfurt and Berlin metro formats. The EU F-Gas Regulation pressures perimeter rack manufacturers to certify thermal-break compatibility with new refrigerant chemistries. Engineering offices in Stuttgart and Milan absorb redesign costs to maintain access to EU-27 retail chains.
China
Domestic supermarket expansion drives specification of modular, reconfigurable metal fixtures for seasonal resets in Shanghai and Shenzhen. The country's national environmental regulator enforces industrial emission standards on coating and finishing operations. Fabrication clusters in Zhejiang and Guangdong provinces export volume shipments to Southeast Asian retail buildouts.
India
Reliance Retail and Avenue Supermarts specify modular metal systems for format expansion in Maharashtra and Karnataka. The Bureau of Indian Standards mandates load-safety certifications for warehouse and floor-stacked rack assemblies. Fabricators in Gujarat and Tamil Nadu scale capacity to serve organized retail growth in Tier-1 and Tier-2 cities.
France
Cosmetics and electronics showrooms in Paris and Lyon invest in precision-engineered tabletop displays for quarterly planogram rotations. REACH material-disclosure mandates require full substrate documentation for metal substrates sold into member states. Italian metalworkers in Milan coordinate with French retailers on circular-economy procurement criteria for low-carbon aluminum alloys.
Retail Display Racks Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor base organizes around three archetypes: domestic full-service fabricators with captive coating capacity, precision-engineered tabletop specialists, and scale-driven volume producers serving private-label expansion programs. Consolidation pressures concentrate among supermarket category-management offices demanding faster turnaround and digital-ready specifications. Competitive moves center on backward integration into wire-forming operations and strategic partnerships with IoT sensor providers.
Among U.S.-based fabricators, Lozier Corporation and Madix Inc. exemplify the domestic full-service archetype with captive manufacturing footprints. Eisho Co., Ltd. occupies a position within the precision-engineered tabletop tier, representing Japanese engineering specialization for cosmetics and electronics showroom applications. These three anchors illustrate how geographic concentration and vertical control separate procurement winners from margin-compressed commodity suppliers.
| Leading Market Players |
|---|
| iYubo |
| Storflex |
| Lozier Corporation |
| Supermarket Equipment Etc., Inc. |
| Trion Industries |
| Madix Inc. |
| RUMIS |
| Econoco |
| Eisho Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Zhejiang and Guangdong provinces to Long Beach and Savannah anchor cost dynamics that cascade through supply concentration and downstream price differentiation. Steel coil shipments from these clusters face demurrage volatility that compresses margins for fabricators lacking captive coating capacity, while buyers in Texas and the Southeast absorb premium pricing for rapid-turn custom programs.
Pricing Analysis
Static metal rack systems, sensor-integrated intelligent fixtures, and legacy wire-form configurations stratify across three performance tiers. Cold-rolled steel assemblies with UL 263 fire-code certification command premium positioning against commodity imports lacking substrate documentation. Pricing pressure stems from supermarket category-management consolidation demanding 6-week turnaround cycles. Dollar-store procurement teams exhibit highest price sensitivity, whereas cosmetics showroom operators prioritize precision engineering over unit cost.
Supply Chain Analysis
Contract manufacturing clusters in Zhejiang province, Guangdong fabrication hubs, and captive wire-forming operations in Georgia and North Carolina concentrate production capacity. Raw material flows draw from cold-rolled coil mills, aluminum smelters, and powder-coating chemical suppliers. Single-source vulnerability runs through Chinese substrate dependence for standardized volume shipments. Distribution feeds through regional fabricators with captive finishing capacity serving national grocery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID-integrated rack systems and embedded weight-sensing modules are reshaping fixture procurement into store-automation capital budgets, creating disruption velocity that favors suppliers with IoT partnerships.
For Market Incumbents: Pre-empt structural substitution risk from permanent digital signage by accelerating sensor-integrated product development and securing exclusive IoT provider partnerships. Backward integration into wire-forming and powder-coating operations defends margin position against steel price volatility. Fire-code certification investments create switching costs for supermarket category managers. For New Entrants and Emerging Players: Pursue precision-engineered tabletop segments in Indian organized retail buildout where Reliance Retail and Avenue Supermarts specify modular systems for format expansion. White-space concentration appears in EU Green Deal procurement where domestic fabricators with verified low-carbon supply chains capture member-state public tenders. Partner with German engineering offices on thermal-break compatibility certification to access EU-27 retail chains. For Investors and Strategic Acquirers: Regional fabricators with captive coating capacity in the southeastern United States represent acquisition targets positioned to serve dollar-store procurement consolidation. Long-term viability hinges on differentiation from commodity imports through digital integration capabilities. Monitor supermarket private-label expansion rates as inflection indicator for custom fixture demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire-Forming | Captive supply of precision-formed components compresses turnaround cycles for national grocery chains. |
| IoT Sensor Partnership Formation | Collaboration with RFID providers collapses fixture procurement into broader store-automation budgets. |
| EU Green Deal Certification Investment | Verified low-carbon aluminum documentation unlocks member-state public tender preferences. |
| Rapid-Turn Custom Program Development | Six-week specification cycles capture dollar-store and off-price banner consolidation. |
| Fire-Code Testing Capability Expansion | In-house UL 263 certification reduces new product launch timelines by 8-14 weeks. |
Research Methodology
Cross-validation between primary interviews with fixture procurement managers, category management executives, powder-coating operations directors, and IoT integration specialists anchors the qualitative findings against secondary validation from EPA emission filings, REACH material-disclosure registries, and supermarket capital expenditure disclosures. Bottom-up fabrication capacity assessments triangulate with top-down retail fixture spend estimates across the analysis window.
Calibration against historical procurement cycle data and steel price volatility indices shapes the analytical framework. Segmentation dimensions span fixture type, material certification tier, application velocity, and geographic regulatory cluster. CAGRs derive from regression against private-label expansion rates and organized retail square footage buildout. Sensor integration adoption curves and circular-economy procurement weightings inform projection sensitivity.
Sensitivities concentrate around steel price volatility, REACH regulatory expansion, and digital substitution acceleration in cosmetics and electronics showrooms. Forecasts reflect assumptions on supermarket consolidation pace and EU Green Deal enforcement stringency. Quarterly review of fixture procurement cycle compression and IoT partnership announcement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Retail Vending Machine Market
Retailing
Vietnam Retail Market
Retailing
Out-Door Signage Market
Retailing
European Discount Retail Market
Retailing
Out Store Signage Market
Retailing
Thailand Retail Market
Retailing
Qatar Retail Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Gift Baskets Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
China Retail Market
Retailing
Floor Displays Market
Retailing
United States Hardware Stores Retail Market
Retailing
Consumer Shopping Cart Market
Retailing
Floor Mat Rental Service Market
Retailing
Home Shopping Market