
 North America Retail Vending Machine Market | 2026-2036
North America Retail Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
North America Retail Vending Machine Market Analytics
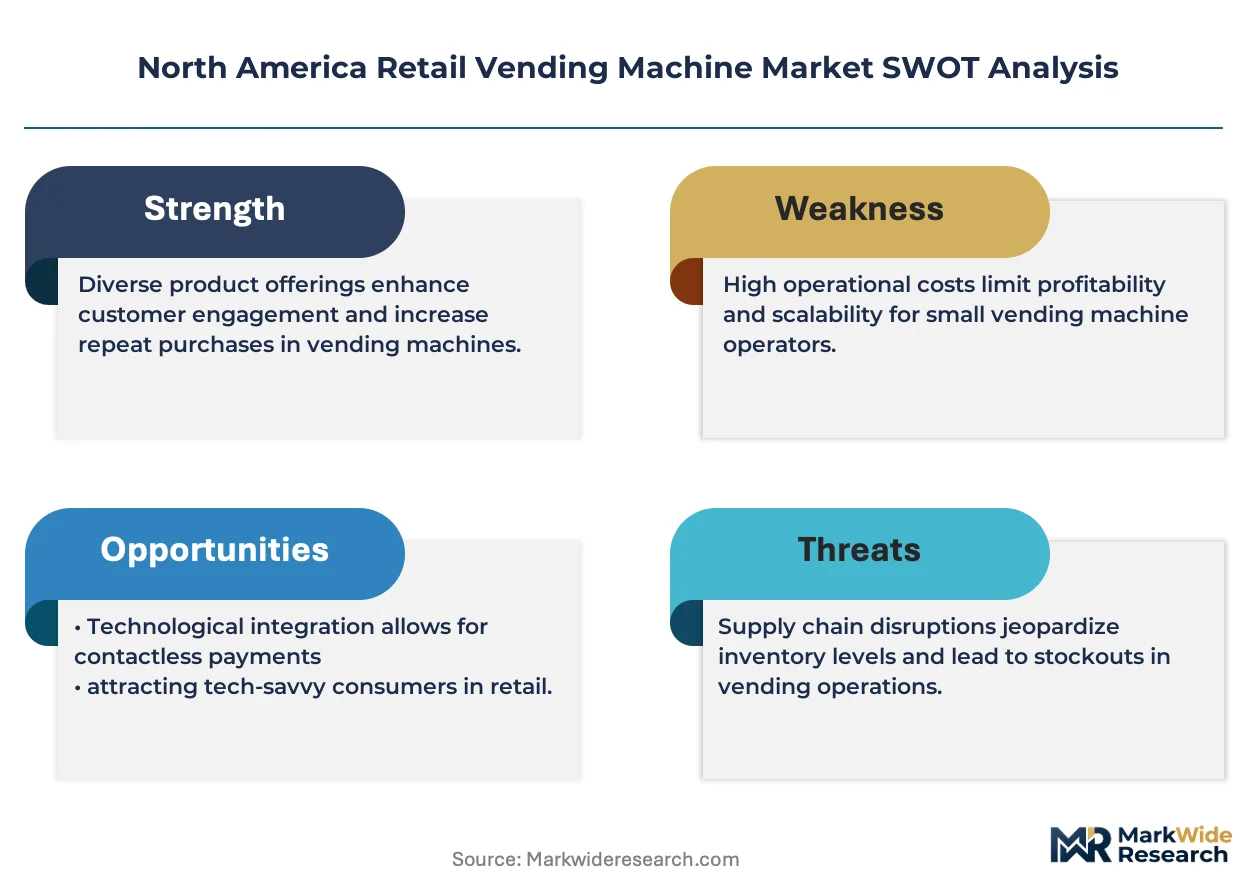
Subscription-based telemetry and remote machine management is expanding as a core revenue layer beyond hardware sales. Crane Merchandising Systems leverages its vertical integration into payment processing and cloud analytics to sustain recurring revenue streams. Fuji Electric Co Ltd anchors its position through compressor technology leadership that controls energy efficiency benchmarks in refrigerated units. Cantaloupe Inc differentiates via software-defined vending platforms that enable dynamic pricing and real-time inventory optimization.
North America retail vending machines are electromechanical dispensing systems integrating refrigeration, payment processing, and telemetry for unattended retail of packaged goods, fresh food, and hygiene products; units typically operate within temperature ranges of 2°C to 5°C for perishables and incorporate UL-certified electrical assemblies for commercial safety. The technology dimension shows cashless systems and IoT-enabled machines capturing margin pools as operators prioritize payment flexibility and predictive maintenance capabilities over traditional mechanical units. Beverage and fresh food segments attract capital allocation as healthcare facilities and educational institutions expand healthy-option procurement standards.
The FDA and USDA set food safety and labeling requirements that directly shape cold-chain vending machine specifications and operator compliance costs across the United States. Health Canada and PMRA enforce parallel standards in Canadian provinces, while NHTSA guidelines influence mobile and transit-hub installation safety protocols. Stakeholders must monitor evolving cashless payment regulations and state-level sugar taxation policies that could redirect product mix decisions.
Market Dynamics
Telemetry monetization and cold-chain compliance mandates are restructuring operator economics across the North America retail vending machine sector, compressing hardware margins while expanding recurring software revenue pools.
Growth Catalysts
- FDA Food Safety Modernization Act:Cold-chain vending specifications now mandate continuous temperature logging and rapid response protocols, forcing equipment upgrades and expanding the addressable market for compliant refrigerated units.
- Airport transit-hub expansion:Convenience retail operators in California's urban corridors and Texas metropolitan clusters are deploying automated fresh food access to capture captive traveler demand.
- IoT-enabled predictive maintenance:Cloud-connected compressor diagnostics reduce downtime costs and extend asset life, accelerating replacement cycles for legacy mechanical units.
Market Restraints
- Refrigerant input volatility:Hydrofluorocarbon phase-down schedules under EPA SNAP regulations compress margins for refrigerated unit manufacturers dependent on legacy cooling chemistries.
- Payment processor concentration:Cashless system reliance on a narrow set of certified payment networks creates single-point vulnerability for operators across the United States and Canada.
- Substitution by micro-fulfillment:Compact automated retail lockers in office buildings and residential towers displace traditional vending footprint in dense urban sub-markets.
Strategic Opportunities
- Educational institution procurement:Healthy-option mandates in K-12 and university foodservice programs create white space for fresh-food vending in underserved Canadian provinces and US Midwest corridors.
- Dynamic pricing algorithms:Software-defined platforms enable real-time inventory optimization and demand-responsive pricing, unlocking margin expansion beyond static mechanical dispensing.
- Healthcare facility expansion:24-hour patient and staff access requirements in hospitals and outpatient clinics drive demand for hygienic, temperature-controlled unattended retail.
Industry Challenges
- Cold-chain certification complexity:Multi-jurisdictional compliance across FDA, USDA, and Health Canada standards extends product launch timelines and strains engineering resources.
- Legacy system integration friction:Retrofitting IoT telemetry onto installed mechanical bases requires custom middleware development, complicating fleet-wide standardization.
- Field service technician scarcity:Electromechanical and refrigeration skill convergence demands hybrid training programs that outpace current vocational pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Retail Vending Machine Market |
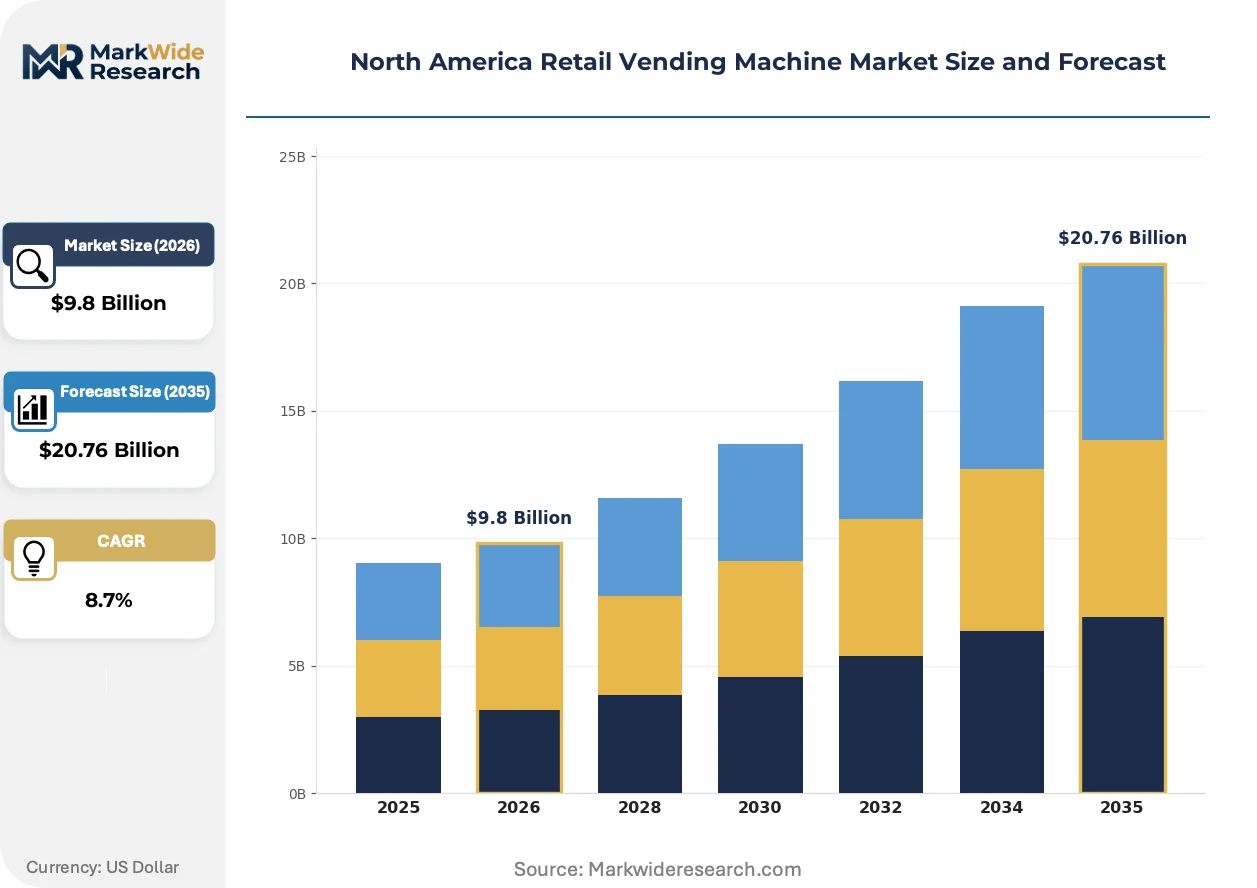
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Fresh Food, Hygiene Products End User: Businesses, Educational Institutions, Public Places, Healthcare Facilities Technology: Cashless Systems, Smart Vending, IoT-Enabled Machines, Traditional Machines Distribution Channel: Direct Sales, Online Sales, Third-Party Vendors, Franchise Outlets |
| Companies Covered | Crane Merchandising Systems, Azkoyen Group, Fuji Electric Co Ltd, Canteen Vending Services, Sanden Corp, Royal Vendors, Cantaloupe Inc, Selecta Group, Seaga Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Retail Vending Machine Market Evolving Landscape
Cashless payment architecture and cloud-native fleet management are displacing mechanical coin-op systems as the foundational layer of vending operator technology stacks.
Computer vision-based product recognition is converging with frictionless checkout systems in high-traffic locations. Airport operators in Dallas-Fort Worth and Toronto Pearson are piloting grab-and-go cabinets that eliminate selection interfaces entirely. This technology compression is collapsing the traditional vending transaction time from 45 seconds to under 10 seconds, reshaping throughput economics in constrained real estate.
The FDA's Food Safety Modernization Act traceability requirements are mandating lot-level tracking from supplier to point-of-sale. Vending operators must now integrate blockchain-enabled supply chain logs or risk disqualification from fresh food procurement contracts. Healthcare facility foodservice managers in California and Texas are prioritizing vendors with demonstrable cold-chain audit trails, filtering supplier pools.
Subscription telemetry contracts are displacing perpetual software licenses as the dominant commercial model. Operators in Chicago's metropolitan cluster and Vancouver's transit network are bundling remote machine management, dynamic pricing algorithms, and predictive maintenance into monthly per-unit fees. This shift locks in recurring revenue for equipment vendors while transferring technology obsolescence risk to service providers.
North America Retail Vending Machine Market Segmentation
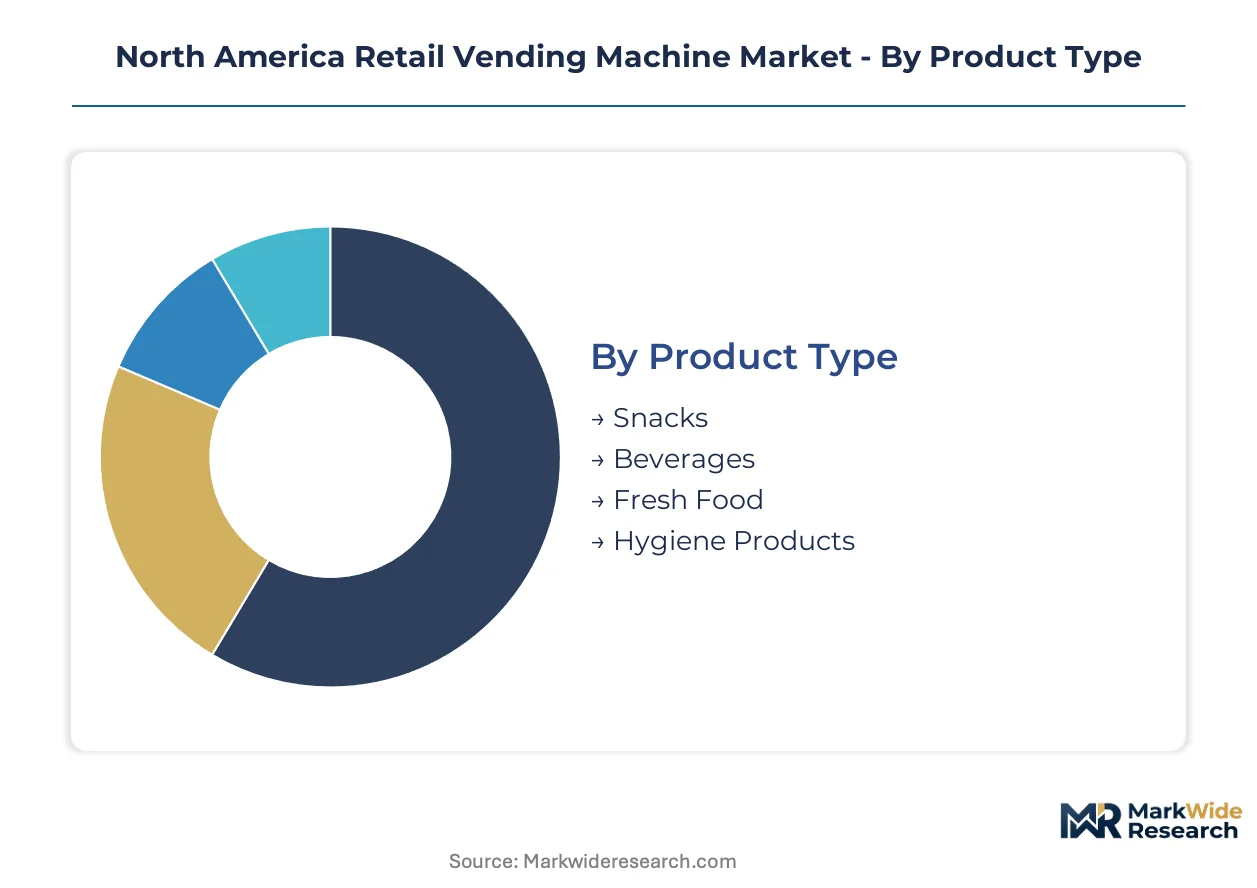
Segmentation in the North America retail vending machine market reveals divergent margin structures and technology requirements across product types, end users, and deployment models. Understanding these divisions exposes where capital allocation concentrates and where compliance costs reshape competitive viability.
Product Type:
Refrigeration intensity and temperature control specifications define the product type axis, separating high-complexity fresh food systems from ambient mechanical dispensers.
- Beverages:Refrigerated units with compressor systems maintaining 2°C to 5°C for bottled and canned drinks dominate installed base across Texas metropolitan clusters. California's urban corridors drive demand for energy-efficient cooling chemistries compliant with EPA SNAP phase-down schedules.
- Fresh Food:Precision cold-chain systems with continuous temperature logging and rapid response protocols satisfy FDA Food Safety Modernization Act mandates. Healthcare facilities in Chicago and Toronto prioritize these units for 24-hour patient access to perishable meals and salads.
- Snacks:Ambient electromechanical dispensers with UL-certified electrical assemblies serve high-traffic transit hubs with minimal maintenance overhead.
- Hygiene Products:Non-refrigerated cabinets with simplified payment interfaces address post-pandemic procurement standards in educational institutions and office complexes.
Beverages leads on scale; fresh food leads on momentum.
End User:
Procurement authority and operating hour requirements segment end users into distinct specification tiers with varying payment flexibility demands.
- Healthcare Facilities:Hospitals and outpatient clinics require hygienic, temperature-controlled unattended retail with 24-hour access for patients and staff. Dallas-Fort Worth medical centers are piloting computer vision-based grab-and-go cabinets to collapse transaction times.
- Educational Institutions:K-12 and university foodservice programs mandate healthy-option vending under procurement standards expanding across Canadian provinces and US Midwest corridors.
- Businesses:Corporate campuses and manufacturing facilities prioritize cashless payment flexibility and predictive maintenance capabilities over legacy mechanical reliability.
- Public Places:Airports and transit hubs in California and Texas metropolitan clusters deploy automated fresh food access to capture captive traveler demand with high-throughput interfaces.
Healthcare facilities leads on specification intensity; educational institutions leads on expansion velocity.
Technology:
Payment architecture and connectivity layers separate technology tiers, with cloud-native platforms displacing mechanical coin-op foundations.
- IoT-Enabled Machines:Cloud-connected units with compressor diagnostics and telemetry monetization capabilities reduce downtime costs and extend asset life. Operators in Vancouver's transit network bundle remote machine management into subscription contracts.
- Cashless Systems:Contactless payment terminals integrated with certified networks address processor concentration risks while satisfying consumer preference for card and mobile transactions.
- Smart Vending:Software-defined platforms with dynamic pricing algorithms and real-time inventory optimization unlock margin expansion beyond static mechanical dispensing.
- Traditional Machines:Coin-operated mechanical bases with limited telemetry face accelerated replacement cycles as retrofitting costs exceed replacement economics.
IoT-enabled machines leads on recurring revenue capture; smart vending leads on margin expansion potential.
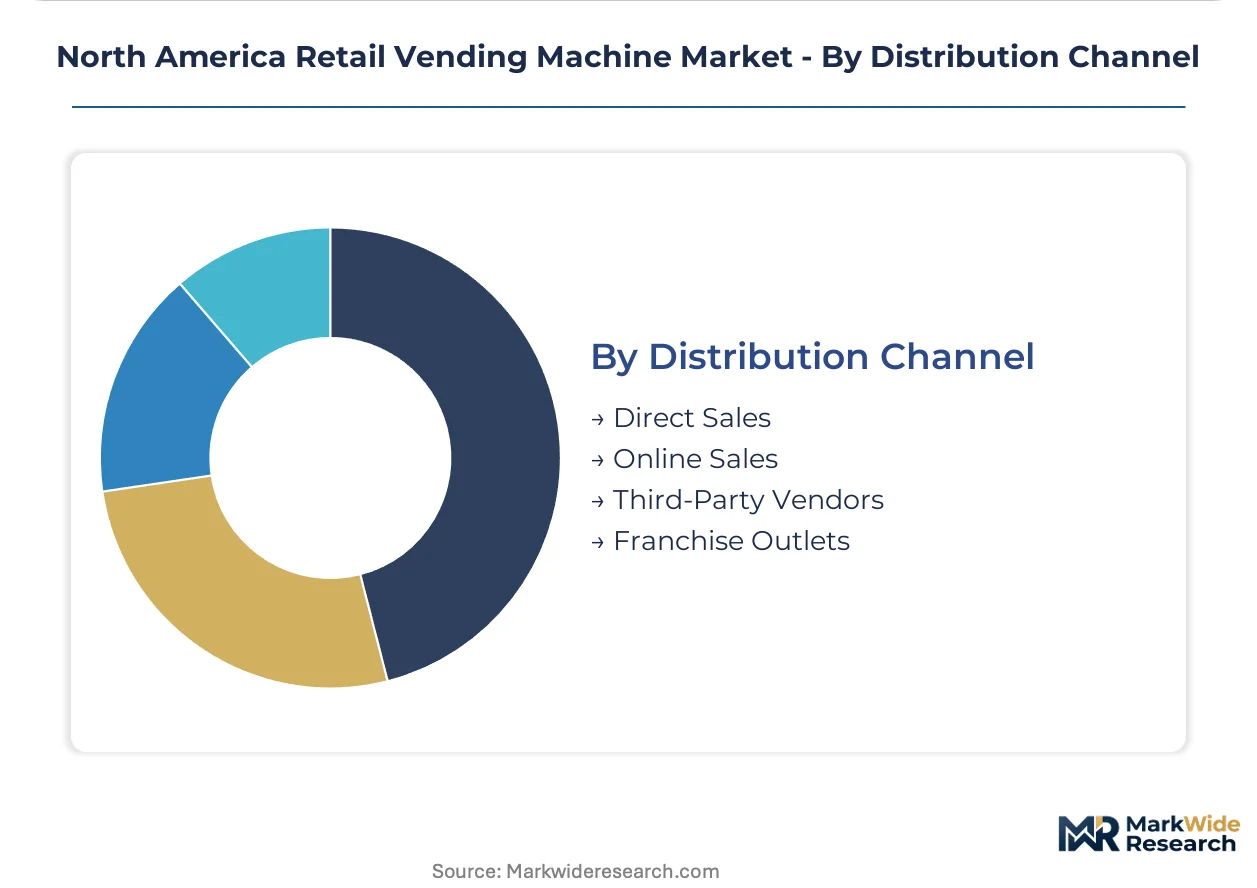
Distribution Channel:
Control over installation, service, and payment processing separates distribution models with divergent working capital and customer relationship structures.
- Direct Sales:Manufacturer-controlled deployment with captive service networks ensures specification compliance and telemetry standardization across fleet installations.
- Third-Party Vendors:Independent operators aggregate multiple equipment brands, fragmenting technology stacks but accelerating geographic penetration in secondary markets.
- Franchise Outlets:Branded vending networks with standardized product mix and operational protocols replicate proven models across state and provincial boundaries.
- Online Sales:E-commerce procurement of standard units with self-installation appeals to small operators minimizing upfront capital commitment.
Direct sales leads on technology integration; third-party vendors leads on geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the dominant share of regional vending deployment, while Canada exhibits faster telemetry adoption velocity per installed unit. Mexico's transit infrastructure investments are accelerating automated retail penetration in Guadalajara and Monterrey metropolitan clusters.
United States
Healthcare facility expansion and airport transit-hub modernization drive equipment procurement across Texas and California metropolitan corridors. FDA Food Safety Modernization Act mandates force continuous temperature logging upgrades in refrigerated units nationwide. Dallas-Fort Worth medical centers pilot computer vision-based grab-and-go cabinets to collapse patient transaction times.
Canada
Educational institution healthy-option procurement standards and Vancouver transit network telemetry bundling accelerate IoT-enabled machine deployment. Health Canada and PMRA enforce parallel cold-chain standards to FDA requirements, extending compliance engineering timelines. Toronto Pearson International Airport tests frictionless checkout systems for captive traveler demand capture.
Mexico
Manufacturing facility automation and Guadalajara metropolitan retail modernization expand unattended vending access. The country's federal consumer protection agency enforces payment terminal certification standards for cashless system reliability. Monterrey industrial parks deploy hygienic vending for 24-hour production floor access.
North America Retail Vending Machine Market Competitive Landscape
Top-tier vendors anchor the integrated systems tier, while mid-scale specialists compete on regional service density and retrofit flexibility. The vendor base spans three structural tiers: full-stack manufacturers with captive payment processing, component specialists dominating compressor and refrigeration subsystems, and software-defined platform operators monetizing telemetry subscriptions. Consolidation pressures favor M&A activity among payment processing aggregators and geographic expansion by European-origin equipment fabricators into underserved US Midwest corridors.
Among the named participants, Crane Merchandising Systems and Fuji Electric Co Ltd occupy positions exemplifying vertical integration archetypes across hardware and energy-efficiency subsystems, while Cantaloupe Inc represents the software-defined platform model with recurring revenue telemetry contracts. Azkoyen Group and Sanden Corp anchor European and Asian-origin specialist positions respectively. Seaga Manufacturing exemplifies the mid-tier regional fabricator archetype with standardized unit configurations.
| Leading Market Players |
|---|
| Crane Merchandising Systems |
| Azkoyen Group |
| Fuji Electric Co Ltd |
| Canteen Vending Services |
| Sanden Corp |
| Royal Vendors |
| Cantaloupe Inc |
| Selecta Group |
| Seaga Manufacturing |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA-compliant cold-chain systems and ambient mechanical units splits both pricing power and sourcing strategies across the North America retail vending machine market. Premium refrigerated platforms command substantial markups for continuous temperature logging capabilities, while commodity snack dispensers compete on volume scale and minimal service overhead.
Pricing Analysis
Capacity additions in Mexico and Southeast Asia are reshaping price floors for compressor assemblies and electromechanical components. Three-tier pricing structure across premium IoT-enabled, standard refrigerated, and economy ambient units reflects UL certification levels and telemetry bundling intensity. Cost compression in economy ambient tiers is intensifying because of micro-fulfillment locker substitution in dense urban corridors. Educational institutions exhibit highest price sensitivity due to constrained procurement budgets, while healthcare facilities prioritize specification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for semiconductor controllers and China for compressor motor assemblies. Component sourcing draws from Mexico for electromechanical fabrication, Japan for precision refrigeration valves, and domestic US facilities for final assembly integration. Raw material dependencies include copper winding stock, hydrofluorocarbon refrigerants under EPA SNAP phase-down pressure, and cold-rolled steel for cabinet enclosures. Tariff exposure on Chinese electronic controllers creates margin volatility for mid-tier fabricators. Distribution runs through manufacturer-direct service networks for enterprise healthcare deployments and fragmented third-party vendor channels for transit-hub installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America retail vending machine market functions as a stable compounder, with FDA Food Safety Modernization Act mandates ensuring sustained equipment replacement cycles across refrigerated installed bases.
For Market Incumbents: Hedge refrigerant transition risk by accelerating R&D into natural cooling chemistries ahead of EPA SNAP enforcement timelines. Deepen backward integration into payment processing infrastructure to offset processor concentration vulnerability. Secure exclusive service contracts with Dallas-Fort Worth and Toronto Pearson airport operators to defend against European equipment fabricators expanding into North American transit hubs. For New Entrants and Emerging Players: Computer vision-based frictionless checkout systems offer a technology-first wedge into healthcare facility grab-and-go procurement. Target underserved Canadian provinces and US Midwest educational corridors where healthy-option vending mandates outpace incumbent service density. Pursue software-defined platform partnerships with existing vending operators rather than capital-intensive hardware manufacturing entry. For Investors and Strategic Acquirers: Consolidation pressure builds where payment processing aggregators lack captive hardware manufacturing capabilities. The market supports long-term compounder positioning through recurring telemetry subscription revenue pools displacing transactional equipment sales. Acquisition target archetype: regional service operators with dense installed bases in Texas and California metropolitan clusters lacking IoT retrofit capabilities. Monitor FDA enforcement intensity on cold-chain traceability requirements as inflection indicator for fresh-food vending equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Cloud-native fleet management locks in recurring revenue beyond hardware margins for Crane Merchandising Systems and Cantaloupe Inc. |
| Refrigerant Technology Transition | Natural cooling chemistry R&D responds to EPA SNAP phase-down schedules compressing legacy hydrofluorocarbon margins. |
| Healthcare Facility Partnership | 24-hour patient access contracts with Dallas-Fort Worth medical centers validate computer vision grab-and-go deployment economics. |
| Educational Institution Expansion | Healthy-option procurement mandates in Canadian provinces and US Midwest corridors open white-space penetration for fresh-food vending. |
| Payment Infrastructure Control | Captive processing networks insulate operators from single-point vulnerability in certified payment network concentration. |
Research Methodology
Direct dialogue with vending operator fleet managers, OEM procurement directors, healthcare facility foodservice executives, airport concession operators, and refrigeration component suppliers grounded the qualitative foundation. Secondary validation drew from FDA enforcement databases, EPA SNAP regulatory filings, SEC 10-K disclosures from listed equipment vendors, and customs trade data on compressor assembly imports. Bottom-up unit economics modeling triangulated against top-down market sizing across installed base and replacement cycle assumptions.
Segmentation outputs across product type, end user, technology tier, and distribution channel structured the analytical framework across the projection horizon. CAGRs were derived from equipment shipment trajectories, telemetry subscription attach rates, and cold-chain compliance-driven replacement elasticities. Forecast inputs incorporated refrigerant phase-down schedules, airport transit-hub expansion pipelines, and educational procurement mandate adoption curves.
The model holds under steady FDA enforcement intensity and stable payment network certification standards; deviation in refrigerant regulation acceleration or cashless payment fraud incidence would shift replacement timing and operator technology investment priorities. Forecasts reflect documented assumptions on telemetry monetization velocity and cold-chain certification complexity timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Gift Baskets Market
Retailing
Subscription Box Market
Retailing
Furniture Rental Service Market
Retailing
United States Hardware Stores Retail Market
Retailing
Global Food and Non-Food Retail Market
Retailing
Singapore Gifting Market
Retailing
Philippines Retail Industry Market
Retailing
China Retail Market
Retailing
Floor Mat Rental Service Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Floor Displays Market
Retailing
Out-Door Signage Market
Retailing
Electronics Retailing Market
Retailing
Clothing Retail Market
Retailing
Thailand Retail Market
Retailing
Home Shopping Market