
 Australia Retail Bags Market | 2026-2036
Australia Retail Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Retail Bags Market Insights
Buyer consolidation among Australia's supermarket duopoly is repositioning procurement leverage toward volume-contracting chains with dedicated sustainability mandates. Detmold Group leverages its integrated fiber-pulp operations to supply major grocery banners with kraft-paper alternatives at scale. Visy Industries anchors containerboard recycling loops that feed directly into retail bag manufacturing, sustaining cost advantages in paper-based segments. Amcor competes through specialty barrier coatings that extend paper bag functionality into wet-grocery applications previously reserved for plastic.
Retail bags are engineered carry containers manufactured from HDPE, LDPE, kraft paper, or biodegradable polymers, typically specified by load capacity, tear resistance, and seal integrity to transport consumer purchases from point-of-sale. Their primary commercial purpose centers on brand visibility, product protection, and regulatory compliance across checkout environments. Paper bags and compostable bags are capturing structural margin pools as single-use plastic restrictions harden, while reusable bags face demand saturation in metropolitan supermarkets where consumer stockpiling has outpaced replacement cycles. HDPE and LDPE segments still dominate transaction volumes in convenience stores and specialty shops with lighter regulatory exposure.
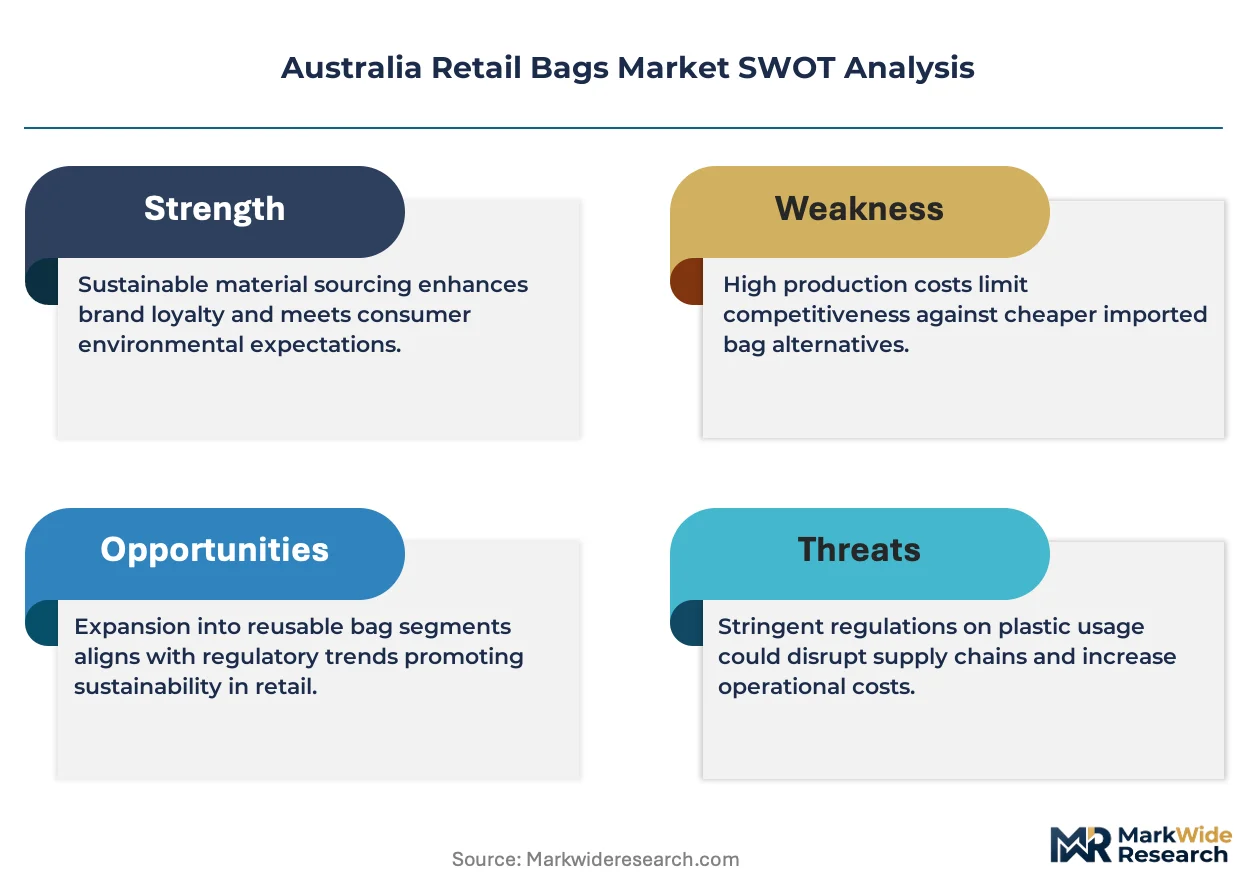
TGA administers compostability certification for bioplastic contact materials, while the Australian Competition and Consumer Commission enforces green marketing claims that constrain how retailers label bag environmental credentials. State-level plastic bag bans in Queensland, Western Australia, and South Australia operate alongside the National Plastics Plan, collectively forcing material substitution timelines that outpace supply chain adaptation in some regions. Stakeholders must monitor emerging biopolymer feedstock costs and state enforcement variance to calibrate inventory and certification investments.
Market Dynamics
State-level plastic bag bans are compressing material substitution timelines faster than supply chains can reconfigure, forcing rapid pivots from HDPE and LDPE toward certified compostable alternatives and kraft-paper formats across Australian retail channels.
Growth Catalysts
- The National Plastics Plan:Federal coordination accelerates harmonized phase-out schedules, reducing regulatory fragmentation that previously slowed national supplier retooling.
- Supermarket duopoly procurement:Coles and Woolworths consolidate bag sourcing through sustainability-mandated volume contracts, creating guaranteed offtake for certified compostable manufacturers.
- Biopolymer feedstock innovation:Emerging PLA and PBAT formulations from agricultural waste streams reduce reliance on fossil-derived inputs, improving lifecycle credentials for export-facing retailers.
Market Restraints
- Compostable resin cost volatility:Biopolymer feedstock prices fluctuate with corn starch and sugarcane markets, squeezing margins for converters locked into fixed-price retail contracts.
- Domestic pulp supply concentration:Containerboard availability depends heavily on Visy Industries' recycling loops, creating bottleneck risk during export demand surges.
- Wet-grocery technical limitations:Paper bag moisture barriers remain inferior to plastic for frozen and chilled categories, limiting complete substitution in supermarket fresh departments.
Strategic Opportunities
- Tasmanian retail expansion:The island state's lagging enforcement timeline offers a transitional window for plastic-alternative suppliers to establish beachheads before full ban implementation.
- Home-compostable certification tier:TGA's separate stream for backyard-compostable materials opens premium positioning distinct from industrial-compostable commoditization.
- Direct-store-delivery channel innovation:Bypassing centralized distribution, specialty bag producers embed with independent grocers and convenience chains for faster regulatory response.
Industry Challenges
- TGA certification backlog:Testing queue delays for compostability verification extend product launch timelines, freezing inventory capital for six to nine months.
- Retrofitting legacy extrusion lines:Converting HDPE/LDPE equipment for biopolymer processing demands capital outlays that mid-tier converters struggle to finance.
- Greenwashing enforcement exposure:ACCC litigation against vague environmental claims forces legal review of all packaging copy, adding compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Retail Bags Market |
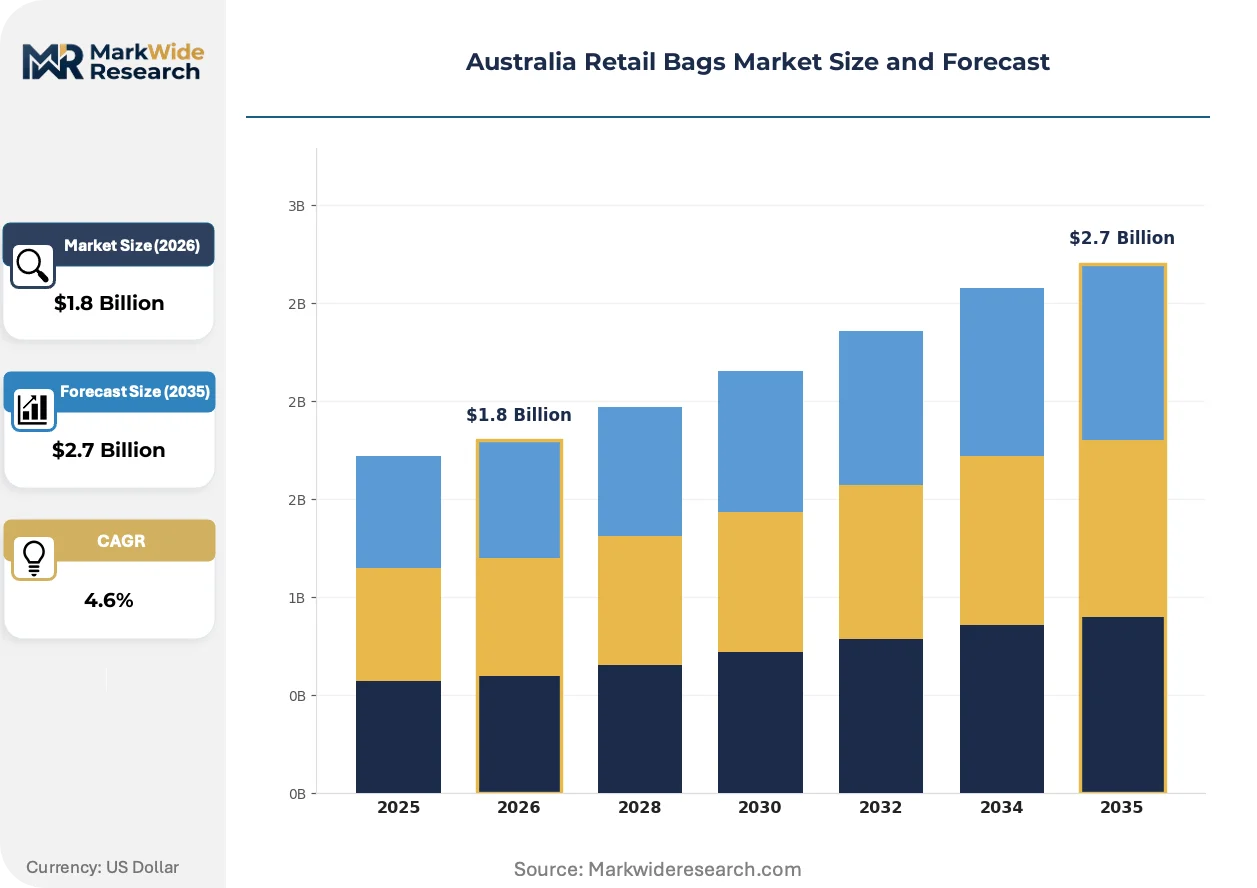
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Paper Bags, Reusable Bags, Compostable Bags End User: Supermarkets, Convenience Stores, Online Retailers, Specialty Shops Material: HDPE, LDPE, Kraft Paper, Biodegradable Plastics Size: Small, Medium, Large, Extra Large |
| Companies Covered | Detmold Group, Visy Industries, Amcor, United Paper, Gispac, Pacific National Industries, BioPak, Pact Group, Polypac Converting, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Retail Bags Market Trends and Innovations
Material science breakthroughs and enforcement tightening are compressing the viable technology set, favoring integrated producers with captive pulp or polymer capabilities over merchant converters dependent on spot inputs.
Barrier-coated kraft paper is consolidating functional performance previously split between paper and plastic substrates. Supermarket fresh departments adopt these formats for wet-grocery applications where moisture resistance once mandated polyethylene. The technology is consolidating procurement decisions around single-material streams that simplify end-of-life sorting and reduce contamination in composting facilities.
The National Plastics Plan harmonization with Queensland, Western Australia, and South Australia state bans creates unified compliance deadlines that override previous staggered timelines. Retail chains must synchronize national bag assortments rather than state-specific SKUs, compressing supplier qualification windows. Victoria and New South Wales retailers face the steepest adaptation curves as enforcement dates converge with highest transaction volumes.
Consumer stockpiling of reusable totes has saturated metropolitan supermarket demand, collapsing replacement cycles from quarterly to biennial. Independent convenience stores and specialty food retailers now drive unit volume growth as plastic restrictions penetrate smaller format channels. Queensland and South Australia convenience networks exhibit the sharpest demand inflection as enforcement extends beyond major grocery banners.
Australia Retail Bags Market Segmentation
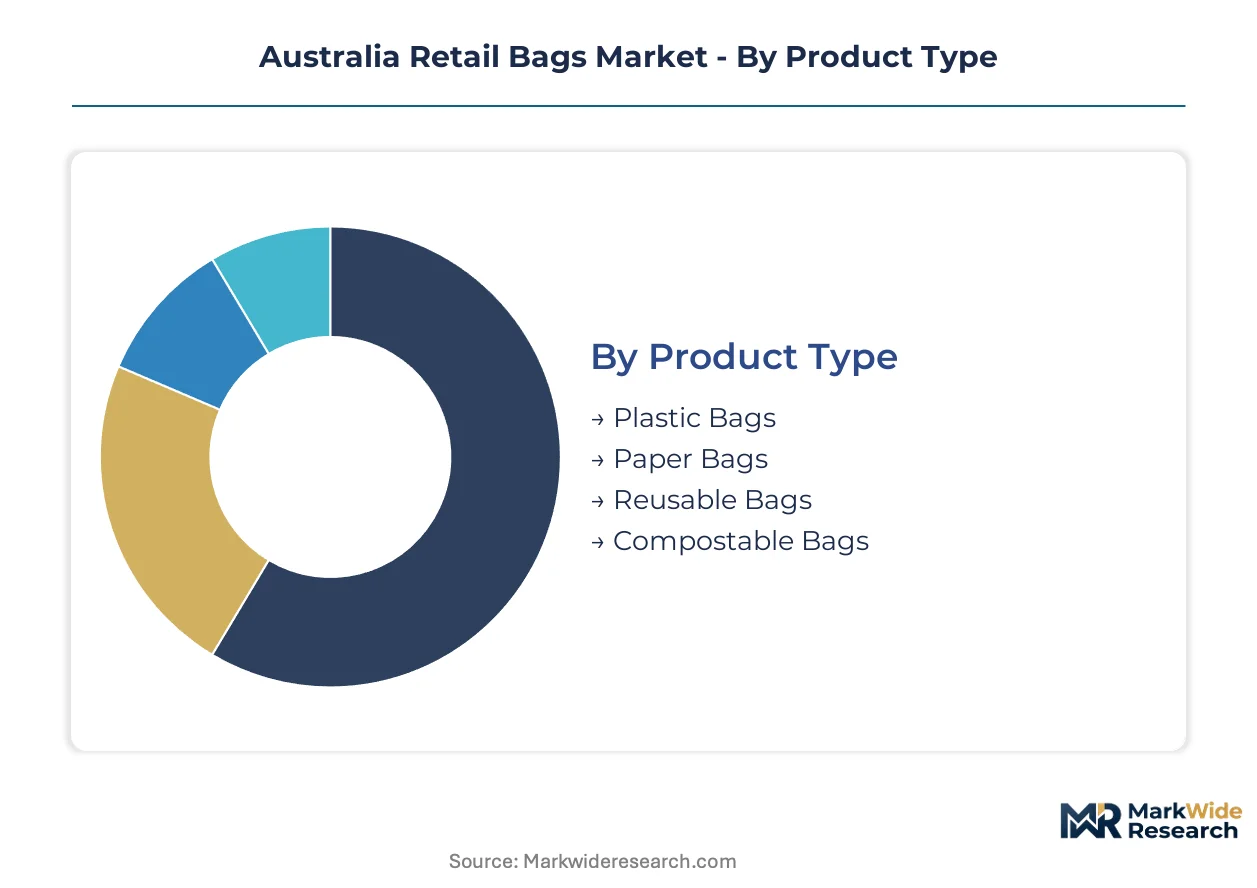
Retail bag procurement in Australia fragments across material specifications, end-use channel requirements, and state-level regulatory timelines. Understanding segment interdependencies helps suppliers align certification investments with volume concentration points.
Product Type:
Standalone carry formats dominate checkout environments, while embedded multi-use systems reshape replacement economics.
- Paper Bags:Kraft-pulp constructions with barrier coatings now handle wet-grocery loads previously reserved for polyethylene. Supermarket chains in New South Wales and Victoria specify these for fresh departments as plastic bans harden.
- Compostable Bags:TGA-certified biopolymer formulations from PLA and PBAT feedstocks carry industrial-compostable credentials for regulatory compliance. Queensland and Western Australia retailers prioritize these for single-use applications ahead of enforcement deadlines.
- Reusable Bags:Woven polypropylene and cotton totes face demand saturation in metropolitan supermarkets where consumer stockpiling has collapsed replacement cycles.
- Plastic Bags:HDPE and LDPE formats persist in convenience stores and specialty channels with lighter regulatory exposure or grandfathered exemptions.
Paper bags lead volumes today; compostable bags are gaining share fastest.
End User:
Channel concentration determines contract scale and sustainability mandate intensity.
- Supermarkets:Coles and Woolworths consolidate procurement through volume-contracting frameworks that mandate certified compostable or paper alternatives. Their duopoly position forces rapid supplier qualification at national scale.
- Convenience Stores:Smaller format operators in Queensland and South Australia drive unit growth as enforcement extends beyond major grocery banners. These channels require flexible minimum order quantities and faster regulatory response.
- Online Retailers:E-commerce fulfillment demands lightweight, durable formats with print compatibility for brand visibility during last-mile delivery.
- Specialty Shops:Boutique food retailers and independent grocers prioritize aesthetic differentiation through custom-printed kraft paper and premium reusable options.
Supermarkets anchor procurement volume; convenience stores are expanding most quickly.
Material:
Feedstock selection locks in cost structure and end-of-life pathway.
- Kraft Paper:Visy Industries' containerboard recycling loops supply integrated fiber-pulp operations that feed retail bag manufacturing at scale.
- Biodegradable Plastics:Agricultural waste-derived PLA and PBAT formulations reduce fossil dependency for export-facing retailers.
- HDPE:High-density polyethylene remains cost-advantaged for load-bearing applications in channels with deferred regulatory timelines.
- LDPE:Low-density variants persist in flexible formats for frozen and chilled categories where moisture barriers remain critical.
Kraft paper dominates current sourcing; biodegradable plastics show the steepest expansion trajectory.
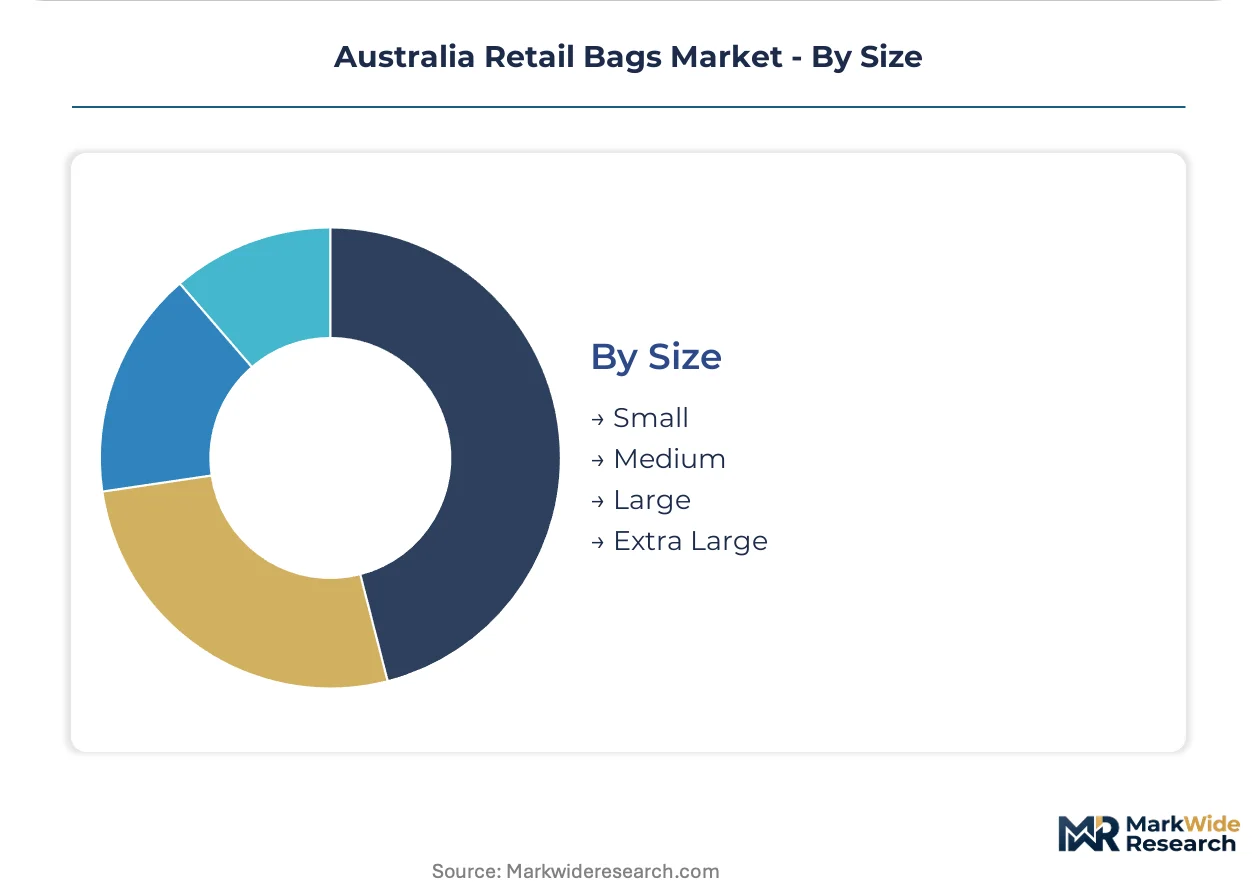
Size:
Capacity specification aligns with merchandise mix and handling automation.
- Large:Standard supermarket carry formats accommodate weekly grocery loads with reinforced handles and base gussets for structural integrity.
- Medium:Convenience store and specialty shop specifications balance portability with sufficient volume for impulse purchases.
- Small:Compact formats serve pharmaceutical, cosmetic, and confectionery retailers with premium presentation requirements.
- Extra Large:Bulk retail and home improvement channels specify oversized capacities for non-standard merchandise dimensions.
Large formats command the highest unit volumes; medium sizes are climbing fastest in convenience channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail bag manufacturing clusters concentrate along Australia's eastern seaboard, where pulp mills, polymer converters, and supermarket distribution networks intersect most densely.
New South Wales
Sydney's retail corridor drives premium paper bag demand as Woolworths headquarters mandates certified compostable procurement across all banners. The state's single-use plastic ban enforcement from June 2022 forced rapid supplier qualification, compressing TGA certification timelines for local converters. Parramatta's logistics hub hosts Detmold Group's integrated fiber-pulp operations supplying kraft-paper alternatives at scale.
Victoria
Melbourne's supermarket density generates Australia's highest transaction volumes for large-format carry bags, with Coles' national sourcing office driving sustainability-mandated volume contracts. The state's plastic bag ban aligns with National Plastics Plan harmonization, eliminating grandfathered exemptions that previously sheltered smaller retailers. Visy Industries anchors containerboard recycling loops in Melbourne's western industrial zone, feeding directly into retail bag manufacturing.
Queensland
Brisbane's convenience store networks exhibit the sharpest demand inflection as enforcement extends beyond major grocery banners into smaller format channels. The state's deferred regulatory timeline relative to southern neighbors created transitional inventory windows for plastic-alternative suppliers. Gold Coast specialty food retailers prioritize aesthetic differentiation through custom-printed kraft paper formats.
Western Australia
Perth's geographic isolation intensifies supply chain bottlenecks, with biopolymer feedstock costs fluctuating sharply during agricultural export surges. The state's 2018 plastic bag ban predated eastern harmonization, forcing early converter retooling that now supplies mature compostable bag markets. Fremantle's port infrastructure handles imported PLA and PBAT formulations for regional distribution.
South Australia
Adelaide's retail market pioneered Australia's first state-wide plastic bag ban in 2009, creating longest-running substitution dynamics for supplier capability development. The state's smaller scale enables faster regulatory response from independent grocers and convenience chains. BioPak's compostable manufacturing presence anchors industrial-compostable supply for export-facing retailers.
Australia Retail Bags Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Australia's retail bag supply base, creating tiered procurement options for supermarket chains versus independent retailers. Market structure consolidates around integrated fiber-pulp operators with captive recycling loops and specialty converters with TGA-certified compostable capabilities. Three archetypes dominate: scale-driven containerboard recyclers, biopolymer formulation specialists, and barrier-coating technology developers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with converters securing long-term pulp offtake or biopolymer feedstock agreements to lock in margin stability.
Among Australian-based integrated manufacturers, Detmold Group, Visy Industries, and Amcor occupy distinct positioning vectors. Detmold exemplifies the fiber-pulp integration archetype, leveraging captive kraft-paper production for supermarket volume contracts. Visy Industries anchors the containerboard recycling tier, with closed-loop operations that sustain cost advantages in paper-based segments. Amcor represents specialty barrier-coating development, extending paper bag functionality into applications previously reserved for plastic substrates.
| Leading Market Players |
|---|
| Detmold Group |
| Visy Industries |
| Amcor |
| United Paper |
| Gispac |
| Pacific National Industries |
| BioPak |
| Pact Group |
| Polypac Converting |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between TGA-certified compostable bags and uncertified commodity alternatives drives parallel pricing and sourcing architectures across Australian retail procurement. Premium tiers command sustained margin pools through verified industrial-compostable credentials that satisfy Coles and Woolworths sustainability mandates, while commodity kraft-paper segments compete on Visy Industries' captive fiber supply and scale economies.
Pricing Analysis
Capacity additions in Queensland and Western Australia are reshaping price floors for biopolymer-based formats as converter retooling accelerates ahead of state enforcement deadlines. Three-tier pricing structure across premium certified-compostable, standard barrier-coated paper, and economy uncoated kraft levels reflects TGA certification investment and volume contract scale. Cost compression in standard-tier paper runs through agricultural pulp export competition and energy input volatility. Convenience store chains exhibit highest price sensitivity due to thin merchandise margins, while supermarket duopoly procurement locks in least-sensitive long-term offtake agreements.
Supply Chain Analysis
Single-source vulnerability sits with Visy Industries' containerboard recycling loops that feed eastern seaboard paper bag manufacturing. Raw material dependencies center on Australian wheat straw and sugarcane bagasse for agricultural-waste-derived PLA, imported PBAT resin through Fremantle port infrastructure, and domestic kraft pulp from integrated fiber operations. Supply chain risk concentrates in biopolymer feedstock price volatility tethered to global corn starch and sugar commodity markets. Distribution runs through centralized supermarket distribution centers in Sydney and Melbourne, with direct-store-delivery bypass emerging for independent convenience and specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian retail bags constitute a late-cycle quality story as supermarket procurement hardens around certified compostable specifications and barrier-coated functionality previously reserved for plastic substrates.
For Market Incumbents: To counter biopolymer feedstock cost volatility and TGA certification backlogs, Detmold Group and Visy Industries should deepen captive fiber-pulp integration while accelerating barrier-coating R&D for wet-grocery applications. Securing long-term agricultural waste offtake agreements with Queensland sugarcane processors reduces exposure to spot resin markets. For New Entrants and Emerging Players: Independent convenience chains in Tasmania and Queensland represent the most penetrable channel tier, with flexible minimum order quantities and deferred regulatory timelines enabling faster supplier qualification than national supermarket frameworks. A direct-store-delivery model embedding with specialty food retailers and boutique grocers bypasses centralized distribution bottlenecks and captures aesthetic differentiation premiums for custom-printed kraft formats. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack capital to retrofit legacy HDPE extrusion lines for biopolymer processing or finance six-to-nine-month TGA certification timelines. Target acquisition archetypes include regional converters with established convenience channel relationships and pending compostable certifications. The signal to watch is Queensland enforcement timeline acceleration, which would compress transitional inventory windows and strand non-compliant plastic-alternative suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Certification Investment | Industrial-compostable verification unlocks Coles and Woolworths volume-contracting frameworks. |
| Barrier-Coating Technology Development | Moisture-resistant kraft formulations extend paper bag functionality into frozen and chilled categories. |
| Agricultural Waste Feedstock Partnerships | Queensland sugarcane and wheat straw offtake agreements reduce biopolymer resin cost volatility exposure. |
| Direct-Store-Delivery Channel Buildout | Bypassing Sydney and Melbourne distribution centers accelerates regulatory response for independent retailers. |
| Legacy Extrusion Line Retrofit | Biopolymer processing capability conversion captures state ban enforcement timelines ahead of competitor qualification. |
Research Methodology
Direct dialogue with supermarket sustainability procurement leads, biopolymer converter operations managers, TGA certification specialists, and independent convenience chain buyers grounded qualitative assessment in operational reality. Secondary validation drew from Australian Bureau of Agricultural and Resource Economics feedstock data, state environmental protection agency enforcement schedules, customs records for PLA and PBAT imports, and ACCC green marketing litigation filings. Bottom-up channel volume estimates triangulated against top-down National Plastics Plan implementation projections.
Bottom-up modeling aggregated unit demand across supermarket, convenience, online retail, and specialty shop channels, with material-grade splits for kraft paper, certified compostable, reusable, and residual plastic formats. Top-down cross-checks applied state-level regulatory enforcement timelines to transaction volume concentration in New South Wales, Victoria, Queensland, Western Australia, and South Australia. CAGRs derived from elasticity-adjusted price trajectories and substitution rate assumptions across the projection horizon, with biopolymer feedstock cost curves and pulp fiber availability as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to TGA certification queue durations, agricultural commodity export demand surges, and state enforcement variance. Forecasts embed assumptions regarding National Plastics Plan harmonization timing and biopolymer formulation performance improvements that could accelerate or retard material substitution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Floor Mat Rental Service Market
Retailing
Subscription Box Market
Retailing
North America Retail Vending Machine Market
Retailing
In Store Signage Market
Retailing
Floor Displays Market
Retailing
Consumer Products and Retail Market
Retailing
Philippines Retail Industry Market
Retailing
Global Food and Non-Food Retail Market
Retailing
Furniture Rental Service Market
Retailing
Singapore Gifting Market
Retailing
Out Store Signage Market
Retailing
Out-Door Signage Market
Retailing
Retail Signage Market
Retailing
United States Hardware Stores Retail Market
Retailing
Home Shopping Market