
 Clothing Retail Market | 2026-2036
Clothing Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Clothing Retail Market Insights
CE marking under the EU Textile Regulation is collapsing the competitive field for European market access, forcing suppliers to prove chemical compliance or exit. Inditex leverages its vertical manufacturing network to certify products faster than fragmented rivals. The TJX Companies competes through off-price sourcing flexibility that sidesteps premium certification costs. Lululemon Athletica differentiates via Bluesign-approved material partnerships that command higher price realization.
Clothing retail encompasses the commercial distribution of finished apparel through multi-channel networks, spanning woven and knitted garments constructed from natural fibers, synthetics, and blended textiles via cut-make-trim or fully fashioned production. The sector serves consumer wardrobe replacement, occupational dress codes, and lifestyle expression needs across demographic cohorts. Activewear commands accelerating margin pools as performance fabric innovation merges with casual workplace norms. Discount channels sustain volume leadership in developing economies where price sensitivity dominates purchase decisions. Direct-to-consumer distribution captures the fastest expansion, though brick-and-mortar retains decisive influence in fit-dependent categories such as tailored bottoms and outerwear.
The EU Green Deal's textile strategy and ECHA REACH chemical restrictions impose traceability mandates that reshape supplier qualification across European markets. The US EPA and FTC Green Guides enforce labeling standards that penalize unsubstantiated sustainability claims in North American commerce. China's SAMR and GB standards govern domestic textile safety thresholds that foreign entrants must satisfy for market participation. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance investments that fail to transfer across borders.
Market Dynamics
EU Green Deal textile traceability mandates are forcing supplier qualification redesigns across European markets, compressing the competitive field for market access while accelerating capital deployment into certification infrastructure.
Growth Catalysts
- EU Green Deal textile strategy:Mandatory circularity reporting creates first-mover advantage for compliant suppliers. Brands investing early in traceability systems capture shelf space from laggards.
- Performance fabric innovation:Moisture-wicking and temperature-regulating textiles expand activewear into workplace-adjacent categories. Corporate dress code relaxation accelerates category blurring.
- China's domestic brand preference:Rising middle-class consumers redirect spending from foreign labels to local designers. Domestic supply chains shorten lead times and improve margin capture.
Market Restraints
- Cotton price volatility:Climate-driven harvest variability and water scarcity in major growing regions compress fabric cost predictability. Hedging costs erode working capital efficiency.
- Polyester feedstock concentration:Crude oil derivative supply chains cluster in Middle Eastern and Chinese petrochemical complexes. Geopolitical friction disrupts synthetic fiber input security.
- ECHA REACH chemical restrictions:Expanded substance ban lists force reformulation of dyes, finishes, and functional coatings. Reformulation timelines extend product development cycles by 8-14 months.
Strategic Opportunities
- India's organized retail penetration:Modern trade formats capture under 15% of apparel volume in tier-2 and tier-3 cities. Mall development and e-commerce logistics investment unlock volume scaling.
- Textile-to-textile recycling:Chemical depolymerization of blended fabrics converges with automated fiber sorting. Closed-loop material flows reduce virgin input dependency and satisfy EU circularity mandates.
- Rental platform infrastructure:Subscription models for occasion wear and maternity categories expand addressable market without production volume increases. Logistics networks specialized in reverse garment flow create defensive moats.
Industry Challenges
- Bluesign and OEKO-TEX certification backlog:Testing laboratory capacity constraints extend approval timelines. Product launches miss seasonal windows, forcing discount-driven clearance.
- Legacy ERP-to-traceability platform integration:Batch-record systems lack granularity for fiber-level tracking. Custom middleware development consumes IT resources and delays compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clothing Retail Market |
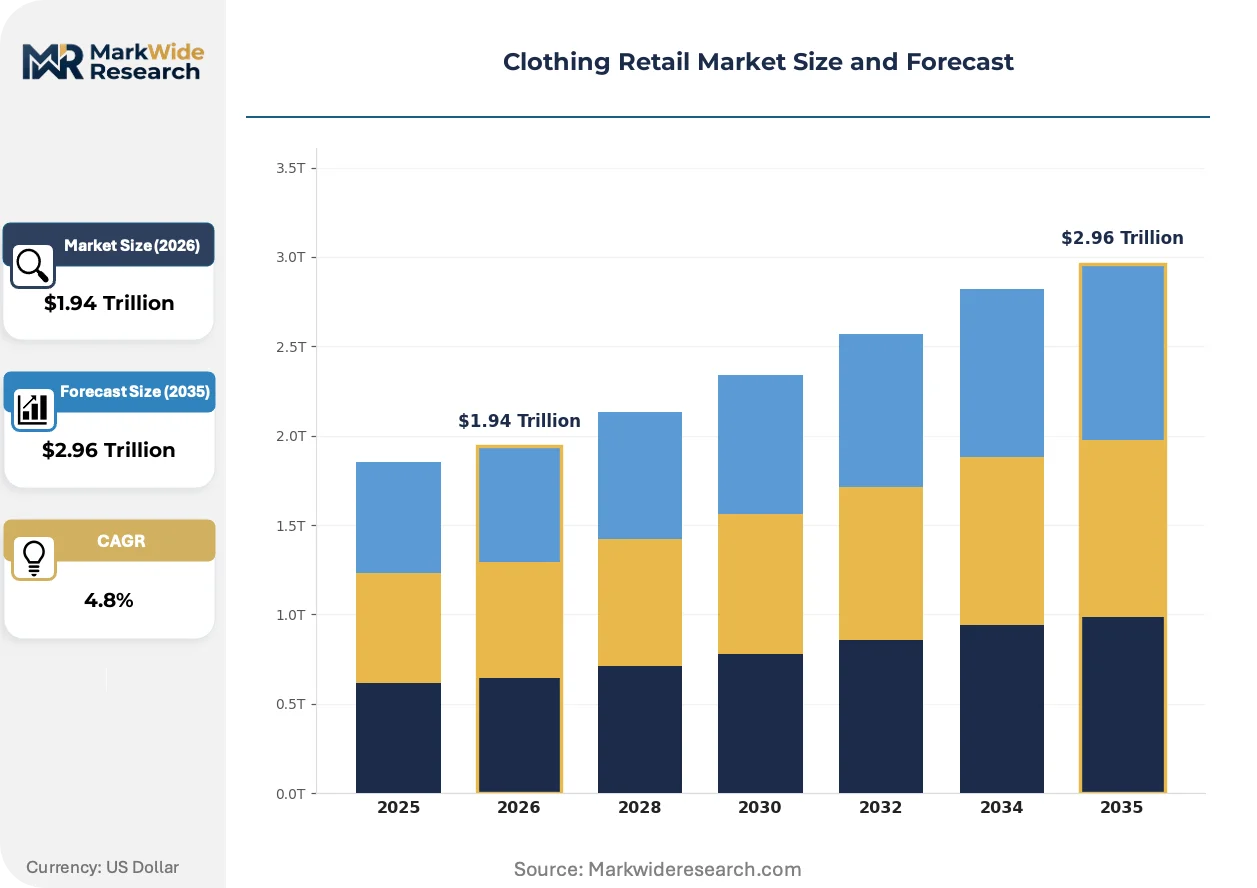
| Market Size in 2026 | $1.94 Trillion |
| Market Size in 2035 | $2.96 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tops, Bottoms, Outerwear, Activewear Customer Type: Men, Women, Kids, Unisex Price Tier: Luxury, Premium, Mid-range, Discount Distribution Channel: Online, Brick-and-Mortar, Franchise, Direct-to-Consumer |
| Companies Covered | Ross Stores, NEXT, Inditex, Aritzia, Burlington Stores, The TJX Companies, Lululemon Athletica, The Gap, Fast Retailing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clothing Retail Market Trends and Innovations
Digital product passports and AI-driven demand forecasting are compressing the traditional apparel calendar from concept to shelf, while regulatory chemical restrictions force material science investment.
Blockchain-enabled fiber provenance systems is bifurcating supply chain transparency standards. Premium and mass-market segments adopt divergent verification depths. Luxury houses deploy granular farm-to-garment tracking while value players rely on batch-level certification, compressing price realization for mid-tier brands caught between investment levels.
EU ECHA REACH substance restrictions expand restricted chemical lists annually. Dye houses and finishers face forced equipment upgrades or contract loss. Italian and Portuguese textile clusters accelerate waterless dyeing adoption to maintain European market access, while Turkish suppliers absorb displaced volume from non-compliant Asian competitors.
Resale platform integration into primary retail channels disrupts traditional inventory ownership models. Young adult consumers in urban China and Germany treat secondhand as first-choice for statement pieces. Brand-operated takeback programs and peer-to-peer marketplaces fragment volume across decentralized fulfillment networks, compressing centralized distribution economics.
Clothing Retail Market Segmentation
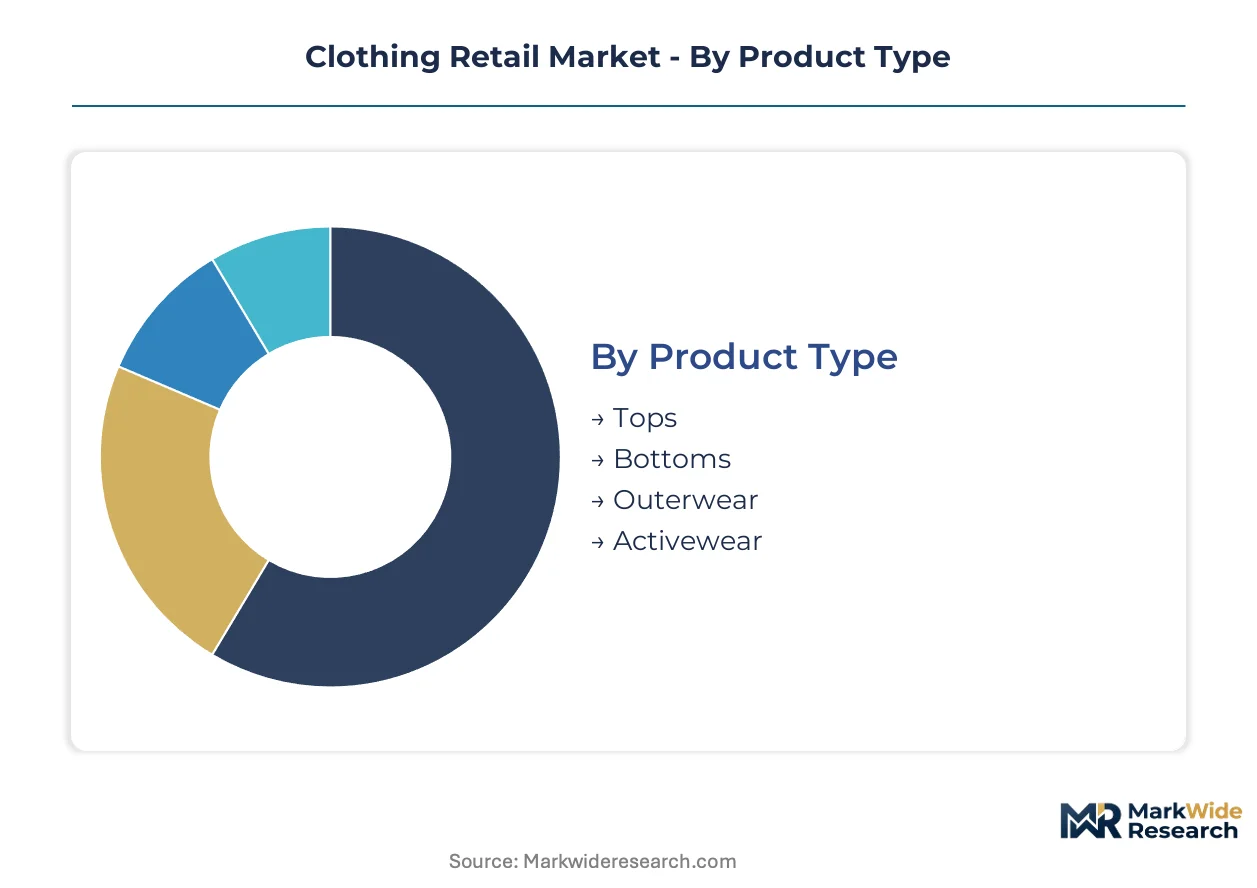
Segmentation in clothing retail reveals how margin pools concentrate across product categories, customer cohorts, and channel architectures. Understanding these divisions exposes where capital deployment yields pricing power versus where volume scaling dominates competitive economics.
Product Type:
Margin pools concentrate disproportionately in categories where technical performance justifies price premiums and repeat purchase frequency sustains inventory turns.
- Activewear:Engineered with moisture-wicking synthetics and compression weaves, this category commands the highest gross margins through performance claims that resist direct comparison. Demand concentrates in urban China and Germany where corporate dress codes have relaxed fastest, though cotton price volatility compresses blended fabric cost predictability.
- Outerwear:Technical insulation and waterproof membranes require specialized manufacturing partnerships that limit supplier fragmentation. Seasonal concentration in Nordic markets and alpine regions creates inventory risk, with EU ECHA REACH restrictions on fluorinated water repellents forcing material reformulation cycles.
- Tops:High-velocity basics with shorter design cycles and lower technical barriers to entry.
- Bottoms:Fit-dependent category retaining brick-and-mortar influence for denim and tailored trousers.
The dominant share belongs to Tops, while Activewear is closing the gap fastest.
Customer Type:
Volume distribution across demographic cohorts determines marketing spend allocation and sizing curve complexity in supply chain planning.
- Women:The broadest addressable market spanning professional, casual, and occasion wear with the highest purchase frequency. Chinese domestic brands capture rising middle-class spending through localized trend cycles that foreign labels struggle to match.
- Kids:Replacement-driven demand from growth spurts creates predictable replenishment patterns. Parents in tier-2 Indian cities increasingly favor organized retail formats for quality assurance, though price sensitivity limits premium penetration.
- Men:Lower purchase frequency with higher average transaction values in tailored categories.
- Unisex:Emerging category blurring traditional merchandising boundaries, concentrated in streetwear and sustainable labels.
Women's segment holds the volume base, with Kids expanding most quickly in developing market modern trade.
Price Tier:
Certification investment requirements and traceability infrastructure costs create divergent competitive fields across price positioning.
- Luxury:Granular farm-to-garment tracking through blockchain-enabled provenance systems justifies price multiples. Italian textile clusters deploy waterless dyeing to maintain European market access under tightening EU Green Deal mandates.
- Discount:Off-price sourcing flexibility sidesteps premium certification costs through batch-level compliance documentation. TJX Companies and similar operators exploit supplier overruns and canceled orders without bearing traceability infrastructure investments.
- Premium:Bluesign and OEKO-TEX certification creates defensive moats but extends approval timelines.
- Mid-range:Caught between investment levels, facing compressed price realization as transparency standards bifurcate.
Discount tier captures the volume leadership, while Luxury is climbing the fastest on circularity-premium positioning.
Distribution Channel:
Capital intensity and inventory ownership models separate channels with fundamentally different working capital profiles.
- Direct-to-Consumer:Captures the fastest expansion through owned digital storefronts and app-based retention programs. Inditex leverages vertical manufacturing networks to compress concept-to-shelf timelines while fragmented rivals struggle with legacy ERP integration.
- Online:Third-party marketplace presence requires margin sacrifice for traffic acquisition but defrays fulfillment infrastructure costs. Young adult consumers in urban Germany and China treat resale platforms as first-choice for statement pieces.
- Brick-and-Mortar:Retains decisive influence in fit-dependent categories, with mall development in tier-2 Indian cities unlocking volume scaling.
- Franchise:Capital-light international expansion with quality control challenges in operator selection.
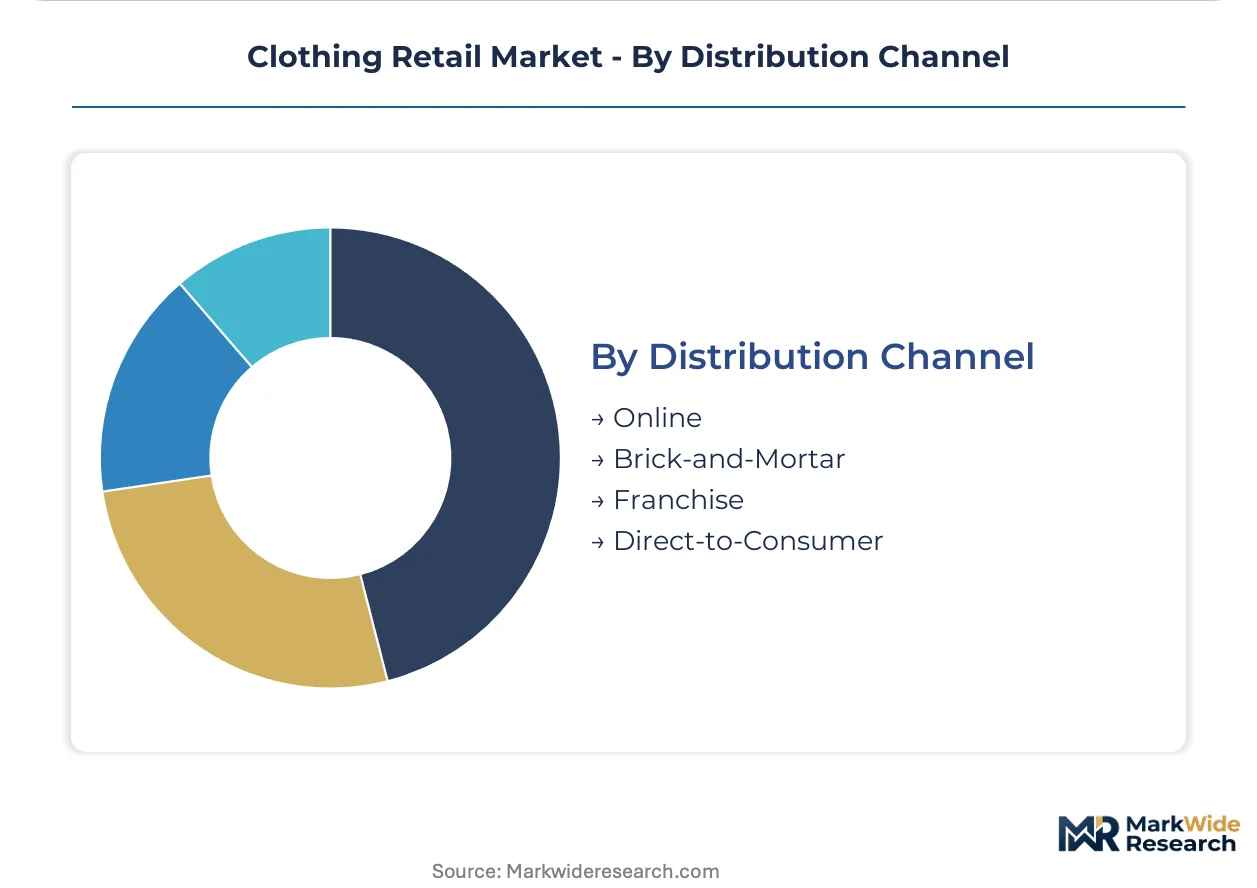
Brick-and-Moor retains the revenue base, though Direct-to-Consumer is gaining share fastest through data-driven personalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Affluent urban professionals concentrate purchasing power in coastal Chinese cities, German metropolitan corridors, and American coastal metros. Young adult cohorts in these markets treat resale platforms as primary discovery channels. Regulatory divergence between EU circularity mandates and US labeling standards forces parallel compliance investments.
China
Rising middle-class consumers in Shanghai and Beijing redirect spending toward domestic labels like Anta and Li-Ning. SAMR's GB standards govern textile safety thresholds that foreign entrants must satisfy. The Yangtze River Delta manufacturing cluster shortens lead times for domestic brands capturing premium positioning.
Germany
Corporate dress code relaxation accelerates activewear adoption among Berlin and Munich professionals. EU Green Deal textile traceability mandates force supplier qualification redesigns. The Bavarian textile cluster deploys waterless dyeing systems to maintain market access under tightening ECHA REACH restrictions.
United States
Young adults in New York and Los Angeles treat secondhand as first-choice for statement pieces. FTC Green Guides enforce labeling standards that penalize unsubstantiated sustainability claims. The Los Angeles apparel district specializes in rapid-turn domestic production for direct-to-consumer brands.
India
Parents in tier-2 cities favor organized retail formats for children's quality assurance. BIS certification requirements create entry barriers for unorganized competitors. The Tiruppur knitwear cluster in Tamil Nadu invests in effluent treatment to satisfy export compliance for European buyers.
Italy
Luxury houses in Milan deploy granular farm-to-garment tracking through blockchain-enabled provenance systems. EU ECHA REACH substance restrictions expand restricted chemical lists annually. The Como silk district accelerates natural dye adoption to defend premium positioning against traceability-invested rivals.
Clothing Retail Market Competitive Landscape
Player mix skews toward vertically integrated specialists and off-price sourcing platforms with divergent compliance cost structures. The competitive field compresses around certification-capable suppliers as EU market access rules tighten. Two strategic archetypes dominate: integrated manufacturers with captive supply chains, and flexible sourcing operators exploiting supplier overruns. Consolidation pressures intensify through M&A activity among mid-tier brands, while technology licensing partnerships proliferate for traceability platform deployment.
Among North American off-price operators, Ross Stores and Burlington Stores exemplify sourcing flexibility that sidesteps premium certification investments. Inditex anchors the integrated manufacturing archetype with vertical networks compressing concept-to-shelf timelines. These three occupy positions across the pricing tier spectrum, with the off-price pair representing batch-level compliance documentation and the Spanish operator representing granular traceability infrastructure.
| Leading Market Players |
|---|
| Ross Stores |
| NEXT |
| Inditex |
| Aritzia |
| Burlington Stores |
| The TJX Companies |
| Lululemon Athletica |
| The Gap |
| Fast Retailing |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts with cotton suppliers lock in fiber access and cost visibility for vertically integrated manufacturers serving European markets under EU Green Deal traceability mandates. These arrangements insulate compliant suppliers from spot market volatility while non-integrated brands absorb margin compression from reformulation delays.
Pricing Analysis
Cost-plus contracts indexed to ICE cotton futures dominate raw material procurement, with dye house and finishing premiums layered on top. Price differentiation hinges on Bluesign certification tier and geographic delivery cost to European distribution centers. Pricing pressure intensifies in the mid-range tier as transparency standards bifurcate between luxury blockchain tracking and discount batch-level documentation. Discount channel buyers exhibit highest price sensitivity, while luxury purchasers accept premiums for farm-to-garment provenance.
Supply Chain Analysis
Yarn spinning concentration in the Yangtze River Delta creates chokepoint vulnerability for brands dependent on Chinese synthetic fiber output. Finished apparel manufacturing draws from Bangladesh, Vietnam, and India for cut-make-trim assembly, with cotton cultivation anchored in Texas, India, and Brazil. Single-source vulnerability in Chinese petrochemical complexes for polyester feedstock threatens input security. Distribution runs through direct-to-consumer digital storefronts and third-party marketplace partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clothing retail sits in early-cycle expansion as resale platform infrastructure matures from niche experimentation to primary channel integration. Young adult adoption curves in urban China and Germany signal mainstream penetration ahead.
For Market Incumbents: Compound defensive positioning through backward integration into waterless dyeing capacity and captive textile recycling infrastructure. EU ECHA REACH chemical restrictions threaten supplier relationships for non-compliant dye houses. Certification investment in Bluesign-approved material partnerships creates margin protection against mid-tier price erosion.
For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 organized retail penetration gap, where modern trade formats capture under 15% of apparel volume. Occasion wear and maternity rental platforms represent the most penetrable white-space. Launch through logistics networks specialized in reverse garment flow to build operational moats.
For Investors and Strategic Acquirers: Specialist traceability platform developers with legacy ERP integration capabilities represent the priority acquisition archetype. Long-term viability favors operators who can amortize compliance infrastructure across multi-brand client bases. Watch for inflection when EU Green Deal circularity reporting mandates trigger forced supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Textile-to-Textile Recycling Investment | Chemical depolymerization capacity satisfies EU circularity mandates while reducing virgin cotton dependency. |
| Digital Product Passport Deployment | Blockchain-enabled fiber provenance systems justify luxury price multiples under tightening traceability requirements. |
| Waterless Dyeing Adoption | Italian and Portuguese textile clusters deploy supercritical CO2 systems to maintain ECHA REACH compliance. |
| Rental Platform Infrastructure Buildout | Subscription models for occasion wear expand addressable market without production volume increases. |
| Direct-to-Consumer Channel Expansion | Owned digital storefronts capture data-driven personalization advantages over third-party marketplaces. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, SEC apparel retailer filings, and EU regulatory submissions to validate market sizing. Interviews with brand sustainability officers, textile mill procurement directors, retail category buyers, and dye house technical managers inform operational assumptions. Top-down macroeconomic indicators and bottom-up channel checks triangulate volume estimates.
Segmentation dimensions modeled include product type, customer demographic, price tier positioning, and distribution channel architecture across the projection horizon. CAGRs derive from regression analysis against historical penetration curves and regulatory adoption timelines. Forecast inputs incorporate EU Green Deal implementation schedules and China's domestic brand preference shifts.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and China middle-class consumption growth; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA REACH substance restriction expansions and cotton harvest variability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Vietnam Retail Market
Retailing
Out-Door Signage Market
Retailing
Retail Vending Machine Market
Retailing
Floor Displays Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
Subscription Box Market
Retailing
Global Food and Non-Food Retail Market
Retailing
European Discount Retail Market
Retailing
Philippines Retail Industry Market
Retailing
United States Hardware Stores Retail Market
Retailing
Retail Display Racks Market
Retailing
In Store Signage Market
Retailing
Electronics Retailing Market
Retailing
Consumer Shopping Cart Market
Retailing
Out Store Signage Market