
 Asia-Pacific Duty-Free Retailing Market | 2026-2036
Asia-Pacific Duty-Free Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Duty-Free Retailing Market Analytics
The gap between premium luxury assortments and mass-market commodity SKUs is shifting as airport concessionaires reallocate floor space toward high-margin exclusives. China Duty Free Group leverages its Hainan Island monopoly to anchor domestic traffic away from overseas competitors. Lotte Duty Free sustains its Korean hub position through beauty brand exclusivity and celebrity licensing partnerships. DFS Group differentiates via curated regional product mixes that reflect destination-specific traveler demographics.
Duty-free retailing denotes the sale of goods exempt from certain local or national taxes and duties, typically occurring within designated zones such as international airports, seaports, and border crossings where merchandise must remain sealed until departure. The model relies on volume-based procurement, restricted access controls, and real-time customs integration to maintain price advantages over domestic retail channels. Fragrances and cosmetics command the deepest margin pools due to brand-controlled scarcity and travel-exclusive SKUs. Spirits competes for basket share through aged-stock differentiation and regional bottling exclusives. The airports channel dominates transaction volume but faces structural pressure from online pre-order platforms that compress dwell-time economics.
China's SAMR and customs authorities enforce strict cross-border e-commerce documentation for duty-eligible purchases, while South Korea's Korea Customs Service regulates purchase quantity limits and eligibility verification for foreign tourists. These frameworks directly determine permissible sales channels, inventory authentication requirements, and refund mechanics for operators. Japan's METI oversees consumer protection standards for inbound retail, adding compliance layers to product labeling and return policies. Stakeholders must monitor how biometric passenger verification and digital customs pre-clearance reshape the operational boundary between physical duty-free floors and digital pre-order fulfillment.
Market Dynamics
China's MIIT and SAMR are tightening cross-border e-commerce compliance rules for duty-free goods, forcing operators to restructure inventory authentication and pricing transparency systems. This regulatory pressure is compressing margins while accelerating consolidation among concessionaires who lack capital for compliance infrastructure.
Growth Catalysts
- Hainan Island duty-free zone expansion:Domestic Chinese tourists now represent the dominant buyer cohort, redirecting spend from overseas competitors into the domestic zone. SAMR frameworks support this geographic concentration through streamlined customs pre-clearance.
- Biometric passenger verification:Airport operators deploy facial recognition and digital identity systems to reduce dwell-time friction. This technology compresses transaction cycles and expands throughput capacity per square meter.
- Cross-border air traffic normalization:Southeast Asian business travelers are expanding their spend on premium fragrances and spirits as flight volumes recover. This demand pattern concentrates in airport channels with established beauty brand exclusivity.
Market Restraints
- Inventory authentication cost inflation:China's SAMR mandates real-time customs integration and documentation for every duty-eligible SKU. Small concessionaires lack capital for these systems.
- Korean purchase quantity limits:Korea Customs Service restricts foreign tourist eligibility verification and per-transaction caps. These rules compress basket sizes for Chinese group travelers.
- Digital pre-order platform substitution:Online fulfillment channels compress dwell-time economics at physical airport floors. This technical displacement threatens the core revenue model of location-dependent concessionaires.
Strategic Opportunities
- Vietnam and Indonesia airport privatization:Secondary Southeast Asian hubs are tendering duty-free concessions to international operators. These markets remain underpenetrated relative to passenger growth trajectories.
- Japan METI consumer protection alignment:Inbound retail labeling and return policy standards create compliance moats for operators who invest early. This regulatory tailwind favors scaled players with legal infrastructure.
- Blockchain-IoT inventory tracking:Convergence of distributed ledger systems and sensor networks enables real-time provenance verification. This technology pairing reduces customs inspection delays and shrinkage losses.
Industry Challenges
- Legacy ERP-to-customs API integration:Operators must reconfigure decades-old inventory systems for real-time SAMR and Korea Customs Service data exchange. This reconfiguration demands scarce technical talent and extended capex cycles.
- Fragrance and spirits licensing complexity:Brand-controlled exclusivity agreements create IP disputes when concessionaires operate across overlapping territories. Legal teams must navigate conflicting territorial claims from LVMH, Estée Lauder, and Pernod Ricard portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Duty-Free Retailing Market |
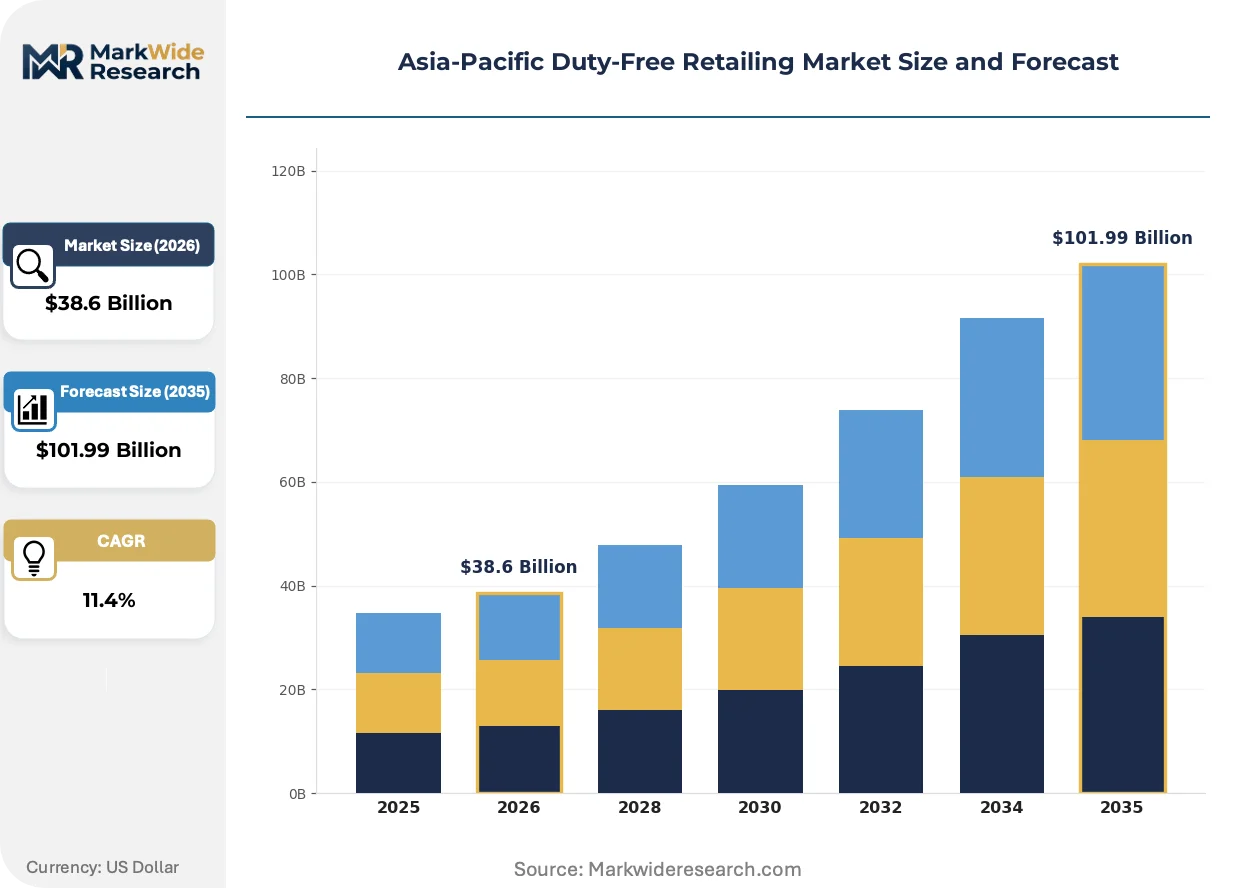
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fragrances, Cosmetics, Spirits, Confectionery Distribution Channel: Airports, Cruise Ships, Border Shops, Online Customer Type: Travelers, Tourists, Business Travelers, Locals Service Type: Self-Service, Full-Service, Click & Collect, Loyalty Programs |
| Companies Covered | China Duty Free Group, Lotte Duty Free, Shilla Duty Free, DFS Group, Avolta AG, King Power International Group, Gebr. Heinemann, Ever Rich Duty Free, Lagardère Travel Retail, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Duty-Free Retailing Market Evolving Landscape
Digital pre-order platforms and biometric verification systems are compressing the operational boundary between physical duty-free floors and online fulfillment. This convergence is reshaping how concessionaires allocate capital between real estate and technology infrastructure.
Unified commerce platforms is consolidating passenger data, inventory, and payment systems into single-stack architectures. Airport operators in Singapore and Hong Kong deploy these systems to enable seamless pre-order-to-pickup workflows. This consolidation is reducing dwell-time dependency and expanding revenue capture beyond physical floor constraints.
China's SAMR cross-border e-commerce documentation requirements are mandating real-time pricing transparency and SKU-level customs integration. Duty-free operators must restructure procurement and inventory systems to comply. The fragrances and cosmetics segment faces the steepest compliance burden due to brand-controlled scarcity and travel-exclusive SKU complexity.
Chinese domestic tourists are pivoting spend toward Hainan's duty-free zone, displacing historical purchasing patterns at Seoul Incheon and Tokyo Narita. This geographic rotation concentrates demand in a single domestic jurisdiction. Airport concessionaires in Korea and Japan are responding by deepening beauty brand exclusivity and celebrity licensing partnerships to retain Chinese transit passengers.
Asia-Pacific Duty-Free Retailing Market Segmentation
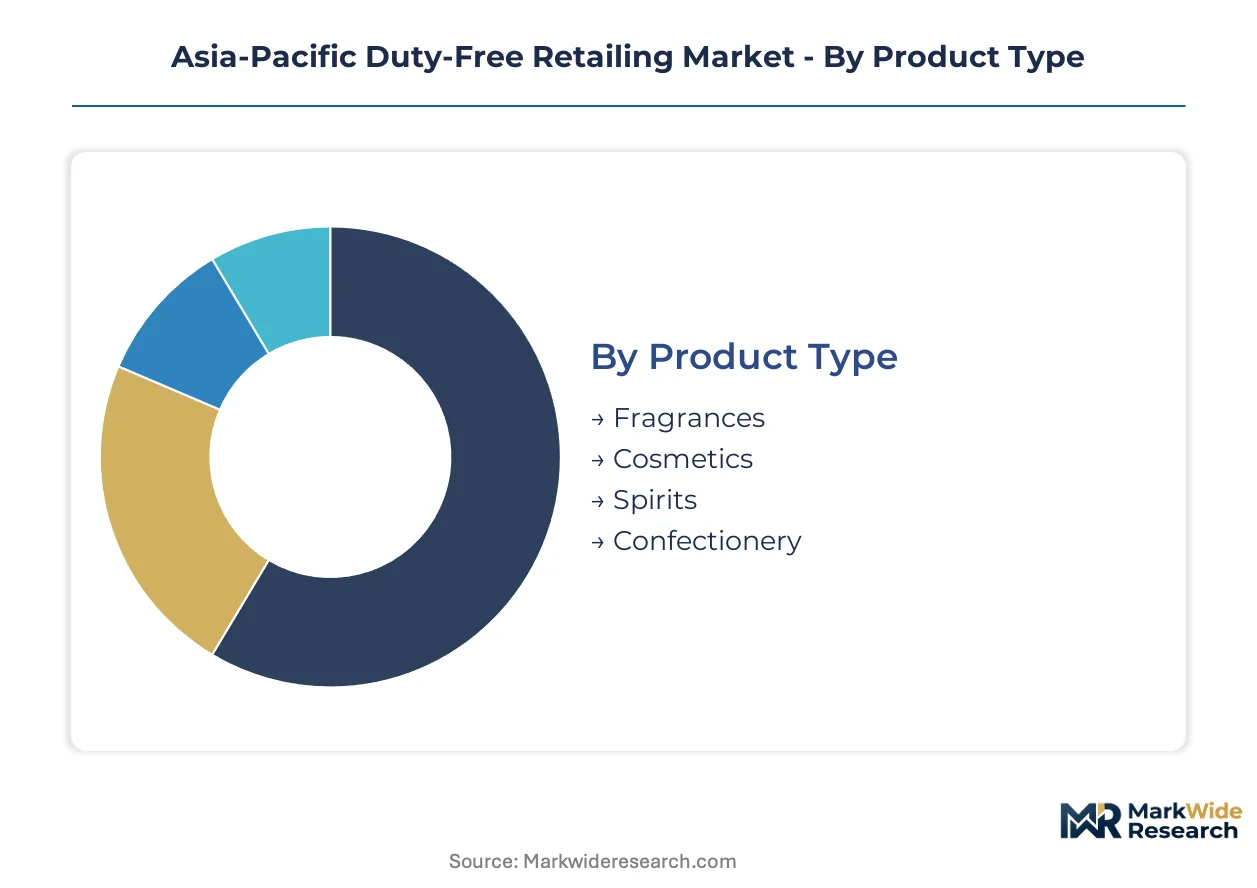
Duty-free operators calibrate inventory depth and service intensity against passenger dwell times and purchase authorization rules. Segmentation discipline separates high-velocity airport corridors from low-frequency border shops, each demanding distinct procurement and staffing models.
Product Type:
Standardization dominates fragrances and spirits through brand-controlled SKUs, while cosmetics and confectionery allow greater private-label flexibility.
- Fragrances:Travel-exclusive bottle sizes and limited-edition packaging create artificial scarcity. Demand clusters in Hainan's duty-free zone where domestic Chinese tourists now channel spend previously directed at Seoul Incheon. SAMR documentation requirements add compliance overhead to every SKU.
- Cosmetics:K-beauty and prestige skincare lines anchor Korean hub competitiveness through celebrity licensing partnerships. Korean concessionaires leverage brand exclusivity to retain Chinese transit passengers facing purchase quantity limits from Korea Customs Service.
- Spirits:Aged-stock differentiation and regional bottling exclusives drive basket composition. Southeast Asian business travelers expand category spend as cross-border air traffic normalizes.
- Confectionery:Localized packaging and seasonal gift sets serve impulse purchase patterns at airport departure gates.
Most installed capacity flows through Fragrances. Expansion is steepest in Cosmetics.
Distribution Channel:
Channel economics diverge sharply between real estate-dependent airport floors and technology-enabled fulfillment alternatives.
- Airports:Dwell-time constraints compress transaction cycles while biometric verification systems expand throughput per square meter. Physical floors face structural pressure from digital pre-order platforms that erode location premiums.
- Online:Pre-order-to-pickup workflows reduce passenger friction but demand real-time customs integration. China's MIIT and SAMR tightening of cross-border e-commerce compliance rules forces inventory authentication system upgrades.
- Cruise Ships:Extended voyage durations enable appointment-based selling and higher-ticket consultations.
- Border Shops:Lower footfall volumes favor self-service formats with reduced staffing overhead.
Transaction volume concentrates in Airports. Technology investment is climbing fastest in Online.
Customer Type:
Service design separates time-constrained business travelers from leisure tourists with extended browsing windows.
- Business Travelers:Compressed schedules favor pre-order platforms and expedited pickup lanes. Southeast Asian corridors show expanding premium fragrance and spirits spend as flight volumes recover.
- Tourists:Extended dwell times support full-service consultations and discovery-driven purchasing. Chinese domestic tourists now dominate Hainan Island's duty-free zone.
- Travelers:General transit passengers respond to impulse merchandising at departure gates.
- Locals:Domestic purchase authorization under Hainan frameworks creates a distinct regulatory category.
Revenue density peaks with Business Travelers. Volume expansion is strongest among Tourists.
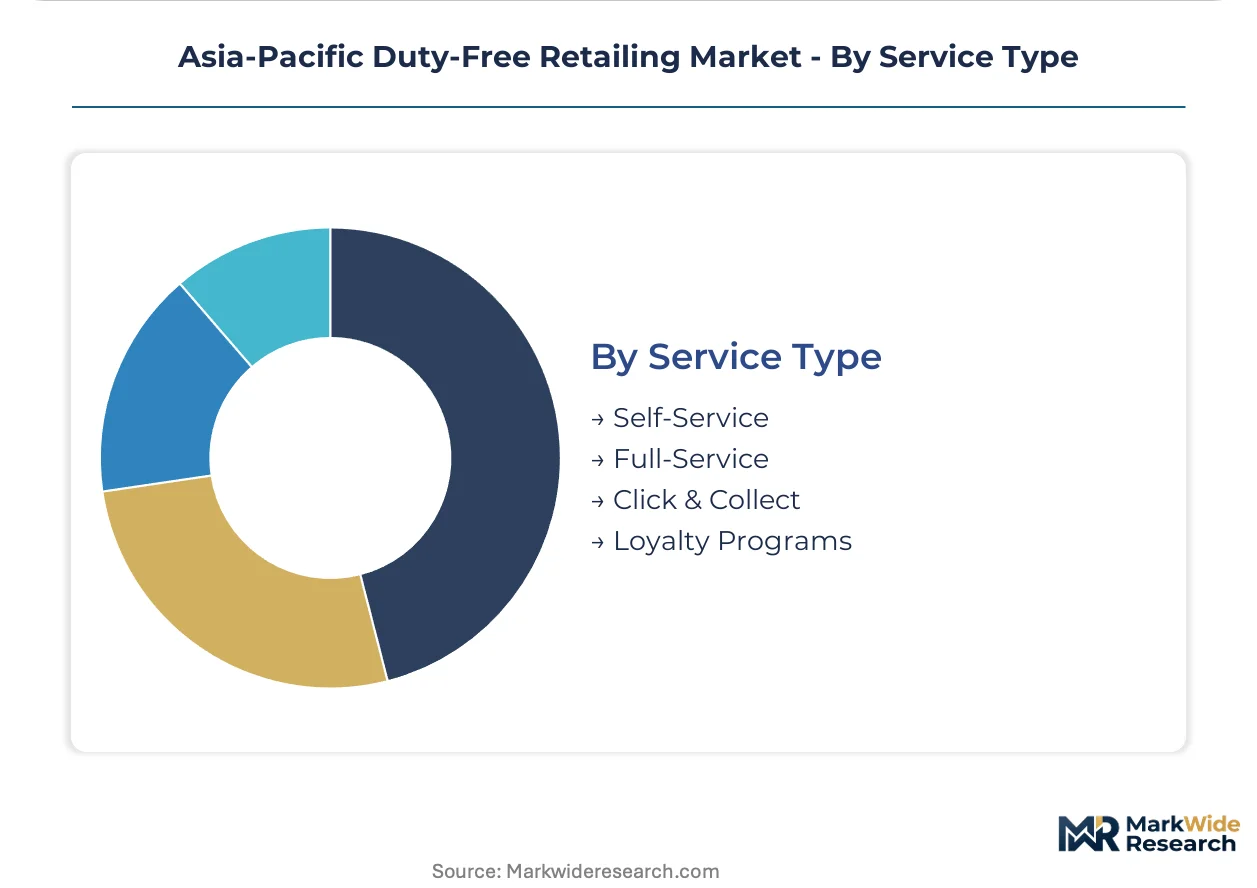
Service Type:
Capital allocation shifts between labor-intensive full-service models and technology-mediated self-service alternatives.
- Self-Service:Reduced staffing ratios suit high-volume airport gates with standardized product presentations. Singapore and Hong Kong operators deploy unified commerce platforms to enable seamless workflows.
- Full-Service:Consultative selling supports premium cosmetics and spirits categories requiring education and sampling. Brand-controlled exclusivity agreements dictate staffing certification requirements.
- Click & Collect:Digital pre-order with physical fulfillment compresses dwell-time dependency while maintaining customs verification touchpoints.
- Loyalty Programs:Passenger data consolidation enables personalized remarketing across travel occasions.
Operational footprint centers on Self-Service. Investment momentum favors Click & Collect.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled retail operations talent concentrates in Singapore and Hong Kong, where unified commerce platforms and biometric verification systems demand specialized technical workforce pools. These hubs anchor regional technology deployment while secondary markets scale through airport privatization and regulatory alignment.
China
Hainan Island duty-free zone expansion redirects domestic tourist spend from Seoul and Tokyo into a single domestic jurisdiction. SAMR and MIIT compliance frameworks mandate real-time customs integration and SKU-level documentation. Sanya and Haikou retail clusters concentrate investment in fragrance and cosmetics exclusives.
South Korea
K-beauty brand licensing partnerships anchor competitiveness for Chinese transit passengers. Korea Customs Service purchase quantity limits and eligibility verification compress basket sizes for group travelers. Seoul Incheon duty-free floors deepen beauty brand exclusivity to defend against Hainan diversion.
Japan
Inbound tourism recovery drives cosmetics and spirits demand at Narita and Haneda corridors. METI consumer protection standards for retail labeling and return policies create compliance infrastructure requirements. Tokyo and Osaka airport clusters invest in full-service consultation formats for premium categories.
Singapore
Biometric passenger verification and unified commerce platforms reduce dwell-time friction at Changi Airport. The country's national aviation regulator supports seamless pre-order-to-pickup workflow deployment. Marina Bay and Jewel retail clusters integrate digital and physical fulfillment channels.
Vietnam
Airport privatization tenders open duty-free concessions to international operators in underpenetrated secondary hubs. The country's national customs authority develops frameworks for real-time inventory authentication. Ho Chi Minh City and Da Nang aviation clusters scale passenger throughput faster than retail infrastructure.
Asia-Pacific Duty-Free Retailing Market Competitive Landscape
Top-tier vendors anchor Hainan and Korean hub positions, while mid-scale concessionaires compete for Southeast Asian privatization tenders. The vendor base stratifies across three tiers: state-affiliated monopolies, diversified travel retail conglomerates, and specialized regional operators. Two strategic archetypes dominate: geography-locked exclusivity holders and technology-enabled platform operators. Competitive moves concentrate on M&A for concession rights and biometric infrastructure deployment.
Among Chinese state-affiliated operators, China Duty Free Group exemplifies the geography-locked monopoly archetype through its Hainan Island position. Korean conglomerate-tier players Lotte Duty Free and Shilla Duty Free occupy positions defined by K-beauty brand exclusivity and celebrity licensing partnerships. These three companies represent distinct competitive vectors: domestic market capture, transit passenger retention, and technology-mediated service design.
| Leading Market Players |
|---|
| China Duty Free Group |
| Lotte Duty Free |
| Shilla Duty Free |
| DFS Group |
| Avolta AG |
| King Power International Group |
| Gebr. Heinemann |
| Ever Rich Duty Free |
| Lagardère Travel Retail |
| Others |
Value Network & Pricing Analysis
Hainan Island's domestic tourist surge redirects procurement volumes toward China Duty Free Group's monopoly, forcing concessionaires to restructure supplier relationships and absorb compliance cost inflation from SAMR documentation mandates.
Pricing Analysis
Travel-exclusive SKU bundling against unbundled commodity spirits creates the dominant pricing split. Three-tier pricing structure across travel-exclusive, domestic parallel, and gray-market channels separates legitimate inventory from diverted stock. Price differentiation hinges on brand-controlled scarcity and real-time customs authentication overhead. Pricing pressure stems from digital pre-order platforms compressing location premiums at physical airport floors. Business travelers show lowest price sensitivity due to compressed schedules, while leisure tourists exhibit highest elasticity to promotional depth.
Supply Chain Analysis
Fragrance and cosmetics supply rests on French and Swiss specialty chemical producers for concentrated formulations, with secondary blending capacity in South Korea and Singapore for K-beauty and regional SKUs. Glass bottle sourcing concentrates in Italy and China, while travel-exclusive packaging design feeds from Paris and Milan creative agencies. Single-source vulnerability runs through LVMH and Estée Lauder portfolio allocation decisions for duty-free exclusives. Distribution runs through bonded warehouse networks at Changi, Incheon, and Sanya Haikou International Airport, with real-time customs API integration determining release velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Chinese domestic tourists pivot spend toward Hainan Island's duty-free zone, elevating premium fragrance and cosmetics specifications over mass-market commodity SKUs.
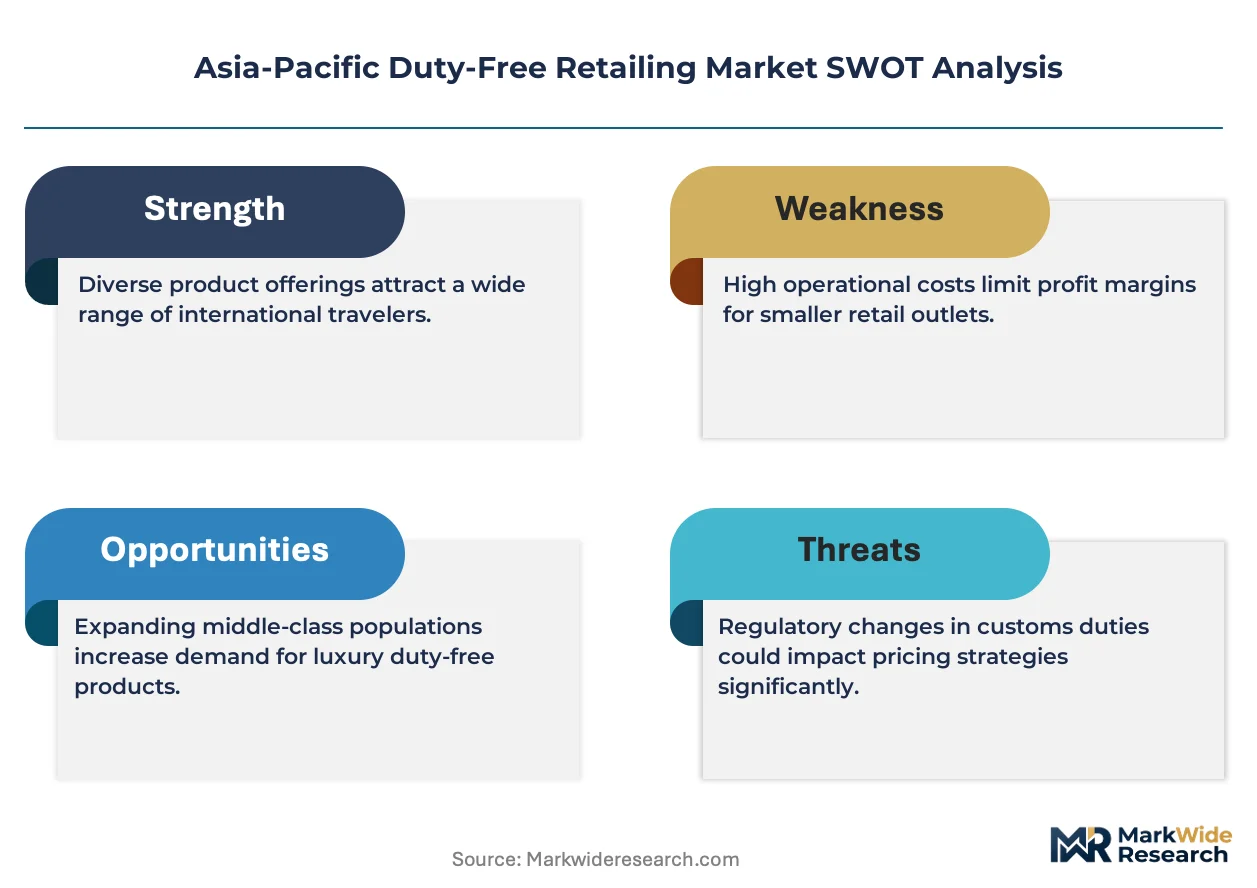
For Market Incumbents: Anticipate biometric verification infrastructure and unified commerce platform deployment as defensive necessities against dwell-time erosion from digital pre-order substitution. Deepen K-beauty brand exclusivity and celebrity licensing partnerships to retain Chinese transit passengers facing Korea Customs Service purchase limits. Prioritize SAMR compliance infrastructure investment as a margin defense lever against smaller concessionaires lacking capital for real-time customs integration. For New Entrants and Emerging Players: Blockchain-IoT inventory tracking technology offers a wedge into Vietnam and Indonesia airport privatization tenders where legacy operators lack provenance verification capabilities. Target underpenetrated secondary Southeast Asian hubs in Da Nang and Surabaya where passenger growth outstrips retail infrastructure deployment. Pursue white-label concession partnerships with state aviation authorities rather than direct brand licensing to circumvent incumbent exclusivity moats. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-enabled platform operators possessing biometric infrastructure and unified commerce stack deployment capability across multiple jurisdictions. Long-term viability favors scaled players with legal infrastructure for METI consumer protection alignment and SAMR documentation compliance. Watch Korea Customs Service purchase limit relaxation as the critical inflection signal for Korean hub recovery against Hainan diversion.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Infrastructure Deployment | Changi Airport's facial recognition systems reduce transaction friction and expand throughput per square meter. |
| Brand Exclusivity Deepening | Lotte Duty Free's K-beauty licensing partnerships defend Korean hub competitiveness against Hainan diversion. |
| Unified Commerce Platform Integration | Singapore and Hong Kong operators consolidate passenger data, inventory, and payment into seamless pre-order-to-pickup workflows. |
| Blockchain-IoT Inventory Tracking | Real-time provenance verification reduces customs inspection delays and shrinkage losses for fragrance and spirits SKUs. |
| Regulatory Compliance Infrastructure | SAMR-mandated real-time customs integration creates compliance moats favoring scaled concessionaires with capital reserves. |
Research Methodology
Bottom-up passenger traffic and dwell-time modeling reconciled against top-down concession revenue tracking forms the analytical core of this study. Primary interviews with airport concession directors, duty-free procurement managers, brand licensing executives, and customs technology officers combined with secondary validation from SAMR regulatory filings, Korea Customs Service policy bulletins, and airport authority tender documents. Trade data from China's MIIT cross-border e-commerce monitoring systems and Singapore's aviation regulator passenger statistics anchored supply-side triangulation against demand-side spend pattern surveys.
Input-output matrices map passenger volume by corridor against SKU-level margin profiles and authentication cost burdens across the projection horizon. Segmentation dimensions include product category, distribution channel, customer type, and service format, with regional regulatory cluster as an additional duty-free-specific dimension. CAGRs derive from corridor-specific passenger recovery trajectories, concession contract renewal terms, and compliance cost inflation curves. Forecast inputs incorporate biometric verification adoption rates and digital pre-order platform penetration assumptions.
The model holds under stable cross-border air traffic normalization and continued Hainan Island policy support; deviation in Korea-Japan diplomatic relations or SAMR enforcement intensity would shift corridor-level revenue allocations. A small set of named triggers—Korea Customs Service purchase limit adjustments, Vietnam airport privatization timelines, and blockchain-IoT authentication standardization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Subscription Box Market
Retailing
North America Retail Vending Machine Market
Retailing
Home Shopping Market
Retailing
Philippines Retail Industry Market
Retailing
Department Stores Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
Floor Mat Rental Service Market
Retailing
Consumer Products and Retail Market
Retailing
Retail Display Racks Market
Retailing
Global Food and Non-Food Retail Market
Retailing
Thailand Retail Market
Retailing
Vietnam Retail Market
Retailing
Furniture Rental Service Market
Retailing
Retail Signage Market
Retailing
Qatar Retail Market
Retailing
China Retail Market