
 Qatar Retail Market | 2026-2036
Qatar Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Retail Market Insights
Luxury hospitality and F&B integration with retail is realigning how operators configure floor space in Doha's premium developments. Al Mana leverages its long-standing automotive and luxury brand representation to sustain dominance in high-end watch and fashion segments. Chalhoub Group anchors its position through curated beauty and luxury portfolios across Gulf markets. LuLu Group International competes on grocery volume and price positioning, extending its hypermarket footprint to capture budget-conscious expatriate households.
Qatar retail encompasses the sale of finished goods to end consumers through physical and digital channels, spanning product categories from perishables to durables, with transaction completion occurring at point-of-sale systems integrated with inventory management and customer relationship platforms. The sector serves household consumption, tourism spending, and business procurement needs across a small, high-income population base. Clothing and electronics segments lead revenue generation, while online channels represent the fastest-growing distribution pathway as logistics infrastructure matures. The luxury price tier commands disproportionate margin pools, reflecting Qatar's per-capita wealth concentration and tourist inflows from premium travel segments.
Qatar's Ministry of Commerce and Industry, the Qatar Central Bank, and the Qatar Tourism Authority collectively shape market access through commercial agency rules, payment system oversight, and visitor visa policies that directly affect tourist spending volumes. Product standards for imported electronics and food items require compliance certification, filtering which international suppliers can operate directly versus through local partners. Stakeholders must monitor Lusail's retail development pipeline and evolving e-commerce fulfillment regulations to anticipate where competitive positioning will shift next.
Market Dynamics
Qatar's Ministry of Commerce and Industry has tightened commercial agency regulations, forcing international brands to restructure market entry through mandatory local partnerships rather than direct operations.
Growth Catalysts
- Commercial Agency Law Reform:The Ministry of Commerce and Industry's updated framework mandates local representation, creating structured partnership opportunities for domestic distributors.
- Lusail Development Pipeline:New mall construction in this emerging district is drawing anchor tenants and premium retail clustering away from saturated West Bay corridors.
- Experiential Retail Integration:Hospitality and F&B operators are leasing contiguous floor space, extending dwell time and per-visit spending among high-net-worth consumers.
Market Restraints
- Import Dependency for Electronics:Compliance certification requirements for consumer electronics create bottlenecks at Qatar's ports, extending time-to-shelf for new product launches.
- Labor Market Concentration:Retail operations rely heavily on expatriate workforce segments subject to visa quota fluctuations and sponsorship system reforms.
- Real Estate Cost Escalation:Premium mall space in Doha's established districts commands rents that compress margins for mid-tier fashion and general merchandise operators.
Strategic Opportunities
- E-commerce Fulfillment Maturation:Logistics infrastructure investments are enabling same-day delivery capabilities previously limited to grocery verticals.
- Tourist Visa Liberalization:Qatar Tourism Authority's expanded entry policies are extending visitor stays and duty-free spending allowances.
- Beauty and Personal Care White Space:Curated prestige beauty portfolios remain underrepresented relative to Gulf peers, creating assortment differentiation potential.
Industry Challenges
- Inventory Localization Complexity:Point-of-sale and ERP integration with legacy stock management systems requires capex outlays that strain mid-size operator balance sheets.
- Payment System Fragmentation:Qatar Central Bank oversight of digital wallet providers creates compliance timelines that delay omnichannel rollout for multi-brand retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Retail Market |
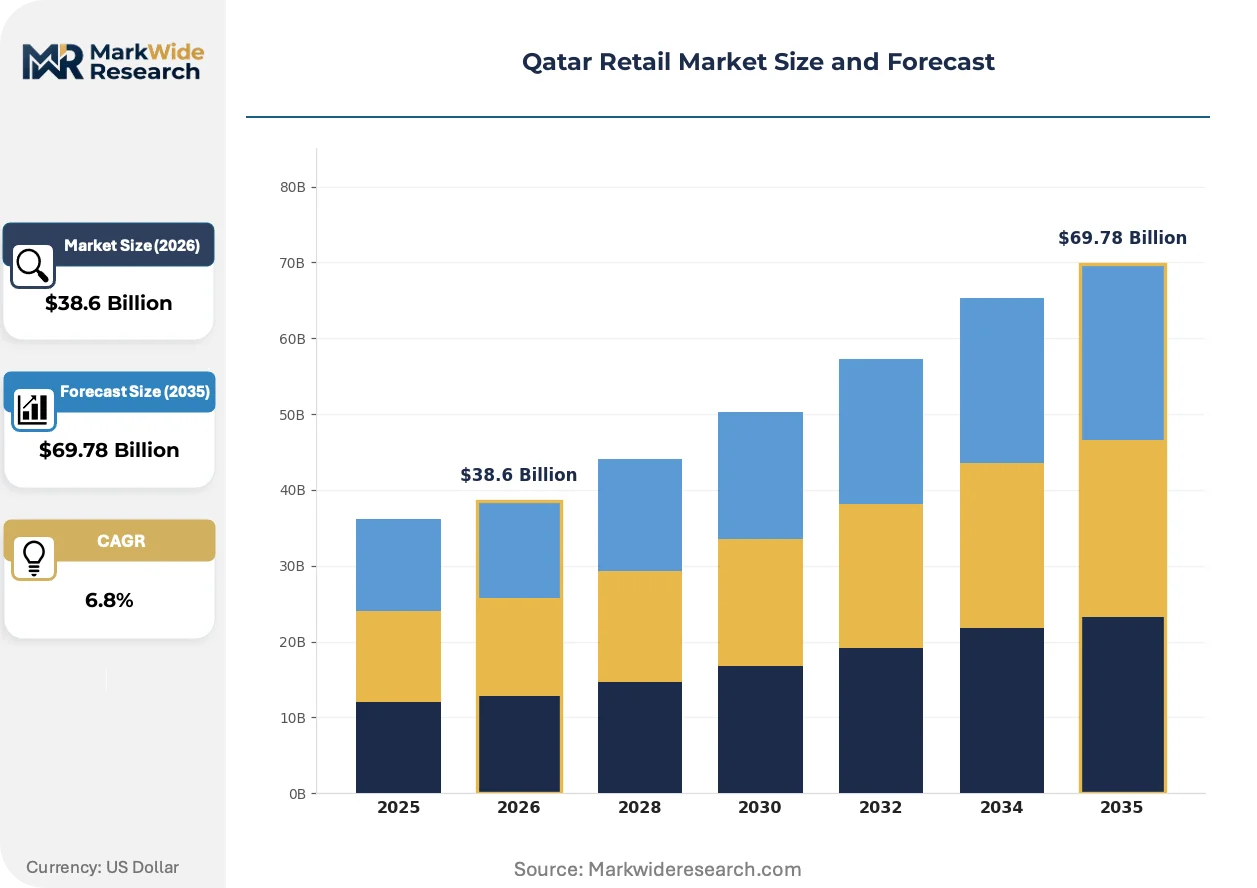
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Electronics, Groceries, Home Decor Price Tier: Luxury, Mid-Range, Budget, Discount Distribution Channel: Online, Department Stores, Supermarkets, Specialty Stores Customer Type: Local Residents, Tourists, Expatriates, Business Professionals |
| Companies Covered | Chalhoub Group, LuLu Group International, Alshaya Group, Gulf Marketing Group, Al Jassim Group, Al Tayer Group, Al Mana, Landmark Group, Majid al Futtaim Retail, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Retail Market Trends and Innovations
Retail configuration in Qatar is pivoting toward immersive environments where transaction volume matters less than per-visit yield. Technology deployment and regulatory adaptation are determining which operators capture this shift.
Artificial intelligence-powered demand forecasting is absorbing historical sales volatility across fashion and electronics categories. Department store operators and luxury multi-brand concepts are adopting these tools to reduce markdown exposure on seasonal inventory. The technology is absorbing guesswork from buying decisions, compressing working capital cycles for distributors managing multiple agency lines.
Qatar Central Bank's oversight framework for Buy Now Pay Later services is reshaping checkout infrastructure requirements. The regulation mandates real-time credit scoring integration and caps on transaction volumes for unlicensed providers. Electronics and furniture retailers are most affected, with several operators pausing BNPL partnerships until licensing pathways clarify.
Visitor purchasing patterns are fragmenting across shorter, higher-frequency trips rather than concentrated seasonal spending. Luxury malls in Lusail are responding with appointment-based personal shopping and private suite configurations. This behavioral shift is most visible among tourists from South Asian source markets, where pre-trip planning and mobile booking now dominate itinerary construction.
Qatar Retail Market Segmentation
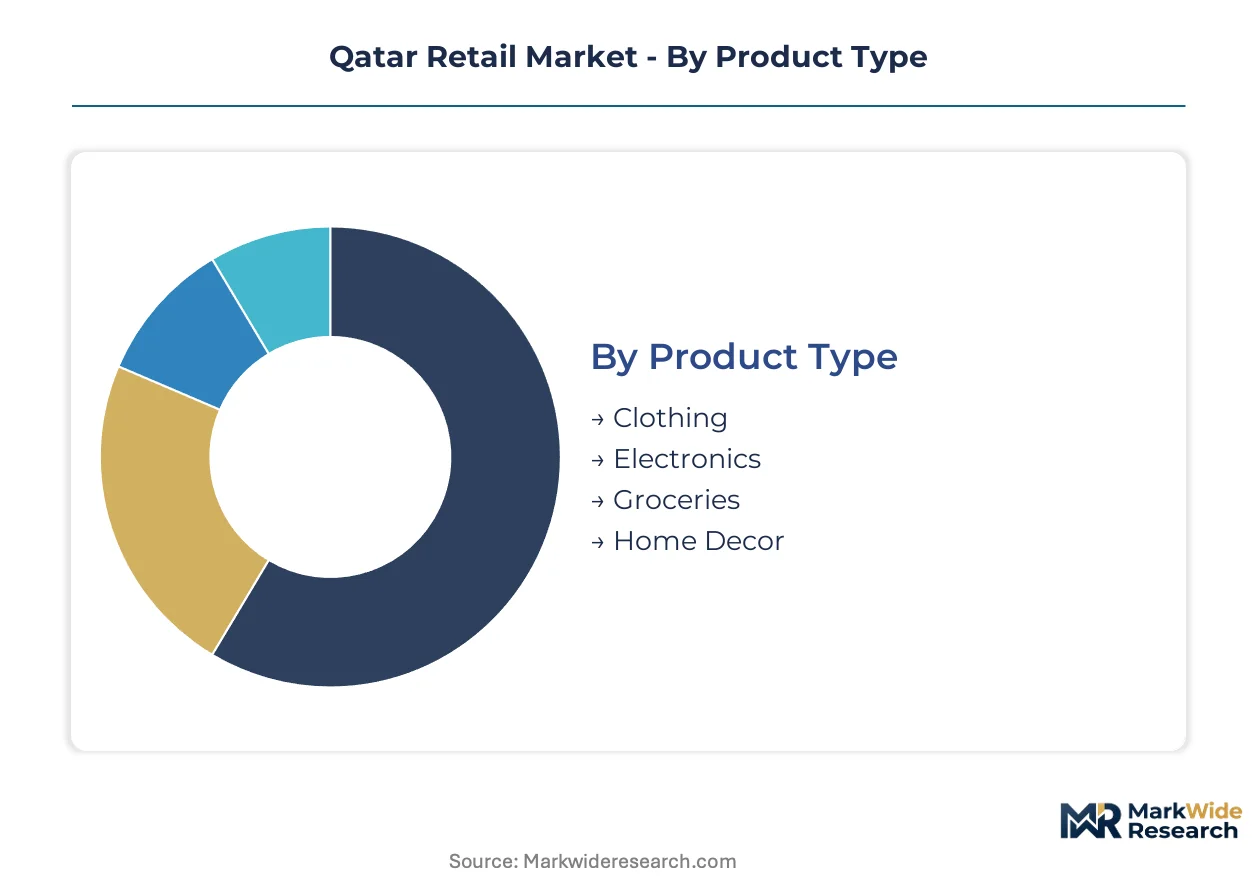
Retail segmentation in Qatar reflects purchasing power concentration among high-net-worth households and tourists, alongside distinct channel preferences shaped by infrastructure maturity. Understanding these divides enables operators to align inventory depth, location strategy, and service models with profit pool distribution.
Product Type:
Standardization dominates commodity categories while customization potential concentrates in discretionary segments where brand equity and experiential presentation differentiate capture rates.
- Clothing:Apparel spans fast fashion through haute couture, with sizing and climate-adapted fabrics responding to regional preferences. Demand clusters in Doha's West Bay luxury corridors and Lusail's emerging mall developments, driven by tourist visa liberalization extending visitor dwell time.
- Electronics:Consumer devices and home appliances require Qatar Central Bank payment system compliance and Ministry of Commerce import certification. Certification bottlenecks at Doha Port compress margins for mid-tier operators while benefiting established distributors with regulatory relationships.
- Groceries:Perishables and packaged foods dominate transaction frequency, with LuLu Group and Carrefour competing on hypermarket footprint and price positioning.
- Home Decor:Furniture and interior furnishings serve expatriate household formation and luxury residential development in Lusail.
Leading the category by volume: Groceries. Expanding most quickly: Electronics.
Price Tier:
Margin structure inversely correlates with price tier, as luxury commands disproportionate profit pools relative to transaction frequency.
- Luxury:High-end watches, fashion, and jewelry sustain 40-60% gross margins through exclusive distribution rights and appointment-based service models. Al Mana and Chalhoub Group dominate agency representation, with Lusail's private suite configurations capturing tourist spending.
- Mid-Range:Accessible premium brands bridge mass market and luxury, occupying anchor tenant positions in established malls. West Bay rent escalation pressures operators to optimize floor productivity through hospitality-F&B adjacencies.
- Budget:Value-oriented general merchandise serves price-sensitive expatriate segments in secondary mall locations.
- Discount:Promotional pricing and outlet formats remain underdeveloped relative to Gulf peers, constrained by limited off-mall retail zoning.
Highest margin capture: Luxury. Steepest expansion trajectory: Mid-Range.
Distribution Channel:
Channel investment intensity tracks customer acquisition cost differentials, with digital infrastructure capex displacing traditional square footage expansion.
- Online:E-commerce platforms and marketplace aggregators leverage same-day delivery infrastructure investments previously limited to grocery verticals. Qatar Central Bank digital wallet oversight creates compliance timelines delaying omnichannel rollout for multi-brand operators.
- Department Stores:Multi-brand concepts integrate AI-powered demand forecasting to reduce fashion markdown exposure, compressing working capital cycles.
- Supermarkets:Hypermarket and supermarket formats anchor grocery volume, with LuLu extending footprint to capture budget-conscious households.
- Specialty Stores:Mono-brand boutiques and curated concept stores concentrate in premium mall developments, emphasizing experiential engagement over transaction velocity.
Dominant by revenue: Department Stores. Gaining share fastest: Online.
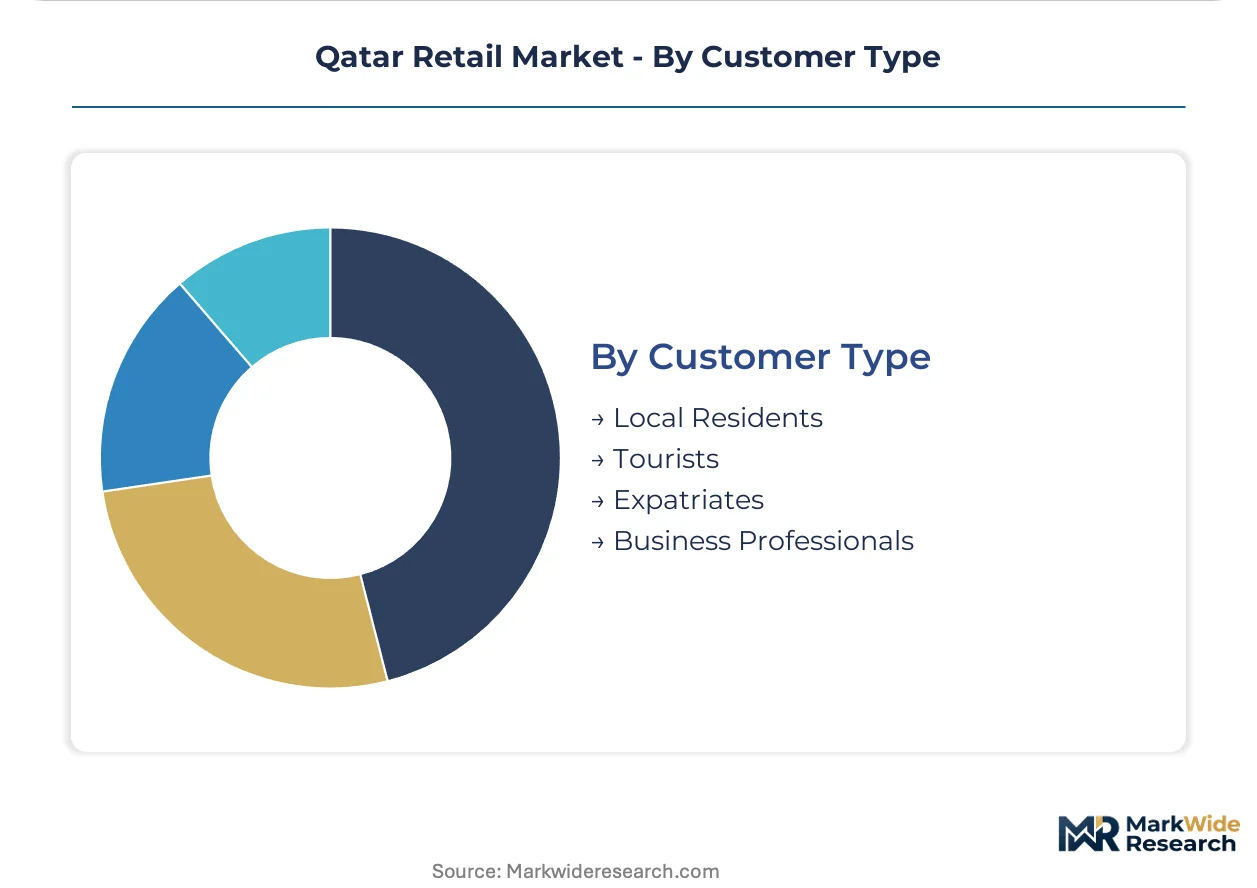
Customer Type:
Spending pattern fragmentation across resident, visitor, and professional segments determines location strategy and assortment breadth.
- Local Residents:Qatari nationals and established families drive luxury watch, jewelry, and high-fashion demand through relationship-based purchasing at Al Mana-flagged boutiques.
- Tourists:Visitor spending concentrates in duty-free and luxury mall environments, with South Asian source markets shifting toward pre-trip mobile booking and appointment-based personal shopping.
- Expatriates:Budget-conscious households from South Asia and Southeast Asia sustain grocery hypermarket volume and mid-range fashion turnover.
- Business Professionals:Corporate transient demand supports convenience-oriented formats and business district retail in West Bay office corridors.
Largest spending pool: Local Residents. Fastest-growing segment: Tourists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's Ras Bufontas Free Zone and Qatar Science & Technology Park concentrate logistics and distribution infrastructure, anchoring retail supply chain investment in the emirate's commercial corridors.
West Bay
Luxury watch and fashion demand concentrates along the Doha Corniche and City Center corridors, driven by high-net-worth Qatari nationals and corporate transients. Qatar Central Bank payment system oversight shapes point-of-sale infrastructure requirements for international brand boutiques. The district's established mall developments face rent escalation pressures as hospitality-F&B adjacencies reshape floor space economics.
Lusail
New mall construction and residential development are drawing anchor tenants away from saturated West Bay corridors, with private suite configurations targeting tourist spending. Qatar Tourism Authority's visitor visa liberalization extends dwell time for South Asian source markets. Place Vendôme and Lusail Marina cluster premium retail around experiential hospitality integration.
The Pearl-Qatar
Affluent resident demand supports curated lifestyle retail and waterfront dining concepts across the artificial island's precincts. Ministry of Commerce and Industry commercial agency regulations mandate local partnership structures for international brands entering this high-income enclave. Porto Arabia and Qanat Quartier concentrate mono-brand boutiques and specialty F&B operators.
Al Wakrah and Industrial Area
Budget-conscious expatriate households from South Asia sustain hypermarket volume and value-oriented general merchandise turnover. Qatar's port infrastructure and customs certification requirements for imported electronics create distribution bottlenecks affecting time-to-shelf. The Industrial Area's logistics warehousing supports last-mile fulfillment capabilities for e-commerce platforms.
Al Khor and Northern Municipalities
Resident population growth and liquefied natural gas industry employment anchor convenience retail and grocery expansion beyond Doha's core. Infrastructure investment in northern road corridors improves supply chain connectivity for distribution operators. Ras Laffan's industrial workforce generates captive demand for food service and essential retail formats.
Qatar Retail Market Competitive Landscape
Top-tier vendors anchor luxury brand representation, while mid-scale operators compete on grocery volume and hypermarket footprint. The market structure reflects concentrated agency rights held by long-established family conglomerates alongside Gulf-based retail specialists expanding across GCC markets. Three archetypes dominate: luxury multi-brand distributors, grocery hypermarket chains, and regional franchise operators. Competitive moves center on securing exclusive commercial agency licenses and integrating hospitality-F&B adjacencies within premium mall developments.
Among Qatar-based luxury distributors, Al Mana exemplifies the multi-sector conglomerate archetype spanning automotive and high-end fashion representation. Chalhoub Group occupies a position as the Gulf-wide beauty and luxury specialist with curated portfolio concentration. LuLu Group International sits within the volume-driven grocery tier, competing on price positioning and hypermarket footprint expansion across budget-conscious expatriate segments.
| Leading Market Players |
|---|
| Chalhoub Group |
| LuLu Group International |
| Alshaya Group |
| Gulf Marketing Group |
| Al Jassim Group |
| Al Tayer Group |
| Al Mana |
| Landmark Group |
| Majid al Futtaim Retail |
| Others |
Pricing and Supply Chain Analysis
Luxury-to-mass tier divergence in Qatar retail manifests through import certification bottlenecks at Doha Port that inflate landed costs for mid-tier electronics while exclusive agency rights protect premium watch and fashion margins. Qatar Central Bank payment system compliance adds friction to omnichannel pricing parity, segmenting supply chain responsiveness between established distributors with regulatory relationships and new entrants facing extended time-to-shelf.
Pricing Analysis
Short lead-time premiums attach to luxury fashion and electronics launches cleared through established distributor relationships with Qatar's Ministry of Commerce and Industry. Three-tier pricing structure across luxury, mid-range, and budget levels stratifies by brand exclusivity and after-sales service bundling. Cost compression in mid-range apparel intensifies because West Bay rent escalation forces hospitality-F&B adjacency investments. Expatriate households from South Asia exhibit highest price sensitivity, while Qatari nationals demonstrate lowest sensitivity to premium markups on exclusive agency lines.
Supply Chain Analysis
Single-source vulnerability sits with China for consumer electronics manufacturing and India for textile inputs, with both feeding through Doha Port certification checkpoints. Raw material dependencies span semiconductor components, climate-adapted fabrics, and perishable food imports. Tariff exposure concentrates in electronics categories subject to Qatar Central Bank payment system oversight and Ministry of Commerce import documentation. Distribution runs through Ras Bufontas Free Zone logistics warehousing, with last-mile fulfillment extending to Lusail and West Bay mall developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar retail operates as a supply-constrained market where premium mall space scarcity in Doha's established districts props pricing power for incumbent luxury distributors. Limited off-mall retail zoning and commercial agency law mandates create structural bottlenecks that sustain margin pools.
For Market Incumbents: Hedge against Lusail development pipeline saturation by securing exclusive commercial agency licenses ahead of competitor entry. Defensive consolidation through backward integration into logistics warehousing at Ras Bufontas Free Zone counters rent escalation pressures in West Bay. Channel control investments in appointment-based personal shopping infrastructure capture shifting tourist purchasing patterns from South Asian source markets.
For New Entrants and Emerging Players: The price-point gap between luxury agency lines and budget hypermarket formats offers white-space targeting in curated prestige beauty portfolios, which remain underrepresented relative to Gulf peers. Most penetrable segment sits with mid-range fashion bridging mass and luxury through hospitality-F&B adjacencies in emerging Lusail developments. Go-to-market angle centers on e-commerce fulfillment partnerships leveraging same-day delivery infrastructure maturation beyond grocery verticals.
For Investors and Strategic Acquirers: Re-rating potential sits with regional grocery hypermarket chains given Qatar Tourism Authority visa liberalization extending visitor dwell time and duty-free spending allowances. Long-term viability over a five-to-ten year horizon favors operators with captive logistics infrastructure and exclusive brand representation portfolios. Acquisition target archetype includes mid-scale distributors with underutilized commercial agency licenses and scalable e-commerce fulfillment capabilities. Signal to watch is Ministry of Commerce and Industry enforcement patterns on foreign direct investment restrictions in retail operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Commercial Agency Licensing | Qatar's Ministry of Commerce and Industry mandates local partnerships, creating defensible market access moats. |
| E-commerce Fulfillment Infrastructure | Same-day delivery capabilities beyond grocery verticals unlock omnichannel revenue capture for multi-brand operators. |
| Hospitality-F&B Floor Space Integration | Experiential retail adjacencies in Lusail and West Bay malls extend dwell time and per-visit spending yields. |
| Beauty Portfolio Curation | Prestige beauty assortment gaps relative to Gulf peers create differentiation potential for specialized distributors. |
| Logistics Warehousing Expansion | Ras Bufontas Free Zone concentration supports last-mile efficiency and import certification bottleneck mitigation. |
Research Methodology
Independent corroboration across distributor executives, mall development operators, and regulatory affairs specialists underwrites the qualitative findings on commercial agency law impacts. Primary interviews with luxury brand managers, hypermarket procurement leads, and Qatar Tourism Authority planning officers combined with secondary validation from customs trade records, SEC filings of listed retail conglomerates, and Qatar Central Bank payment system disclosures. Bottom-up channel volume estimates and top-down GDP consumption allocation triangulate market sizing across the analysis window.
Comparable-period anchoring to pre-pandemic tourist spending baselines and post-liberalization visa policy implementation frames the projection horizon. Segmentation dimensions modeled span price tier, product category, distribution channel, and customer archetype alongside regulatory compliance tier as an industry-specific dimension. CAGRs derive from fitted trend extrapolation adjusted for Ministry of Commerce policy enforcement intensity and Lusail development pipeline completion rates. Forecast inputs include visitor arrival patterns from South Asian source markets and hypermarket footprint expansion announcements.
Underlying measurement precision varies by segment; luxury brand representation and grocery hypermarket volume carry tighter precision than emerging e-commerce platform revenue. Forecasts reflect assumptions on Qatar Tourism Authority policy continuity and commercial agency law enforcement consistency. Specific risk factors that could revise projections include port infrastructure bottlenecks, expatriate visa quota fluctuations, and payment system regulatory delays. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Floor Mat Rental Service Market
Retailing
Home Shopping Market
Retailing
Consumer Shopping Cart Market
Retailing
North America Retail Vending Machine Market
Retailing
Out-Door Signage Market
Retailing
Department Stores Market
Retailing
In Store Signage Market
Retailing
Australia Retail Bags Market
Retailing
Retail Vending Machine Market
Retailing
United States Hardware Stores Retail Market
Retailing
Floor Displays Market
Retailing
Singapore Gifting Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
Electronics Retailing Market
Retailing
Vietnam Retail Market