
 Furniture Rental Service Market | 2026-2036
Furniture Rental Service Market Size, Share, and Industry Trends Forecast 2026-2036
Furniture Rental Service Market Analysis
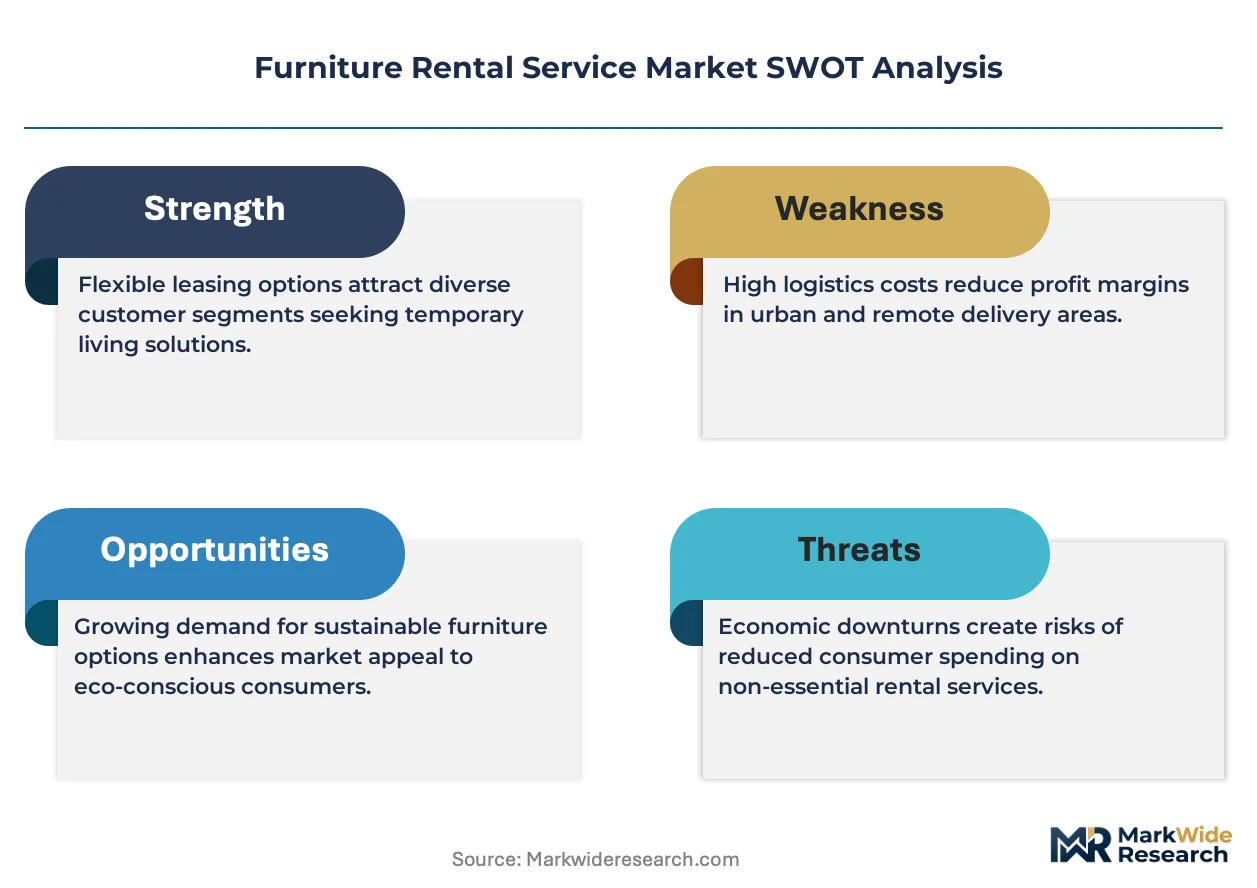
ISO 14001 environmental management certification is bifurcating the competitive landscape into compliant and non-compliant tiers. CORT sustains broad geographic coverage through its national warehouse and delivery infrastructure. Feather differentiates via technology leadership in digital inventory management and subscription customization. Furlenco anchors high-frequency residential turnover in dense Indian metropolitan markets.
Furniture rental services involve the temporary provision of movable assets—typically sofas, desks, chairs, and tables—through contractual agreements specifying duration, condition standards, and return protocols, with inventory depreciated over standardized useful lives. The primary commercial purpose centers on converting capital expenditure into operational expenditure while preserving flexibility for end-users facing mobility or scaling uncertainty. Residential rental commands the largest revenue pool due to recurring monthly subscriptions, while event rental generates the highest per-transaction margins despite episodic demand. Corporate customer segments increasingly favor yearly terms that reduce administrative overhead compared to monthly cycles.
The US EPA guides chemical emissions standards for upholstered products, directly affecting refurbishment costs and inventory eligibility for rental circulation. The EU REACH regulation and F-Gas Framework impose material traceability and climate-impact disclosures that operators must embed in logistics contracts. India's BIS certification mandates durability testing for re-rented furniture, creating compliance barriers for informal competitors. Stakeholders must monitor how extended producer responsibility amendments in multiple jurisdictions will redistribute end-of-life costs between manufacturers and rental platforms.
Market Dynamics
Extended producer responsibility amendments are redistributing end-of-life costs between manufacturers and rental platforms, forcing operators to redesign logistics contracts and refurbishment workflows around asset recovery obligations.
Growth Catalysts
- Corporate Relocation Programs:United States enterprises are expanding commercial adoption through flexible workspace policies that convert capital expenditure into operational expenditure for mobile workforces.
- Circular Economy Regulations:The European Union's asset recovery obligations are creating compliant operational tiers that favor certified rental operators over informal competitors.
- Urban Migration Patterns:India's startup density and metropolitan residential turnover are accelerating subscription uptake for temporary furnishing solutions.
Market Restraints
- Refurbishment Cost Volatility:The US EPA's chemical emissions standards for upholstered products directly inflate reconditioning expenses and restrict inventory eligibility for rental circulation.
- Compliance Fragmentation:India's BIS certification mandates durability testing that creates barriers for informal operators, concentrating supply among capital-intensive incumbents.
- Substitution Pressure:Second-hand furniture marketplaces and peer-to-peer rental platforms erode pricing power for established subscription models.
Strategic Opportunities
- Technology Convergence:Digital inventory management systems integrating IoT sensors with predictive maintenance algorithms enable condition-based pricing and automated return protocols.
- Regulatory Tailwinds:The EU F-Gas Framework's climate-impact disclosure requirements create competitive differentiation for operators embedding carbon accounting into logistics contracts.
- Channel Innovation:Embedded finance partnerships with property technology platforms allow point-of-lease origination at apartment move-in, capturing demand at decision moments.
Industry Challenges
- ISO 14001 Certification Timelines:Environmental management system implementation requires 12-18 month compliance windows that delay market entry for new operators.
- Legacy System Integration:Enterprise resource planning migration to subscription-native platforms creates operational friction for established players with depreciated technology stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furniture Rental Service Market |
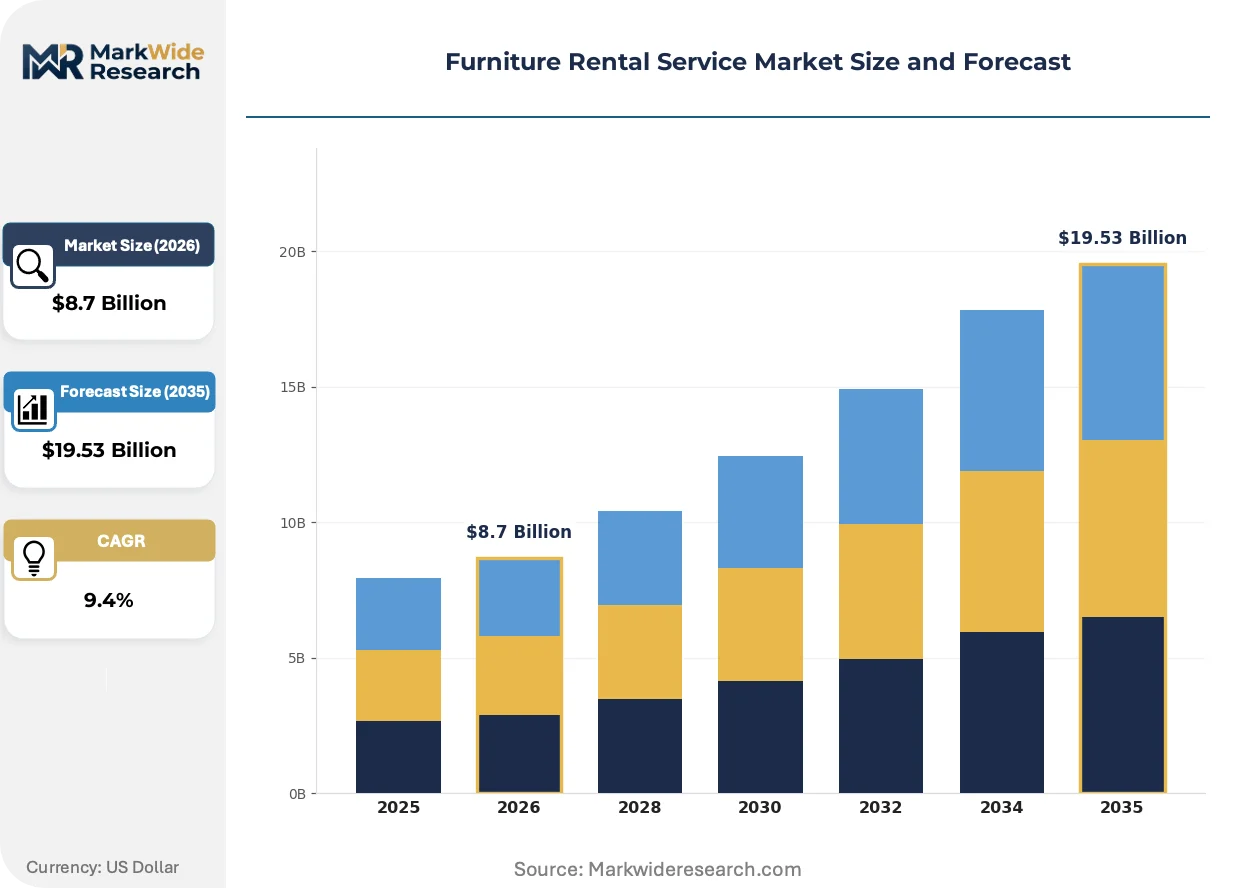
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Rental, Office Rental, Event Rental, Short-term Rental Product Type: Sofas, Desks, Chairs, Tables Customer Type: Individuals, Corporates, Event Planners, Startups Duration: Monthly, Yearly, Weekly, Daily |
| Companies Covered | Feather, Luxe Modern Rentals, CORT, AFR Furniture Rental, Fashion Furniture Rental, Furlenco, Brook Furniture Rental, Fernished Inc., RentoMojo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furniture Rental Service Market Emerging Trajectories
Asset digitization and regulatory disclosure mandates are compressing operational margins while creating new service layers around traceability and circularity compliance.
Modular furniture systems with standardized connection interfaces and component-level replaceability are fragmenting traditional product lifecycle economics. Corporate customers in technology and professional services sectors are adopting these systems at accelerating pace to support reconfiguration without full replacement. This technology is fragmenting supplier relationships as buyers source frames, fabrics, and hardware from specialized vendors rather than integrated manufacturers.
The EU REACH regulation's material traceability requirements are imposing documentation burdens across upholstery, adhesives, and surface treatments. Rental operators must now embed substance-of-concern tracking into procurement contracts and refurbishment workflows. Commercial segments serving multinational corporations face the steepest compliance costs, driving consolidation toward operators with dedicated regulatory affairs functions.
Subscription customization tools allowing real-time furniture swaps are displacing fixed-term contracts in residential segments. Digital-native renters in dense Indian and United States metropolitan markets favor platforms offering style rotation over ownership commitment. This behavioral shift compresses customer lifetime value calculations while increasing logistics network density requirements for same-day exchange fulfillment.
Furniture Rental Service Market Segmentation
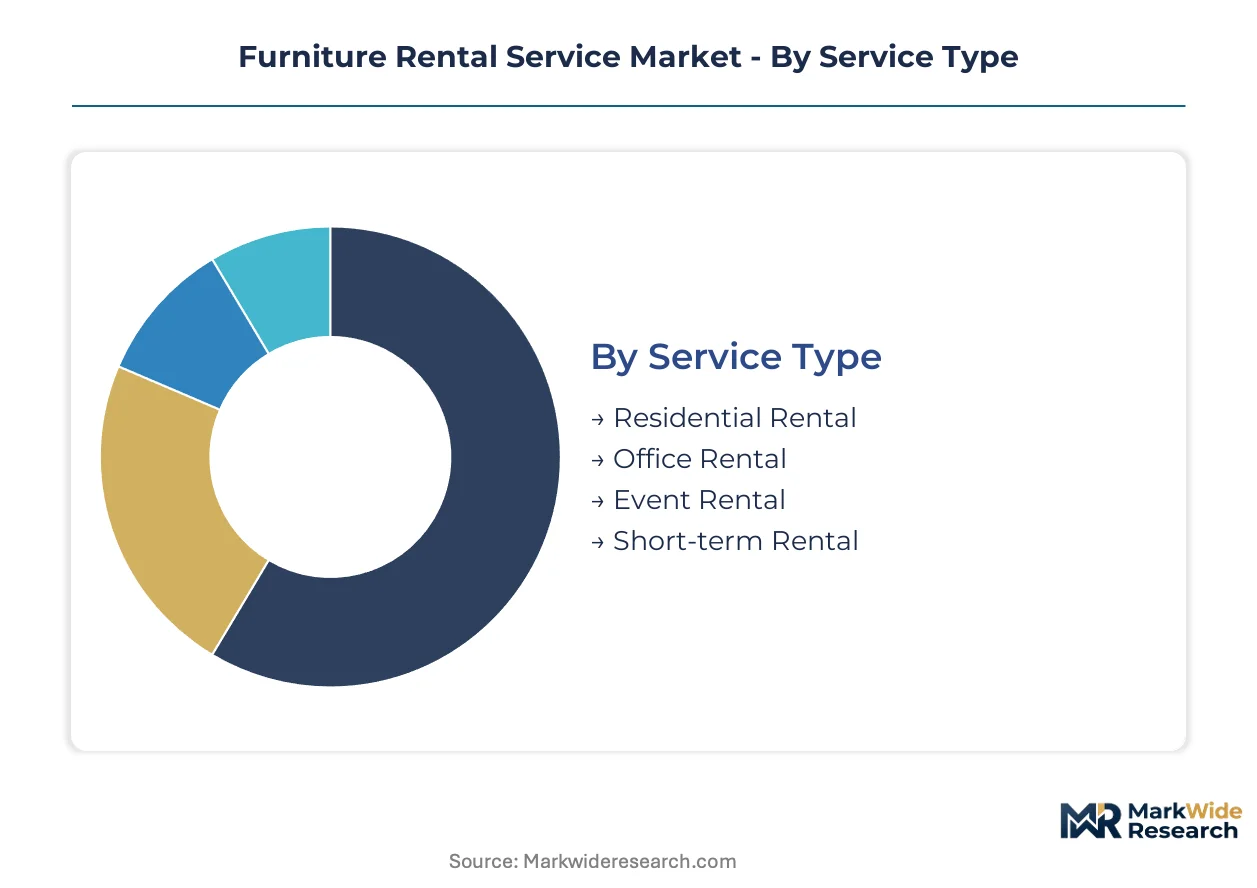
Furniture rental operators configure inventory pools and logistics networks around distinct usage patterns that determine depreciation schedules, refurbishment intensity, and contract structures. Segmentation reveals where capital deployment concentrates and which customer relationships generate recurring revenue versus episodic transactions.
Service Type:
Residential rental dominates domestic consumption patterns across the United States and India, while office and event rental segments serve export-led corporate mobility programs and international exhibition circuits.
- Residential Rental:Monthly subscription models for sofas, beds, and dining sets target urban migrants and temporary residents in metropolitan clusters. Demand concentrates in Bangalore, Mumbai, and New York City where startup density and corporate relocation volumes create sustained turnover.
- Office Rental:Desks, workstations, and conference furniture deployed through yearly contracts support flexible workspace scaling. Corporate customers in technology and professional services sectors favor this segment to convert capital expenditure into operational expenditure during expansion phases.
- Event Rental:High-margin episodic transactions for exhibitions, weddings, and corporate functions. Inventory utilization depends on seasonal concentration in convention hubs.
- Short-term Rental:Weekly and daily furniture provision for temporary housing, film production, and disaster relief. Operators in this segment optimize for rapid deployment velocity rather than asset longevity.
Residential rental holds the largest share; momentum sits with office rental as hybrid work policies extend commercial adoption.
Product Type:
Margin structures vary sharply across product categories, with upholstered items requiring intensive refurbishment and hard surfaces offering longer circulation cycles.
- Sofas:Fabric and leather upholstery systems with standardized dimensions for modular replacement. US EPA emissions standards for chemical treatments directly inflate reconditioning costs and restrict inventory eligibility for rental circulation.
- Desks:Height-adjustable and fixed-surface workstations with component-level replaceability. Corporate customers in technology sectors are adopting modular frame systems that support reconfiguration without full replacement.
- Chairs:Ergonomic task seating and accent furniture with standardized connection interfaces. Durability testing under India's BIS certification creates compliance barriers for informal operators.
- Tables:Dining, conference, and side tables with surface treatments requiring substance-of-concern tracking under EU REACH regulation.
Sofas generate the highest refurbishment revenue per unit; desks are gaining share fastest as modular systems fragment traditional lifecycle economics.
Customer Type:
Contract structures and pricing power diverge between individual subscribers seeking flexibility and institutional buyers optimizing procurement scale.
- Individuals:Digital-native renters in dense metropolitan markets favor platforms offering real-time style rotation over ownership commitment. Subscription customization tools are displacing fixed-term contracts in this segment.
- Corporates:Multinational enterprises with dedicated relocation programs drive yearly contract adoption to reduce administrative overhead. These customers face the steepest EU compliance costs, driving consolidation toward operators with regulatory affairs functions.
- Event Planners:Episodic demand concentrated in convention and wedding seasons. Relationships depend on same-day fulfillment capability and damage waiver terms.
- Startups:High-frequency residential turnover in Indian metropolitan markets accelerates subscription uptake. This segment compresses customer lifetime value calculations while increasing logistics network density requirements.
Corporates anchor contract value; startups are expanding most quickly as venture-funded density rises in Bangalore and Hyderabad.
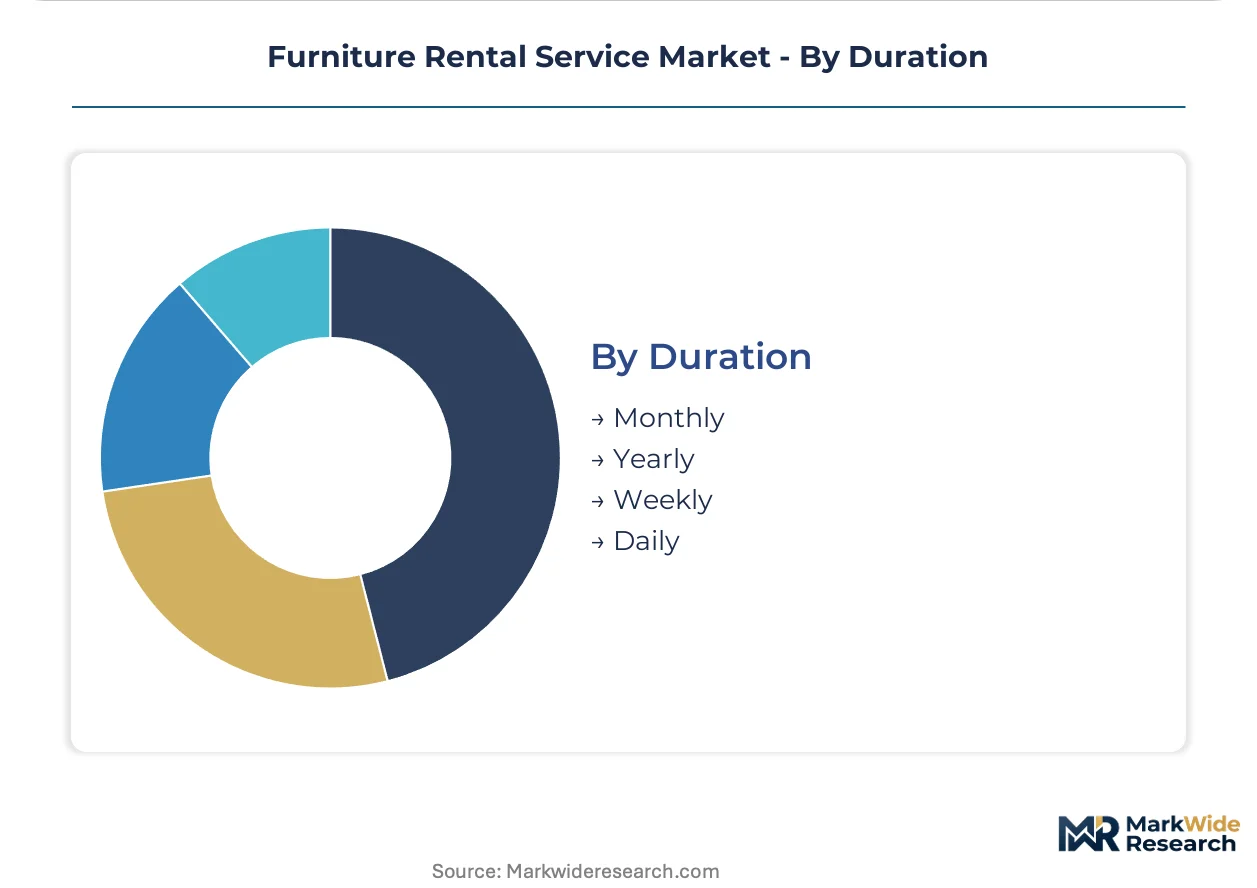
Duration:
Contract length determines logistics routing efficiency and asset depreciation recognition, with longer terms enabling predictive maintenance scheduling.
- Monthly:Residential subscriptions with highest churn rates and style rotation frequency. Platforms optimize for same-day exchange fulfillment in dense urban networks.
- Yearly:Corporate preference reducing procurement cycle burden. These contracts enable condition-based pricing through IoT-enabled inventory tracking.
- Weekly:Transitional housing and temporary project staffing. Operators balance utilization rates against rapid turnaround requirements.
- Daily:Event and emergency provision with premium pricing to offset low asset turns.
Monthly contracts command the largest volume base; yearly terms are climbing the fastest as enterprises consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate relocation managers and startup founders represent the dominant buyer archetypes, with procurement patterns diverging between yearly enterprise contracts and monthly residential subscriptions. Geographic concentration tracks venture capital density and flexible workspace adoption rates.
United States
Corporate relocation programs and hybrid workspace policies drive commercial adoption across technology and professional services sectors. The EPA guides chemical emissions standards for upholstered products, directly affecting refurbishment economics. Demand clusters in New York City and San Francisco where startup density and mobile workforces sustain subscription turnover.
India
Urban migration and venture-funded startup density accelerate residential subscription uptake in metropolitan markets. BIS certification mandates durability testing for re-rented furniture, creating compliance barriers for informal operators. Bangalore and Mumbai anchor inventory deployment as high-frequency turnover compresses customer lifetime value calculations.
Germany
Corporate sustainability mandates and circular economy adoption favor certified rental operators over purchase models. EU REACH regulation imposes material traceability requirements across upholstery and surface treatments. Berlin and Munich concentrate demand as multinational enterprises consolidate vendor relationships around regulatory compliance.
United Kingdom
Flexible workspace scaling and temporary housing demand support both office and residential rental growth. The F-Gas Framework requires climate-impact disclosures embedded in logistics contracts. London dominates transaction volume through dense logistics networks enabling same-day exchange fulfillment.
France
Extended producer responsibility amendments redistribute end-of-life costs between manufacturers and rental platforms. ECHA substance-of-concern tracking mandates documentation across adhesives and fabrics. Paris anchors commercial adoption as enterprises redesign procurement around asset recovery obligations.
Furniture Rental Service Market Vendor Landscape
Player mix skews toward national warehouse operators and digital-native subscription platforms with fragmented regional specialists at the periphery. The vendor base separates into three strategic archetypes: capital-intensive incumbents with logistics infrastructure, technology-led platforms with inventory management systems, and metropolitan-focused specialists with high-frequency turnover expertise. Dominant competitive moves include ISO 14001 certification pursuit and embedded finance partnerships with property technology platforms.
Within the capital-intensive tier, CORT and AFR Furniture Rental occupy positions as established warehouse and delivery infrastructure operators. Feather and Furlenco exemplify the technology-led archetype, with the former representing digital inventory management capabilities and the latter anchoring high-frequency residential turnover in dense Indian metropolitan markets. These four companies collectively illustrate how competitive positioning bifurcates between geographic coverage depth and subscription customization agility.
| Leading Market Players |
|---|
| Feather |
| Luxe Modern Rentals |
| CORT |
| AFR Furniture Rental |
| Fashion Furniture Rental |
| Furlenco |
| Brook Furniture Rental |
| Fernished Inc. |
| RentoMojo |
| Others |
Supply Flow & Price Mechanics
Warehouse network density in the United States and India establishes minimum efficient scale thresholds that filter out sub-scale operators and compress price floors for surviving competitors. National coverage requirements force capital deployment into hub-and-spoke logistics infrastructure, while metropolitan inventory pooling determines last-mile cost structures that differentiate urban versus suburban pricing tiers.
Pricing Analysis
Cost-plus contracts with fuel-surcharge indexation dominate corporate yearly agreements, insulating operators from diesel volatility while exposing margins to labor-cost inflation. Three-tier pricing structure across premium, standard, and economy levels segments residential subscriptions by furniture grade and exchange frequency. Price differentiation hinges on ISO 14001 certification status and same-day fulfillment capability. Cost compression in the refurbishment tier is intensifying because EPA emissions standards for chemical treatments inflate reconditioning expenses. Startups exhibit highest price sensitivity; multinational corporates least.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific manufacturing clusters through Los Angeles and Rotterdam ports constrain inventory acquisition economics for upholstered goods. China, Vietnam, and Malaysia anchor frame and fabric production. Component sourcing draws from specialized adhesive suppliers in Germany and surface-treatment vendors in Italy. Single-source vulnerability concentrates in modular hardware systems patented by select European manufacturers. Distribution runs through national warehouse networks with regional cross-docks enabling next-day residential fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as hybrid work policies splinter corporate demand into project-based and yearly contract niches that national incumbents under-serve. Modular furniture adoption and subscription customization tools are creating service-layer gaps between standardized offerings and tailored enterprise procurement.
For Market Incumbents: Fortify refurbishment capacity in EPA-regulated upholstery categories to defend margin position against specialty reconditioning entrants. Deepen backward integration into logistics real estate in Bangalore and Mumbai to capture Indian startup density before capital-light competitors establish last-mile density. ISO 14001 certification investment remains essential for EU commercial contract eligibility. For New Entrants and Emerging Players: Same-day style rotation for digital-native residential subscribers represents the most penetrable white-space target, as national operators optimize for yearly corporate contracts rather than high-frequency exchange logistics. Embedded finance partnerships with property technology platforms offer direct point-of-lease origination at apartment move-in moments. Target weekly and short-term rental durations where utilization-based pricing models displace fixed subscription tiers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with IoT-enabled inventory tracking and predictive maintenance algorithms over asset-heavy warehouse specialists. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than geographic coverage alone. Acquisition target archetype: metropolitan-focused platforms with dense exchange networks in venture-capital-rich Indian cities. Monitor EU extended producer responsibility amendment implementation timelines as inflection indicator for asset recovery cost redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14001 Certification Pursuit | Environmental management certification unlocks EU corporate contract tiers under REACH and F-Gas disclosure mandates. |
| Embedded Finance Partnership | Property technology platform integration captures residential demand at apartment move-in decision moments. |
| Modular System Adoption | Component-level replaceability fragments supplier relationships and enables reconfiguration without full asset replacement. |
| IoT Inventory Integration | Sensor-enabled condition tracking supports predictive maintenance and automated return protocol enforcement. |
| Refurbishment Capacity Expansion | EPA-compliant reconditioning infrastructure defends margin position against chemical emissions standard cost inflation. |
Methodological Framework
Operator-level perspectives from warehouse logistics directors, refurbishment facility managers, corporate procurement officers, and property technology platform executives anchored the qualitative base. Primary interviews combined with secondary validation from EPA emissions guidance documents, EU ECHA substance-of-concern databases, BIS certification registries, and SEC filings from publicly traded logistics operators. Bottom-up unit economics modeling triangulated against top-down market sizing from national furniture production and trade flow data.
Sensitivity analysis across subscription duration, exchange frequency, and refurbishment cost scenarios shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include service type, product category, customer archetype, and contract duration. CAGRs derived from logistic curve fitting to historical adoption patterns in corporate relocation and residential turnover metrics. Forecast inputs incorporated urban migration velocity indices and venture capital deployment density in Indian metropolitan markets.
Forecasts assume regulatory continuity in EPA emissions standards, EU REACH amendments, and India's BIS durability testing regimes; material policy shifts would require re-modeling of refurbishment cost structures and inventory eligibility constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Subscription Box Market
Retailing
Consumer Shopping Cart Market
Retailing
Home Shopping Market
Retailing
Out Store Signage Market
Retailing
Global Food and Non-Food Retail Market
Retailing
European Discount Retail Market
Retailing
Qatar Retail Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
Australia Retail Bags Market
Retailing
Philippines Retail Industry Market
Retailing
Department Stores Market
Retailing
Singapore Gifting Market
Retailing
Consumer Products and Retail Market
Retailing
Retail Display Racks Market
Retailing
North America Retail Vending Machine Market
Retailing
Retail Signage Market