
 In Store Signage Market | 2026-2036
In Store Signage Market Size, Share, and Industry Trends Forecast 2026-2036
In Store Signage Market Foresight
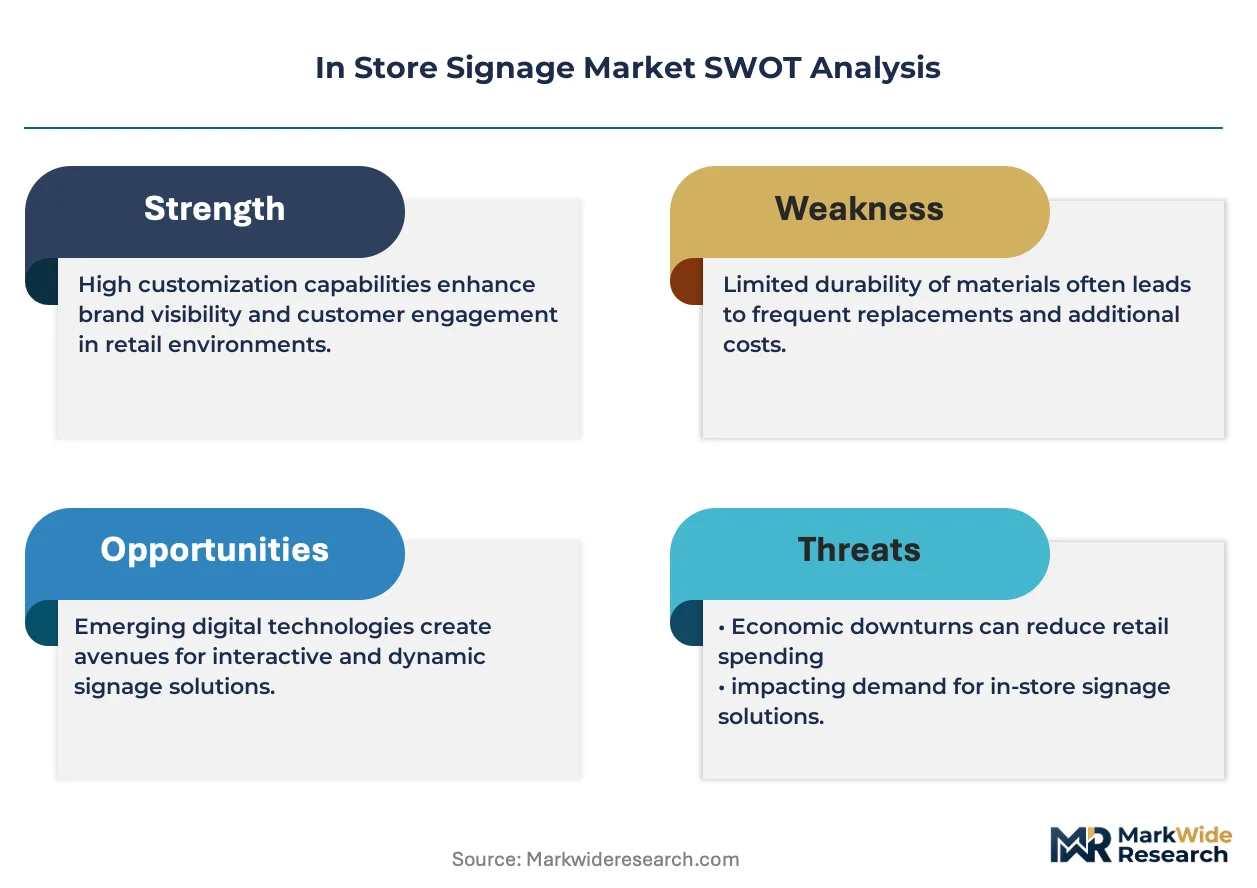
Multi-source procurement for display modules is shifting toward vertically integrated panel suppliers with captive semiconductor capacity. Samsung Electronics leverages in-house chip fabrication to secure supply continuity for high-resolution retail screens. Daktronics anchors its competitive position through specialized manufacturing scale in LED video architecture for big-box environments. LG Electronics differentiates via advanced OLED signage lines that command premium positioning in luxury retail channels.
In store signage encompasses static and dynamic visual communication systems deployed within retail environments to direct, inform, or persuade shoppers at the point of purchase, typically incorporating substrates such as vinyl, fabric, or direct-view LED with luminance ratings exceeding 1,000 nits for digital variants. Digital displays now capture the fastest expansion as retailers replace fluorescent-backlit posters with network-managed screens enabling real-time content swaps. Banners and floor graphics remain mature segments where margin pools concentrate in specialized substrate coatings and adhesive formulations rather than commodity printing. Fabric materials are gaining share in temporary installations where lightweight transport and tool-free mounting reduce labor costs for seasonal marketing campaigns.
The Federal Communications Commission regulates electromagnetic emissions from networked digital signage, while the EPA administers hazardous substance restrictions affecting printed substrate disposal and recycling pathways. The EU RoHS directive and REACH framework constrain heavy metal content in electronic displays and chemical composition of adhesive-backed vinyl, compelling material reformulation across export-oriented supply chains. Stakeholders must monitor evolving extended producer responsibility mandates and determine whether regional compliance investments justify dedicated product lines or unified global platform strategies.
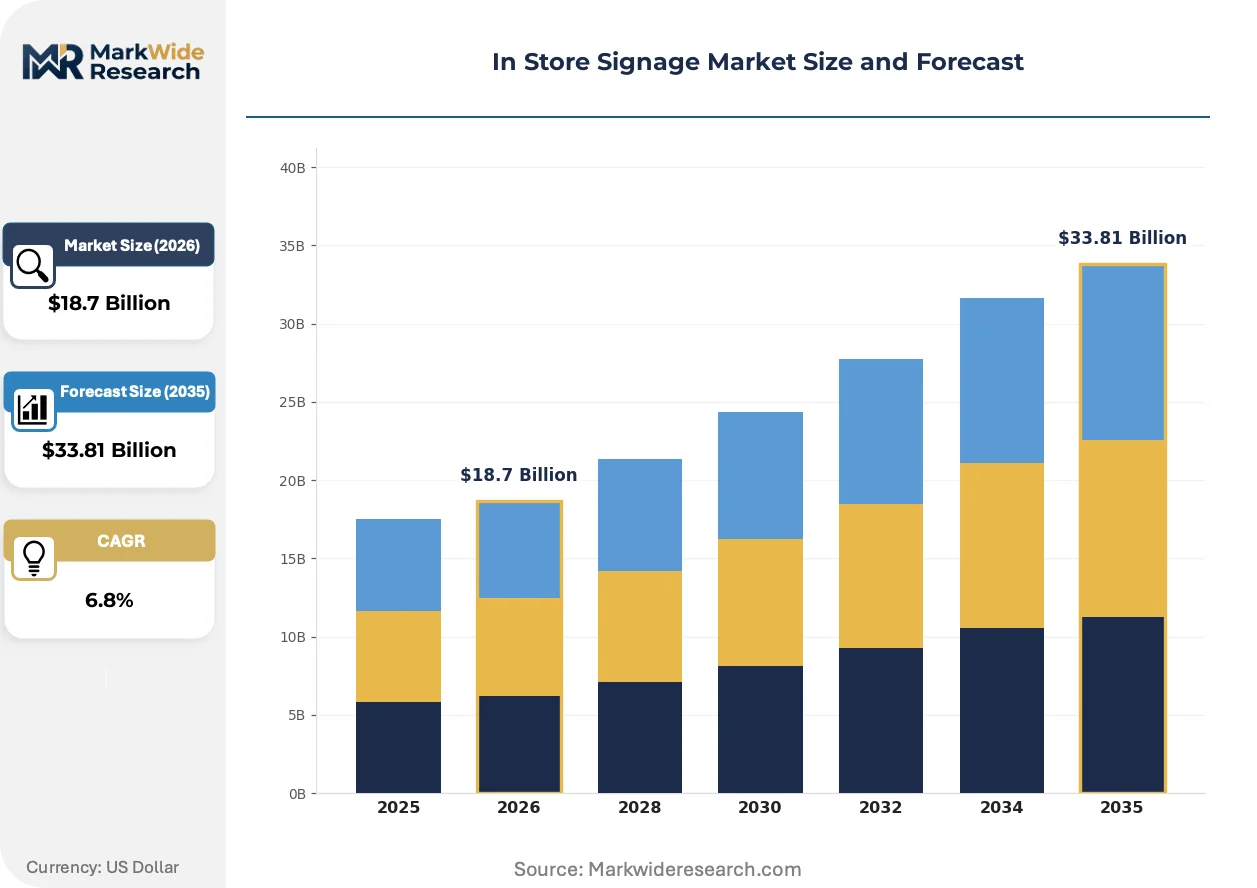
Market Dynamics
Retail digitalization is compressing refresh cycles for static signage while accelerating procurement of network-managed LED displays that bridge physical stores with e-commerce fulfillment workflows.
Growth Catalysts
- EU RoHS and REACH compliance deadlines:European retailers are replacing legacy fluorescent-backlit fixtures with LED-based digital systems to meet hazardous substance restrictions and extended producer responsibility mandates.
- Smart store pilots in China:Domestic retail chains are deploying sensor-integrated signage networks that synchronize shelf-edge displays with inventory management and mobile payment systems.
- LED efficiency standards:United States Department of Energy regulations on display luminance and power consumption are forcing hardware upgrades across big-box retail estates.
Market Restraints
- Indium and gallium supply concentration:Thin-film transistor substrates for OLED signage depend on rare earth processing concentrated in Chinese smelting operations, creating input cost volatility.
- Technical limitation of outdoor readability:Direct-view LED modules below 2.5mm pixel pitch suffer luminance degradation and thermal management failures in high-ambient-light environments without active cooling.
- FCC electromagnetic emissions testing:Networked digital signage deployments face certification delays and retesting costs when firmware updates alter radio frequency signatures.
Strategic Opportunities
- Pharmacy and healthcare retail convergence:Drugstore chains are installing prescription pickup queue management displays that combine static wayfinding with dynamic wait-time updates.
- India PLI scheme for electronics manufacturing:Domestic assembly incentives are attracting display module investments that could serve Southeast Asian retail expansion.
- Convergence of e-paper and solar harvesting:Battery-free shelf-edge labels with ambient light charging are eliminating wiring infrastructure in grocery retrofit programs.
Industry Challenges
- Embedded systems firmware integration:Retail IT departments lack personnel trained to synchronize content management platforms with legacy point-of-sale and inventory databases.
- Content localization at scale:National retailers struggle to maintain brand consistency while enabling real-time price and promotion updates across thousands of franchise-operated locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Store Signage Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Banners, Digital Displays, Floor Graphics, Hanging Signage Material: Plastic, Vinyl, Fabric, Paper Application: Product Promotion, Directional Signage, Brand Awareness, Seasonal Marketing Installation: Permanent, Temporary, Adhesive, Freestanding |
| Companies Covered | Samsung Electronics, LG Electronics, Daktronics, NEC Display Solutions, Panasonic Corporation, Sharp Corporation, STRATACACHE, Scala, BrightSign, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Store Signage Market Shifts & Advancements
Display hardware is fragmenting into specialized form factors while software platforms consolidate, creating divergent investment priorities across the value chain.
Mini-LED backlighting is absorbing the premium segment of retail display procurement that previously specified OLED for high-contrast applications. Luxury department stores and flagship automotive showrooms are adopting mini-LED for window-facing installations where burn-in risk and peak brightness requirements disqualify organic emitters. The technology is absorbing margin pools that concentrated in Korean panel fabrication, redistributing value toward Chinese LED chip packagers and diffusion film suppliers.
California's Title 24 building efficiency standards now mandate automated daylight dimming for all new retail construction exceeding specific square footage thresholds. The regulation forces specification of ambient light sensors and networked control systems even for static signage retrofits. Big-box retailers in the state are responding by consolidating vendor relationships with full-service integrators capable of delivering hardware, commissioning, and compliance documentation as single-source contracts.
Category managers at grocery and mass merchandise chains are unbundling content production from hardware procurement, treating creative services as separate spend pools with distinct vendor qualification criteria. This separation disrupts the traditional bundled model where display manufacturers provided turnkey solutions including template libraries and managed network operations. The shift is most visible in North American and Western European markets where retail marketing organizations have built internal digital asset management capabilities.
In Store Signage Market Segmentation
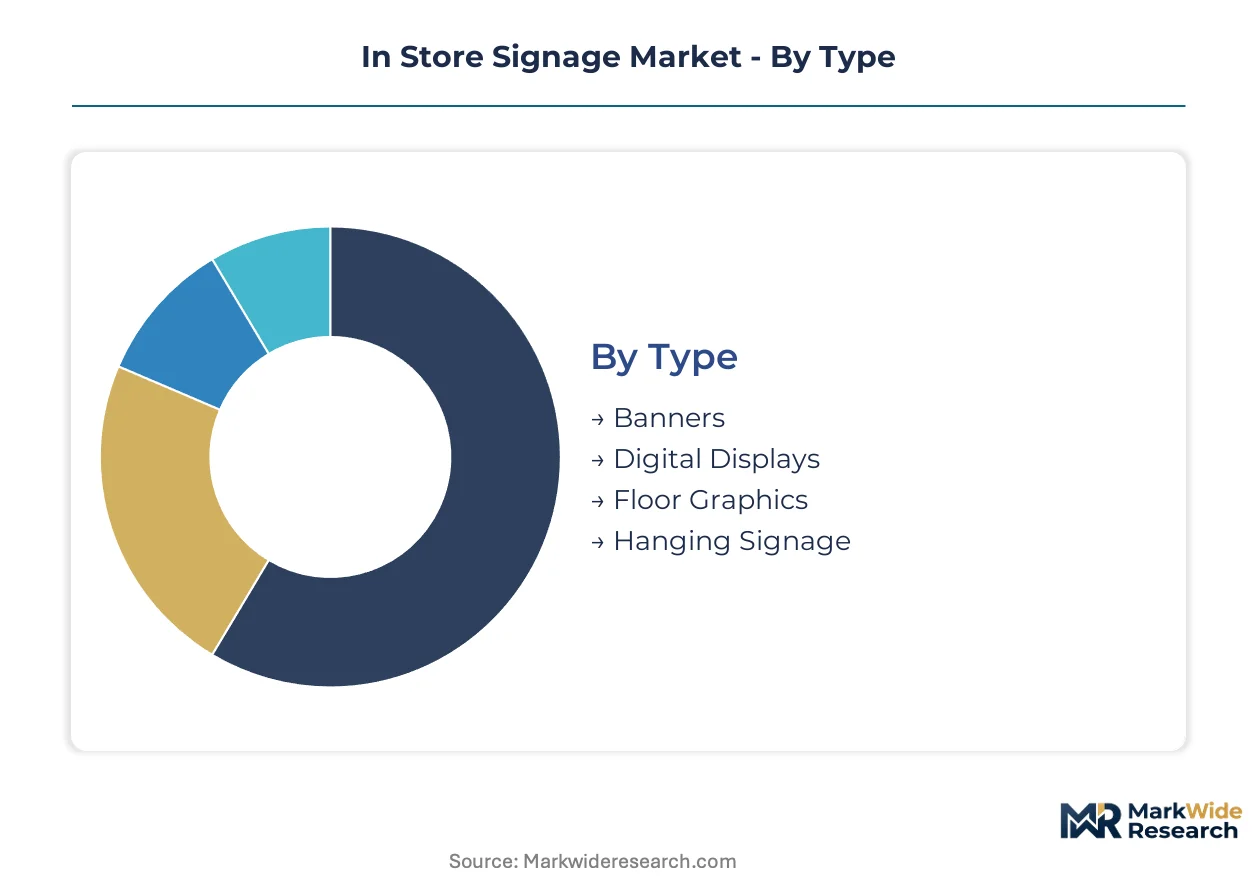
Segmentation in the in-store signage market reveals divergent capital requirements and margin structures across hardware, substrate, and service layers. Procurement patterns vary sharply between retailers refreshing legacy static estates and those building network-managed digital infrastructure.
Type:
Capital intensity peaks in segments requiring semiconductor content and network integration, while substrate-based formats demand lower upfront outlay but compress margins through commoditization.
- Digital Displays:Direct-view LED and LCD panels with luminance ratings exceeding 1,000 nits, incorporating system-on-chip processors and wireless connectivity modules. Demand concentrates in Chinese supermarket chains deploying sensor-integrated networks that synchronize shelf-edge content with inventory systems and mobile payment workflows.
- Banners:Flexible vinyl or fabric substrates suspended from ceiling infrastructure or mounted on wall systems, typically produced through wide-format solvent or UV-curable printing. European mass merchandise retailers are replacing fluorescent-backlit poster fixtures with LED-based alternatives to satisfy EU RoHS hazardous substance restrictions.
- Floor Graphics:Slip-resistant adhesive-backed vinyl applied to high-traffic retail surfaces, with specialized coatings enabling scuff resistance and solvent cleaning.
- Hanging Signage:Suspended dimensional or flat substrates deployed for wayfinding and promotional messaging in big-box environments with elevated ceiling clearance.
Most installed capacity flows through Banners. Expansion is steepest in Digital Displays.
Material:
Material selection governs durability specifications, transport logistics, and compliance with evolving chemical safety mandates across export markets.
- Vinyl:Polyvinyl chloride substrates with adhesive backing and protective overlaminates, dominating temporary promotional installations. REACH framework constraints on phthalate plasticizers and heavy metal stabilizers are compelling reformulation investments across EU-bound supply chains.
- Fabric:Polyester or nylon textiles with dye-sublimation printing, enabling lightweight transport and tool-free mounting for seasonal campaign rotations. Grocery and apparel retailers in North American markets are expanding fabric procurement to reduce installation labor costs in frequent refresh programs.
- Plastic:Rigid polystyrene, acrylic, or polycarbonate sheets for dimensional lettering and structural sign faces.
- Paper:Coated or synthetic stocks for short-duration promotional inserts and shelf talkers in high-velocity retail categories.
Volume leadership sits with Vinyl. Fabric is gaining share fastest.
Application:
Application segmentation aligns with retail organizational structures, separating marketing-led promotional spend from operations-directed wayfinding investment.
- Product Promotion:Price messaging, feature callouts, and limited-time offer creative deployed at shelf edge or aisle entry. Drugstore chains in the United States are converging prescription pickup queue management with promotional content, combining static wayfinding substrates with dynamic wait-time updates on adjacent screens.
- Directional Signage:Wayfinding systems guiding shopper flow through store layouts, including departmental identifiers and service location markers. Big-box retailers in California are consolidating vendor relationships under Title 24 building efficiency mandates requiring automated daylight dimming and networked control documentation.
- Brand Awareness:Logo-forward creative reinforcing identity in entry zones and high-visibility architectural features.
- Seasonal Marketing:Temporary installations aligned with calendar-driven merchandising events and holiday promotional windows.
Product Promotion commands the largest installed base. Directional Signage is expanding most quickly.
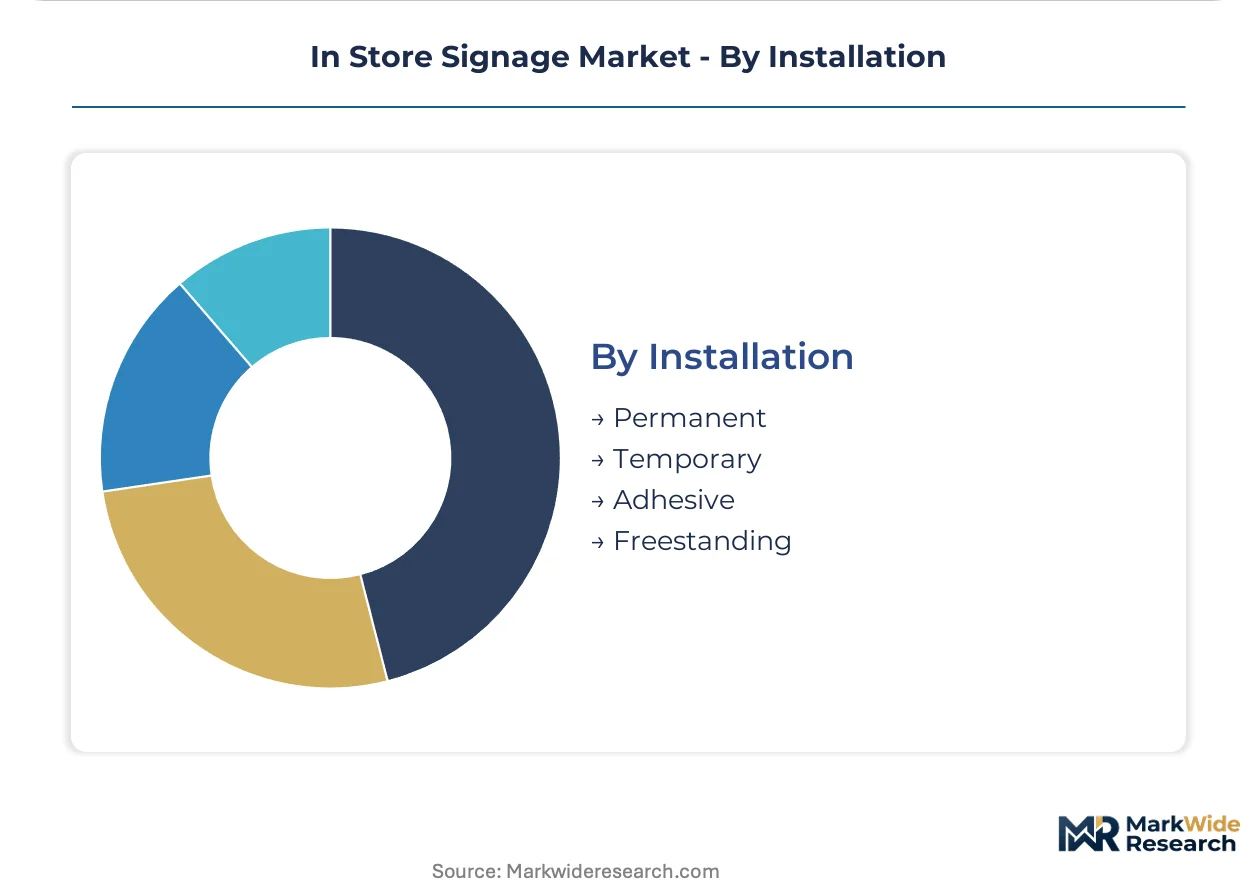
Installation:
Installation method determines total cost of ownership calculations and retrofit feasibility in existing retail estates with varying structural conditions.
- Permanent:Hardwired electrical connections, structural anchoring, and integrated architectural finishes requiring professional trade labor. Luxury automotive showrooms and flagship department stores are specifying permanent mini-LED installations for window-facing applications where burn-in risk and peak brightness requirements disqualify organic emitter technologies.
- Temporary:Tool-free mounting systems enabling rapid deployment and removal without surface damage or electrical infrastructure. Grocery chains are expanding temporary installations to support accelerated promotional cadences without capitalizing fixed assets.
- Adhesive:Pressure-sensitive backing for direct substrate-to-surface attachment on walls, floors, and fixtures.
- Freestanding:Self-supporting structures including A-frames, stanchions, and modular display systems requiring no building modification.
Permanent installations represent the largest cumulative investment. Temporary is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's retail real estate development clusters dominate procurement volumes for both static and digital signage formats. Supermarket chains across Guangdong and Jiangsu provinces are expanding sensor-integrated display networks that synchronize shelf-edge content with inventory management systems.
China
Domestic retail chains in Shanghai and Shenzhen are deploying smart store pilots with network-managed LED displays bridging physical stores with mobile payment workflows. MIIT regulations on display energy efficiency are accelerating hardware refresh cycles across state-owned supermarket networks. The Yangtze River Delta manufacturing corridor supplies captive semiconductor capacity for high-resolution retail screens.
United States
Big-box retailers are replacing fluorescent-backlit poster fixtures with LED-based systems under Department of Energy luminance regulations. California's Title 24 building efficiency standards mandate automated daylight dimming for new retail construction exceeding specific square footage thresholds. Retail estates in Texas and Florida are consolidating vendor relationships with full-service integrators delivering compliance documentation as single-source contracts.
Germany
Mass merchandise retailers are retrofitting legacy static estates to satisfy EU RoHS hazardous substance restrictions and REACH framework constraints on heavy metal content. Extended producer responsibility mandates under the EU Green Deal are compelling material reformulation across export-oriented supply chains. Industrial signage fabrication concentrates in North Rhine-Westphalia and Bavaria.
India
Domestic assembly incentives under the PLI scheme for electronics manufacturing are attracting display module investments serving Southeast Asian retail expansion. Drugstore chains in Maharashtra and Karnataka are installing prescription pickup queue management displays combining static wayfinding with dynamic wait-time updates. The Delhi-NCR corridor hosts emerging integrators consolidating hardware procurement with content management platforms.
Japan
Luxury department stores in Tokyo and Osaka are adopting mini-LED backlighting for window-facing installations where burn-in risk disqualifies organic emitter technologies. METI efficiency standards on commercial display power consumption are forcing upgrades across flagship automotive showrooms. The Kanto region anchors specialized manufacturing scale in LED video architecture.
In Store Signage Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated smart store deployments and battery-free shelf-edge applications. The vendor base separates into three archetypes: vertically integrated panel suppliers with captive semiconductor capacity, specialized manufacturers of LED video architecture for big-box environments, and premium-tier providers of advanced display lines commanding positioning in luxury retail channels. Competitive moves concentrate on backward integration into chip fabrication and consolidation of vendor relationships under single-source compliance contracts.
Among Korean-based electronics conglomerates, Samsung Electronics and LG Electronics represent the vertically integrated archetype with in-house fabrication capabilities. Daktronics, a U.S.-based specialist, exemplifies the scale-driven manufacturer focused on LED video systems. These three occupy positions across the premium and standard tiers, with Samsung anchoring supply continuity for high-resolution retail screens, LG differentiating through advanced display technologies, and Daktronics securing competitive position through specialized manufacturing scale.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Daktronics |
| NEC Display Solutions |
| Panasonic Corporation |
| Sharp Corporation |
| STRATACACHE |
| Scala |
| BrightSign |
| Others |
Supply & Pricing Matrix
Big-box retail procurement concentration in North American and European chains anchors project-based pricing with volume-scaled discounts for network-managed LED deployments. Cost compression in commodity vinyl substrates feeds supplier consolidation as margin pools migrate toward semiconductor-intensive digital formats.
Pricing Analysis
Input-cost pass-through from indium and gallium volatility shapes OLED signage pricing, with Chinese smelting concentration amplifying quarterly adjustments. Three-tier pricing structure across premium, standard, and economy levels separates mini-LED flagship installations from fluorescent-backlit retrofits and temporary fabric campaigns. Pricing pressure stems from EU RoHS compliance deadlines accelerating hardware refresh cycles. Grocery chains exhibit highest price sensitivity due to thin promotional margins, while luxury automotive showrooms absorb premium positioning for burn-in-resistant window-facing installations.
Supply Chain Analysis
Single-source vulnerability sits with Chinese gallium processing and Taiwanese thin-film transistor substrate fabrication for high-resolution retail screens. LED chip packagers in the Yangtze River Delta and diffusion film suppliers in South Korea anchor upstream capacity. Raw material dependencies include rare earth elements, polysilicon for semiconductor wafers, and specialized optical films. Tariff exposure on display module imports into the United States threatens cost structures. Distribution runs through full-service integrators consolidating hardware procurement with compliance documentation under single-source contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as retailer procurement shifts toward premium mini-LED specifications displacing legacy OLED in flagship installations.
For Market Incumbents: Deploy backward integration into captive semiconductor capacity to secure supply continuity against Chinese rare earth processing concentration. Consolidate vendor relationships under compliance-documentation bundling to capture California Title 24 retrofit demand. Defend margin position by specializing manufacturing scale in LED video architecture for big-box environments rather than competing on commodity vinyl substrates. For New Entrants and Emerging Players: Battery-free e-paper shelf-edge labels with solar harvesting offer the most penetrable wedge for grocery retrofit programs lacking electrical infrastructure. Target pharmacy queue management convergence combining static wayfinding with dynamic wait-time displays. Pursue white-label content management platform licensing to retailers unbundling creative services from hardware procurement. For Investors and Strategic Acquirers: Display module manufacturers serving Southeast Asian retail expansion are the most active acquirer targets in this space. Long-term viability hinges on software platform consolidation outpacing hardware fragmentation. Watch for MIIT energy efficiency mandate acceleration in Chinese state-owned supermarket networks as inflection indicator for procurement volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Fabrication | Samsung Electronics secures supply continuity for high-resolution retail screens against rare earth volatility. |
| Compliance Documentation Bundling | Full-service integrators capture California Title 24 retrofit demand with single-source contracting. |
| Sensor-Integrated Smart Store Deployment | Domestic chains in Guangdong synchronize shelf-edge displays with inventory and mobile payment systems. |
| E-Paper Solar Harvesting Convergence | Battery-free shelf-edge labels eliminate wiring infrastructure in grocery retrofit programs. |
| Content Management Platform Unbundling | North American retailers separate creative services spend pools with distinct vendor qualification criteria. |
Research Methodology
Direct dialogue with retail procurement directors, signage integrators, display module manufacturers, and regulatory compliance officers grounds qualitative findings. Secondary validation draws from MIIT efficiency filings, EPA hazardous substance registrations, EU ECHA REACH substance databases, and customs trade records for display module flows. Bottom-up and top-down triangulation cross-checks manufacturer shipment data against retailer capex disclosures.
Bottom-up modeling aggregates unit economics across digital display, banner, floor graphic, and hanging signage formats. Segmentation dimensions include hardware type, substrate material, application purpose, and installation method. CAGRs derive from hardware refresh cycle compression rates and smart store pilot expansion trajectories. Forecast inputs incorporate LED efficiency standard adoption curves and extended producer responsibility mandate implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply disruptions, tariff regime shifts, and firmware certification delays under FCC electromagnetic emissions protocols. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Retail Display Racks Market
Retailing
Vietnam Retail Market
Retailing
Thailand Retail Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
Furniture Rental Service Market
Retailing
Qatar Retail Market
Retailing
Out Store Signage Market
Retailing
Out-Door Signage Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
European Discount Retail Market
Retailing
United States Hardware Stores Retail Market
Retailing
Floor Displays Market
Retailing
Subscription Box Market
Retailing
China Retail Market
Retailing
Electronics Retailing Market
Retailing
Philippines Retail Industry Market