
 Thailand Retail Market | 2026-2036
Thailand Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Retail Market Insights
The widening gap between luxury mall experiences and discount-driven convenience formats is realigning how Thai retailers allocate capital and floor space. CP Axtra Public Co Ltd leverages its wholesale-club infrastructure to dominate bulk purchasing across provincial cities. Central Group anchors premium positioning through mixed-use developments that integrate retail with hospitality and residential towers. The Mall Group competes on experiential density, packing entertainment and dining into suburban super-regional formats.
Thailand retail encompasses the sale of consumer goods through physical and digital channels, spanning transactions from fresh produce to electronics, with inventory turnover cycles typically measured in days for perishables and weeks for durables. The sector functions as Thailand's largest private employer and a critical tax collection point for the Ministry of Finance. Grocery sales through supermarkets and convenience stores command the highest transaction frequency and supply chain investment intensity. Electronics and home goods sold via online channels represent the fastest-expanding margin pool as logistics networks penetrate second-tier provinces. Clothing distributed through department stores faces structural pressure from direct-to-consumer platforms and cross-border e-commerce fulfillment.
Thailand's Ministry of Commerce enforces the Trade Competition Act to prevent monopolistic consolidation among retail conglomerates, while the Revenue Department scrutinizes e-commerce VAT collection from digital marketplace operators. The country's national pharmaceutical regulator and consumer protection frameworks mandate product labeling standards that directly affect imported merchandise assortments. Stakeholders must track how BOI-promoted warehouse automation investments alter labor economics and whether provincial zoning boards accelerate or constrain hypermarket expansion outside Bangkok's orbit.
Market Dynamics
The Trade Competition Act enforced by Thailand's Ministry of Commerce is actively constraining horizontal consolidation among retail conglomerates, forcing capital deployment toward vertical efficiency gains rather than market share capture through acquisition.
Growth Catalysts
- BOI Digital Infrastructure Incentives:Tax privileges for warehouse automation and e-commerce platform investments are accelerating fulfillment network expansion into second-tier provinces.
- Urban Middle-Class Household Formation:Organized grocery formats capture rising disposable income as Bangkok metropolitan families prioritize time-saving over price-driven wet market visits.
- Cross-Border E-Commerce Logistics Maturation:Direct-to-consumer fulfillment infrastructure is modularizing import pathways for electronics and home goods, compressing traditional distributor margins.
Market Restraints
- Revenue Department VAT Scrutiny:Enhanced collection mandates on digital marketplace operators impose compliance overhead that disadvantages small-scale cross-border sellers.
- Provincial Zoarding Board Delays:Hypermarket expansion outside Bangkok's orbit faces permitting friction that extends development timelines and inflates land acquisition costs.
- Labor Economics Disruption:BOI-promoted warehouse automation investments are displacing low-skill warehouse roles faster than retraining programs absorb displaced workers.
Strategic Opportunities
- Isaan Province Retail Underpenetration:Northeastern Thailand's secondary cities present whitespace for wholesale-club formats targeting bulk purchasing behavior among agricultural cooperatives.
- Mixed-Use Development Convergence:Integration of retail floorspace with residential towers and hospitality assets generates captive foot traffic and diversified revenue streams.
- Experiential Density Differentiation:Suburban super-regional formats combining entertainment, dining, and shopping are capturing weekend leisure expenditure from Bangkok's outer ring.
Industry Challenges
- Legacy POS Integration Complexity:Real-time inventory synchronization between physical stores and e-commerce platforms demands middleware investment that strains mid-tier retailer IT budgets.
- Perishable Supply Chain Reconfiguration:Cold chain infrastructure gaps between Bangkok distribution hubs and provincial endpoints generate spoilage losses that compress grocery margins.
- Product Labeling Compliance Burden:Consumer protection frameworks mandate Thai-language packaging standards that complicate direct import assortments and extend procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Retail Market |
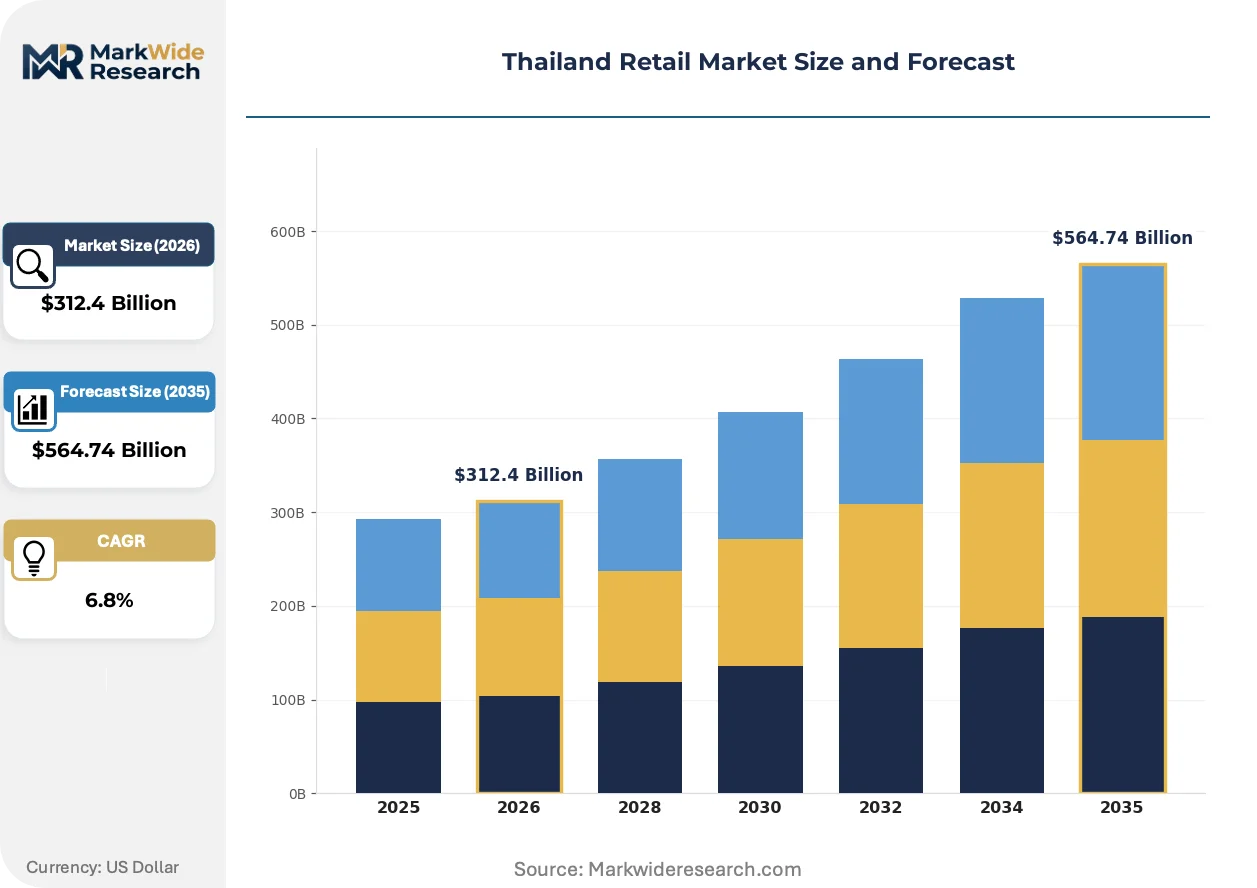
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Electronics, Groceries, Home Goods Customer Type: Families, Young Adults, Retirees, Professionals Distribution Channel: Online, Supermarkets, Convenience Stores, Department Stores Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | CP Axtra Public Co Ltd, Central Group, CP All, The Mall Group, AEON Co. Ltd., Berli Jucker Public Co. Ltd., AS Watson Group, Home Product Center Public Co, King Power Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Retail Market Trends and Innovations
Retail technology deployment in Thailand is pivoting from customer-facing applications toward back-end infrastructure that compresses fulfillment costs and enables same-day delivery promises outside the capital.
Robotic warehouse automation is modularizing fulfillment center design, allowing CP Axtra and Central Group to scale automated picking systems incrementally across provincial distribution nodes. Mid-market grocery operators are adopting these systems at 40-60 percent scale compared to Bangkok flagship facilities. The technology is modularizing capital deployment, enabling staged automation rollouts that match regional demand density rather than requiring full-build commitments upfront.
Thailand's Trade Competition Act amendments are tightening merger review thresholds for retail conglomerates, forcing organic growth strategies over acquisition-led expansion. The Ministry of Commerce now scrutinizes wholesale-club format dominance in specific provincial catchments as potential monopolistic conduct. Large-format grocery operators are responding by diversifying into convenience store networks and online marketplaces that fall below concentration triggers.
Consumer fulfillment expectations are compressing delivery windows from next-day to same-day across Bangkok's outer metropolitan ring, with provincial cities following at 18-24 month lag. Traditional department store channels are losing apparel and electronics volume to direct-to-consumer platforms that bypass distributor markups. This behavioral shift is most visible in Chonburi and Pathum Thani provinces, where cross-border e-commerce penetration rates approach half of Bangkok levels despite inferior logistics infrastructure.
Thailand Retail Market Segmentation
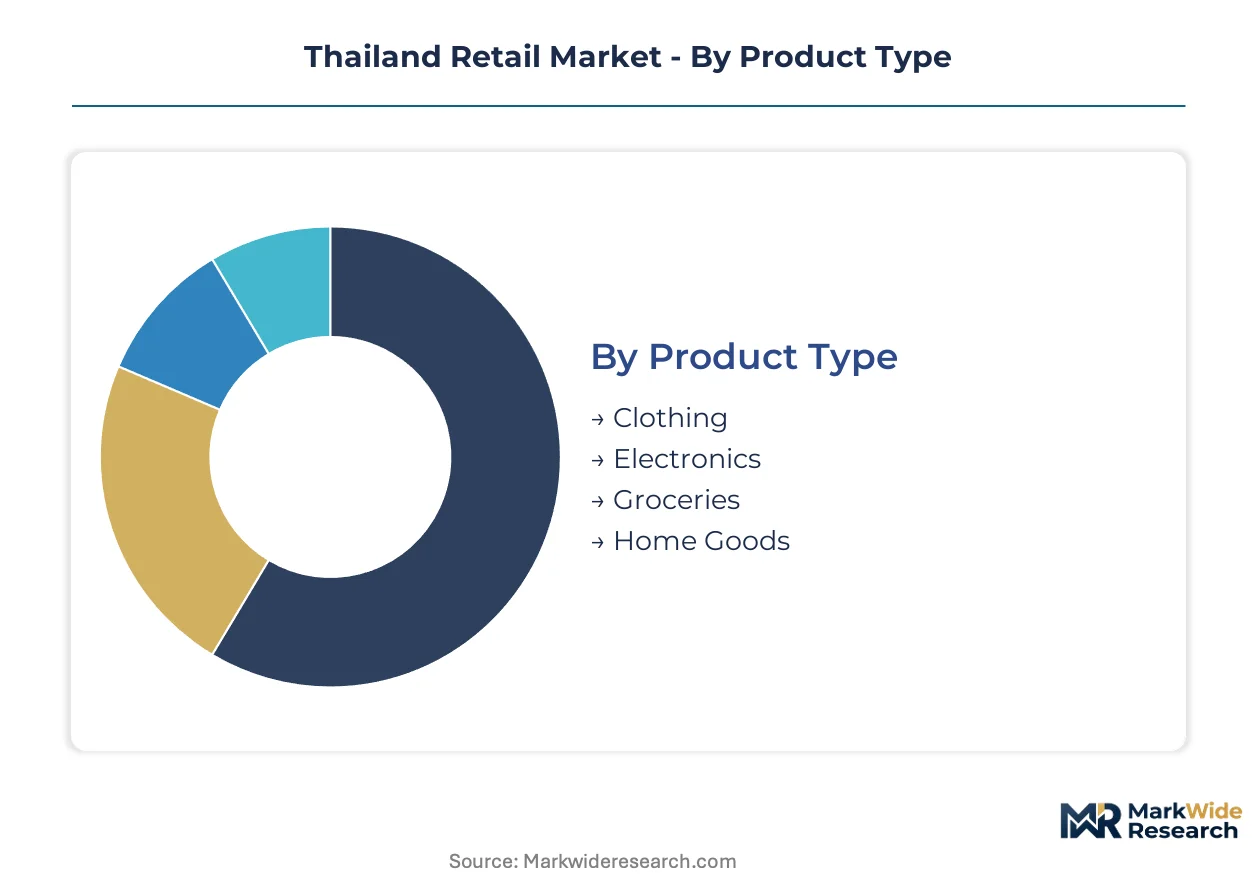
Segmentation in Thailand's retail landscape reveals how purchasing behavior fragments across income tiers, life stages, and channel preferences. Understanding these divides helps operators allocate capital between Bangkok's premium corridors and provincial expansion zones.
Product Type:
Product specifications and inventory velocity determine supply chain architecture and margin structure across Thailand's retail categories.
- Groceries:Perishable SKUs demand cold-chain infrastructure from Bangkok distribution hubs to provincial endpoints. Fresh produce and packaged foods generate the highest transaction frequency among Bangkok metropolitan households prioritizing time-saving over wet market visits.
- Electronics:Smartphone, laptop, and home appliance specifications require authorized service networks and warranty fulfillment capabilities. Demand concentrates in Chonburi and Pathum Thani provinces where cross-border e-commerce penetration approaches capital-region levels despite inferior logistics infrastructure.
- Clothing:Apparel assortments face structural pressure from direct-to-consumer platforms and cross-border fulfillment.
- Home Goods:Furniture and décor specifications favor showroom-based purchasing with delivery coordination.
Groceries leads on scale; electronics leads on momentum.
Customer Type:
Life-stage economics and household formation patterns drive format selection and price-tier targeting across Thailand's retail ecosystem.
- Families:Multi-generational households with children under 18 drive bulk purchasing behavior and wholesale-club membership concentration. This segment dominates CP Axtra's provincial expansion strategy targeting agricultural cooperatives in secondary cities.
- Young Adults:Digital-native consumers aged 18-34 prioritize mobile-first purchasing and same-day delivery expectations. Smartphone penetration and social commerce integration accelerate online channel adoption among this cohort in Bangkok's outer metropolitan ring.
- Professionals:Time-constrained dual-income households favor convenience store networks and organized grocery formats.
- Retirees:Fixed-income seniors exhibit price elasticity and traditional channel loyalty.
Families anchor volume concentration; young adults drive channel migration fastest.
Distribution Channel:
Channel economics and fulfillment infrastructure maturity determine capital deployment priorities between physical and digital retail networks.
- Online:Marketplace platforms and direct-to-consumer sites compress delivery windows from next-day to same-day across Bangkok's outer ring. Electronics and home goods sold via digital channels expand margins as logistics networks penetrate second-tier provinces.
- Supermarkets:Organized grocery formats capture rising disposable income through private-label expansion and fresh produce standardization. Central Group and CP Axtra compete on perishable supply chain density.
- Convenience Stores:High-frequency, small-basket formats dominate urban corridors and transit-adjacent locations.
- Department Stores:Legacy apparel and electronics channels face structural pressure from cross-border e-commerce fulfillment.
Supermarkets retain the largest transaction volume; online channels gain share fastest.
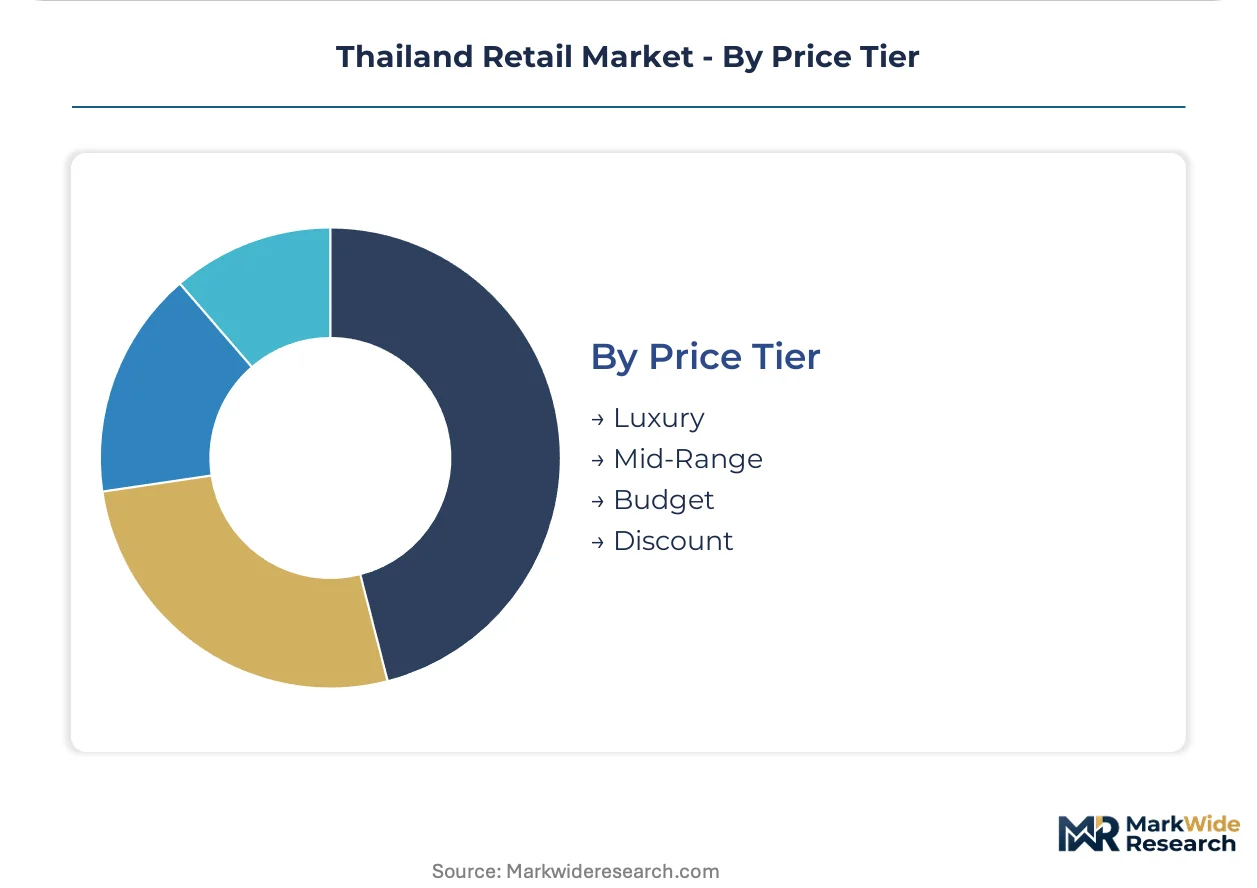
Price Tier:
Purchasing power distribution and brand positioning strategies stratify Thailand's retail market across four distinct economic bands.
- Mid-Range:Mass-market positioning targets Bangkok's urban middle-class with standardized quality and predictable pricing. This tier captures the widest household penetration across metropolitan and provincial markets.
- Discount:Price-driven formats emphasize volume turnover and limited SKU breadth. Bulk purchasing behavior among agricultural cooperatives in Isaan province sustains wholesale-club expansion outside Bangkok's orbit.
- Luxury:Premium positioning integrates retail with hospitality and residential towers in mixed-use developments.
- Budget:Entry-price formats serve fixed-income retirees and rural households with high price elasticity.
Mid-range commands the broadest household reach; discount formats expand most quickly into provincial whitespace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's retail density exceeds Vietnam's by a factor of three in modern grocery square footage per capita, yet both markets face similar last-mile infrastructure gaps outside capital regions. Provincial expansion economics differ sharply between these Southeast Asian neighbors.
Bangkok Metropolitan Region
Urban middle-class households drive organized grocery demand through Central Group's mixed-use towers and CP Axtra's wholesale-club networks. The Ministry of Commerce enforces Trade Competition Act merger thresholds that limit horizontal consolidation. Rama IX and Ratchada corridors concentrate luxury retail development anchored by hospitality-integrated complexes.
Chonburi Province
Cross-border e-commerce penetration approaches Bangkok levels for electronics and home goods despite inferior logistics infrastructure. The Board of Investment extends tax privileges for warehouse automation investments into this Eastern Economic Corridor hub. Laem Chabang port proximity attracts fulfillment center development serving direct-to-consumer import channels.
Pathum Thani Province
Young adult consumers aged 18-34 accelerate mobile-first purchasing and same-day delivery expectations across Bangkok's outer ring. Provincial zoning boards impose permitting friction that extends hypermarket development timelines. Rangsit and Thanyaburi districts concentrate suburban super-regional formats competing on experiential density.
Isaan Region
Agricultural cooperatives sustain bulk purchasing behavior that supports wholesale-club format expansion into secondary cities. Cold chain infrastructure gaps between Bangkok distribution hubs and provincial endpoints generate spoilage losses. Khon Kaen and Udon Thani present whitespace for organized grocery penetration targeting price-elastic rural households.
Chiang Mai Province
Fixed-income retirees and tourism-dependent service workers exhibit traditional channel loyalty and high price elasticity. The Revenue Department's enhanced VAT collection mandates on digital marketplace operators disadvantage small-scale cross-border sellers. Nimmanhaemin and airport corridors concentrate mid-range retail development serving domestic tourists and digital nomad residents.
Thailand Retail Market Competitive Landscape
Top-tier vendors anchor Bangkok's premium corridor development, while provincial specialists exploit whitespace in secondary cities through format adaptation. The market exhibits tiered concentration with three conglomerates controlling organized grocery and mixed-use retail infrastructure. Strategic archetypes include wholesale-club operators leveraging agricultural cooperative relationships, premium mixed-use developers integrating hospitality assets, and experiential density specialists packing entertainment into suburban formats. Competitive moves center on vertical efficiency investments in warehouse automation and organic format diversification to evade merger review thresholds.
Within the conglomerate tier, CP Axtra Public Co Ltd and Central Group occupy positions representing divergent capital deployment strategies, while The Mall Group exemplifies experiential density specialization. CP Axtra leverages wholesale-club infrastructure across provincial cities. Central Group anchors premium positioning through hospitality-integrated developments. The Mall Group competes on suburban super-regional formats combining entertainment and dining.
| Leading Market Players |
|---|
| CP Axtra Public Co Ltd |
| Central Group |
| CP All |
| The Mall Group |
| AEON Co. Ltd. |
| Berli Jucker Public Co. Ltd. |
| AS Watson Group |
| Home Product Center Public Co |
| King Power Group |
| Others |
Pricing and Supply Chain Analysis
Family-owned retail conglomerates anchored by agricultural-to-consumer conglomerate structures dominate Thailand's retail infrastructure, channeling procurement discipline through captive supply networks while enforcing price stability across Bangkok's premium corridors and provincial wholesale-club expansion zones.
Pricing Analysis
The bundled-vs-unbundled service split separates membership-based wholesale-club formats from transactional convenience retail, with three-tier pricing structure across premium, standard, and economy levels capturing divergent household income bands. Price differentiation rests on format convenience and geographic delivery cost, with Bangkok metropolitan households absorbing premium positioning while Isaan agricultural cooperatives drive volume through bulk discount tiers. Pricing pressure stems from cross-border e-commerce fulfillment compressing traditional distributor margins in electronics and home goods. Fixed-income retirees exhibit highest price sensitivity, while dual-income professional households demonstrate lowest elasticity for time-saving formats.
Supply Chain Analysis
Single-source vulnerability sits with China-based electronics component suppliers and Vietnamese apparel manufacturing clusters that feed Thailand's direct-to-consumer import channels. Raw material dependencies span cold-chain equipment for perishables, automated warehouse robotics, and cross-border logistics middleware. Tariff exposure through ASEAN trade framework adjustments presents structural risk to electronics import pathways. Distribution feeds from Bangkok metropolitan distribution hubs through provincial cold-chain nodes to wholesale-club endpoints in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's retail sector functions as a regulatory compounder, with Trade Competition Act amendments tightening merger review thresholds and forcing organic growth strategies that reshape capital deployment patterns across conglomerate portfolios.
For Market Incumbents: Hedge against cross-border e-commerce penetration by accelerating warehouse automation investments eligible for Board of Investment tax privileges, while diversifying format portfolios into convenience store networks that fall below concentration triggers. Central Group and CP Axtra must prioritize vertical integration into captive cold-chain infrastructure to defend margin position against perishable spoilage losses in provincial expansion zones. For New Entrants and Emerging Players: Enter via Isaan Province's wholesale-club whitespace targeting agricultural cooperative bulk purchasing behavior, or through experiential density formats in Pathum Thani's suburban corridors where young adult consumers demand entertainment-integrated retail. Direct-to-consumer fulfillment infrastructure for electronics and home goods offers the most penetrable go-to-market angle, leveraging modular cross-border logistics maturation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier grocery operators lacking warehouse automation scale or mixed-use development integration capability. Long-term viability over a five-to-ten year window favors targets with Board of Investment-promoted digital infrastructure credentials and established provincial zoning relationships. Monitor Revenue Department VAT enforcement intensity on digital marketplace operators as the critical inflection signal for cross-border e-commerce competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Automation Scale-Up | BOI tax privileges accelerate fulfillment network expansion into second-tier provinces beyond Bangkok's orbit. |
| Mixed-Use Development Integration | Central Group's hospitality-anchored towers generate captive foot traffic and diversified revenue streams. |
| Convenience Store Network Diversification | Format fragmentation evades Trade Competition Act merger review thresholds while capturing urban corridor density. |
| Cross-Border Logistics Partnership | Direct-to-consumer fulfillment infrastructure compresses traditional electronics distributor margins in Chonburi. |
| Experiential Density Format Launch | The Mall Group's suburban super-regional positioning captures weekend leisure expenditure from Bangkok's outer ring. |
Research Methodology
Bottom-up retail format modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with category buyers at Central Group and CP Axtra, provincial zoning board officials, warehouse automation vendors, and cross-border logistics operators with secondary validation through Thailand Ministry of Commerce trade statistics, Revenue Department VAT collection reports, and Board of Investment incentive disclosure filings.
Input-output matrix framing connects household formation patterns across Bangkok metropolitan and provincial income tiers to fulfillment infrastructure deployment trajectories, with segmentation dimensions spanning product type, customer life-stage, distribution channel maturity, and price-tier positioning across the projection horizon. CAGRs derive from demand density projections matched against supply-side capacity buildout schedules, incorporating cold-chain penetration rates and warehouse automation adoption curves as Thailand-specific forecast inputs.
Inputs from Ministry of Commerce enforcement actions and Board of Investment approval records were available through the study window; gaps in provincial zoning board deliberation timelines introduce uncertainty bands around hypermarket expansion forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
European Discount Retail Market
Retailing
Retail Display Racks Market
Retailing
China Retail Market
Retailing
Subscription Box Market
Retailing
Retail Vending Machine Market
Retailing
Floor Mat Rental Service Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
Singapore Gifting Market
Retailing
Department Stores Market
Retailing
Furniture Rental Service Market
Retailing
Out Store Signage Market
Retailing
Out-Door Signage Market
Retailing
Retail Signage Market
Retailing
North America Retail Vending Machine Market
Retailing
United States Hardware Stores Retail Market
Retailing
Consumer Shopping Cart Market