
 Consumer Products and Retail Market | 2026-2036
Consumer Products and Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Products and Retail Market Analysis
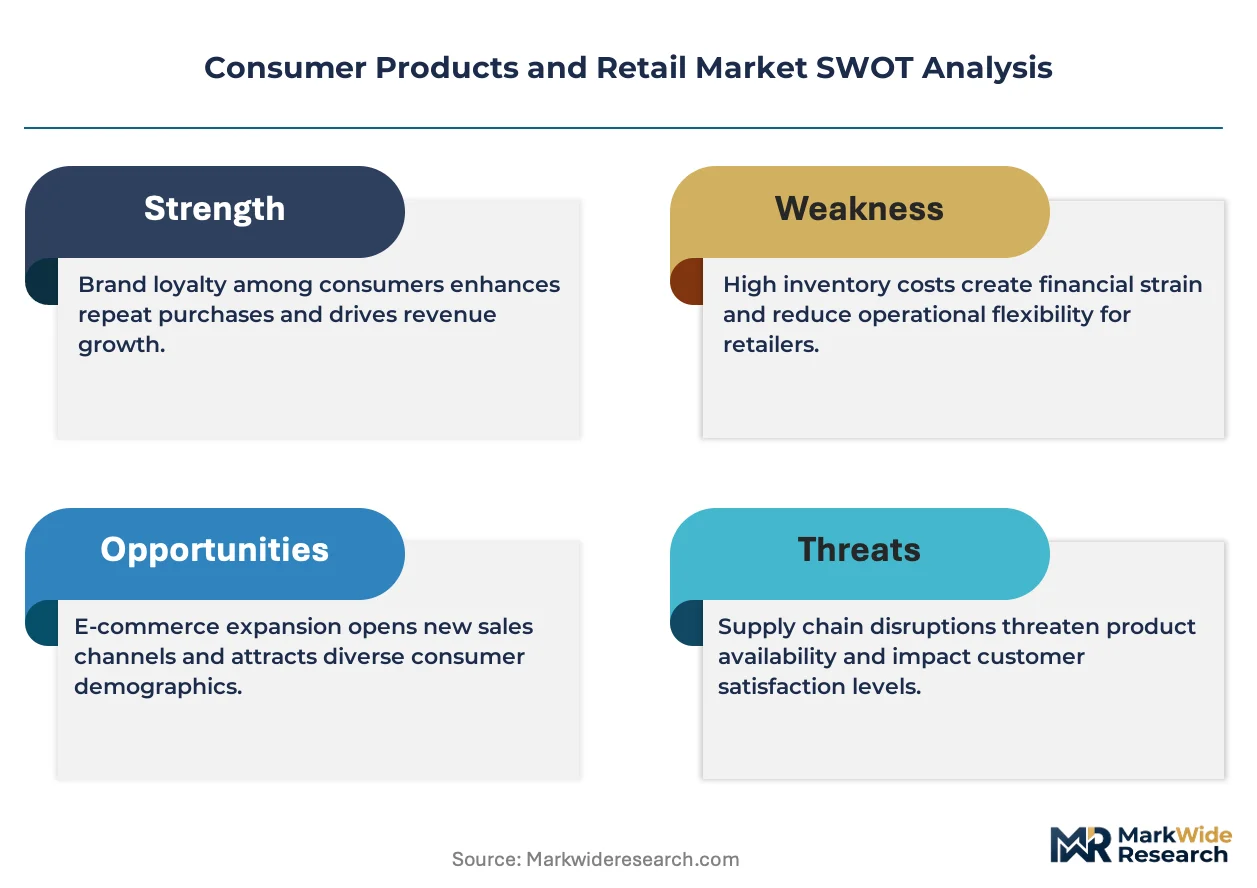
Buyer concentration among large-format retailers is consolidating as Walmart, Amazon, and Costco capture disproportionate household wallet share through integrated fulfillment networks. Walmart leverages its store-as-warehouse infrastructure to compress last-mile costs. Amazon sustains Prime-driven recurring revenue through predictive inventory positioning. Costco anchors member loyalty with curated SKU discipline and bulk-value positioning.
Consumer products and retail encompasses the design, sourcing, distribution, and sale of finished goods to end consumers through physical and digital channels, with inventory velocity measured by weeks-of-supply targets typically below twelve for perishables and seasonal categories. The sector's primary purpose is matching manufactured output to fragmented household demand while optimizing working capital turns. Electronics within product type segments commands premium margin pools due to replacement-cycle compression and warranty attach rates. Distribution channel dynamics favor online growth where algorithmic personalization and returns logistics now determine profitability, while brick-and-mortar retains defensive value in grocery and immediate-need categories.
FDA oversees product safety claims and labeling standards for personal care and food-contact items sold through retail channels, while FTC monitors pricing transparency and deceptive advertising practices that shape competitive conduct. State-level Extended Producer Responsibility laws in California and Oregon are forcing retailers to absorb end-of-life collection costs for electronics and packaging materials. Stakeholders must monitor how fragmented regulatory layering across federal and state jurisdictions reshapes compliance economics and private-label sourcing decisions.
Market Dynamics
Mass-market grocery chains are absorbing larger shares of household spending as consumers prioritize essentials over discretionary categories, forcing retailers to restructure fulfillment infrastructure and SKU rationalization strategies around omnichannel density.
Growth Catalysts
- EU Green Deal and CSRD:Mandatory supply chain reporting and product lifecycle transparency requirements are accelerating retailer investment in traceability infrastructure and supplier audit protocols.
- Omnichannel fulfillment networks:Store-as-warehouse models and predictive inventory positioning are compressing last-mile delivery economics for perishable and seasonal categories.
- Private-label expansion:Controlled sourcing and captive manufacturing are capturing margin pools previously allocated to national brands in food and personal care segments.
Market Restraints
- Input cost volatility in packaging materials:Resin and fiber price swings are compressing working capital turns for retailers with thin private-label margins.
- Supply concentration in Asian electronics manufacturing:Component sourcing dependency creates vulnerability to port congestion and tariff layering.
- Extended Producer Responsibility laws:California and Oregon mandates are forcing retailers to absorb end-of-life collection costs for electronics and packaging materials.
Strategic Opportunities
- Algorithmic personalization in online channels:Machine learning-driven recommendation engines and dynamic pricing are unlocking profitability in returns-intensive categories.
- Member loyalty programs:Curated SKU discipline and bulk-value positioning are anchoring recurring revenue streams in warehouse club formats.
- Biodegradable packaging innovation:Material science advances in compostable films are opening premium shelf-space allocation in European grocery chains.
Industry Challenges
- Fragmented regulatory layering:Federal FDA labeling standards diverging from state-level EPR mandates are complicating private-label sourcing decisions and compliance economics.
- Returns logistics complexity:Reverse supply chain reconfiguration for online apparel and electronics is straining warehouse automation capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Products and Retail Market |
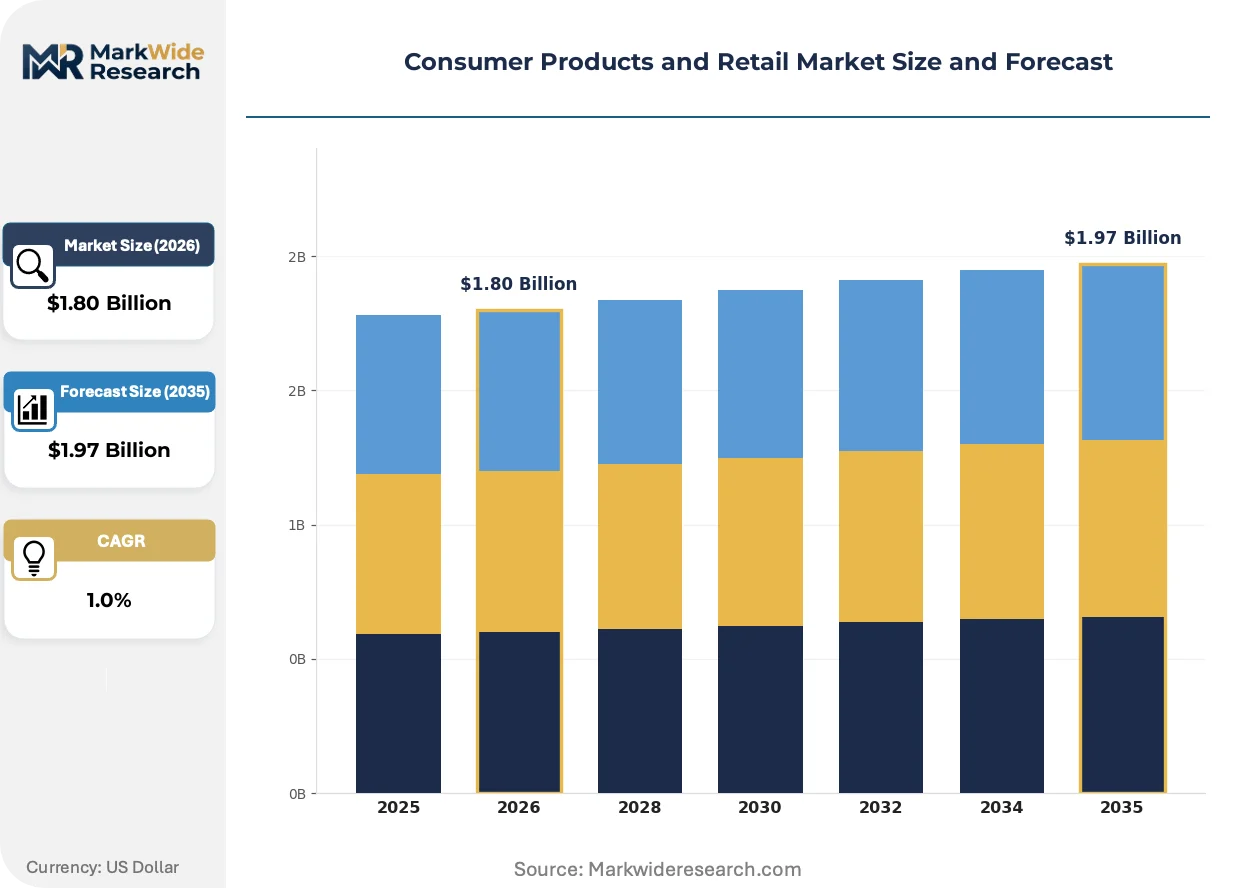
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Clothing, Home Goods, Personal Care Price Tier: Luxury, Mid-Range, Budget, Discount Distribution Channel: Online, Brick-and-Mortar, Direct Sales, Wholesale Customer Type: Families, Professionals, Students, Seniors |
| Companies Covered | Home Depot, CVS, Walmart, Target, Walgreens, Amazon, Kroger, Procter & Gamble, Costco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Products and Retail Market Emerging Trajectories
Predictive analytics and automation are restructuring how inventory velocity aligns with fragmented household demand, compressing the gap between manufacturing output and consumption timing across physical and digital channels.
Artificial intelligence-driven demand forecasting is consolidating procurement decisions for perishable categories. Grocery chains with twelve-week supply targets are adopting machine learning models that reduce spoilage rates. This consolidation is compressing buyer power toward retailers with proprietary data infrastructure.
REACH and RoHS substance restrictions are forcing reformulation of food-contact materials and electronics coatings sold through European retail channels. Manufacturers are accelerating substitution timelines for restricted phthalates and heavy metals. Personal care and small-appliance segments are absorbing the steepest compliance cost escalations.
Household purchasing is rotating toward immediate-need fulfillment in grocery and pharmacy categories. Convenience-oriented urban consumers are displacing planned stock-up trips with rapid delivery apps and curbside pickup. This behavioral shift is most visible in United States metropolitan markets where density supports sub-two-hour delivery economics.
Consumer Products and Retail Market Segmentation
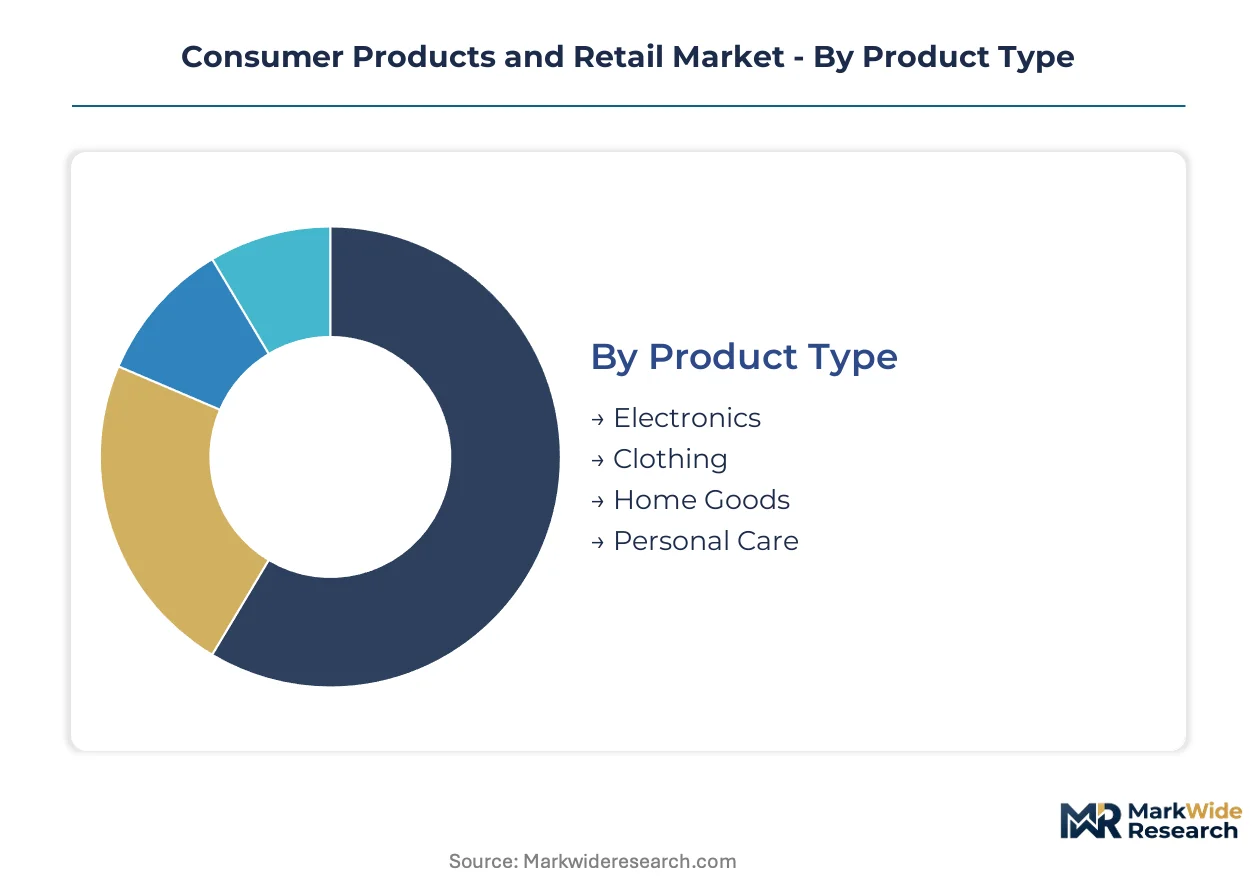
Segmentation in consumer products and retail determines how capital allocates across fulfillment infrastructure, inventory depth, and margin architecture. Distinct demand profiles across product categories, price tiers, and channel preferences force retailers to configure separate operating models for each slice.
Product Type:
Volume concentration sits in high-velocity consumables. Premium margin capture concentrates in technology-intensive categories with compressed replacement cycles.
- Electronics:Semiconductor-dependent devices with warranty attach opportunities and rapid obsolescence windows. Demand clusters in United States metropolitan corridors where same-day fulfillment density justifies predictive inventory positioning. Tariff exposure on Asian component sourcing compresses margin buffers.
- Clothing:Apparel with high return rates and seasonal SKU velocity requiring flexible sourcing. Fast-fashion consumption concentrates in urban European markets where REACH compliance adds reformulation costs. Returns logistics intensity strains warehouse automation capex cycles.
- Home Goods:Bulky furniture and décor with extended purchase cycles.
- Personal Care:FDA-regulated formulations with recurring replenishment patterns.
Mature deployment sits with Personal Care. Newer deployment is concentrated in Electronics.
Price Tier:
Margin architecture stratifies across four distinct willingness-to-pay bands. Each tier demands separate supplier negotiation postures and shelf-space allocation rules.
- Luxury:Brand-equity-driven positioning with controlled distribution scarcity and experiential retail fixtures. Demand concentrates in United Arab Emirates and Swiss duty-free corridors where tourism flows sustain premium pricing power. CSRD disclosure requirements are forcing supply chain transparency investments.
- Mid-Range:Quality-perception balancing acts targeting professional households with stable disposable income. Private-label encroachment is compressing national brand volumes in European grocery channels. Costco's curated SKU discipline anchors this tier in warehouse club formats.
- Budget:Value-engineered specifications with thin supplier margins and high volume throughput.
- Discount:Liquidation-adjacent positioning with minimal service infrastructure.
Margin pressure concentrates in Budget. Strategic investment flows toward Luxury.
Distribution Channel:
Fulfillment economics diverge sharply between asset-light digital and fixed-cost physical footprints. Channel choice determines working capital intensity and customer data capture depth.
- Online:Algorithmic personalization engines and returns-intensive logistics networks. Amazon's Prime-driven recurring revenue depends on predictive inventory positioning across United States fulfillment nodes. FTC pricing transparency scrutiny shapes promotional conduct.
- Brick-and-Mortar:Immediate-need capture with defensive value in grocery and pharmacy categories. Walmart's store-as-warehouse infrastructure compresses last-mile costs for perishable segments. California EPR mandates are adding end-of-life collection overhead.
- Direct Sales:Manufacturer-owned channels with full margin retention.
- Wholesale:Volume aggregation with reduced brand control.
Capital deployment favors Online. Defensive positioning remains with Brick-and-Mortar.
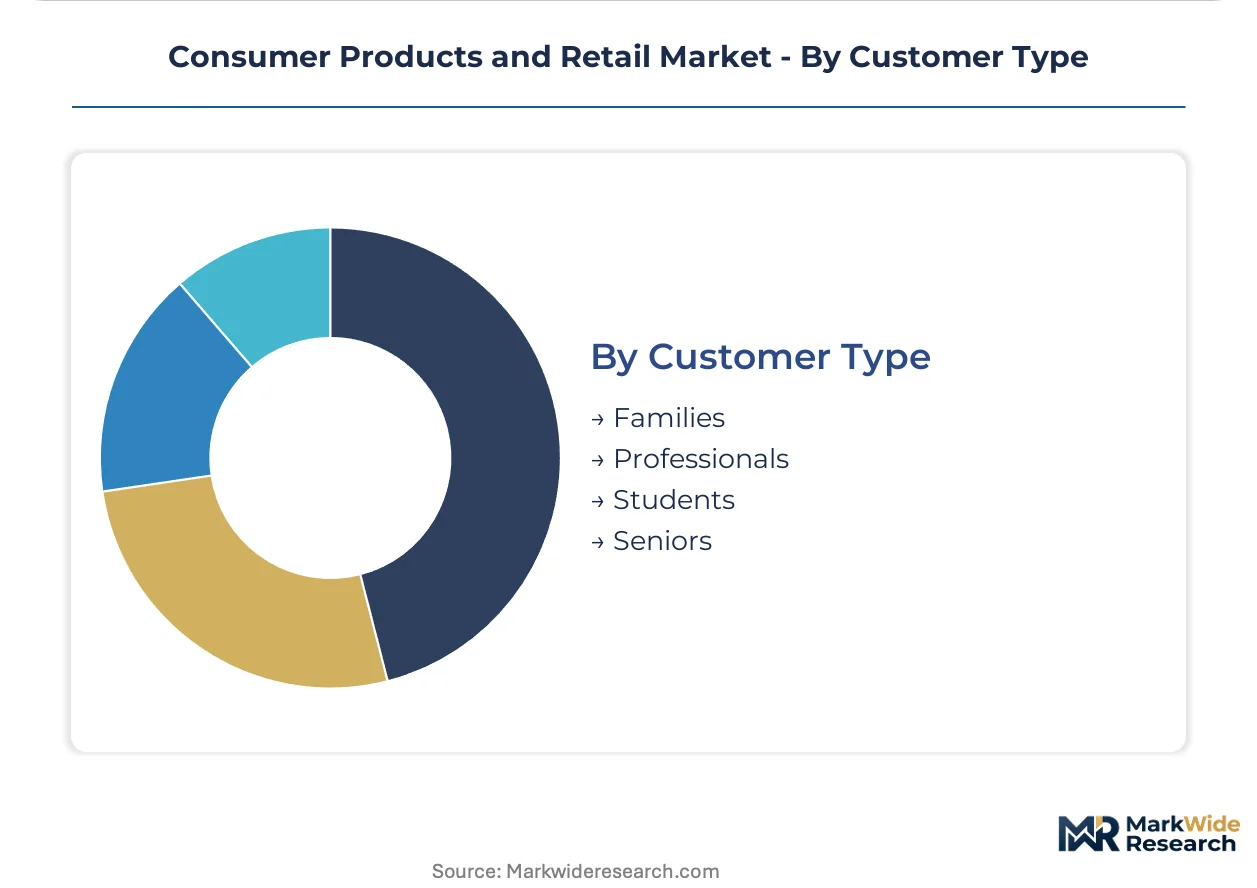
Customer Type:
Life-stage segmentation drives category mix and trip frequency patterns. Each cohort demands distinct loyalty mechanism design.
- Families:Bulk purchasing with basket-size optimization and meal-planning convenience needs. Demand concentrates in United States suburban markets where warehouse club density supports stock-up economics. Private-label expansion captures margin pools in food and household essentials.
- Professionals:Time-constrained purchasing with premium convenience willingness-to-pay. Rapid delivery app adoption clusters in dense European urban centers where sub-two-hour fulfillment is viable. GDPR compliance shapes data-driven personalization investments.
- Students:Price-sensitive discretionary spending with digital-native channel preferences.
- Seniors:Pharmacy-adjacent purchasing with service-assisted transaction needs.
Technology investment prioritizes Professionals. Service infrastructure concentrates on Seniors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household spending concentration in the United States is absorbing disproportionate wallet share through omnichannel fulfillment density, while European regulatory layering and Asian manufacturing hubs reshape competitive positioning across distinct national markets.
United States
Walmart and Amazon capture dominant household wallet share through store-as-warehouse infrastructure and Prime-driven predictive inventory positioning. FTC monitors pricing transparency and deceptive advertising practices that constrain promotional conduct. Greater Boston and Pacific Northwest metropolitan corridors concentrate rapid delivery app adoption where sub-two-hour fulfillment economics justify technology investment.
Germany
Mid-range private-label encroachment compresses national brand volumes in grocery channels as consumers prioritize value-engineered specifications. REACH and RoHS substance restrictions force reformulation of food-contact materials and electronics coatings sold through retail channels. Bavaria and North Rhine-Westphalia anchor warehouse club density where curated SKU discipline captures recurring revenue streams.
China
Semiconductor-dependent electronics manufacturing concentrates component sourcing for global retail supply chains despite tariff exposure on Asian inputs. SAMR and GB standards regulate product safety claims and labeling for personal care items distributed through domestic channels. Yangtze River Delta and Pearl River Delta clusters dominate packaging material production where resin price swings compress working capital turns.
United Kingdom
GDPR compliance shapes data-driven personalization investments for time-constrained professional households adopting rapid delivery services. CSRD disclosure requirements force supply chain transparency investments among luxury retailers with controlled distribution scarcity. London/Southeast corridor concentrates premium brand-equity positioning where experiential retail fixtures sustain pricing power.
India
Bulk purchasing patterns among suburban families drive private-label expansion in food and household essentials as warehouse club formats penetrate emerging markets. FSSAI oversees food safety standards for retail distribution while BIS certification requirements apply to electronics and small appliances. Maharashtra and Gujarat industrial corridors concentrate manufacturing partnerships where domestic sourcing reduces import dependency.
Consumer Products and Retail Market Vendor Landscape
United States retailers anchor one tier through integrated fulfillment networks and member loyalty programs; European specialists hold defensive positioning through regulatory compliance infrastructure and curated transparency investments. The vendor base stratifies across three tiers: mass-market operators with store-as-warehouse density, digital-native platforms with algorithmic personalization engines, and warehouse clubs with bulk-value positioning. Dominant competitive moves include private-label portfolio expansion into food and personal care segments, and predictive inventory positioning across perishable and seasonal categories.
Within the mass-market tier, Walmart exemplifies store-as-warehouse infrastructure deployment that compresses last-mile costs for grocery categories. Amazon occupies a position on the digital-native vector where Prime-driven recurring revenue depends on predictive inventory positioning across fulfillment nodes. Costco anchors the warehouse club archetype through curated SKU discipline and member loyalty programs that capture margin pools in bulk purchasing segments.
| Leading Market Players |
|---|
| Home Depot |
| CVS |
| Walmart |
| Target |
| Walgreens |
| Amazon |
| Kroger |
| Procter & Gamble |
| Costco |
| Others |
Supply Flow & Price Mechanics
Private-label versus national-brand divergence compresses margin pools unevenly across grocery and personal care segments, with controlled sourcing anchoring pricing power for retailers while resin volatility and Asian component dependency strain cost structures upstream.
Pricing Analysis
Volume concentration in consumables trades against premium capture in electronics and luxury positioning. Three-tier pricing structure across premium, standard, and economy levels reflects brand equity, certification grade, and fulfillment speed. Pricing pressure stems from input cost volatility in packaging materials. Budget-tier households exhibit highest price sensitivity; luxury buyers demonstrate lowest elasticity.
Supply Chain Analysis
Extended Producer Responsibility laws in California and Oregon are reshaping domestic-content requirements for end-of-life collection infrastructure. Manufacturing concentrates in China for electronics components, Bangladesh and Vietnam for apparel, and Germany for precision machinery. Resin, semiconductors, and organic cotton constitute critical input dependencies. Tariff exposure on Asian sourcing creates structural vulnerability. Distribution runs through omnichannel nodes with store-as-warehouse density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private-label capacity constraints prop national-brand pricing power, creating a supply-constrained environment where controlled sourcing investments determine competitive survival.
For Market Incumbents: Cement store-as-warehouse infrastructure to compress last-mile costs against Amazon's predictive inventory positioning. Deepen backward integration into food-contact materials to offset REACH reformulation cost escalations. Prioritize curated SKU discipline to anchor member loyalty against warehouse club encroachment. For New Entrants and Emerging Players: Begin with rapid delivery app partnerships in United States metropolitan corridors where sub-two-hour fulfillment economics justify technology investment. Target time-constrained professional households in dense European urban centers. Leverage algorithmic personalization as primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated private-label specialists given CSRD disclosure requirements forcing supply chain transparency investments. Five-to-ten-year viability favors operators with captive manufacturing and traceability infrastructure. Monitor biodegradable packaging innovation adoption curves as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Private-Label Portfolio Expansion | Captures margin pools in food and personal care segments previously allocated to P&G and Unilever. |
| Store-as-Warehouse Infrastructure | Walmart's fulfillment node density compresses last-mile costs below digital-native competitors. |
| Algorithmic Personalization Investment | Machine learning recommendation engines unlock profitability in returns-intensive apparel categories. |
| Biodegradable Packaging Transition | Compostable film advances open premium shelf-space allocation in European grocery chains. |
| Member Loyalty Program Deepening | Costco's curated SKU discipline anchors recurring revenue streams in bulk purchasing segments. |
Methodological Framework
Multi-period observation of inventory velocity metrics, private-label penetration rates, and omnichannel fulfillment cost structures anchored the trend analysis, supplemented by interviews with category buyers at mass-market retailers, supply chain planners at grocery chains, brand managers at consumer products companies, and regulatory compliance officers. Secondary validation drew from Nielsen retail audit data, customs import records, FDA labeling guidance documents, and SEC 10-K disclosures. Bottom-up SKU-level modeling triangulated against top-down household expenditure surveys.
Segment-weighting applied product type, price tier, distribution channel, and customer life-stage dimensions across the projection horizon. Electronics, clothing, home goods, and personal care constituted the product-type split. CAGRs derived from trend extrapolation of inventory turns, private-label share trajectories, and fulfillment cost compression curves. Forecast inputs included resin price volatility indices and EPR compliance cost estimates.
Underlying measurement precision varies by segment; online channel metrics carry tighter precision than direct sales estimates. Forecasts embed assumptions around regulatory implementation timelines and consumer behavioral stickiness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
In Store Signage Market
Retailing
Electronics Retailing Market
Retailing
Subscription Box Market
Retailing
North America Retail Vending Machine Market
Retailing
Clothing Retail Market
Retailing
Out Store Signage Market
Retailing
Global Food and Non-Food Retail Market
Retailing
Furniture Rental Service Market
Retailing
Singapore Gifting Market
Retailing
Retail Signage Market
Retailing
Vietnam Retail Market
Retailing
Qatar Retail Market
Retailing
Floor Mat Rental Service Market
Retailing
United States Hardware Stores Retail Market
Retailing
Asia-Pacific Duty-Free Retailing Market
Retailing
Floor Displays Market