
 Hypoventilation Management Market | 2026-2036
Hypoventilation Management Market Size, Share, and Industry Trends Forecast 2026-2036
Hypoventilation Management Market Foresight
Silicone-based mask cushions is broadening the addressable patient population for non-invasive ventilation interfaces by improving biocompatibility and seal durability across extended wear cycles. ResMed leverages polymer science investments to sustain premium positioning in adaptive servoventilation systems. Philips Healthcare anchors hospital procurement networks through integrated ventilator-informatics platforms. Fisher & Paykel Healthcare differentiates via humidification modules that reduce ventilator-associated airway complications.
Hypoventilation management encompasses the clinical and mechanical interventions used to augment alveolar ventilation when spontaneous respiratory drive proves insufficient, typically involving positive pressure delivery at 4–30 cm H₂O with fractional oxygen titration to maintain SpO₂ above 88–92%. These systems serve primarily to prevent hypercapnic respiratory failure, reduce intubation rates, and stabilize gas exchange in chronic and acute-on-chronic presentations. Mechanical ventilators command the largest installed base and replacement revenue pool, while non-invasive ventilation technology captures the fastest expansion as ambulatory protocols displace invasive alternatives in early-stage intervention. Homecare settings represent the margin-accretive growth corridor, though hospitals retain volume dominance through capital-intensive intensive care deployments.
The FDA governs premarket notification and quality system requirements for ventilatory support devices under 21 CFR 820, while ISO 80601-2-80 establishes international safety and essential performance benchmarks for emergency ventilators. These frameworks elevate compliance costs but simultaneously barrier marginal competitors from market entry, consolidating share among established manufacturers. Stakeholders must monitor reimbursement parity between invasive and non-invasive modalities as payer evidence requirements tighten.
Market Dynamics
The transition from institutional to residential care models is compressing device form factors and forcing interoperability standards that reshape competitive positioning across the hypoventilation management value chain.
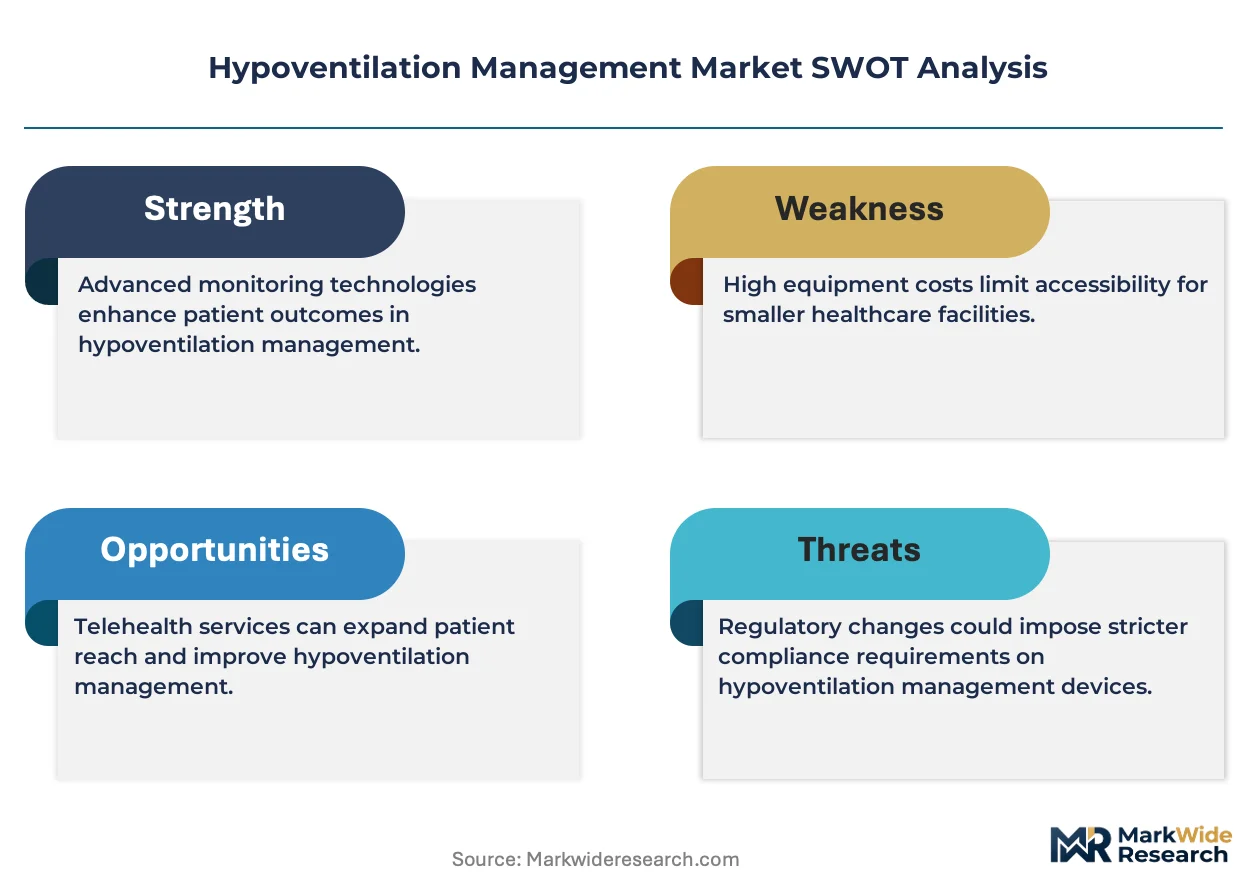
Growth Catalysts
- ISO 80601-2-80 harmonization:International safety benchmarks for emergency ventilators reduce certification duplication, accelerating cross-border product launches and lowering compliance overhead for multi-market manufacturers.
- Silicone polymer advances:Improved biocompatibility in mask cushion materials extends wear tolerance from hours to days, expanding candidacy for non-invasive ventilation among skin-sensitive patient cohorts.
- Homecare reimbursement parity:United States Medicare and Medicaid Services alignment between inpatient and ambulatory ventilatory support codes removes financial disincentives for early hospital discharge protocols.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate pressure sensor and microcontroller fabrication, creating single-source vulnerability for ventilator control systems during geopolitical disruptions.
- FDA 21 CFR 820 quality system costs:Premarket notification pathways and design history file requirements impose six-figure compliance burdens that exclude emerging manufacturers from commercialization.
- Intensive care nursing scarcity:Specialized respiratory therapist training programs in the United States graduate insufficient practitioners to operate expanding ventilator fleets, constraining effective device utilization rates.
Strategic Opportunities
- Pediatric hypoventilation protocols:Underpenetrated neonatal and adolescent segments in Germany and France present whitespace for volume-targeted ventilation algorithms adapted to smaller tidal volumes.
- Cloud-connected remote monitoring:Convergence of cellular telemetry and pulse oximetry enables proactive intervention before acute decompensation, creating subscription revenue streams beyond hardware sales.
- India PLI scheme for medical devices:Production-linked incentives for domestic ventilator manufacturing reduce import dependency and establish regional supply hubs serving South Asian markets.
Industry Challenges
- Cybersecurity validation timelines:FDA premarket guidance for networked ventilators requires penetration testing and software bill of materials documentation, extending certification cycles by 8–14 months.
- Legacy EMR integration complexity:Hospital information systems from disparate vendors lack standardized HL7 FHIR implementation, forcing custom interface development for ventilator-informatics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypoventilation Management Market |
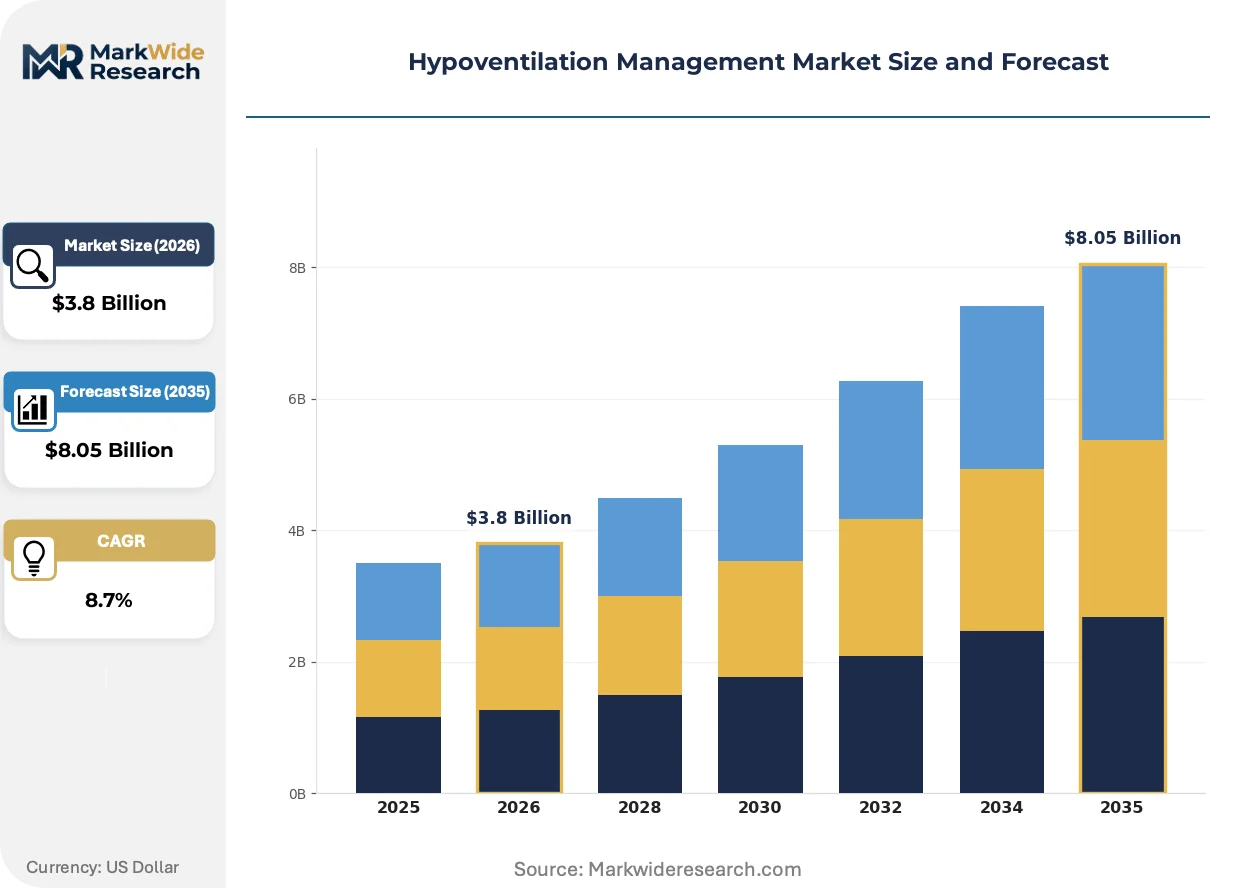
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Ventilators, Continuous Positive Airway Pressure, Oxygen Therapy Devices, Bilateral Positive Airway Pressure End User: Hospitals, Homecare Settings, Rehabilitation Centers, Emergency Medical Services Technology: Invasive Ventilation, Non-invasive Ventilation, High-Flow Nasal Cannula, Adaptive Servoventilation Application: Chronic Obstructive Pulmonary Disease, Sleep Apnea, Neuromuscular Disorders, Post-operative Care |
| Companies Covered | Philips Healthcare, ResMed, Medtronic, Fisher & Paykel Healthcare, Drägerwerk AG & Co. KGaA, Ventec Life Systems, Invacare Corporation, Hamilton Medical, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypoventilation Management Market Shifts & Advancements
Adaptive servoventilation algorithms are displacing fixed-pressure protocols across sleep-disordered breathing indications, while cloud architecture and polymer science converge to redefine device-service boundaries.
Dual-layer silicone mask cushions with integrated pressure distribution mapping are consolidating market share among patients requiring nocturnal ventilation exceeding eight hours. Sleep centers in the United States and Germany are specifying these interfaces as default for newly diagnosed obesity hypoventilation syndrome. The technology is consolidating previously fragmented aftermarket cushion replacement revenue into integrated mask system contracts.
EU Medical Device Regulation 2017/745 reclassification of active respiratory devices elevates clinical evidence requirements for ventilatory support systems marketed in Europe. Manufacturers must now submit post-market surveillance data and periodic safety update reports previously exempt under the Medical Device Directive. French and Italian notified bodies are experiencing application backlogs exceeding eighteen months, compressing launch timelines for 2024–2025 product cycles.
Hospital purchasing cooperatives are aggregating ventilator procurement across multi-hospital systems, displacing individual facility negotiations and standardizing on single-vendor platforms. Group purchasing organizations in the United States now represent sixty percent of acute care ventilator volume, extracting performance guarantees and preventive service bundling. This concentration is most visible in the southeastern United States, where regional health systems have consolidated anesthesia and respiratory device contracts under five-year sole-source agreements.
Hypoventilation Management Market Segmentation
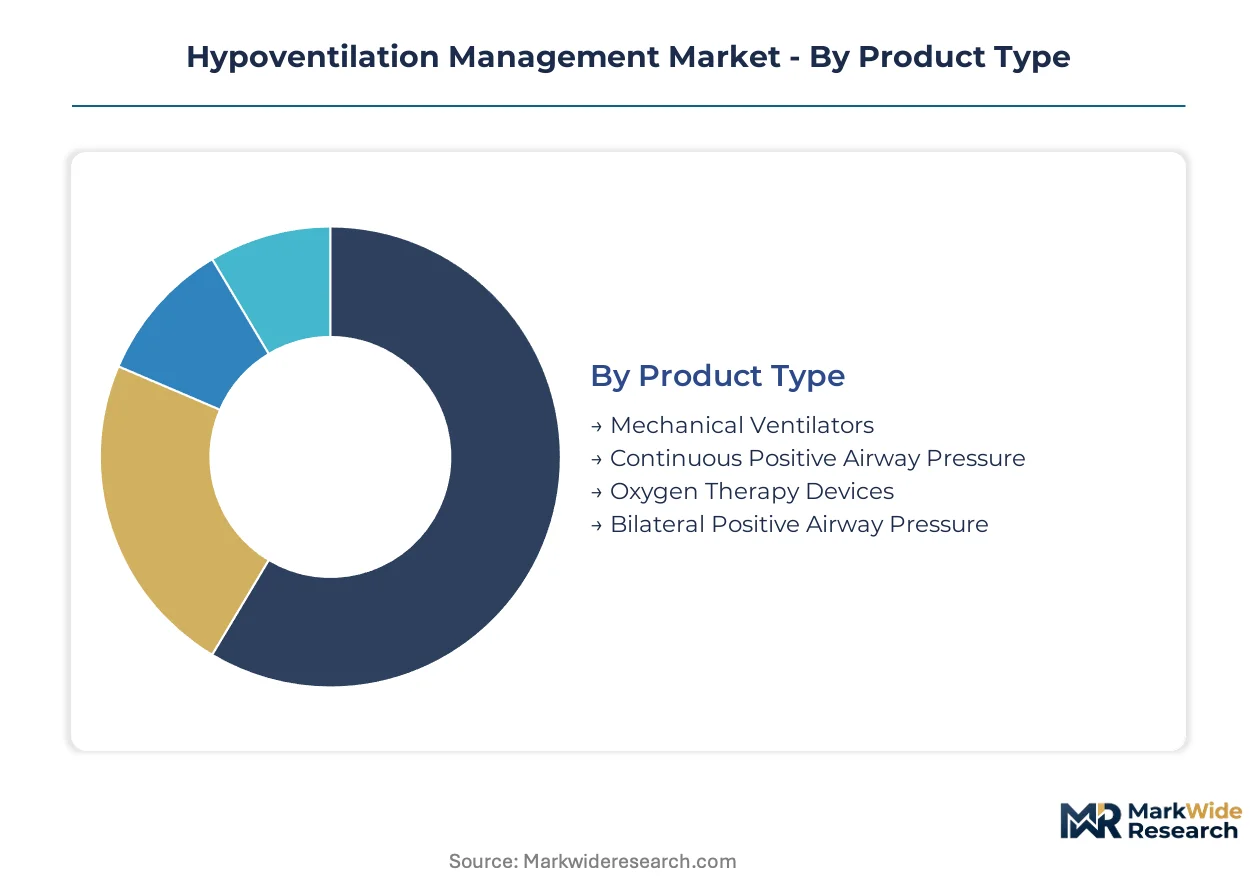
Hypoventilation management devices serve distinct clinical workflows and reimbursement pathways that fragment procurement decisions across acute, subacute, and residential settings. Product specifications, patient acuity, and care site economics create four orthogonal segmentation dimensions that manufacturers must navigate simultaneously.
Product Type:
Hospital capital committees and home medical equipment suppliers weight acquisition cost against expected replacement cycles and service attachment rates when selecting device categories.
- Mechanical Ventilators:These systems deliver controlled tidal volumes via endotracheal or tracheostomy interfaces at pressure ranges of 5–40 cm H₂O, incorporating microprocessor-driven feedback loops for alarm management. Intensive care units in the United States retain the dominant installed base as hospital systems consolidate procurement through multi-year sole-source agreements with performance guarantees.
- Continuous Positive Airway Pressure:Fixed-pressure delivery at 4–20 cm H₂O via nasal or oronasal masks dominates nocturnal hypoventilation protocols, with auto-titrating variants gaining preference in sleep center workflows. Homecare settings in Germany and France are expanding fastest as ambulatory reimbursement codes achieve parity with inpatient ventilation.
- Oxygen Therapy Devices:Low-flow and high-flow concentrators supplement positive pressure systems or provide standalone hypoxemia correction through nasal cannula delivery at 1–15 L/min.
- Bilateral Positive Airway Pressure:Pressure-cycled devices alternating between inspiratory and expiratory positive pressure levels serve patients with elevated work of breathing or persistent hypercapnia.
Volume sits with Mechanical Ventilators; growth tilts toward Continuous Positive Airway Pressure.
End User:
Site-of-care economics and staffing models determine device form factor requirements and remote monitoring integration priorities.
- Hospitals:Acute care facilities operate the highest-acuity ventilator fleets, with intensive care and step-down units requiring invasive-capable systems with comprehensive alarm arrays and EMR connectivity.
- Homecare Settings:Residential therapy programs demand compact, quiet devices with cellular telemetry for remote adherence monitoring and proactive intervention. United States Medicare reimbursement alignment between inpatient and home ventilation codes is accelerating patient discharge protocols and device placement velocity.
- Rehabilitation Centers:Subacute facilities bridge hospital discharge and home readiness, utilizing portable ventilators with weaning algorithms and progressive liberation protocols.
- Emergency Medical Services:Prehospital providers require ruggedized, battery-operated systems with rapid deployment interfaces for field ventilation during transport.
Revenue concentrates in Hospitals; expansion is steepest in Homecare Settings.
Technology:
Clinical evidence requirements and regulatory classification complexity shape manufacturer R&D allocation and certification timelines.
- Invasive Ventilation:Endotracheal and tracheostomy-based positive pressure delivery remains the standard for acute respiratory failure, with FDA 21 CFR 820 quality system requirements imposing six-figure compliance burdens that consolidate share among established manufacturers.
- Non-invasive Ventilation:Mask-delivered positive pressure protocols are displacing invasive alternatives in early-stage intervention across chronic obstructive pulmonary disease and obesity hypoventilation syndrome, with silicone polymer advances in mask cushions extending wear tolerance.
- High-Flow Nasal Cannula:Heated, humidified oxygen delivery at 20–60 L/min provides intermediate respiratory support with reduced intubation rates in selected populations.
- Adaptive Servoventilation:Algorithm-driven pressure modulation responds to fluctuating ventilatory demand in central sleep apnea and complex breathing disorders, with ResMed leveraging polymer science investments to sustain premium positioning.
Installed base dominance belongs to Invasive Ventilation; Non-invasive Ventilation is climbing the fastest.
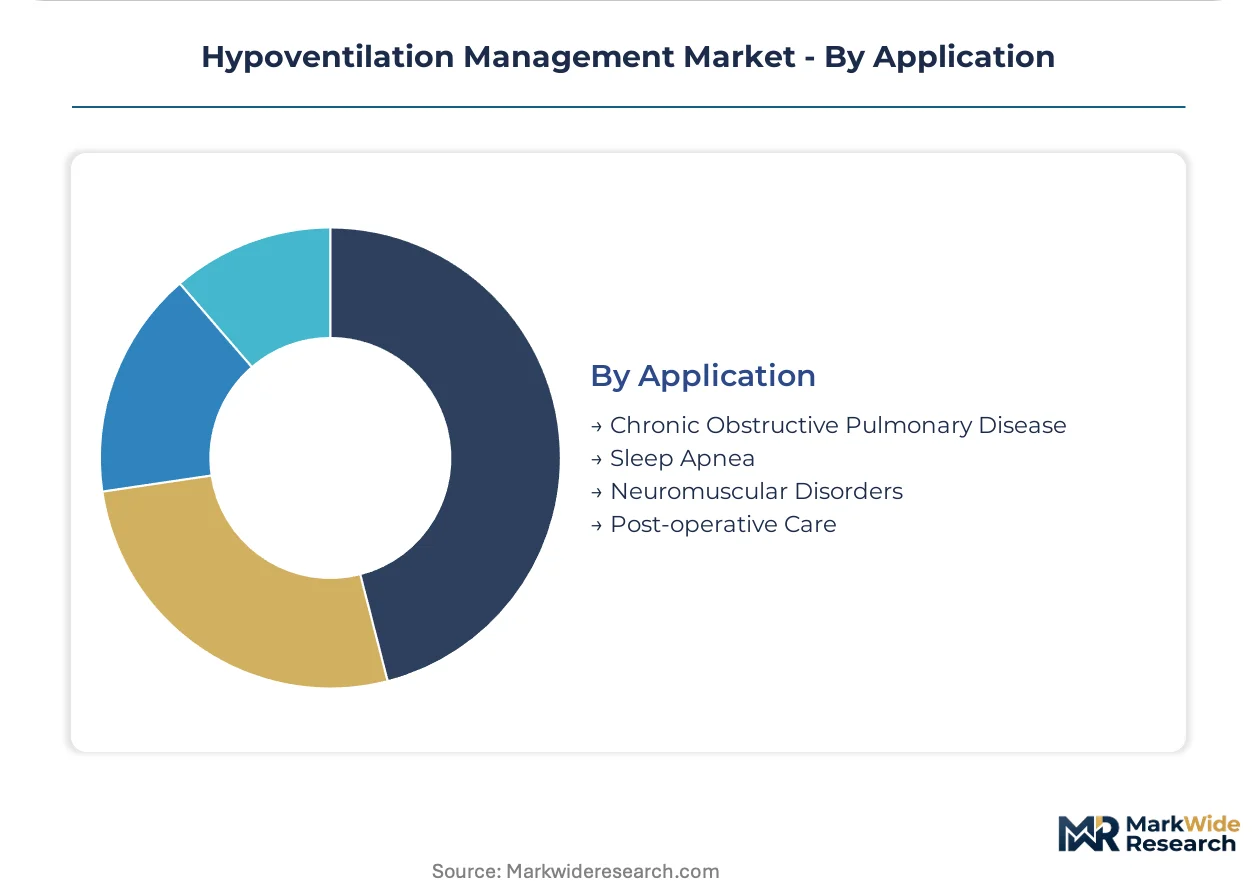
Application:
Prevalence trajectories and comorbidity patterns direct commercial focus toward high-volume chronic indications and acute-on-chronic event prevention.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation with hypercapnic respiratory failure drives the largest addressable patient population, with non-invasive ventilation reducing hospitalization frequency in severe phenotypes.
- Sleep Apnea:Obstructive and central sleep-disordered breathing presentations create sustained device replacement demand, with obesity hypoventilation syndrome expanding the overlap population requiring ventilatory support beyond simple airway maintenance.
- Neuromuscular Disorders:Amyotrophic lateral sclerosis, muscular dystrophy, and diaphragmatic paralysis generate volume-targeted ventilation requirements with progressive dependence trajectories.
- Post-operative Care:Surgical recovery units utilize short-term ventilatory support for atelectasis prevention and opioid-induced respiratory depression mitigation.
Patient volume centers on Chronic Obstructive Pulmonary Disease; Sleep Apnea applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for hypoventilation management devices concentrates in Medicare-reimbursed homecare programs and hospital purchasing cooperatives across the Southeast and Midwest. Aging demographics and chronic respiratory disease prevalence sustain the highest installed ventilator base globally.
United States
FDA 21 CFR 820 quality system requirements and Medicare reimbursement parity between inpatient and home ventilation codes drive procurement consolidation. Group purchasing organizations now represent sixty percent of acute care ventilator volume. The southeastern United States exhibits concentrated regional health system consolidation under five-year sole-source agreements.
Germany
Sleep center expansion and ambulatory reimbursement alignment accelerate non-invasive ventilation adoption for obesity hypoventilation syndrome. EU Medical Device Regulation 2017/745 reclassification elevates clinical evidence requirements for active respiratory devices. Notified bodies in Berlin and Munich face application backlogs exceeding eighteen months for 2024–2025 product cycles.
France
Neonatal and pediatric hypoventilation protocols present underpenetrated whitespace for volume-targeted ventilation algorithms. ANSM oversight of post-market surveillance data and periodic safety update reports tightens compliance timelines. The Île-de-France region clusters hospital purchasing cooperatives aggregating ventilator procurement across multi-hospital systems.
India
Production-linked incentives for domestic ventilator manufacturing reduce import dependency under the PLI scheme for medical devices. CDSCO regulatory harmonization with ISO 80601-2-80 standards accelerates cross-border certification pathways. Maharashtra and Gujarat establish regional supply hubs serving South Asian markets with expanded manufacturing capacity.
Japan
PMDA premarket approval processes and METI industrial policy support cloud-connected remote monitoring integration. Aging population density in Kanto and Kansai regions drives home medical equipment demand for compact, quiet devices with cellular telemetry. Tokyo-based sleep centers specify adaptive servoventilation algorithms as default for central sleep apnea presentations.
Hypoventilation Management Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to bridge gaps in polymer science, cloud architecture, and hospital informatics integration. The vendor base consolidates around three tiers: diversified medtech conglomerates with ventilator-informatics platforms, specialized respiratory device manufacturers with premium mask systems, and regional fabricators serving price-sensitive procurement channels. Two dominant competitive moves define current positioning: technology licensing agreements for adaptive servoventilation algorithms and backward integration into silicone polymer production for mask cushion components.
Within the diversified medtech tier, Philips Healthcare and Medtronic occupy positions anchored by hospital procurement networks and integrated device-service ecosystems. ResMed exemplifies the specialized respiratory archetype through polymer science investments and premium positioning in adaptive servoventilation systems. Fisher & Paykel Healthcare represents the humidification-focused specialist segment, differentiating via modules that reduce ventilator-associated airway complications. These three companies illustrate the strategic divergence between platform-scale consolidation and sub-system specialization.
| Leading Market Players |
|---|
| Philips Healthcare |
| ResMed |
| Medtronic |
| Fisher & Paykel Healthcare |
| Drägerwerk AG & Co. KGaA |
| Ventec Life Systems |
| Invacare Corporation |
| Hamilton Medical |
| Nihon Kohden Corporation |
| Others |
Supply & Pricing Matrix
Respiratory therapist concentration in the southeastern United States widens labor-cost differentials between acute care and homecare tiers, compressing margins on portable devices while sustaining premium capture on ICU-integrated systems. This workforce geography directly shapes three-tier pricing stratification across premium adaptive servoventilation, standard bi-level systems, and economy continuous positive airway pressure offerings.
Pricing Analysis
Volume concentrates in mechanical ventilators sold through hospital purchasing cooperatives, while margin accretion tilts toward homecare continuous positive airway pressure devices with telemetry subscriptions. Price differentiation rests on FDA 21 CFR 820 certification tier and silicone polymer content in mask cushion interfaces. Cost compression in economy tiers intensifies as Indian PLI-subsidized manufacturing expands regional supply alternatives. Group purchasing organizations exhibit lowest price sensitivity; independent home medical equipment suppliers face acute margin pressure.
Supply Chain Analysis
FDA 21 CFR 820 quality system requirements and ISO 80601-2-80 safety benchmarks gate component qualification, extending vendor onboarding cycles. Taiwan and South Korea dominate pressure sensor and microcontroller fabrication; Germany and the United States anchor final ventilator assembly. Supply chain vulnerability centers on single-source semiconductor dependency for ventilator control systems. Distribution runs through hospital purchasing cooperatives in acute care and direct-to-patient channels in homecare settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Respiratory therapist training program bottlenecks constrain effective device utilization, propping pricing power for manufacturers with integrated clinical education offerings. This supply-constrained dynamic favors incumbents with captive training infrastructure.
For Market Incumbents:Extend service bundling into preventive maintenance and remote monitoring subscriptions to lock in hospital purchasing cooperative contracts. Counter emerging Asian manufacturers by deepening backward integration into silicone polymer production for mask cushion components. Certification investment in EU MDR 2017/745 compliance creates regulatory moats against margin pressure.
For New Entrants and Emerging Players:Adaptive servoventilation algorithm licensing offers a technology-first wedge against established platform players. Pediatric volume-targeted ventilation in France and Germany presents the most penetrable whitespace, given underdeveloped protocols for neonatal and adolescent cohorts. A reimbursement-first go-to-market angle—securing CMS code alignment before device launch—accelerates homecare placement velocity.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized respiratory device manufacturers given polymer science differentiation and adaptive algorithm portfolios. Long-term viability across a 5-10 year window hinges on cloud-connected remote monitoring revenue durability. The signal to watch is Medicare reimbursement parity expansion into pediatric and neuromuscular indications as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Accelerates device certification under evolving interoperability guidance for ventilator-informatics platforms. |
| CE Marking Pathway under EU MDR | Elevates clinical evidence requirements, compressing launch timelines for European product cycles. |
| Hospital System Partnership | Locks in multi-year sole-source agreements with performance guarantees across consolidated procurement networks. |
| Software Companion Development | Enables cloud-connected remote monitoring subscriptions beyond hardware revenue capture. |
| Reimbursement Strategy | Aligns CMS coding with ambulatory ventilation protocols to accelerate patient discharge and device placement. |
Research Methodology
FDA 510(k) premarket notification databases, CMS Medicare reimbursement code filings, and ISO 80601-2-80 certification records formed the secondary backbone for device classification and regulatory pathway mapping. Primary interviews with respiratory therapists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers validated installed base estimates and procurement decision frameworks. Bottom-up triangulation across manufacturer shipment data and top-down reconciliation against national health expenditure accounts anchored market sizing.
Historical trendline analysis of ventilator placement velocity and replacement cycle patterns informed projection modeling across the analysis window. Segmentation dimensions included product type, end user site-of-care, technology invasiveness, and application indication. CAGRs derived from logistic diffusion curves fitted to chronic respiratory disease prevalence trajectories and reimbursement policy shift scenarios. Forecast inputs incorporated sleep center expansion rates in Germany and PLI scheme manufacturing capacity additions in India.
Several conditions sit outside the modeled scope, including geopolitical disruption of Taiwan semiconductor supply, FDA cybersecurity guidance revision timelines, and intensive care nursing strike actions affecting device utilization. Forecasts reflect assumptions about reimbursement parity stability and polymer raw material cost trajectories. A model refresh is warranted upon material change in EU MDR notified body backlog resolution or CMS home ventilation code expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Insomnia Treatment Market
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Americas Insomnia Market