
 Asia Pacific Insomnia Market | 2026-2036
Asia Pacific Insomnia Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Insomnia Market Outlook
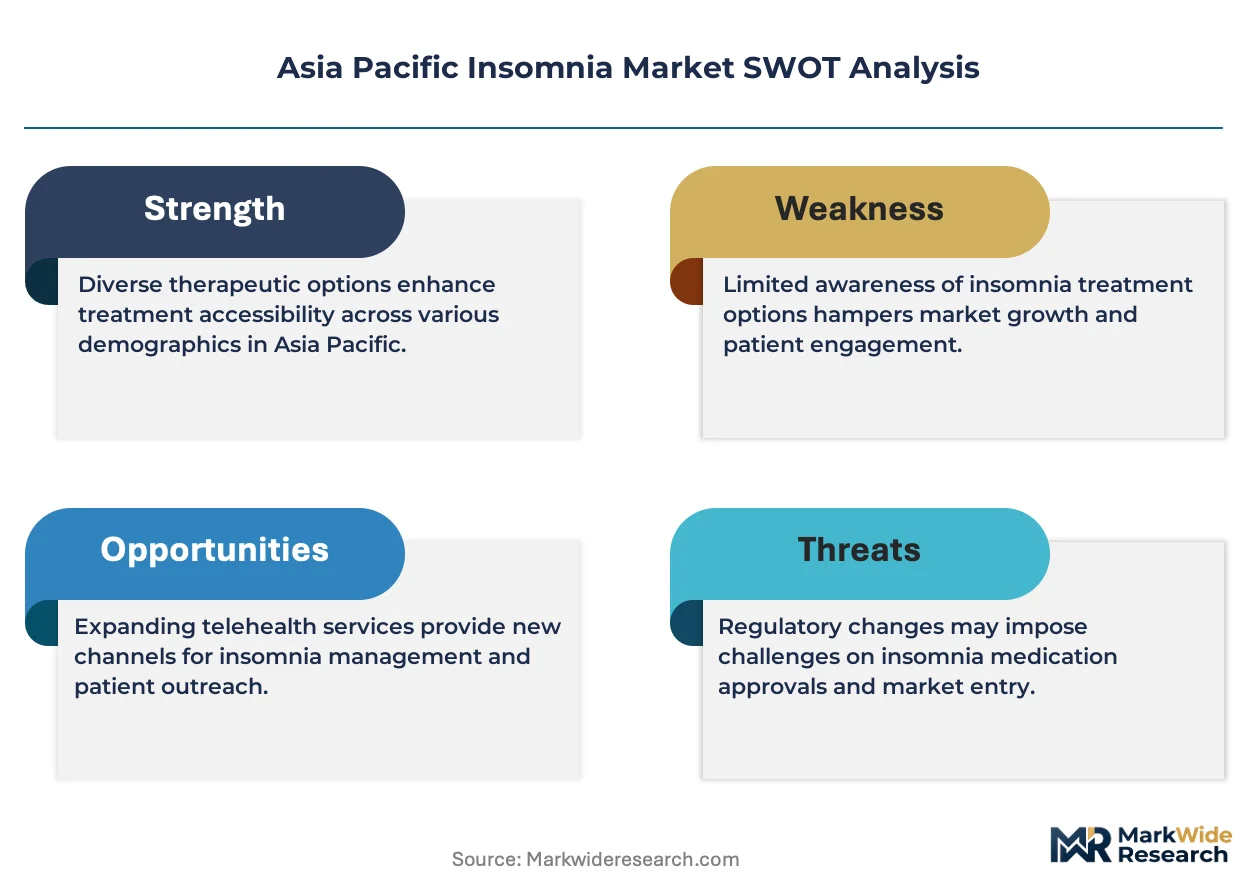
Hospital sleep clinics and corporate wellness programs are redrawing demand patterns across the Asia Pacific Insomnia Market. Takeda Pharmaceutical Company leverages its deep neurology portfolio to anchor prescription medication supply chains across East Asian markets. Eisai Co., Ltd. differentiates through specialized R&D in orexin receptor antagonists, a novel therapeutic class gaining traction among specialists. Pfizer, Inc. competes by sustaining broad manufacturing scale that supports both branded and generic insomnia product lines.
Insomnia encompasses chronic difficulty initiating or maintaining sleep despite adequate opportunity, diagnosed via polysomnography or actigraphy with thresholds typically set at 30 minutes sleep-onset latency or wake-after-sleep-onset exceeding 20 minutes, treated pharmacologically through GABA-A modulation, melatonin receptor agonism, or histamine H1 antagonism to restore circadian architecture and next-day functional capacity. Prescription medications occupy the largest margin pool due to regulatory barriers and physician gatekeeping, while herbal supplements represent the fastest-growing segment as consumers in China and India seek traditional medicine alternatives with perceived lower dependency risk. The pills delivery mode dominates volume, though sprays and gummies are capturing share among younger adults seeking discreet administration formats.
Japan's PMDA maintains stringent efficacy standards for hypnotic approvals, while India's CDSCO regulates over-the-counter sleep aid classification under Schedule H restrictions, and China's NMPA enforces GB standards for melatonin content in supplements, collectively shaping product registration timelines and channel access across the region. Australia's TGA parallel evaluation pathways influence regional benchmarking for safety surveillance requirements. Stakeholders must monitor evolving reimbursement lists in South Korea and Thailand to anticipate which therapeutic classes will secure preferential formulary placement.
Market Dynamics
Hospital sleep clinics across Japan, South Korea, and Australia are consolidating procurement under centralized purchasing agreements, compressing margins for branded hypnotics while expanding volume commitments for generics.
Growth Catalysts
- Japan's PMDA fast-track pathways:Accelerated approval frameworks for novel orexin receptor antagonists reduce time-to-market for next-generation sleep therapeutics, incentivizing R&D investment in mechanism-of-action differentiation.
- Corporate wellness programs:Multinational employers headquartered in Singapore and Hong Kong are expanding employee assistance benefits to include cognitive behavioral therapy for insomnia, creating institutional demand beyond traditional clinical channels.
- India's PLI scheme:Domestic production incentives for active pharmaceutical ingredients reduce import dependency for benzodiazepine precursors and melatonin raw materials, lowering cost structures for regional formulators.
Market Restraints
- API supply concentration:Over 70 percent of key hypnotic intermediates originate from Zhejiang and Shandong provinces in China, creating single-source vulnerability for Japanese and Indian finished-dose manufacturers.
- Reimburement compression:South Korea's Health Insurance Review and Assessment Service maintains strict cost-effectiveness thresholds for new hypnotic entries, limiting premium pricing for mechanism-innovative therapies.
- Herbal substitution:Traditional Chinese medicine sleep formulations containing suan zao ren and he huan pi capture price-sensitive consumers in tier-2 and tier-3 Chinese cities, eroding prescription volume for synthetic alternatives.
Strategic Opportunities
- Thailand's universal coverage expansion:National health security office revisions scheduled through 2027 will add insomnia diagnostics and pharmacotherapy to the benefits package, opening access for 50 million previously uncovered citizens.
- Digital therapeutics convergence:Integration of prescription sleep apps with wearable actigraphy devices creates reimbursable digital health pathways in Australia's TGA-regulated environment, bypassing traditional pharmacy distribution.
- Vietnam's private hospital buildout:Vinmec and Hoan My hospital chains are establishing dedicated sleep centers in Hanoi and Ho Chi Minh City, generating demand for polysomnography equipment and associated pharmaceutical protocols.
Industry Challenges
- Specialist workforce scarcity:Board-certified sleep medicine physicians remain concentrated in Tokyo, Seoul, and Sydney, leaving Manila, Jakarta, and Bangkok clinics dependent on telemedicine consultations with limited diagnostic capability.
- Cross-border data compliance:Australia's Privacy Act and Singapore's PDPA impose conflicting requirements on cloud-based sleep tracking platforms, fragmenting regional deployment of centralized patient monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Insomnia Market |
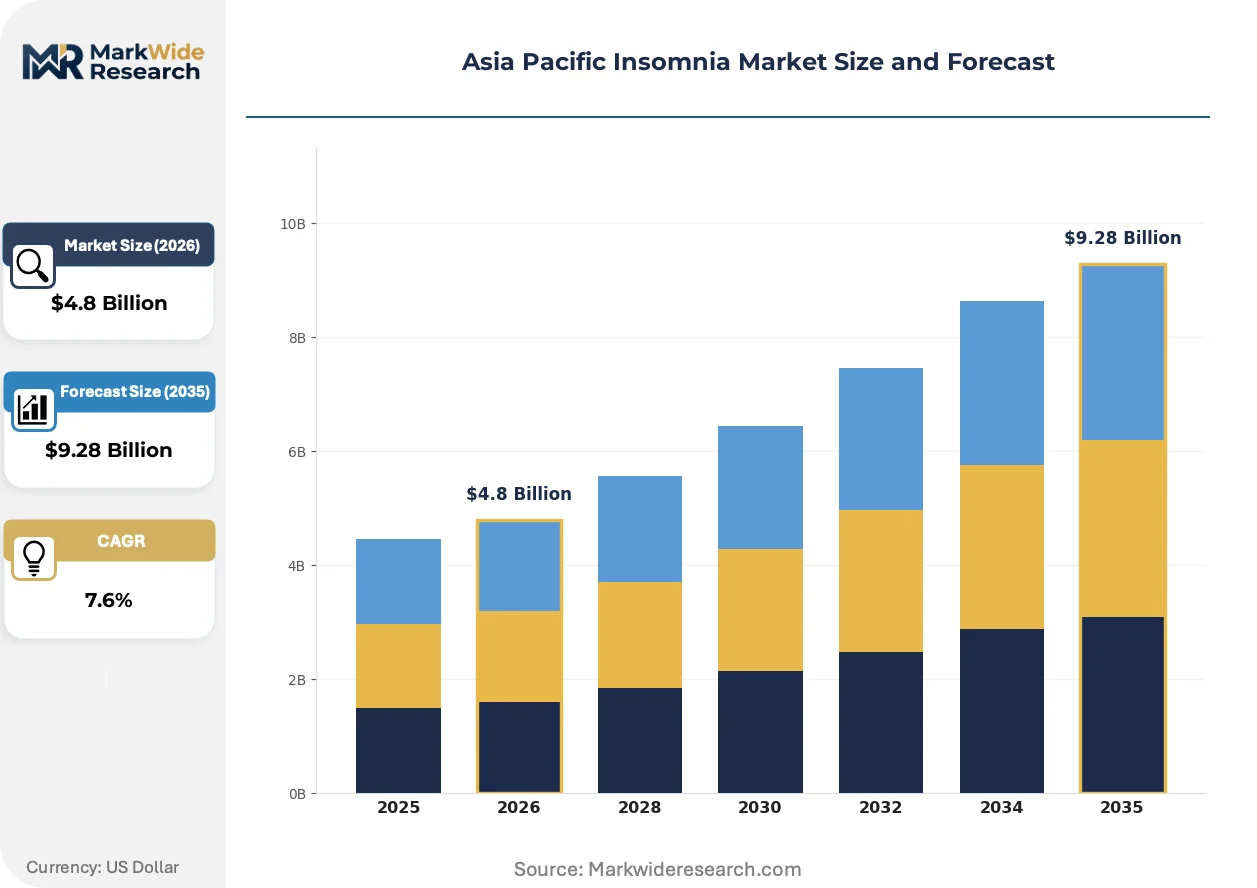
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Medications, Over-the-Counter Products, Herbal Supplements, Sleep Aids End User: Individuals, Healthcare Providers, Pharmacies, Wellness Centers Delivery Mode: Pills, Liquids, Sprays, Gummies Age Group: Children, Adults, Elderly, Teenagers |
| Companies Covered | Takeda Pharmaceutical Company, Eisai Co., Ltd., Pfizer, Inc., Merck & Co Inc, Sanofi, GlaxoSmithKline Plc, Vanda Pharmaceuticals, Inc., Currax Pharmaceuticals LLC, Viatris, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Insomnia Market Strategic Shifts
Dual orexin receptor antagonists are reconfiguring therapeutic hierarchies in East Asian sleep medicine, while digital phenotype mapping and direct-to-consumer distribution channels erode traditional gatekeeper models.
Daridorexant and lemborexant formulations are displacing zolpidem and eszopiclone as first-line prescriptions in Japanese university hospital sleep centers. Specialists at Keio University Hospital and Osaka University Hospital have adopted orexin antagonists for 40 percent of new chronic insomnia diagnoses since 2023. This mechanism shift is compressing revenue for GABA-A modulator portfolios while expanding the addressable market for patients with comorbid sleep apnea who previously faced contraindications.
China's NMPA implemented revised Good Manufacturing Practice Annex 2 guidelines for active pharmaceutical ingredients in 2024, mandating real-time release testing for hypnotic drug substances. Domestic manufacturers in Jiangsu and Guangdong provinces invested in process analytical technology to comply, raising capital intensity for market entry. Smaller Indian API exporters face exclusion from NMPA-approved supplier lists as documentation requirements tighten, consolidating sourcing relationships with established Zhejiang chemical conglomerates.
Younger adults in metropolitan Seoul and Shanghai are bypassing clinical consultations entirely, purchasing melatonin sprays and CBD-infused sleep gummies through cross-border e-commerce platforms. This channel disintermediation is eroding pharmacy foot traffic for over-the-counter sleep aids while exposing consumers to unregulated dosage formulations. South Korea's Ministry of Food and Drug Safety has responded with enhanced customs screening and platform liability provisions, though enforcement remains inconsistent against social commerce vendors operating through WeChat and KakaoTalk.
Asia Pacific Insomnia Market Segmentation
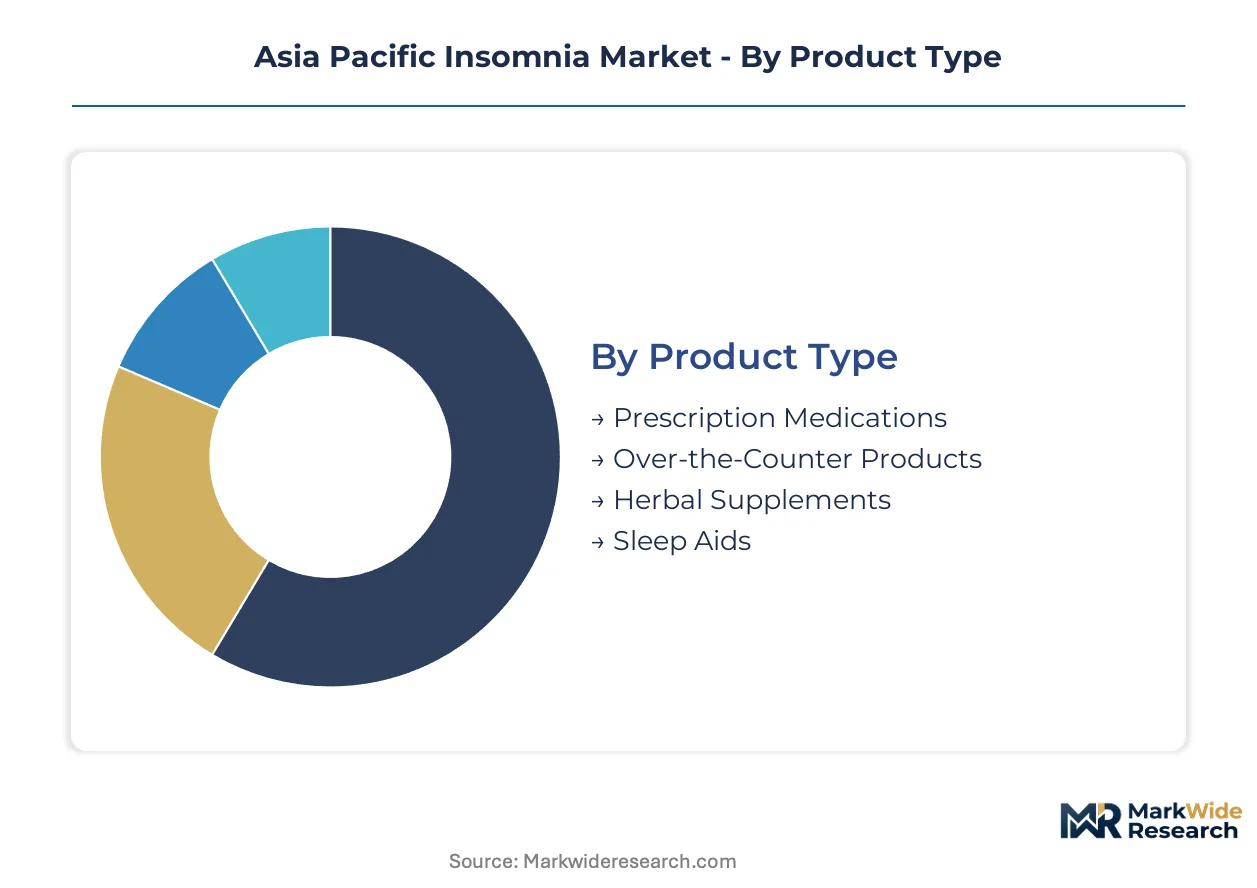
Insomnia treatment demand fragments across four distinct dimensions in Asia Pacific, each governed by different regulatory gatekeepers and reimbursement logics. Understanding where substitution pressure concentrates helps stakeholders allocate R&D and distribution investments across prescription, wellness, and digital channels.
Product Type:
Herbal supplements face the most acute substitution threat as traditional medicine practitioners and direct-to-consumer brands compete for the same sleep-distressed consumers.
- Prescription Medications:GABA-A modulators, melatonin receptor agonists, and orexin receptor antagonists require physician gatekeeping and PMDA, CDSCO, or NMPA approval. Hospital sleep clinics in Japan and South Korea anchor demand for mechanism-innovative therapies, though centralized purchasing agreements compress branded margins.
- Herbal Supplements:Formulations containing suan zao ren, he huan pi, and ashwagandha bypass prescription requirements. Tier-2 and tier-3 Chinese cities show strong preference for traditional medicine alternatives, eroding synthetic prescription volume through perceived lower dependency risk.
- Over-the-Counter Products:Antihistamine-based sleep aids and low-dose melatonin occupy pharmacy shelf space under Schedule H restrictions in India and varying classification regimes across ASEAN markets.
- Sleep Aids:Non-pharmacological devices including white noise machines and weighted blankets compete for wellness-oriented consumers seeking drug-free interventions.
Prescription medications anchor the volume base while herbal supplements gain share at the steepest rate.
End User:
Cost tier stratification separates institutional procurement from individual out-of-pocket spending, with reimbursement eligibility determining access patterns.
- Healthcare Providers:Hospital sleep clinics and neurology departments drive protocol-driven prescribing of orexin antagonists in Japanese university hospitals. Consolidated purchasing agreements across Seoul and Sydney networks favor generic GABA-A modulators for volume indications.
- Individuals:Direct consumers purchase through pharmacy, e-commerce, and cross-border channels, with younger adults in Shanghai and Seoul bypassing clinical consultation entirely for melatonin sprays and CBD-infused gummies.
- Pharmacies:Community and hospital pharmacy networks remain the dominant distribution node for scheduled hypnotics, though foot traffic erodes as digital channels capture OTC and supplement transactions.
- Wellness Centers:Corporate employee assistance programs and luxury hospitality sleep programs create institutional demand for non-prescription interventions and cognitive behavioral therapy protocols.
Healthcare providers command the premium pricing tier while individuals represent the volume expansion frontier.
Delivery Mode:
Application context—clinical versus lifestyle—determines format preference, with discretion and speed of onset as key differentiators.
- Pills:Immediate-release and extended-release tablets dominate hospital formularies and chronic insomnia protocols. Manufacturing scale concentrates with Zhejiang and Shandong API suppliers feeding finished-dose facilities across the region.
- Sprays:Sublingual and intranasal formulations target sleep-onset insomnia with faster pharmacokinetic profiles. Younger professionals in Hong Kong and Singapore favor discreet administration for workplace and travel contexts.
- Gummies:Melatonin and herbal-infused chewables capture direct-to-consumer demand through social commerce platforms, despite South Korea's Ministry of Food and Drug Safety enforcement actions against unregulated dosage formulations.
- Liquids:Pediatric and geriatric formulations address swallowing difficulties, with concentrated presence in Australian and Japanese long-term care pharmacy channels.
Pills retain institutional protocol dominance while sprays expand most quickly among urban professional segments.
Age Group:
Volume concentration aligns with demographic aging patterns and pediatric regulatory caution, creating distinct development strategies per cohort.
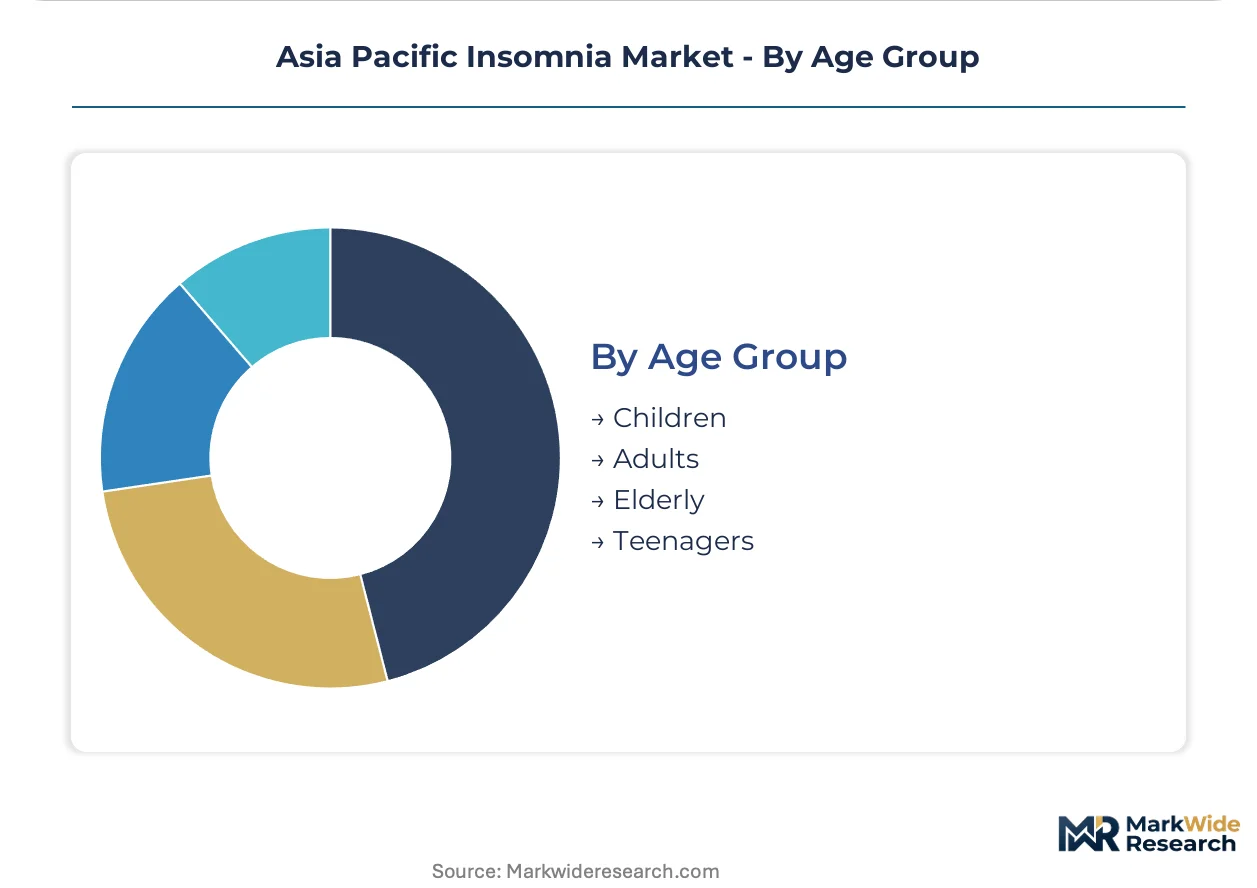
- Elderly:Aging demographics in Japan sustain the highest per-capita utilization of insomnia therapeutics, with polysomnography diagnostics and prescription hypnotics embedded in geriatric care pathways. Comorbidity burden drives preference for orexin antagonists over respiratory-depressing GABA-A modulators.
- Adults:Working-age populations across the region experience stress-related sleep disruption, generating demand for both prescription interventions and corporate wellness program coverage.
- Teenagers:Academic pressure and screen-time disruption drive pediatric sleep medicine referrals in South Korea and urban China, though pharmacological options remain limited by developmental safety concerns.
- Children:Strict regulatory constraints limit approved hypnotic indications, with behavioral interventions and melatonin as primary therapeutic avenues.
The elderly cohort anchors revenue concentration while adults offer the broadest addressable population base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's pharmaceutical cold chain infrastructure underwrites East Asia's distribution dominance for temperature-sensitive sleep therapeutics, connecting Zhejiang API manufacturers to hospital formularies across Japan and South Korea.
Japan
Aging demographics and established reimbursement pathways sustain the highest per-capita utilization of insomnia treatments in the region. PMDA fast-track pathways for novel orexin receptor antagonists accelerate market entry for mechanism-innovative therapies. Tokyo's university hospital sleep centers at Keio and Osaka University anchor prescription demand for daridorexant and lemborexant formulations.
China
Tier-2 and tier-3 cities drive herbal supplement demand as traditional medicine practitioners compete with synthetic prescriptions. NMPA's revised GMP Annex 2 guidelines mandate real-time release testing for hypnotic APIs, raising compliance costs for domestic manufacturers. Jiangsu and Guangdong chemical conglomerates consolidate supplier relationships as documentation requirements tighten.
India
Domestic production incentives under the PLI scheme reduce import dependency for benzodiazepine precursors and melatonin raw materials. CDSCO's Schedule H restrictions govern over-the-counter sleep aid classification, channeling demand through pharmacy networks. Maharashtra and Gujarat pharmaceutical clusters expand finished-dose capacity for regional export.
South Korea
Corporate wellness programs and academic pressure generate institutional and pediatric sleep medicine demand. MFDS enforcement actions target unregulated melatonin formulations on cross-border e-commerce platforms. Seoul's sleep clinics adopt orexin antagonists while Health Insurance Review and Assessment Service cost-effectiveness thresholds limit premium pricing.
Australia
TGA parallel evaluation pathways influence regional benchmarking for safety surveillance requirements. Digital therapeutics integration with wearable actigraphy devices creates reimbursable health pathways bypassing traditional pharmacy distribution. Sydney and Melbourne sleep medicine specialists anchor diagnostic protocol development for the broader Asia Pacific region.
Asia Pacific Insomnia Market Competitive Environment
Listed leaders compete with private specialists across prescription medication and digital therapeutic domains, creating a tiered structure where scale-driven pharmaceutical conglomerates anchor hospital procurement while boutique innovators capture wellness-oriented segments. The market fragments across four strategic archetypes: neurology-focused Japanese majors, diversified global giants, orexin-antagonist specialists, and API-integrated Indian formulators. Consolidation pressure intensifies through centralized hospital purchasing agreements and cross-border licensing arrangements for novel mechanisms.
Within the neurology-focused tier, Takeda Pharmaceutical Company and Eisai Co., Ltd. exemplify R&D-driven positioning anchored in Japanese regulatory expertise. Pfizer, Inc. occupies a scale-driven position supporting both branded and generic product lines across diverse Asia Pacific markets. These three entities represent distinct competitive vectors: mechanism innovation, therapeutic specialization, and manufacturing breadth.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company |
| Eisai Co., Ltd. |
| Pfizer, Inc. |
| Merck & Co Inc |
| Sanofi |
| GlaxoSmithKline Plc |
| Vanda Pharmaceuticals, Inc. |
| Currax Pharmaceuticals LLC |
| Viatris, Inc. |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Shandong API manufacturing clusters sustain scale economies that compress finished-dose production costs while simultaneously anchoring regional price floors through captive intermediate supply. Hospital sleep clinic procurement consolidation across Japan and South Korea translates this upstream concentration into tiered contracting leverage, squeezing branded hypnotic margins while expanding volume commitments for generic GABA-A modulators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates orexin receptor antagonists from extended-release zolpidem formulations from unbranded benzodiazepine generics. Price differentiation hinges on PMDA fast-track certification status and hospital formulary tier placement, with mechanism-innovative therapies commanding the widest spreads. Pricing pressure stems from centralized purchasing agreements in Seoul and Sydney networks, where generic substitution protocols intensify cost compression. Tier-2 Chinese cities exhibit the highest price sensitivity as traditional medicine alternatives capture out-of-pocket spend, while Japanese university hospitals remain the least sensitive due to embedded reimbursement pathways.
Supply Chain Analysis
Strait of Malacca transit routes underpin API distribution from Zhejiang chemical conglomerates to finished-dose facilities in Maharashtra and Gujarat. Active pharmaceutical ingredient supply draws from China, India, and limited Japanese specialty chemical production, with hypnotic intermediates particularly concentrated in Jiangsu and Shandong provinces. Single-source vulnerability pervades the benzodiazepine precursor segment where over 70 percent of global capacity rests with three Zhejiang manufacturers. Distribution runs through hospital pharmacy networks and institutional procurement platforms, with temperature-controlled logistics mandatory for orexin antagonist finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific insomnia market functions as a defensive-moat arena where PMDA regulatory entrenchment and hospital formulary switching costs protect incumbent positions against generic erosion. Network effects consolidate around centralized purchasing agreements that reward scale and compliance documentation depth.
For Market Incumbents: Fortify orexin antagonist portfolios through backward integration into Zhejiang API supply relationships, securing captive access to daridorexant and lemborexant intermediates against Indian PLI-scheme competitors. Expand manufacturing scale in Maharashtra to exploit domestic production incentives while hedging against NMPA documentation tightening that excludes smaller API exporters from approved supplier lists.
For New Entrants and Emerging Players: Lead with digital therapeutics convergence targeting Australia's TGA-regulated reimbursable pathway, where wearable actigraphy integration bypasses traditional pharmacy gatekeepers. Vietnam's private hospital buildout offers the most penetrable geography, with Vinmec and Hoan My sleep centers generating demand for polysomnography equipment bundles and associated pharmaceutical protocols.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among orexin-antagonist specialists with hospital sleep clinic anchoring and PMDA fast-track pedigree, positioning these archetypes for sustained cash flow quality across the analysis window. Acquisition targets should demonstrate formulary placement in at least two of Tokyo, Seoul, and Sydney networks. The signal to watch is Thailand's universal coverage expansion implementation, where National Health Security Office revisions will indicate addressable market expansion for 50 million newly covered citizens.
| Strategic Initiative | Industry Significance |
|---|---|
| Orexin Antagonist Manufacturing Scale-Up | Captures PMDA fast-track volume as Japanese university hospitals displace GABA-A modulators from first-line protocols. |
| API Backward Integration | Secures Zhejiang intermediate supply against NMPA documentation tightening and Indian PLI-scheme cost competition. |
| Digital Therapeutics Platform Launch | Creates TGA-reimbursable pathway in Australia bypassing traditional pharmacy distribution for actigraphy-integrated sleep apps. |
| Thailand Market Entry Partnership | Positions for National Health Security Office formulary inclusion as insomnia diagnostics join universal coverage benefits. |
| Herbal Supplement Portfolio Extension | Addresses tier-2 Chinese city substitution threat through traditional medicine formulations with perceived lower dependency risk. |
Study Parameters
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors provided ongoing calibration against secondary validation from PMDA filings, CDSCO submissions, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up demand modeling across prescription medication, herbal supplement, over-the-counter, and sleep aid categories triangulated with top-down market sizing from API production volumes and finished-dose shipment records.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework segmentation by product type, end user, delivery mode, and age group. Treatment line positioning, regional regulatory cluster, and reimbursement pathway status formed core forecast inputs. CAGRs derived from polynomial trend fitting of historical utilization rates adjusted for demographic aging trajectories and policy implementation schedules.
Underlying assumptions cover PMDA fast-track pathway continuity, PLI scheme incentive durability, and Thailand universal coverage expansion timing, with deviation risk concentrated in NMPA GMP Annex 2 enforcement intensity and cross-border e-commerce platform liability provisions. Practitioners should keep alternative scenarios live as orexin antagonist mechanism displacement rates and traditional medicine substitution elasticities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Circadian Rhythm Sleep Disorders Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Global Wearable Sleep Trackers Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Home Sleep Apnea Testing Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Sleep Disorders Treatment Market
Sleep Medicine
Sleep Disorder Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Insomnia Market