
 Sleep Soother Market | 2026-2036
Sleep Soother Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Soother Market Analytics
Market Dynamics and Competitive Landscape
A shortage of certified sleep technologists is unwinding manufacturing capacity expansion plans across the industry. ResMed Inc. leverages its vertical integration into mask and device production to sustain margin control against component volatility. Koninklijke Philips N.V. anchors its competitive position through R&D intensity in connected sleep ecosystems. Eight Sleep differentiates via technology leadership in biometric-responsive temperature modulation systems.
Product Architecture and Segment Structure
Sleep soothers encompass non-pharmacological interventions including acoustic, thermal, olfactory, and tactile modalities engineered to reduce sleep latency and improve sleep architecture indices. Sound machines generate calibrated pink or brown noise spectra between 40-60 decibels to mask environmental disruptions and entrain circadian rhythms. Essential oils and herbal teas command mature margin pools in home use applications, while sleep masks with integrated biometric tracking represent the fastest-growing product type within the therapy sessions segment. Online retail channels are capturing disproportionate volume growth as direct-to-consumer brands bypass traditional pharmacy gatekeepers.
Regulatory Environment and Strategic Outlook
FDA oversight of software-as-a-medical-device sleep applications and EPA registration requirements for aromatherapy diffusers shape product development roadmaps and market access timelines in the United States. The Federal Trade Commission monitors advertising claims related to sleep improvement efficacy, creating compliance cost differentials between established manufacturers and new entrants. Stakeholders must monitor evolving reimbursement codes for non-invasive sleep interventions as payors recalibrate coverage policies for behavioral and technological alternatives to pharmaceutical sleep aids.
Market Dynamics
FDA guidance on over-the-counter sleep aid devices is compressing product development timelines while expanding addressable patient populations beyond prescription-dependent cohorts. This regulatory recalibration is forcing manufacturers to reengineer acoustic and thermal modalities for compliance with software-as-a-medical-device frameworks.
Growth Catalysts
- Germany's statutory health insurance expansion:Reimbursement criteria for sleep therapy devices now cover non-pharmacological interventions in pediatric outpatient departments, accelerating hospital procurement cycles.
- Pink noise engineering advances:Calibrated acoustic spectra between 40-60 decibels now entrain circadian rhythms with measurable sleep architecture improvements, driving clinical adoption.
- Biometric-responsive temperature modulation:Integrated sensors enable real-time thermal adjustment based on sleep stage detection, creating new premium product tiers.
Market Restraints
- Certified sleep technologist shortage:Workforce gaps in polysomnography certification are throttling manufacturing capacity expansion across device assembly lines.
- EPA registration timelines for aromatherapy diffusers:Pesticide device classification requirements add 18-24 months to market access for olfactory modality products.
- Component volatility in semiconductor supply:Biometric sensor chip shortages from concentrated Asian foundries disrupt production scheduling for connected sleep masks.
Strategic Opportunities
- Direct-to-consumer online channels:Digital-native brands bypass pharmacy gatekeepers to capture disproportionate volume growth in home-use acoustic devices.
- Behavioral sleep medicine integration:Cognitive behavioral therapy for insomnia protocols create bundled reimbursement opportunities for combined device-therapy programs.
- EU Medical Device Regulation harmonization:MDR conformity assessment mutual recognition agreements streamline multi-country market entry for thermal modulation systems.
Industry Challenges
- FTC advertising claim substantiation:Sleep improvement efficacy assertions require clinical trial documentation, elevating compliance costs for new entrants versus established manufacturers.
- Legacy health system integration:Hospital IT infrastructure incompatibility with biometric data streams from consumer-grade devices blocks enterprise procurement pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Soother Market |
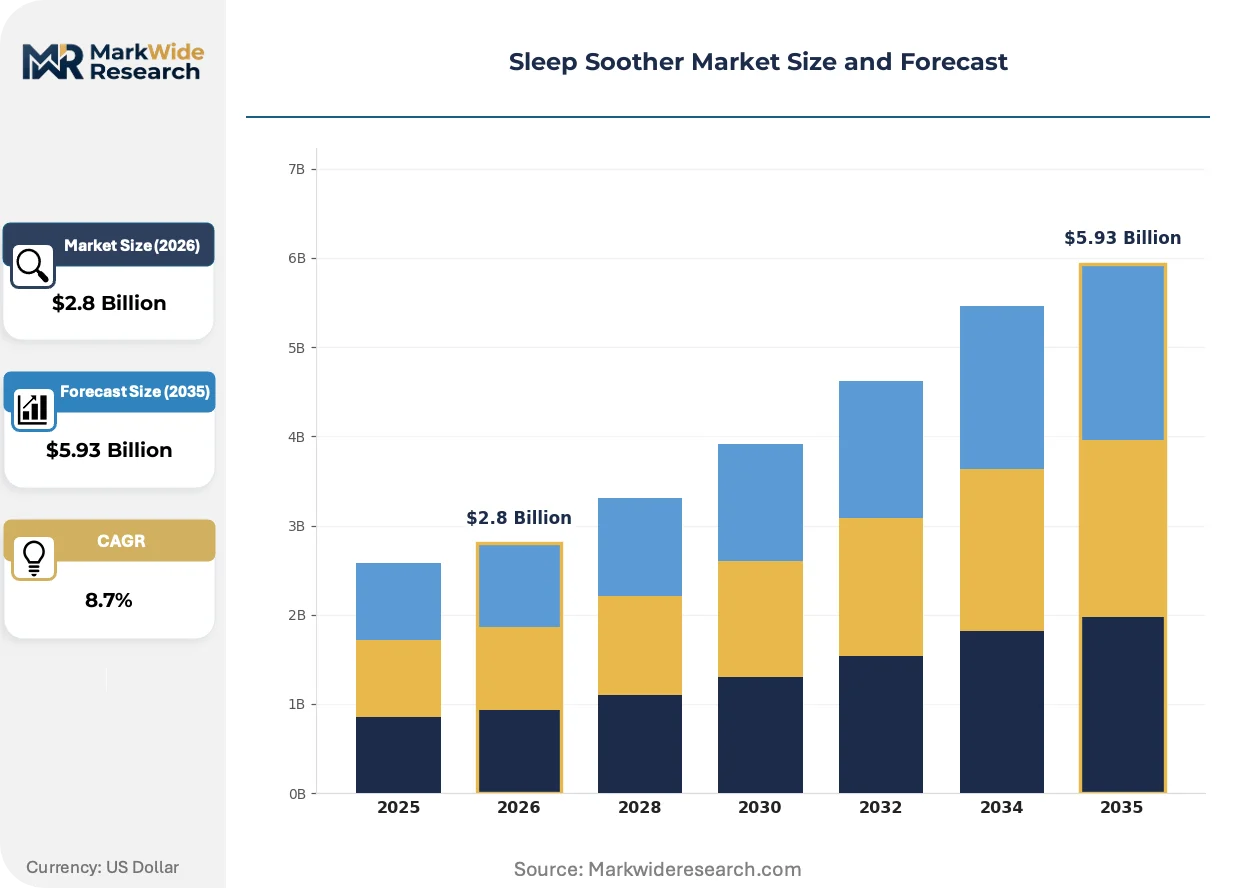
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Sound Machines, Sleep Masks, Herbal Teas Application: Home Use, Spa Services, Travel, Therapy Sessions End User: Individuals, Wellness Centers, Clinics, Corporates Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Supermarkets |
| Companies Covered | ResMed Inc., Koninklijke Philips N.V., Eight Sleep, Oura Health, Fitbit Inc., Tempur Sealy International, Inc., Fisher & Paykel Healthcare Corporation Limited, Smart Nora, Somnox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Soother Market Evolving Landscape
Technology convergence between consumer wellness and clinical sleep medicine is dissolving traditional category boundaries. Product architectures now straddle prescription and over-the-counter regulatory pathways simultaneously.
Biometric sleep tracking is decomposing the distinction between diagnostic and therapeutic devices. Sleep masks with integrated photoplethysmography and accelerometry now stream real-time data to clinical decision support systems. Hospital outpatient departments in Germany and the United States are piloting these dual-use products for remote patient monitoring programs. The technology is decomposing legacy reimbursement silos that previously separated diagnostic testing from therapeutic intervention.
EMA software-as-a-medical-device guidance harmonization with FDA precedent is compressing regulatory divergence across Atlantic markets. European manufacturers now design single technical files satisfying both jurisdictions' cybersecurity and clinical evidence requirements. Sleep application developers targeting pediatric populations face heightened scrutiny for data protection under GDPR Article 8 provisions. This convergence is accelerating first-mover advantage for firms with existing FDA 510(k) clearances.
Subscription service models for consumable sleep interventions are displacing perpetual ownership structures. Essential oil refill programs and algorithm-updated acoustic libraries generate recurring revenue from hardware-installed bases. Direct-to-consumer brands leverage this shift to improve customer lifetime value metrics versus traditional retail distribution. Germany's digital care act reimbursement pathways for app-based sleep coaching are validating this model in statutory health insurance markets.
Sleep Soother Market Segmentation
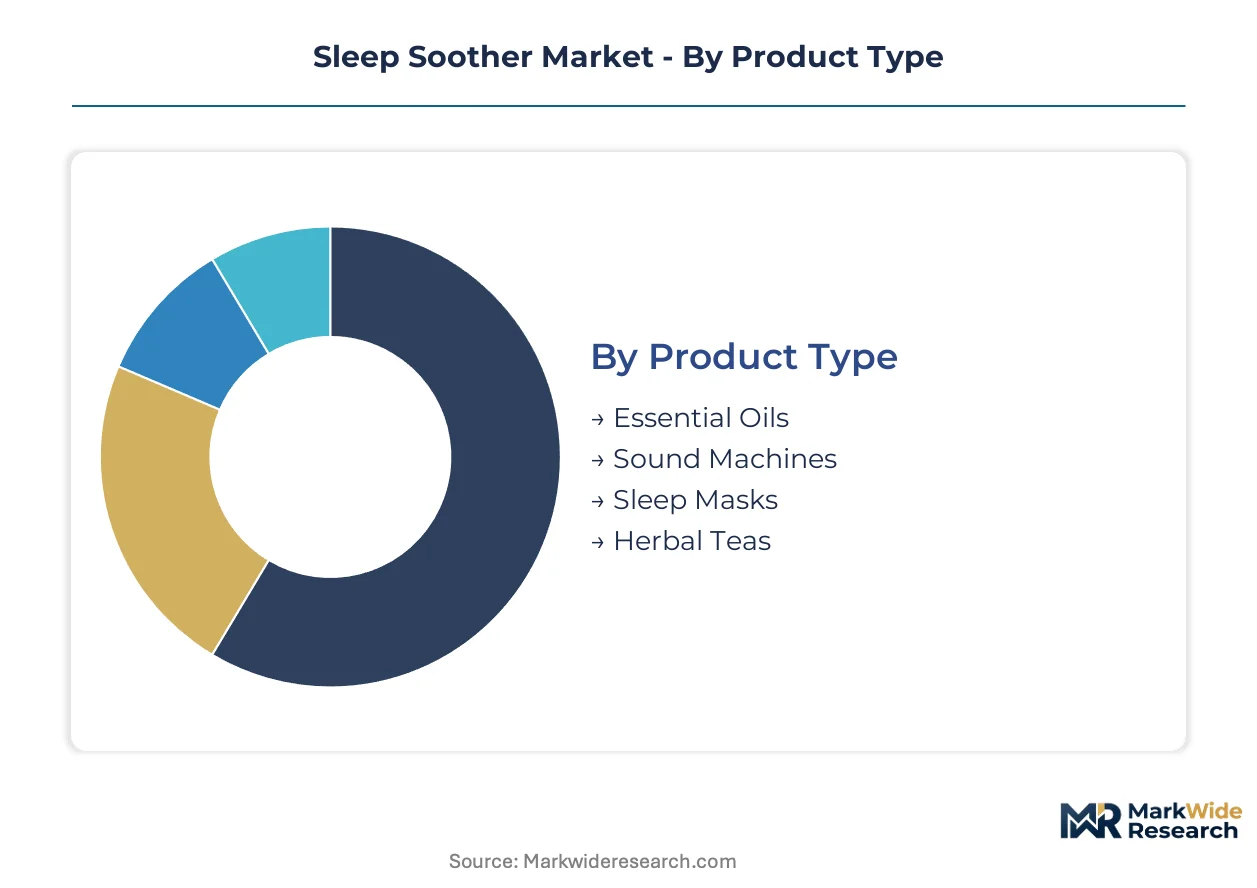
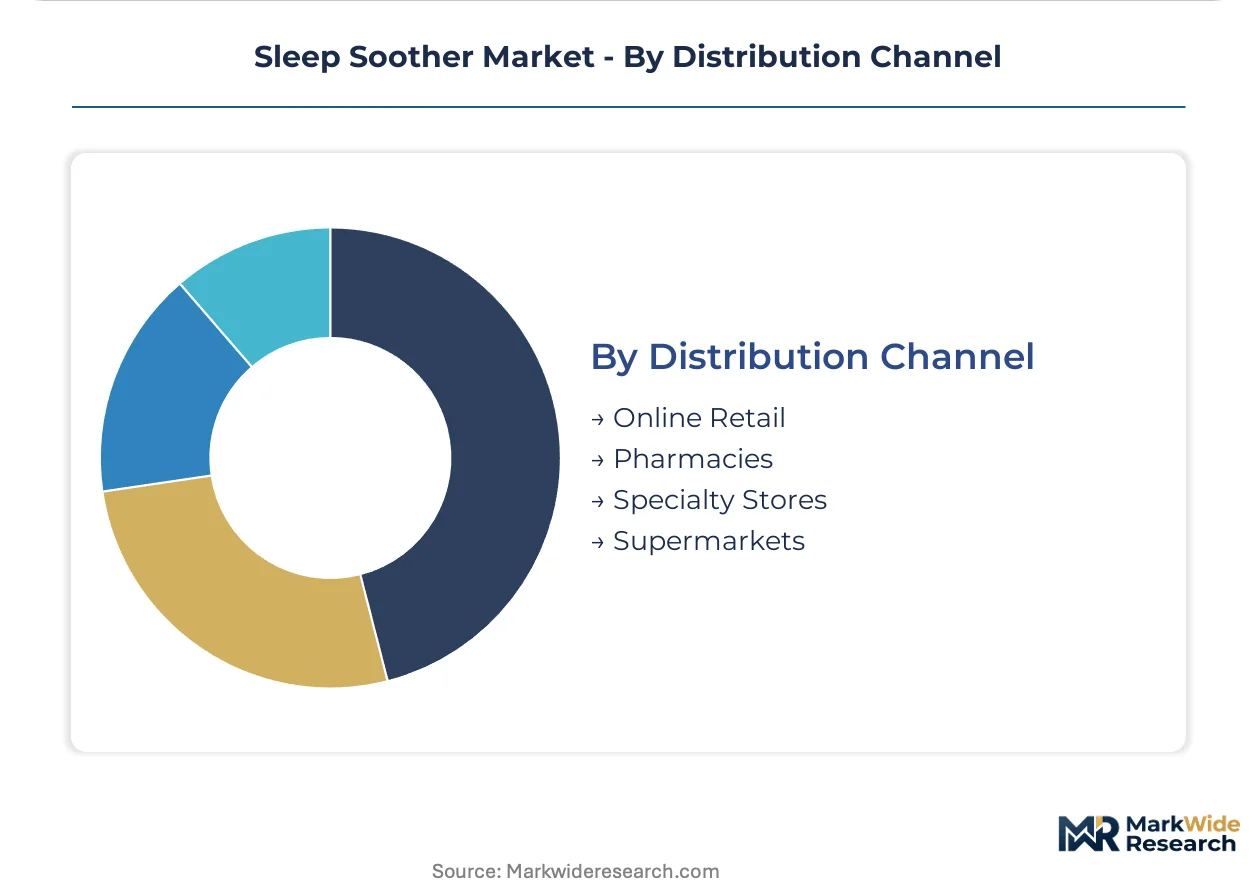
Sleep soother segmentation reveals divergent margin architectures across sensory modalities and channel economics. Product type stratification separates consumable replenishment models from durable hardware platforms, while distribution channel selection determines customer acquisition costs and lifetime value trajectories.
Product Type:
Premium margin pools concentrate in hardware systems with embedded software and sensor arrays, while consumable categories generate recurring revenue at lower per-unit profitability.
- Sound Machines:Calibrated acoustic devices generate pink or brown noise spectra between 40-60 decibels for circadian entrainment. Demand concentrates in pediatric hospital outpatient departments in Germany where statutory health insurance reimbursement now covers non-pharmacological sleep interventions.
- Sleep Masks:Biometric-responsive designs integrate photoplethysmography and accelerometry for real-time sleep stage detection and thermal adjustment. German and United States hospital systems are piloting these for remote patient monitoring programs, decomposing legacy reimbursement silos.
- Essential Oils:Aromatherapy formulations for diffusion command mature margin pools in home use applications with subscription refill programs displacing perpetual ownership.
- Herbal Teas:Botanical sleep aids represent the most accessible entry point for price-sensitive consumers through supermarket and pharmacy channels.
Sleep Masks holds installed capacity. Sound Machines is rotating up the share rankings.
Application:
Volume concentration follows channel access patterns, with institutional procurement cycles diverging sharply from impulse-driven consumer purchasing.
- Home Use:Direct-to-consumer brands bypass traditional pharmacy gatekeepers through online retail channels, capturing disproportionate volume growth in acoustic and thermal modalities. FDA over-the-counter sleep aid device guidance is expanding addressable populations beyond prescription-dependent cohorts.
- Therapy Sessions:Clinical deployment of biometric-tracking sleep masks is gaining share fastest as hospital IT infrastructure gradually accommodates consumer-grade device data streams. Pediatric sleep therapy programs represent a key end-use segment where adoption is accelerating.
- Spa Services:Olfactory and tactile modalities dominate professional wellness environments with bundled service pricing.
- Travel:Portable acoustic devices and compression sleep masks target transient sleep disruption in hospitality and aviation sectors.
Home Use holds installed capacity. Therapy Sessions is rotating up the share rankings.
End User:
Procurement authority and reimbursement eligibility create distinct customer archetypes with diverging price sensitivity and compliance requirements.
- Individuals:Direct purchasers drive volume through online retail channels with algorithm-updated acoustic libraries and essential oil subscription services improving customer lifetime value metrics.
- Clinics:Hospital outpatient departments require FDA software-as-a-medical-device compliance and HIPAA-aligned data handling for connected sleep mask procurement.
- Wellness Centers:Spa and holistic health facilities prioritize olfactory and tactile modalities with lower regulatory barriers than clinical-grade hardware.
- Corporates:Employer wellness programs represent an emerging procurement channel for sleep improvement interventions with occupational health budget alignment.
Individuals holds installed capacity. Clinics is rotating up the share rankings.
Distribution Channel:
Channel selection determines regulatory exposure and customer education requirements, with direct-to-consumer models compressing go-to-market timelines.
- Online Retail:Digital-native brands leverage bypass of pharmacy gatekeepers with subscription service models for consumable interventions and algorithm-updated acoustic libraries.
- Pharmacies:Traditional retail channels face FTC advertising claim substantiation requirements for sleep improvement efficacy assertions, elevating compliance costs versus established manufacturers.
- Specialty Stores:Curated sleep and wellness retailers provide tactile product evaluation for thermal modulation systems and biometric-responsive masks.
- Supermarkets:Mass-market channels concentrate herbal tea and entry-level essential oil distribution with impulse-driven purchasing patterns.
Supermarkets holds installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on over-the-counter sleep aid devices is reshaping product classification pathways in the United States, while Germany's statutory health insurance reimbursement expansion accelerates procurement cycles for pediatric sleep therapy programs. These regulatory shifts concentrate demand in North American and European markets with established reimbursement infrastructure.
United States
Pediatric sleep therapy programs in hospital outpatient departments drive institutional procurement of acoustic and thermal modalities. FDA software-as-a-medical-device frameworks compress development timelines for connected sleep masks with biometric tracking. The Boston-Cambridge corridor anchors clinical validation partnerships between device manufacturers and academic medical centers.
Germany
Statutory health insurance reimbursement for sleep therapy devices now covers non-pharmacological interventions, expanding addressable patient populations beyond prescription-dependent cohorts. EU Medical Device Regulation conformity assessment streamlines multi-country market entry for thermal modulation systems. Bavaria's medical technology cluster concentrates R&D activity for biometric-responsive temperature control systems.
Japan
Aging demographics and workplace wellness mandates elevate employer-sponsored sleep intervention programs. METI standards for consumer health devices shape product safety requirements for home-use acoustic systems. The Kanto region around Tokyo hosts validation trials for circadian entrainment technologies in corporate wellness settings.
United Kingdom
NHS pilot programs for digital therapeutics create procurement pathways for app-integrated sleep coaching platforms. MHRA alignment with FDA software-as-a-medical-device precedent reduces regulatory divergence for transatlantic product launches. London's health technology cluster attracts venture funding for direct-to-consumer sleep mask startups.
Australia
TGA approval pathways for wellness-to-medical device transitions enable market access for biometric-tracking sleep masks. Private health insurance coverage for sleep therapy devices lags statutory systems, creating price-sensitive consumer segments. Melbourne's biomedical research precinct hosts clinical trials for pink noise engineering applications.
Sleep Soother Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the sleep soother market. Established respiratory device manufacturers leverage clinical channel relationships and regulatory expertise, while digital-native entrants capture direct-to-consumer volume through subscription service models. Three archetypes dominate: vertically integrated medical device conglomerates, venture-backed wellness technology startups, and component specialists with captive sensor production. Competitive moves concentrate on M&A for biometric sensor capabilities and strategic partnerships with behavioral sleep medicine providers.
Among established medical device manufacturers, ResMed Inc. and Koninklijke Philips N.V. exemplify the vertically integrated archetype with in-house production of masks and connected device ecosystems. Eight Sleep occupies a position within the venture-backed tier, representing technology leadership in temperature modulation systems. These three companies anchor the competitive structure, with ResMed Inc. and Koninklijke Philips N.V. leveraging regulatory clearance portfolios and Eight Sleep exemplifying the direct-to-consumer growth vector.
| Leading Market Players |
|---|
| ResMed Inc. |
| Koninklijke Philips N.V. |
| Eight Sleep |
| Oura Health |
| Fitbit Inc. |
| Tempur Sealy International, Inc. |
| Fisher & Paykel Healthcare Corporation Limited |
| Smart Nora |
| Somnox |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four month EPA registration timelines for aromatherapy diffusers compress inventory turnover for olfactory modality manufacturers while amplifying pricing power for established players with cleared regulatory portfolios. Semiconductor lead-time volatility for biometric sensor chips further stratifies margin capture between integrated device manufacturers and component-dependent assemblers.
Pricing Analysis
German statutory health insurance reimbursement spreads versus United States out-of-pocket purchasing create a 40-60 decibel acoustic device price band that widens with FDA software-as-a-medical-device compliance tiers. Three-tier pricing structure across premium, standard, and economy levels separates biometric-responsive thermal systems from calibrated sound machines and entry-level herbal formulations. Cost compression in consumable categories intensifies as essential oil subscription programs multiply. Individual direct-to-consumer buyers exhibit highest price sensitivity; German hospital outpatient departments demonstrate lowest.
Supply Chain Analysis
Strategic stockpiling of semiconductor inventory dominates supply planning for connected sleep mask manufacturers facing 18-month biometric sensor chip lead times from concentrated Asian foundries. Component sourcing draws from Taiwan for photoplethysmography sensors, China for thermal modulation hardware, and Germany for precision acoustic engineering. Single-source vulnerability in semiconductor fabrication threatens production scheduling. Distribution runs through direct-to-consumer online channels for hardware platforms and pharmacy networks for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm-updated acoustic libraries and essential oil subscription services expand recurring revenue faster than durable hardware sales, positioning the market as a service-attach opportunity where customer lifetime value metrics favor digital-native entrants over traditional retail distribution.
For Market Incumbents: Fortify margin control through backward integration into mask and sensor production to offset component volatility from Asian foundries. Invest in FDA software-as-a-medical-device certification portfolios to defend against direct-to-consumer brands bypassing pharmacy gatekeepers. Priority lever: captive supply of biometric sensor arrays. For New Entrants and Emerging Players: FDA 510(k) clearance fast-tracks compress regulatory timelines for biometric-tracking sleep masks targeting German hospital outpatient departments. Pediatric sleep therapy programs represent the most penetrable segment with statutory health insurance reimbursement expansion. Go-to-market angle: bundled device-therapy programs aligned with cognitive behavioral therapy for insomnia protocols. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription service models for consumable interventions displace perpetual ownership structures across acoustic and olfactory modalities. Target acquisition archetype: digital-native brands with algorithm-updated content libraries and established direct-to-consumer customer bases. Signal to watch: reimbursement code expansions for non-invasive sleep interventions in statutory health insurance markets.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Sensor Backward Integration | Captive photoplethysmography chip supply from Taiwan foundries insulates margin control against semiconductor volatility. |
| FDA Software-as-a-Medical-Device Submission | 510(k) clearance pathway accelerates market access for connected sleep masks in United States hospital systems. |
| Essential Oil Subscription Program Launch | Recurring refill revenue from hardware-installed bases improves customer lifetime value versus transactional retail. |
| German Hospital System Partnership | Statutory health insurance reimbursement alignment secures procurement pathways for pediatric sleep therapy programs. |
| Pink Noise Algorithm Licensing | Content library monetization extends revenue capture beyond hardware margins in direct-to-consumer channels. |
Research Methodology
The analysis maps acoustic, thermal, olfactory, and tactile modality sub-sectors, each validated through sleep technologists, biomedical engineers, hospital purchasing committee members, and direct-to-consumer brand executives. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EPA pesticide device registrations, German statutory health insurance reimbursement codes, and EU Medical Device Regulation technical files. Bottom-up product-type volume builds triangulate against top-down end-use demand estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models sensory modality, application setting, procurement authority, and distribution channel dimensions. CAGRs derive from regression analysis of historical reimbursement expansion patterns and technology adoption curves. Forecast inputs include semiconductor lead-time indices and regulatory clearance velocity metrics.
The analysis sits within stated boundaries; outcomes outside FDA software-as-a-medical-device guidance stability or German statutory health insurance reimbursement continuity would require recalibration. Forecasts reflect documented assumptions regarding sleep technologist workforce growth and biometric sensor supply normalization. Revision becomes warranted when EPA registration timelines for aromatherapy devices exceed 30 months or when semiconductor fabrication concentration crosses geopolitical risk thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Oral Sleep Apnea Market
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Anti-Snoring Treatment Market
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Short Sleep Syndrome Treatment Market
Sleep Medicine
Nasal Pillow Mask Market
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market
Sleep Medicine
Sleep Disorder Market
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Asia Pacific Sleep Tech Devices Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Sleep Studies Market