
 Idiopathic Hypersomnia (IH) Treatment Market | 2026-2036
Idiopathic Hypersomnia (IH) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Idiopathic Hypersomnia (IH) Treatment Market Foresight
Specialty pharmacy distribution is reconfiguring how patients with idiopathic hypersomnia access reimbursed therapies. Jazz Pharmaceuticals controls the sodium oxybate category through its established risk evaluation and mitigation strategy infrastructure. Harmony Biosciences Holdings anchors the modafinil-adjacent segment with its pitolisant franchise. Takeda Pharmaceutical Company Limited leverages its rare disease commercial footprint to compete in niche sleep disorder markets across multiple geographies.
Idiopathic hypersomnia treatment encompasses pharmacological interventions targeting excessive daytime sleepiness and prolonged nighttime sleep without identifiable cause, with sodium oxybate requiring controlled substance scheduling and specialized dispensing protocols due to its gamma-hydroxybutyrate composition. The primary purpose is restoring functional wakefulness in patients who fail to achieve normal alertness despite adequate sleep duration. Stimulants occupy the largest volume share as first-line prescribing persists among general neurologists unfamiliar with newer mechanisms. Sodium oxybate concentrates margin pools given its orphan pricing structure and restricted distribution requirements. Homecare settings represent the fastest-growing delivery channel as oral formulations enable patient self-administration and reduce institutional dependency.
FDA oversight through REMS programs and DEA scheduling shapes product development economics and patient access timelines for controlled substance candidates. EMA's orphan medicinal product designation and national health technology assessment processes in Germany and France determine reimbursement thresholds across European markets. The European Medicines Agency's centralized procedure influences parallel trade patterns and pricing corridors. Stakeholders must monitor how FDA guidance on novel endpoints for excessive sleepiness could reshape clinical trial design and label expansion opportunities for emerging mechanisms.
Market Dynamics
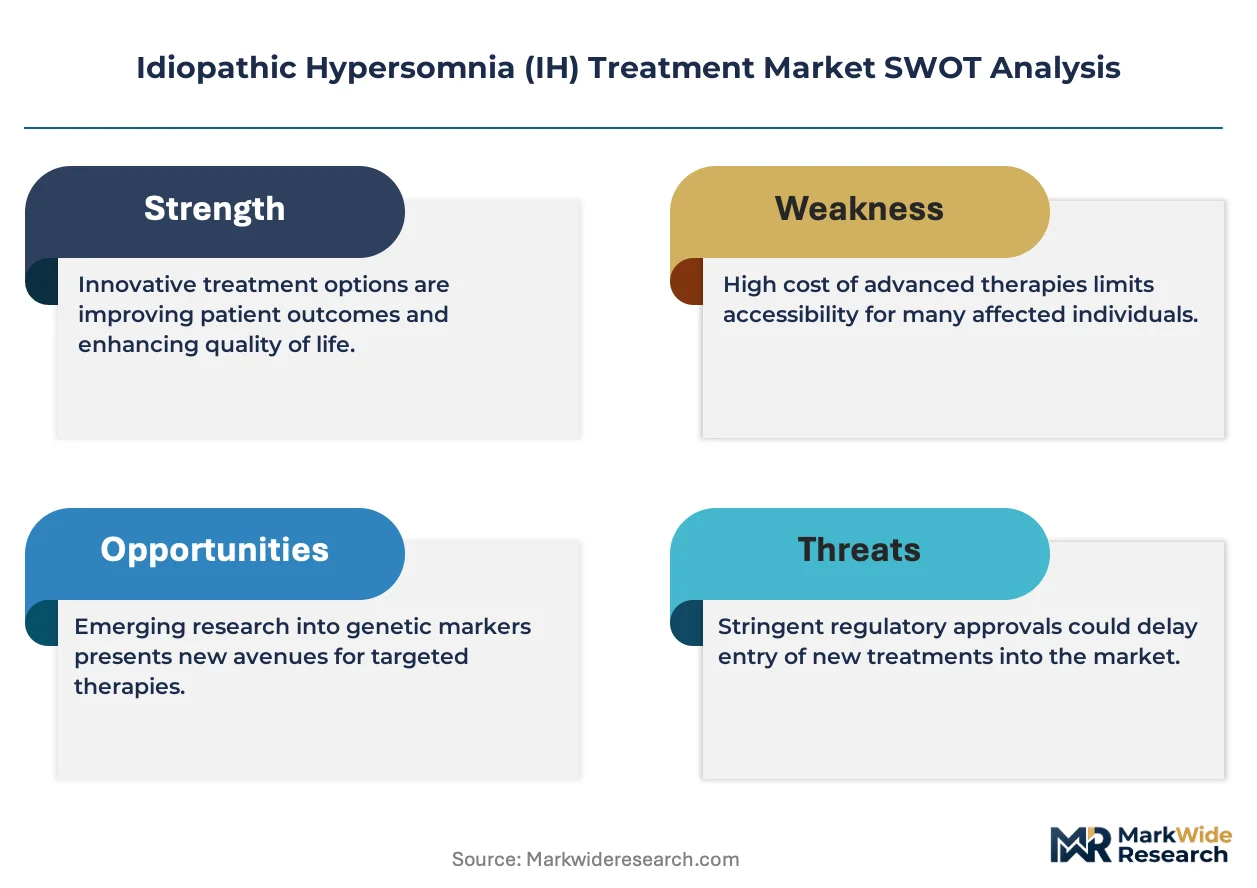
The orphan drug designation pathway is compressing development timelines for novel wakefulness-promoting agents while simultaneously concentrating commercial infrastructure around REMS-compliant distribution networks.
Growth Catalysts
- FDA Orphan Drug Incentives:The seven-year market exclusivity and tax credits for clinical trials accelerate investment in sodium oxybate alternatives and novel mechanisms targeting excessive daytime sleepiness.
- Specialty Neurology Clinic Expansion:Academic medical centers in the United States are building dedicated sleep medicine programs that streamline diagnosis-to-treatment pathways for idiopathic hypersomnia patients.
- Patient Advocacy Mobilization:Condition-specific organizations are elevating recognition among primary care physicians and driving referrals to board-certified sleep specialists.
Market Restraints
- Controlled Substance Scheduling:Sodium oxybate's Schedule III DEA classification imposes specialized dispensing protocols, limited pharmacy networks, and elevated compliance costs that constrain patient access.
- Diagnostic Code Limitations:The absence of distinct ICD-10 billing codes for idiopathic hypersomnia complicates prior authorization processes and reimbursement negotiations with commercial payers.
- Gamma-Hydroxybutyrate Supply Concentration:Single-source API manufacturing for sodium oxybate creates vulnerability to production disruptions and quality enforcement actions.
Strategic Opportunities
- Homecare Administration Models:Oral formulations enabling patient self-administration are displacing institutional sleep center dependency and expanding addressable geography beyond major metropolitan clusters.
- EMA Orphan Medicinal Product Pathway:Parallel designation in Germany and France unlocks centralized reimbursement negotiations and cross-border prescription mobility.
- Novel Endpoint Validation:FDA guidance on objective wakefulness metrics creates label expansion potential for agents targeting sleep inertia and cognitive performance.
Industry Challenges
- Sleep Medicine Specialist Shortage:Fellowship-trained physicians capable of distinguishing idiopathic hypersomnia from narcolepsy and mood disorders remain concentrated in coastal academic centers.
- REMS Infrastructure Complexity:Risk evaluation and mitigation strategy compliance requires certified pharmacies, prescriber enrollment, and patient registry maintenance that fragments commercial operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Idiopathic Hypersomnia (IH) Treatment Market |
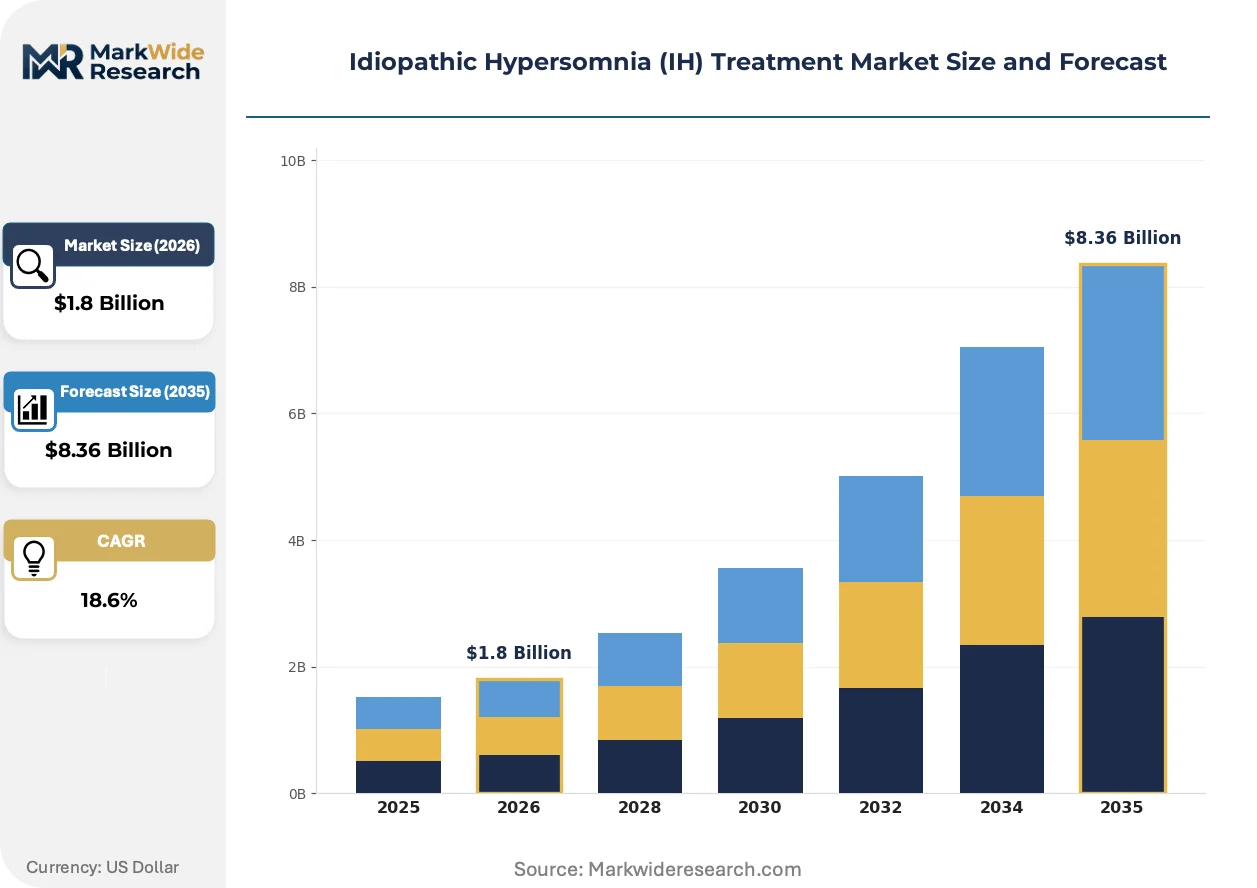
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulants, Modafinil, Sodium Oxybate, Antidepressants Delivery Mode: Oral, Intravenous, Sublingual, Topical End User: Hospitals, Clinics, Homecare Settings, Long-term Care Facilities Application: Chronic Sleep Disorders, Sleep Deprivation, Excessive Daytime Sleepiness, Others |
| Companies Covered | Harmony Biosciences Holdings, BIOPROJET, Jazz Pharmaceuticals, Zevra Therapeutics, Theranexus, Takeda Pharmaceutical Company Limited, Avadel Pharmaceuticals, Pfizer, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Idiopathic Hypersomnia (IH) Treatment Market Shifts & Advancements
Wakefulness-promoting pharmacology is diversifying beyond traditional stimulant classes as histamine H3 antagonists and orexin pathway modulators enter late-stage development pipelines.
Histamine H3 receptor inverse agonists are advancing through Phase III programs with differentiated cardiovascular safety profiles compared to conventional sympathomimetics. Sleep medicine specialists in academic medical centers are prioritizing these mechanisms for patients with comorbid hypertension or anxiety disorders. The technology is hybridizing clinical trial endpoints by combining objective polysomnography metrics with patient-reported functional outcomes.
The FDA's 2023 guidance on novel endpoints for excessive sleepiness disorders is reshaping protocol design for registrational studies. Sponsors must now demonstrate sustained wakefulness across circadian phases rather than single timepoint improvements. This regulatory evolution most directly impacts development programs targeting the maintenance of wakefulness test as a primary endpoint.
Specialty pharmacy distribution is displacing traditional retail channels for controlled substance therapies. Patients now receive coordinated medication delivery through REMS-certified hubs that manage titration protocols and adverse event monitoring. This channel transformation is most advanced in the United States where consolidated payer formularies drive exclusive network arrangements.
Idiopathic Hypersomnia (IH) Treatment Market Segmentation
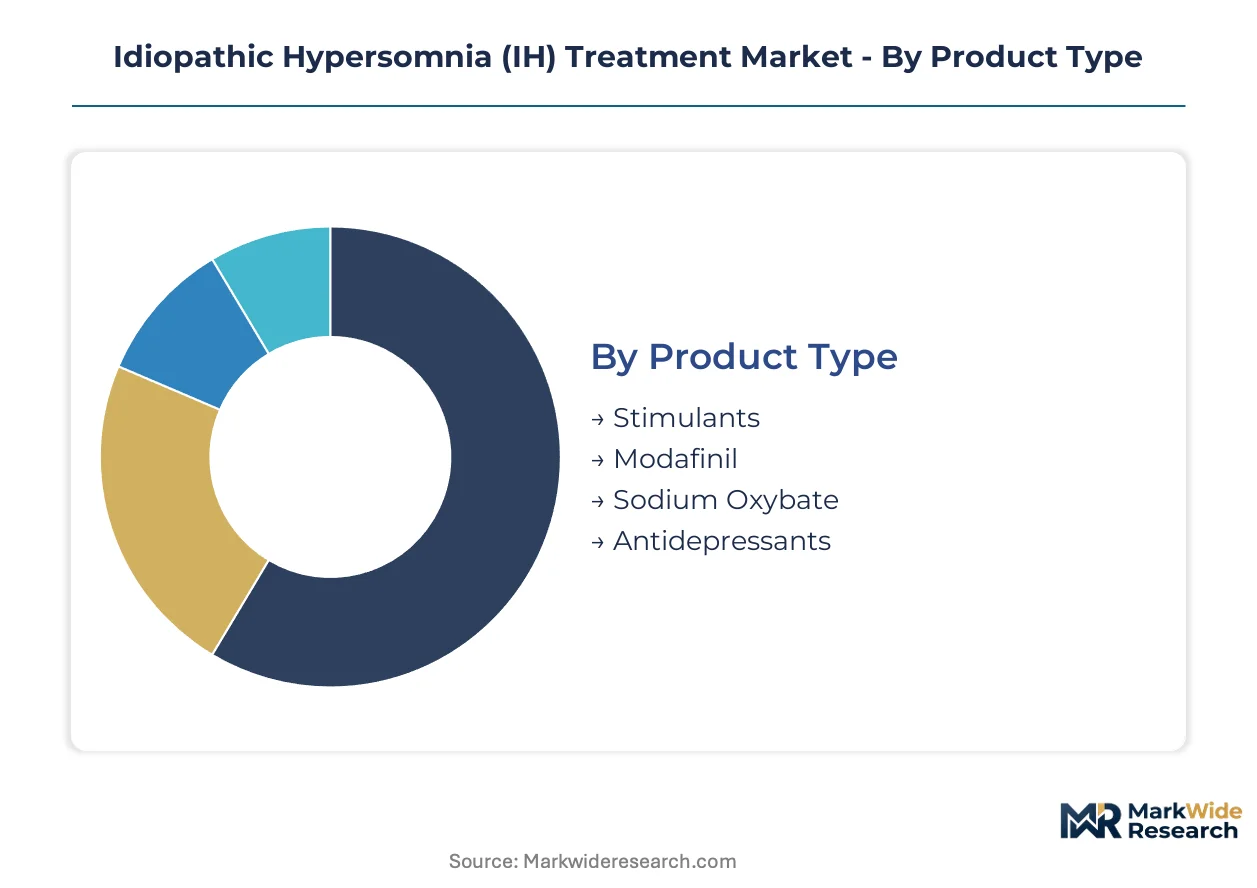
Segmentation in idiopathic hypersomnia treatment reveals how regulatory frameworks, patient acuity, and administration settings fragment commercial opportunity. Each dimension carries distinct reimbursement logic and infrastructure requirements that shape go-to-market economics.
Product Type:
Mature stimulant formulations dominate prescribing volume while novel mechanisms reshape the maturity spectrum across pharmacological classes.
- Stimulants:Traditional sympathomimetic compounds including methylphenidate and amphetamine derivatives constitute the established first-line arsenal. General neurologists in the United States continue initiating therapy with these agents due to familiarity and broad payer coverage, though cardiovascular monitoring requirements limit use in comorbid populations.
- Sodium Oxybate:The gamma-hydroxybutyrate formulation operates under DEA Schedule III constraints with mandatory REMS enrollment, specialized pharmacy networks, and restricted distribution. Its orphan drug pricing structure and consolidated manufacturing concentrate margin capture despite patient access friction from controlled substance protocols.
- Modafinil:Wakefulness-promoting agent with established efficacy profiles and generic availability that erodes branded revenue potential while maintaining substantial prescription volume.
- Antidepressants:Off-label utilization for sleep inertia and mood comorbidities, particularly in European markets where EMA pathways for formal indication expansion remain under exploration.
Stimulants handle the majority of throughput; sodium oxybate is the fastest mover on share.
Delivery Mode:
Patient self-administration capabilities are redistributing volume across administration routes, with oral formulations capturing the cost-to-convenience optimization.
- Oral:Tablet and liquid formulations enable home-based therapy initiation and titration without institutional dependency. FDA-approved sodium oxybate oral solutions and pitolisant tablets anchor this channel's expansion across United States specialty pharmacy networks.
- Intravenous:Reserved for acute decompensation or perioperative management in hospital settings where rapid onset and controlled bioavailability override convenience considerations.
- Sublingual:Emerging absorption pathway for patients with gastrointestinal comorbidities or those requiring rapid onset without first-pass metabolism, though commercial availability remains limited.
- Topical:Experimental transdermal delivery mechanisms in early development for patients with swallowing difficulties or those seeking steady-state plasma levels without peak-trough fluctuations.
Oral delivery commands the volume base; sublingual administration is climbing the fastest on patient preference metrics.
End User:
Site-of-care migration patterns are fragmenting prescribing authority between institutional specialists and community-based management.
- Homecare Settings:REMS-certified specialty pharmacies coordinate direct-to-patient delivery, adverse event monitoring, and prescriber communication for controlled substance therapies. This channel eliminates geographic barriers to access for patients outside major metropolitan clusters.
- Hospitals:Academic medical centers with dedicated sleep medicine programs handle complex diagnostic differentiation, comorbid psychiatric presentations, and therapy initiation for refractory cases requiring polysomnography confirmation.
- Clinics:Board-certified sleep medicine specialists in ambulatory settings manage stable patients through maintenance protocols and annual reassessment.
- Long-term Care Facilities:Skilled nursing environments address elderly populations with polypharmacy considerations and fall risk profiles that complicate stimulant selection.
Homecare settings are expanding most quickly; hospitals retain the highest acuity concentration.
Application:
Diagnostic specificity determines reimbursement pathway viability and clinical trial endpoint selection across indication categories.
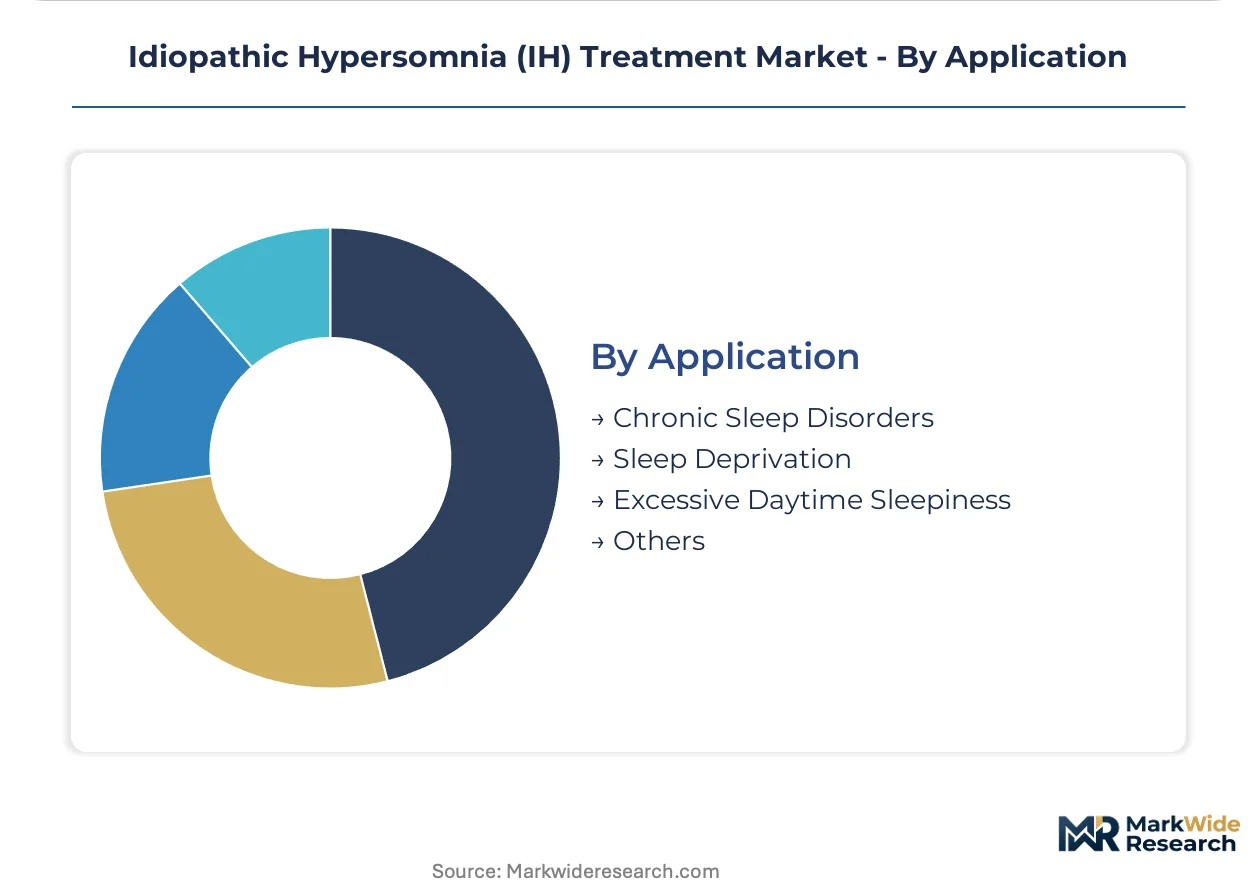
- Excessive Daytime Sleepiness:Primary symptomatic target for all pharmacological interventions, with FDA guidance mandating sustained wakefulness demonstration across circadian phases rather than single timepoint improvement.
- Chronic Sleep Disorders:Encompasses idiopathic hypersomnia with prolonged nighttime sleep duration, sleep inertia, and non-restorative sleep architecture distinct from narcolepsy.
- Sleep Deprivation:Secondary or comorbid presentations where IH treatment overlaps with circadian rhythm interventions and behavioral modification protocols.
- Others:Emerging indications including cognitive performance maintenance and shift work adaptation where mechanistic overlap creates label expansion potential.
Excessive daytime sleepiness anchors the indication base; chronic sleep disorders are gaining share fastest on diagnostic code refinement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and REMS infrastructure anchor the United States as the dominant geography, while EMA pathways and national health technology assessments shape European access timelines. Diagnostic code refinement and patient advocacy concentration drive regional variation in treatment penetration.
United States
Specialty neurology clinic expansion at academic medical centers in Boston, New York, and San Francisco streamlines diagnosis-to-treatment pathways. FDA REMS programs and DEA Schedule III scheduling for sodium oxybate impose specialized dispensing protocols that concentrate commercial infrastructure around certified pharmacy networks. The REMS-certified hub model eliminates geographic barriers for patients outside major metropolitan clusters.
Germany
Federal Institute for Drugs and Medical Devices (BfArM) oversight and G-BA health technology assessment processes determine reimbursement thresholds for wakefulness-promoting agents. EMA orphan medicinal product designation unlocks centralized pricing negotiations that parallel national code refinement efforts. The Munich and Berlin sleep medicine centers anchor diagnostic differentiation capacity for complex presentations.
France
ANSM regulatory frameworks and HAS evaluation procedures shape market access for novel mechanisms targeting excessive daytime sleepiness. EMA centralized procedure influences cross-border prescription mobility and pricing corridors across European markets. The Paris academic hospital network concentrates fellowship-trained sleep medicine specialists capable of distinguishing idiopathic hypersomnia from narcolepsy.
Japan
PMDA orphan drug designation and Ministry of Health, Labour and Welfare reimbursement listings accelerate development timelines for histamine H3 antagonists. National health insurance price adjustment mechanisms create predictable revenue corridors for approved therapies. The Tokyo and Osaka metropolitan clusters host the majority of board-certified sleep medicine specialists and polysomnography infrastructure.
United Kingdom
NICE technology appraisal processes and NHS England specialized commissioning frameworks determine access to sodium oxybate and pitolisant therapies. MHRA post-Brexit regulatory autonomy maintains alignment with EMA orphan pathways while enabling independent label expansion decisions. The London-Southeast corridor concentrates sleep medicine fellowship programs and tertiary referral networks.
Idiopathic Hypersomnia (IH) Treatment Market Competitive Landscape
Orphan drug specialists and diversified rare disease pharmaceutical companies split the market structure, with controlled substance infrastructure requirements creating natural segmentation. The competitive terrain concentrates around REMS-compliant distribution capabilities and specialty pharmacy network relationships. Three archetypes dominate: single-product biotechs with orphan focus, diversified rare disease platforms leveraging sleep disorder adjacencies, and established CNS players with wakefulness-promoting portfolios. Competitive moves center on M&A for REMS infrastructure and strategic partnerships for European market access.
Within the orphan drug specialist tier, Jazz Pharmaceuticals and Harmony Biosciences Holdings exemplify contrasting infrastructure strategies. Jazz anchors the sodium oxybate category through established controlled substance distribution networks, while Harmony occupies the modafinil-adjacent segment with pitolisant franchise development. Takeda Pharmaceutical Company Limited represents the diversified rare disease archetype, leveraging cross-therapeutic area commercial footprints to compete in niche sleep disorder markets. Zevra Therapeutics and Avadel Pharmaceuticals sit within the emerging mechanism development tier, targeting novel endpoints and administration improvements.
| Leading Market Players |
|---|
| Harmony Biosciences Holdings |
| BIOPROJET |
| Jazz Pharmaceuticals |
| Zevra Therapeutics |
| Theranexus |
| Takeda Pharmaceutical Company Limited |
| Avadel Pharmaceuticals |
| Pfizer |
| Teva Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
Single-source gamma-hydroxybutyrate API manufacturing in the United States concentrates upstream control, directing margin capture toward REMS-certified specialty pharmacy networks that manage sodium oxybate distribution downstream. This feedstock concentration creates pricing power asymmetries between controlled substance manufacturers and generic stimulant producers.
Pricing Analysis
United States orphan drug pricing for sodium oxybate sits multiple tiers above European reimbursement ceilings negotiated through EMA centralized procedures. Pricing stratifies across REMS-complex premium, branded standard, and generic economy tiers based on controlled substance scheduling burden and FDA exclusivity status. Cost compression in the stimulant segment intensifies as methylphenidate and amphetamine generics erode branded revenue. Academic medical centers and specialty neurology clinics exhibit lowest price sensitivity due to institutional reimbursement pathways; community-based general neurologists face highest sensitivity from prior authorization friction.
Supply Chain Analysis
Gamma-hydroxybutyrate sodium salt API production anchors in the United States with secondary manufacturing capacity in Italy and Switzerland for European market compliance. Finished dosage form manufacturing draws from controlled substance facilities in the United States, Ireland, and Japan, with pitolisant API sourcing from French specialty chemical producers. Single-source vulnerability pervades the sodium oxybate supply base where DEA quota restrictions limit qualified manufacturers. Distribution runs through REMS-certified specialty pharmacy hubs in the United States and hospital-centric procurement channels in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around consolidated payer formularies and specialty pharmacy networks that dictate access terms, fragmenting prescribing authority away from individual physicians toward institutional procurement committees.
For Market Incumbents: Insulate sodium oxybate margin pools by deepening REMS infrastructure moats and securing DEA manufacturing quota allocations against potential second entrants. Counter histamine H3 antagonist substitution threats through prescriber education investments in academic medical centers. Prioritize formulary placement defense through outcomes-based contracting with national payers. For New Entrants and Emerging Players: Establish a beachhead in the sublingual and novel formulation segment where patient preference differentiation escapes direct price competition with oral generic stimulants. Target European markets through EMA orphan medicinal product designation where centralized reimbursement negotiations reduce fragmentation. Deploy direct-to-patient engagement models that bypass saturated specialty pharmacy networks. For Investors and Strategic Acquirers: Capital is best deployed toward REMS infrastructure platforms and rare disease commercial footprints that accelerate time-to-revenue for pipeline assets across sleep disorder indications. Long-term viability hinges on regulatory exclusivity durability rather than patent estate alone. Watch FDA guidance evolution on novel wakefulness endpoints as the inflection signal for mechanism-class revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Expansion | DEA-compliant distribution networks create defensible moats around controlled substance therapies. |
| EMA Orphan Designation Pursuit | Centralized European reimbursement negotiations reduce national pricing fragmentation. |
| Histamine H3 Pipeline Advancement | Novel mechanisms differentiate cardiovascular safety profiles from sympathomimetic stimulants. |
| Specialty Pharmacy Partnership | Exclusive network arrangements secure patient access and adverse event monitoring capabilities. |
| Novel Endpoint Clinical Trial Design | FDA guidance alignment on sustained wakefulness metrics enables label expansion opportunities. |
Research Methodology
Operator-level perspectives from sleep medicine specialists, REMS program administrators, specialty pharmacy procurement directors, and payer formulary managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA REMS documents, EMA orphan designation filings, ClinicalTrials.gov protocols, and national health technology assessment reports. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation cross-checked segmentation outputs.
Scenario-bracketing across regulatory approval timelines, reimbursement negotiation outcomes, and generic entry assumptions shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include pharmacological class, delivery mode, end-user setting, and regional regulatory cluster. CAGRs derived from patent expiry schedules, orphan exclusivity windows, and diagnostic code adoption curves. Pipeline progression probabilities and label expansion scenarios informed mechanism-specific growth trajectories.
Stress conditions across DEA scheduling reclassification, single-source API disruption, and diagnostic code refinement delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement negotiation success rates. Cross-checking against IQVIA prescription audit data and Symphony Health claims benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Dental Sleep Medicine Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Sleep Study Equipment Market
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Hypoventilation Management Market
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Americas Insomnia Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Non-Wearable Sleep Tracker Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Anti-Snoring Treatment Market
Sleep Medicine
Short Sleep Syndrome Treatment Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Chronotherapy Market