
 Dental Wax Market | 2026-2036
Dental Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Wax Market Analysis
A shift from single-source paraffin procurement to multi-source synthetic and natural wax blending is pivoting supply strategies across the industry. Kerr Corporation leverages captive R&D facilities in North America to sustain formulation leadership in bite registration compounds. Bilkim Ltd. Co anchors its competitive stance through backward integration into refined beeswax supply chains. Metrodent Ltd differentiates via specialized utility wax production for orthodontic appliance fabrication.
Dental wax comprises thermoplastic compounds—typically paraffin, beeswax, carnauba, or synthetic polymers formulated with oils and resins—engineered to precise melting points between 45°C and 75°C for moldability and dimensional stability in crown, bridge, and denture fabrication. Modeling wax commands the largest volume share due to its ubiquity in prosthodontic pattern work, while synthetic wax formulations represent the fastest-expanding material category as laboratories seek batch-to-batch consistency beyond natural wax variability. Dental laboratories absorb the dominant share of end-user demand, though orthodontic clinics are gaining traction as clear aligner workflows expand indirect bonding applications.
ISO 15854 governs dental baseplate wax dimensional stability and biocompatibility, while FDA 21 CFR 872.6890 classifies dental wax as a Class I medical device subject to general controls rather than premarket review. The EU Medical Device Regulation (MDR) reclassification of certain dental laboratory materials is elevating documentation burdens for wax exporters serving European dental laboratories. Stakeholders must monitor evolving material disclosure requirements under REACH and emerging state-level chemical transparency laws in the US as they calibrate product portfolios between natural and synthetic formulations.
Market Dynamics
CAD/CAM restoration workflows are compressing traditional wax pattern timelines while elevating precision requirements for thermoplastic compounds used in crown and bridge fabrication.
Growth Catalysts
- EU MDR reclassification:Elevated documentation standards for dental laboratory materials are accelerating laboratory consolidation toward ISO 15854-certified wax suppliers capable of batch traceability.
- Clear aligner indirect bonding:Orthodontic clinics are expanding utility wax consumption for bracket positioning templates, creating incremental demand beyond prosthodontic applications.
- German dental technology clusters:Concentrated precision manufacturing in Cologne and Munich sustains specialized modeling wax R&D and localized supply security.
Market Restraints
- Natural wax input volatility:Refined beeswax and carnauba supply fluctuations from climate-impacted regions create formulation cost instability for blended compounds.
- REACH disclosure expansion:Evolving chemical transparency mandates in the EU compound compliance burdens for multi-component thermoplastic formulations.
- Digital impression substitution:Intraoral scanning advancement reduces physical pattern demand in anterior crown workflows.
Strategic Opportunities
- India dental laboratory expansion:Underpenetrated prosthodontic outsourcing hubs present volume growth for standardized synthetic wax formulations.
- State-level US chemical laws:Emerging transparency requirements in California and New York create first-mover advantage for preemptive material disclosure.
- Synthetic-natural hybrid convergence:Precision polymer engineering combined with modified natural waxes enables performance-tier differentiation.
Industry Challenges
- CAD/CAM technician reskilling:Traditional wax carving expertise scarcity complicates hybrid digital-physical workflow staffing.
- Dual certification timelines:Simultaneous FDA 21 CFR 872.6890 and EU MDR compliance extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Wax Market |
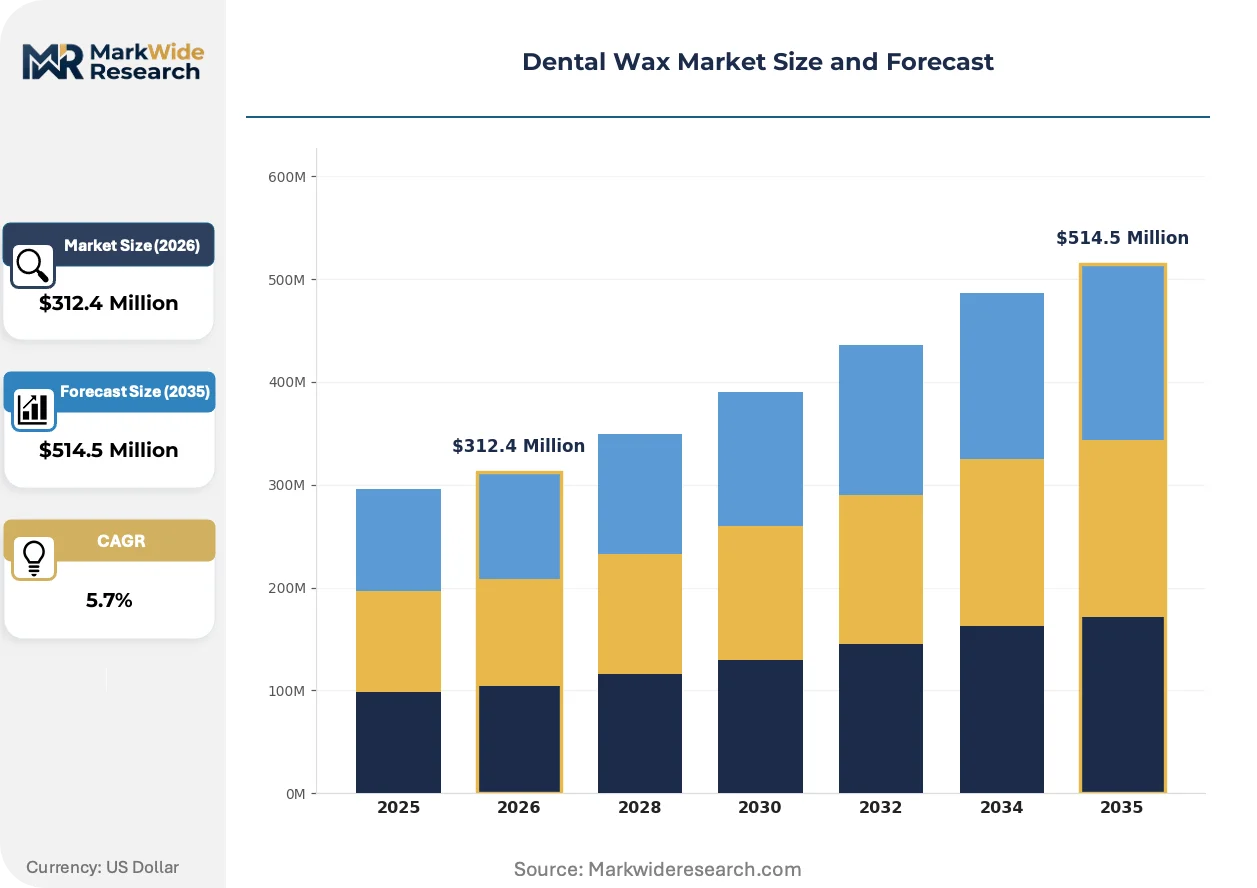
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $514.5 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baseplate Wax, Bite Registration Wax, Modeling Wax, Utility Wax End User: Dental Laboratories, Orthodontic Clinics, Dental Schools, Hospitals Form: Sheets, Strips, Blocks, Granules Material: Paraffin, Beeswax, Carnauba Wax, Synthetic Wax |
| Companies Covered | Bracon Dental, C.J. Robinson Company, Inc, Kerr Corporation, Metrodent Ltd, Bilkim Ltd. Co, DWS Systems, Carmel Industries, Pyrax Polymars, Solstice T&I, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Wax Market Emerging Trajectories
Digital dentistry integration is compressing traditional material specifications while demanding thermoplastic performance consistency across automated and manual fabrication environments.
Precision synthetic polymer waxes are electrifying laboratory throughput capabilities. These engineered compounds deliver batch-to-batch thermal stability within 0.5°C melting point variance. Dental laboratories in Germany and Switzerland are adopting synthetic formulations at accelerated pace for CAD/CAM pattern work. This electrifying standardization is compressing natural wax market share in high-volume restoration segments.
REACH substance disclosure expansion is tightening supply chain visibility requirements. ECHA registration obligations now extend to resin and oil additives in dental baseplate formulations. Wax blenders serving EU dental laboratories are reconfiguring supplier qualification protocols. Small-batch natural wax importers face disproportionate compliance cost absorption.
Direct laboratory procurement consolidation is restructuring distribution economics. Group purchasing organizations and dental laboratory networks are disintermediating traditional dental supply distributors. Bulk synthetic wax contracts now route through centralized procurement platforms. This channel shift is most visible in US multi-location laboratory chains and German dental technology cooperatives.
Dental Wax Market Segmentation
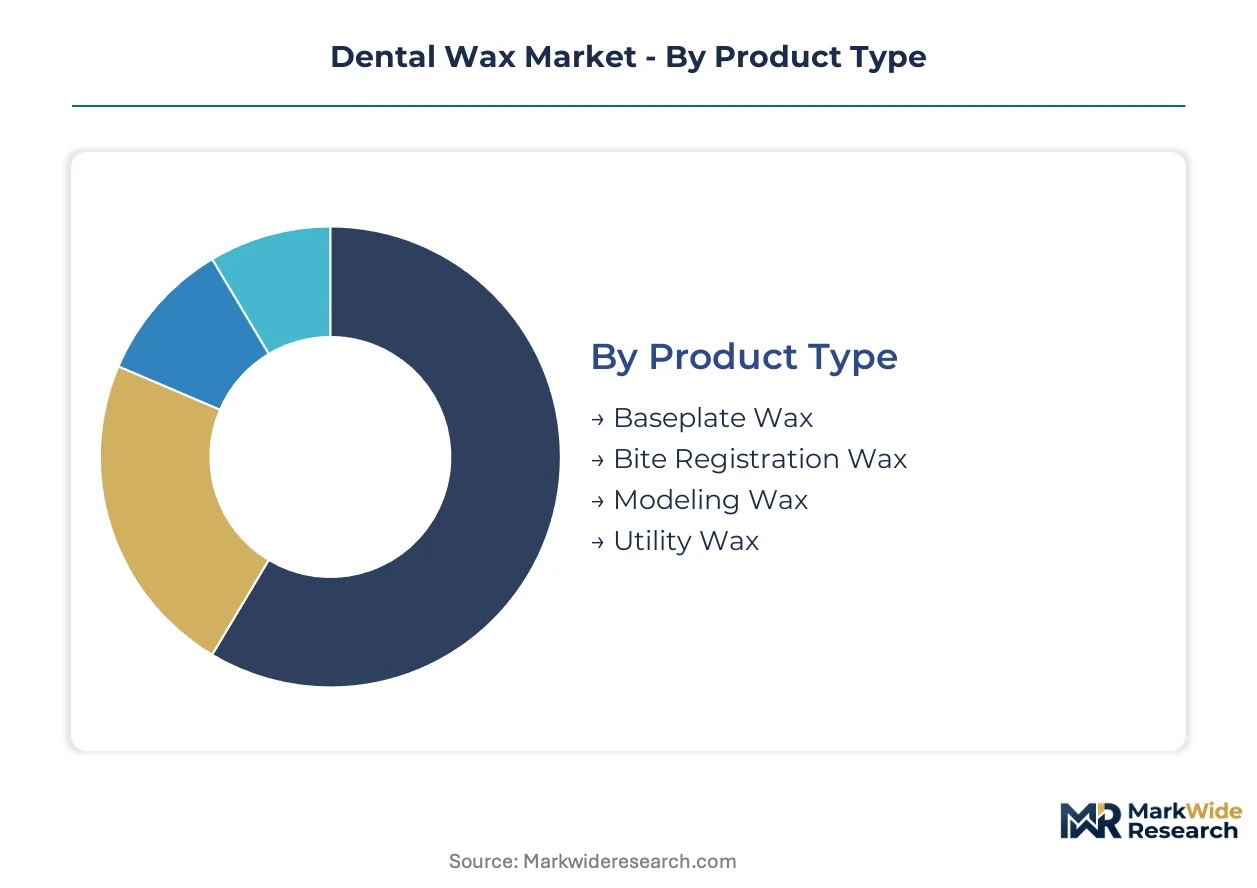
Dental wax segmentation reveals distinct procurement patterns across precision fabrication workflows. Laboratories prioritize thermal stability and dimensional consistency, while orthodontic clinics emphasize handling speed and bracket positioning accuracy.
Product Type:
Standalone pattern materials dominate prosthodontic volume, while bite registration compounds integrate tightly into CAD/CAM verification chains.
- Modeling Wax:Thermoplastic compounds engineered for crown, bridge, and denture pattern work with melting points calibrated between 45°C and 75°C. Dental laboratories in Germany's Cologne and Munich clusters absorb concentrated volumes for precision restoration fabrication, driven by ISO 15854 certification requirements tightening quality benchmarks.
- Bite Registration Wax:Formulations optimized for occlusal relationship capture with rapid setting and minimal distortion. Kerr Corporation's captive R&D facilities in North America sustain formulation leadership, as CAD/CAM workflows elevate precision demands for digital verification stages.
- Baseplate Wax:Dimensionally stable sheets for denture base construction subject to EU MDR reclassification documentation burdens.
- Utility Wax:Orthodontic bracket positioning and appliance modification applications expanding with clear aligner indirect bonding adoption.
Modeling wax leads volumes today; bite registration wax is gaining share fastest.
End User:
Procurement scale separates high-volume laboratory networks from fragmented clinic purchasing, with dental schools representing intermittent bulk buyers.
- Dental Laboratories:Centralized restoration fabrication hubs consuming precision modeling waxes for CAD/CAM pattern work and traditional crown and bridge production. German dental technology cooperatives and US multi-location chains are consolidating procurement through group purchasing organizations, disintermediating traditional distributors.
- Orthodontic Clinics:Utility wax demand concentrates in bracket positioning templates and indirect bonding workflows for clear aligner systems. Clinics in Switzerland and Germany are expanding consumption fastest as aligner penetration accelerates.
- Dental Schools:Educational institutions requiring standardized formulations for student training in wax carving and prosthodontic fundamentals.
- Hospitals:Limited inpatient dental surgery applications with sporadic procurement patterns tied to maxillofacial reconstruction units.
Dental laboratories command the dominant procurement position; orthodontic clinics are climbing the fastest.
Form:
Physical configuration determines handling efficiency across manual carving versus automated dispensing systems.
- Sheets:Baseplate and modeling applications requiring uniform thickness for denture construction and pattern work.
- Strips:Bite registration and utility applications favoring pre-measured portions for chairside efficiency.
- Blocks:High-volume laboratory carving stock for custom pattern fabrication.
- Granules:Automated dispensing systems in CAD/CAM-enabled laboratories requiring precise melt feed.
Blocks retain the largest installed base; granules are expanding most quickly.
Material:
Natural versus synthetic sourcing strategies pivot on batch consistency requirements and supply security priorities.
- Synthetic Wax:Engineered polymer formulations delivering batch-to-batch thermal stability within 0.5°C melting point variance. Dental laboratories in Germany and Switzerland are adopting these compounds at accelerated pace for CAD/CAM pattern work, displacing natural wax in high-volume restoration segments.
- Beeswax:Refined natural wax with established biocompatibility profiles, sourced through backward-integrated supply chains by specialized producers like Bilkim Ltd. Co. Climate-impacted harvest volatility from major producing regions creates formulation cost instability.
- Paraffin:Petroleum-derived base material subject to multi-source procurement strategies shifting away from single-source dependency.
- Carnauba Wax:Hard natural wax from Brazilian palm sources, blended for surface finish properties in premium modeling applications.
Paraffin and beeswax blends lead current volumes; synthetic formulations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dental technology clusters in Cologne and Munich concentrate precision wax demand for CAD/CAM restoration workflows. Laboratories across the country absorb specialized modeling compounds as ISO 15854 certification tightens quality benchmarks. EU MDR reclassification elevates documentation burdens for baseplate wax exporters serving European markets.
Germany
Dental laboratories in Cologne and Munich drive concentrated consumption of precision modeling waxes for crown and bridge fabrication. The EU MDR elevates documentation standards for dental baseplate materials, accelerating laboratory consolidation toward certified suppliers. Bavaria's dental technology cooperatives are disintermediating traditional distributors through centralized procurement platforms.
United States
Multi-location laboratory chains and orthodontic clinics expand utility wax consumption for clear aligner indirect bonding workflows. FDA 21 CFR 872.6890 classifies dental wax as a Class I medical device subject to general controls rather than premarket review. California and New York state-level chemical transparency laws create first-mover advantage for preemptive material disclosure.
Switzerland
Dental laboratories adopt synthetic polymer formulations at accelerated pace for CAD/CAM pattern work requiring batch-to-batch thermal stability. Swissmedic oversight aligns with EU MDR documentation requirements for dental laboratory materials. Zurich and Geneva clusters sustain specialized wax R&D for high-precision restoration segments.
India
Underpenetrated prosthodontic outsourcing hubs present volume growth opportunities for standardized synthetic wax formulations. CDSCO registration requirements govern dental material imports serving domestic laboratory expansion. Maharashtra and Gujarat dental laboratory clusters are scaling capacity to capture international outsourcing demand.
Japan
Precision manufacturing culture sustains demand for thermoplastic compounds with calibrated melting points between 45°C and 75°C. PMDA oversight ensures alignment with international ISO 15854 standards for dental baseplate materials. Tokyo-Osaka dental technology corridors maintain specialized consumption for hybrid digital-physical workflows.
Dental Wax Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue synthetic formulation specialization and regional laboratory network penetration. The vendor base spans multinational dental supply conglomerates, regional wax blenders with captive raw material access, and specialized orthodontic compound manufacturers. Three archetypes dominate: precision synthetic polymer engineers, backward-integrated natural wax refiners, and utility wax specialists serving orthodontic workflows. Competitive moves concentrate on laboratory procurement consolidation partnerships and REACH-compliant supply chain reconfiguration.
Among North American-based formulators, Kerr Corporation exemplifies the precision synthetic tier through captive R&D infrastructure. Bilkim Ltd. Co anchors the natural wax refining archetype with backward integration into beeswax supply chains. Metrodent Ltd occupies the specialized utility segment for orthodontic appliance fabrication. These three entities represent distinct strategic postures within a market segmenting between batch-consistency engineering and traditional material craftsmanship.
| Leading Market Players |
|---|
| Bracon Dental |
| C.J. Robinson Company, Inc |
| Kerr Corporation |
| Metrodent Ltd |
| Bilkim Ltd. Co |
| DWS Systems |
| Carmel Industries |
| Pyrax Polymars |
| Solstice T&I |
| Others |
Supply Flow & Price Mechanics
ISO 15854 certification divergence between premium synthetic formulations and commodity natural blends manifests in both margin structures and procurement network configurations across dental wax supply chains. Laboratories in Germany and Switzerland absorb price premiums for batch-consistent polymer compounds, while price-sensitive buyers in emerging outsourcing hubs default to paraffin-beeswax blends with higher thermal variance.
Pricing Analysis
Input-cost pass-through from refined beeswax and carnauba harvest volatility compresses margins for natural wax blenders in Brazil and Turkey. Three-tier pricing structure across premium synthetic, certified natural, and economy paraffin tiers reflects ISO 15854 compliance grade and volume scale. Pricing pressure stems from REACH disclosure expansion elevating formulation documentation costs. Dental schools and small independent laboratories exhibit highest price sensitivity; German dental technology cooperatives prioritize thermal stability over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Chicago anchor hub-and-spoke patterns serving laboratory networks and orthodontic clinics. Raw material supply concentrates in Brazil for carnauba, China for paraffin derivatives, and Turkey for refined beeswax. Formulation depends on resin and oil additives subject to ECHA registration obligations. Single-source vulnerability runs through Brazilian palm harvest climate exposure. Distribution runs through group purchasing organizations disintermediating traditional dental supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental wax constitutes a late-cycle quality story as CAD/CAM restoration workflows elevate thermal stability specifications above commodity paraffin capabilities. Laboratories now reject batch-variable natural waxes for precision crown and bridge fabrication.
For Market Incumbents: Deepen backward integration into synthetic polymer feedstocks to defend margin position against commodity wax price volatility. Prioritize dual FDA 21 CFR 872.6890 and EU MDR certification investment to compress new entrant launch timelines. Channel control through captive distribution partnerships with German dental technology cooperatives reinforces procurement lock-in. For New Entrants and Emerging Players: Enter via standardized synthetic formulations targeting underpenetrated prosthodontic outsourcing hubs in Maharashtra and Gujarat. The India dental laboratory expansion presents the most penetrable volume opportunity. A direct laboratory procurement platform bypassing traditional distributors offers viable go-to-market positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs disproportionately burden small-batch natural wax importers lacking ECHA registration infrastructure. Long-term viability favors synthetic formulation specialists with captive R&D capabilities over commodity blenders. Watch EU MDR enforcement intensity as inflection indicator for laboratory procurement consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Feedstocks | Captive polymer supply secures batch consistency for CAD/CAM pattern work in German laboratories. |
| Dual Certification Investment | Simultaneous FDA and EU MDR compliance accelerates product launch cycles for baseplate wax exporters. |
| Direct Laboratory Procurement Platform | Group purchasing organization partnerships disintermediate traditional dental supply distribution channels. |
| REACH-Compliant Supply Chain Reconfiguration | ECHA registration alignment reduces compliance burden for resin and oil additive sourcing. |
| Synthetic-Natural Hybrid Formulation Development | Precision polymer engineering with modified natural waxes enables premium tier differentiation. |
Methodological Framework
Multiple input streams — primary interviews with dental laboratory technicians, orthodontic clinic procurement managers, and wax formulation chemists; secondary validation against ISO 15854 certification databases, FDA 510(k) filings, and ECHA substance registrations; customs and trade flow records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement pattern shifts across German dental technology cooperatives, US multi-location laboratory chains, and emerging outsourcing hubs in India.
Historical consumption patterns were cross-referenced against expert panel inputs to construct projection frameworks across the analysis window. Segmentation dimensions modeled include product type, end user archetype, material sourcing strategy, and regional regulatory cluster. CAGRs were derived from volume trajectory analysis calibrated to laboratory capacity expansion rates and clear aligner penetration curves in orthodontic workflows.
Inputs from ECHA registration databases and FDA classification records were available through the study window; gaps in small-batch natural wax import documentation introduce uncertainty bands around emerging market penetration estimates. Forecasts reflect documented assumptions regarding CAD/CAM adoption velocity and EU MDR enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Dental Alginate Market
Dental Materials
Fluoride-Free Toothpaste Market
Dental Materials
Asia-Pacific Toothpaste Market
Dental Materials
Teeth Whitening Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Dental Resins Market
Dental Materials
Solid Toothpaste Market
Dental Materials
Global Zirconia Based Dental Materials Market
Dental Materials
Dental Fiberglass Posts Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Dental Alloys Market