
 Europe Healthcare Information Technology (IT) Market | 2026-2036
Europe Healthcare Information Technology (IT) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Healthcare Information Technology (IT) Market Insights
Market Context
Subscription-based software leasing is tilting competitive dynamics toward asset-light vendors that bypass heavy capital expenditure. Siemens Healthineers AG leverages its imaging-IT convergence to dominate radiology-workflow integration. Oracle sustains cloud infrastructure scale across multi-country hospital networks. Dedalus S.p.A. specializes in region-specific compliance architectures that anchor Southern European deployments.
Technical Definition and Segments
Healthcare Information Technology encompasses software systems, data infrastructure, and digital platforms that manage clinical workflows, patient records, and operational analytics across care delivery organizations, typically requiring HL7 FHIR interoperability protocols and ISO 27001-certified security frameworks. Electronic Health Records occupy the largest installed base, though Telemedicine Solutions generate the fastest expansion as remote consultation becomes standard in rural and post-acute settings. Cloud-Based Solutions capture disproportionate investment flow while On-Premises Systems retain dominance in jurisdictions with strict data-localization requirements.
Regulatory Framework
EMA medical-device software classifications, GDPR health-data processing rules, and the EU AI Act risk-based compliance tiers collectively shape product development roadmaps and market access conditions for vendors operating across member states. The EU Green Deal's digital-health sustainability benchmarks add procurement-weighted environmental criteria to hospital IT tenders. Stakeholders must monitor evolving MDR software-as-medical-device boundaries and national reimbursement codes for digital therapeutics to anticipate where capital allocation priorities will shift next.
Market Dynamics
Hospital procurement across Germany and France is accelerating toward interoperable cloud platforms as GDPR enforcement tightens and the EU AI Act imposes risk-based compliance tiers on clinical decision-support software.
Growth Catalysts
- GDPR health-data processing rules:Stringent data governance mandates in France and the Netherlands are forcing hospital networks to replace legacy silos with certified platforms, creating replacement demand across acute-care facilities.
- Rural telemedicine infrastructure:Post-acute settings and remote consultation networks in Spain and Italy are expanding HL7 FHIR-connected systems to meet national e-health connectivity standards.
- EU Green Deal digital-health benchmarks:Environmental procurement criteria embedded in hospital IT tenders are favoring energy-efficient cloud architectures over on-premises server farms.
Market Restraints
- ISO 27001 certification bottlenecks:Limited accredited auditors in Southern Europe are stretching vendor compliance timelines to 14-18 months, delaying market entry.
- Data-localization statutes:Strict sovereignty requirements in Switzerland and select German Länder are fragmenting cloud infrastructure economics and raising operational complexity.
- Legacy EHR lock-in:Proprietary data formats from dominant installed-base vendors create switching costs that suppress competitive churn in Benelux hospital networks.
Strategic Opportunities
- Poland and Romania e-health programs:Underpenetrated Eastern European markets are launching national digitization roadmaps with EU Recovery Fund backing, opening greenfield deployment windows.
- AI Act high-risk system certification:Early movers achieving CE marking under the new medical-device software classifications will capture preferred-vendor status in radiology and pathology workflows.
- Edge-to-cloud hybrid architectures:Convergence of on-premises inference nodes with centralized analytics is enabling vendors to serve data-sovereignty jurisdictions without full cloud migration.
Industry Challenges
- HL7 FHIR implementation expertise:Scarce integration engineers familiar with R4 and SMART on FHIR protocols are extending project timelines and inflating professional-services costs.
- MDR software-as-medical-device boundary uncertainty:Evolving EMA classification guidance is forcing vendors to maintain parallel regulatory strategies, diverting R&D resources from product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Healthcare Information Technology (IT) Market |
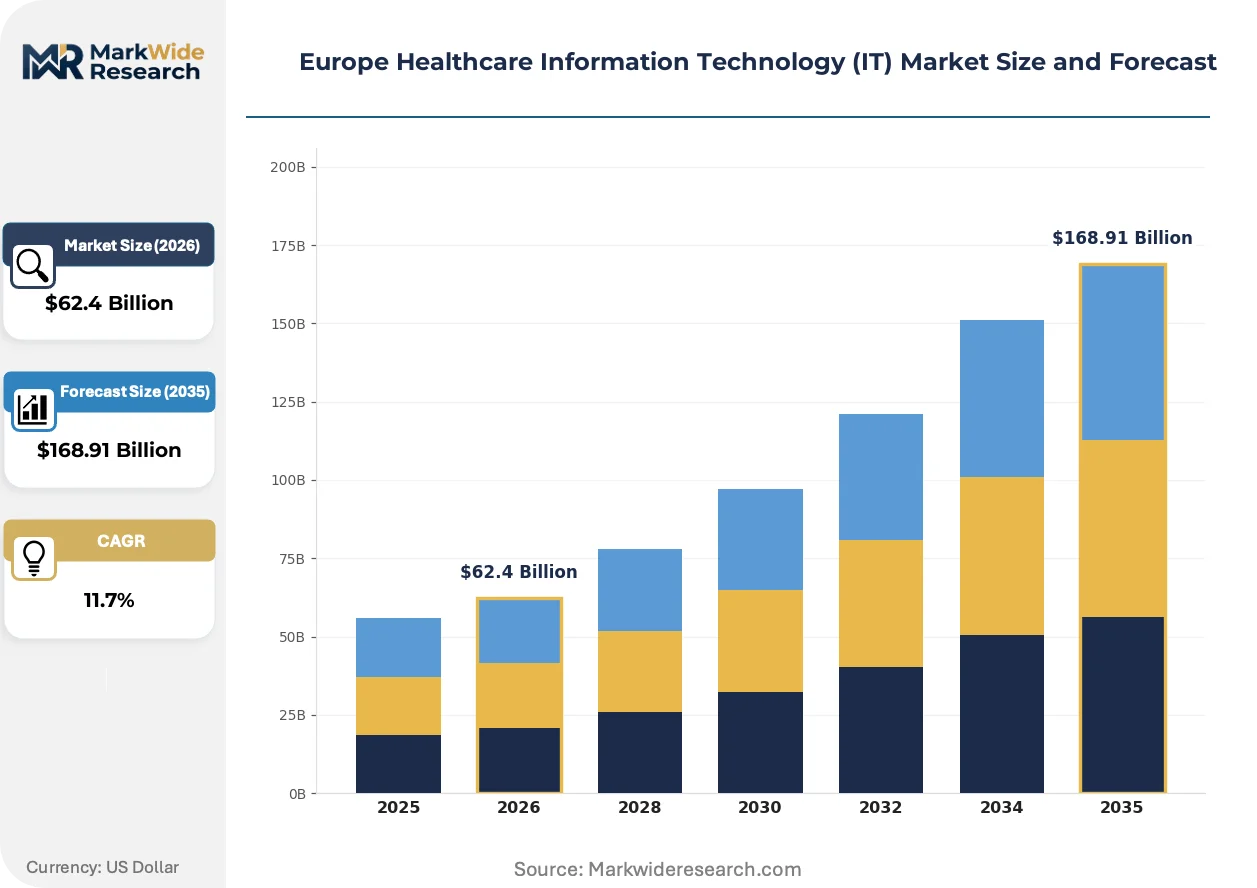
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $168.91 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Records, Telemedicine Solutions, Clinical Decision Support, Health Information Exchange End User: Hospitals, Private Clinics, Nursing Homes, Rehabilitation Centers Technology: Cloud-Based Solutions, On-Premises Systems, Mobile Health Applications, Interoperable Platforms Application: Patient Management, Revenue Cycle Management, Data Analytics, Population Health Management |
| Companies Covered | Siemens Healthineers AG, Oracle, Epic Systems Corporation, Dedalus S.p.A., CompuGroup Medical, Koninklijke Philips N.V., GE HealthCare, Optum, Inc., Veradigm, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Healthcare Information Technology (IT) Market Trends and Innovations
Clinical workflow platforms are converging with diagnostic imaging systems while regulatory frameworks force faster recertification cycles. Vendors are rearchitecting delivery models to meet simultaneous demands for interoperability, sovereignty, and sustainability.
Interoperability middleware is hybridizing previously isolated departmental systems into unified data fabrics. Academic medical centers in Germany and the Netherlands are deploying these integration layers at scale to enable real-time analytics across radiology, pathology, and laboratory workflows. The technology is hybridizing competitive positioning by rewarding vendors with pre-built connector libraries over those requiring custom integration.
The EU AI Act risk-based classification system is compressing product development timelines for clinical decision-support tools. High-risk categorization triggers conformity assessment requirements that parallel MDR pathways, forcing vendors to rebuild quality management systems. Radiology AI modules face the steepest compliance burden, with several vendors withdrawing non-essential features rather than pursuing certification.
Subscription-based leasing is displacing perpetual licensing in hospital procurement across France and Scandinavia. Chief information officers are prioritizing operational expenditure models that transfer infrastructure risk to vendors, particularly for cloud-based analytics platforms. This shift is most pronounced in Paris and Copenhagen hospital networks, where five-year total-cost-of-ownership calculations now dominate vendor selection criteria.
Europe Healthcare Information Technology (IT) Market Segmentation
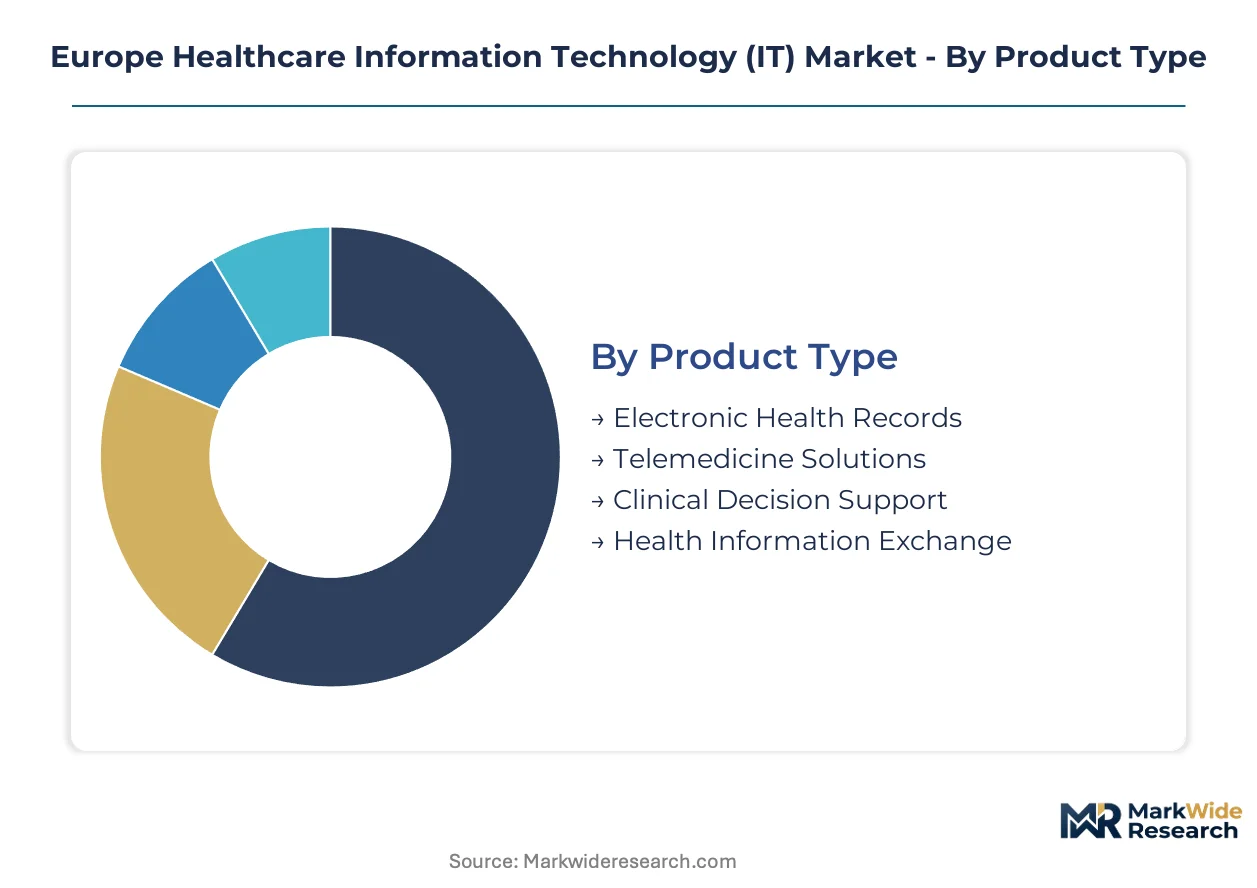
Healthcare IT procurement across Europe follows distinct technology maturity curves and regulatory compliance tiers. Segmentation reveals where capital concentrates versus where replacement cycles accelerate under GDPR and EU AI Act mandates.
Product Type:
Mature installed bases dominate acute-care settings while emerging categories capture greenfield investment in post-acute and ambulatory networks.
- Electronic Health Records:Core clinical data repositories managing longitudinal patient histories across inpatient and outpatient encounters. German hospital networks are consolidating fragmented departmental systems into enterprise EHR platforms to meet interoperability mandates.
- Telemedicine Solutions:Real-time video consultation platforms integrated with diagnostic peripherals and prescription workflows. French and Dutch rural health networks are deploying these systems to satisfy national e-health connectivity standards for remote care delivery.
- Clinical Decision Support:Rules-based and AI-augmented diagnostic assistance tools embedded within physician workflows.
- Health Information Exchange:Cross-organizational data sharing infrastructure enabling care coordination across provider networks.
Electronic Health Records handles the majority of throughput; Telemedicine Solutions is the fastest mover on share.
End User:
Facility scale determines procurement sophistication and compliance burden intensity across the care continuum.
- Hospitals:Large acute-care institutions with complex multi-departmental IT requirements and stringent EMA medical-device software classifications. French public hospital networks are accelerating cloud migration to satisfy GDPR health-data processing rules and EU Green Deal sustainability benchmarks.
- Private Clinics:Independent ambulatory facilities prioritizing cost-efficient SaaS models over capital-intensive infrastructure.
- Nursing Homes:Long-term care facilities requiring medication management and resident monitoring systems.
- Rehabilitation Centers:Post-acute facilities integrating functional outcome tracking with payer reporting requirements.
Hospitals command the largest IT budgets per facility; Private Clinics are expanding fastest as subscription models lower entry barriers.
Technology:
Deployment architecture choices reflect tensions between data sovereignty requirements and operational efficiency gains.
- Cloud-Based Solutions:Centralized infrastructure with vendor-managed security patching and elastic compute scaling. Scandinavian hospital procurement is shifting decisively toward these models as five-year total-cost-of-ownership calculations favor operational expenditure structures.
- On-Premises Systems:Locally hosted infrastructure retaining physical control over patient data and customization capabilities. Swiss and select German Länder jurisdictions mandate these deployments under strict data-localization statutes.
- Mobile Health Applications:Smartphone-native patient engagement and remote monitoring tools.
- Interoperable Platforms:HL7 FHIR-native systems enabling seamless data exchange across heterogeneous vendor environments.
On-Premises Systems retain dominance in regulated jurisdictions; Cloud-Based Solutions are climbing the fastest as energy-efficiency criteria reshape procurement.
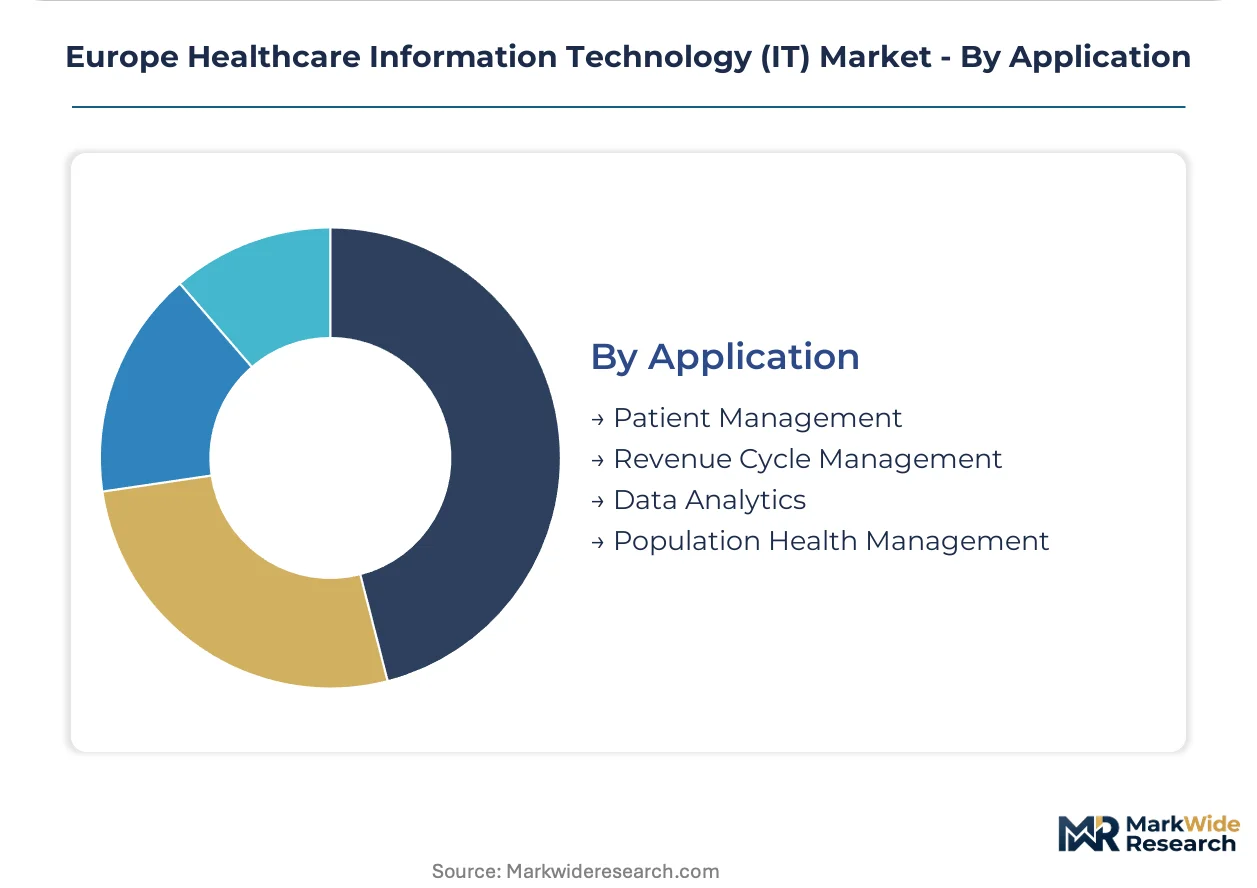
Application:
Functional use cases align IT investment with reimbursement incentives and quality reporting obligations.
- Patient Management:Scheduling, registration, and care coordination workflows spanning encounter-based services. Netherlands hospital networks are consolidating these functions into unified platforms to meet national e-health program connectivity standards.
- Revenue Cycle Management:Claims processing, prior authorization, and patient financial services automation. Benelux providers are prioritizing these tools as diagnosis-related group reimbursement complexity increases.
- Data Analytics:Population-level insights and predictive risk stratification for care management.
- Population Health Management:Accountable care organization infrastructure for value-based contracting.
Patient Management anchors the largest installed base; Data Analytics is gaining share fastest as AI Act compliance creates demand for auditable decision-support infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare IT procurement across Europe tilts toward import-dependent software licensing models, with domestic platform development concentrated in Germany and the Netherlands while cloud infrastructure relies on US and Irish data center investments. Export competitiveness in specialized compliance architectures favors Italian and German vendors serving Mediterranean and Central European hospital networks.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are consolidating fragmented departmental EHR systems into enterprise platforms under GDPR enforcement pressure. The EU AI Act risk-based tiers are forcing clinical decision-support vendors to rebuild quality management systems for CE marking. Berlin-Brandenburg medical centers are deploying interoperability middleware to connect radiology, pathology, and laboratory workflows.
France
Paris hospital networks are accelerating cloud migration to satisfy CNIL health-data processing rules and EU Green Deal sustainability benchmarks in public tenders. The national e-health program mandates system-wide HL7 FHIR connectivity standards across Île-de-France and Auvergne-Rhône-Alpes regions. Lyon academic medical centers are piloting edge-to-cloud hybrid architectures to retain data sovereignty while enabling centralized analytics.
Netherlands
Randstad hospital procurement is shifting decisively toward subscription-based SaaS models as five-year total-cost-of-ownership calculations favor operational expenditure structures. National e-health connectivity standards require seamless patient management integration across Amsterdam and Rotterdam metropolitan networks. Eindhoven Region health technology clusters are developing interoperable platforms for cross-border data exchange with Belgian providers.
Italy
Lombardy and Emilia-Romagna hospital networks are expanding telemedicine infrastructure to meet post-acute care demands in rural provinces. ANSM medical-device software classifications are compressing product development timelines for clinical decision-support tools. Milan-based vendors are specializing in region-specific compliance architectures that anchor Southern European deployments under MDR software-as-medical-device boundaries.
Switzerland
Swissmedic oversight and strict data-localization statutes mandate on-premises systems in Zurich and Geneva hospital networks, fragmenting cloud infrastructure economics. Cantonal procurement favors energy-efficient server architectures that satisfy EU Green Deal digital-health benchmarks without cross-border data transfer. Basel pharmaceutical clusters are driving demand for ISO 27001-certified platforms with localized security patching capabilities.
Europe Healthcare Information Technology (IT) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the interoperability and imaging-IT convergence layers. The vendor base organizes around three strategic archetypes: imaging-IT convergence specialists leveraging diagnostic hardware relationships, cloud infrastructure scale operators serving multi-country hospital networks, and region-specific compliance architects anchoring Southern European deployments. Competitive moves concentrate on M&A for connector library expansion and strategic partnerships for edge-to-cloud hybrid delivery models.
Within the imaging-IT convergence tier, Siemens Healthineers AG and GE HealthCare occupy positions that bridge diagnostic equipment with clinical workflow platforms. Oracle represents the cloud infrastructure scale archetype, while Dedalus S.p.A. exemplifies region-specific compliance specialization for Mediterranean markets. Epic Systems Corporation sits within the enterprise EHR tier, and Koninklijke Philips N.V. anchors the connected care device-to-software integration vector.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Oracle |
| Epic Systems Corporation |
| Dedalus S.p.A. |
| CompuGroup Medical |
| Koninklijke Philips N.V. |
| GE HealthCare |
| Optum, Inc. |
| Veradigm |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in ISO 27001-certified auditor pools across Southern Europe is compressing vendor compliance timelines to 14-18 months, forcing hospital procurement committees to accept premium pricing for pre-certified platforms while accelerating subscription-based SaaS migration to transfer infrastructure risk.
Pricing Analysis
Hospital procurement committees anchor subscription-based SaaS pricing across three-tier structures separating enterprise-grade interoperability platforms from departmental modules and basic patient management tools. Price differentiation rests on HL7 FHIR certification level and EU AI Act compliance tier, with high-risk clinical decision-support modules commanding substantial premiums. Cost compression in on-premises infrastructure is intensifying as energy-efficiency benchmarks in French and Dutch public tenders favor cloud architectures. Private clinics in Scandinavia exhibit highest price sensitivity due to constrained capital budgets, while German academic medical centers show lowest sensitivity given bundled research funding.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are proliferating across vendor-hospital contracting as supply-chain finance facilities ease liquidity constraints for mid-tier platform developers. Software development capacity concentrates in Germany, Ireland, and the Netherlands, with cloud infrastructure provisioning anchored in Irish and Swedish data centers. Raw material dependencies span semiconductor components for diagnostic peripherals, specialized encryption hardware for GDPR-compliant architectures, and energy-efficient server components for Green Deal alignment. Single-source vulnerability in HL7 FHIR integration engineering creates bottleneck risk. Distribution runs through direct enterprise sales teams serving hospital networks, supplemented by GPO contracts in France and Benelux.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Healthcare IT sits in early-cycle expansion as national e-health mandates in France, the Netherlands, and Poland drive replacement demand for legacy siloed systems with interoperable platforms.
For Market Incumbents: Pre-empt cloud-native challengers by accelerating connector library expansion through targeted acquisitions of HL7 FHIR integration specialists. Deepen backward integration into edge-computing hardware to serve Swiss and German data-sovereignty requirements without full cloud dependency. Lock in hospital network preferred-vendor status through multi-year subscription bundles that embed AI Act compliance certification costs.
For New Entrants and Emerging Players: Establish a beachhead in Romanian and Polish hospital digitization programs where EU Recovery Fund backing creates greenfield deployment windows with lower incumbent saturation. Target private clinic networks in Scandinavia with lightweight SaaS patient management tools that undercut enterprise EHR pricing. Pursue channel partnerships with regional systems integrators possessing existing CNIL and GDPR audit relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native telemedicine platforms as vendor-managed infrastructure displaces hospital-owned server farms. Long-term viability favors asset-light interoperability middleware developers with recurring revenue concentration above 70%. Monitor CE marking approval velocity under EU AI Act high-risk classifications as inflection indicator for radiology and pathology AI module commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU AI Act high-risk certification unlocks preferred-vendor status in German radiology networks. |
| Hospital System Partnership | Multi-year SaaS agreements with Paris hospital networks secure recurring revenue under CNIL governance. |
| Platform Integration | HL7 FHIR-native middleware convergence enables real-time analytics across Dutch academic medical centers. |
| Geographic Expansion | Eastern European e-health programs in Poland and Romania offer greenfield deployment with EU Recovery Fund backing. |
| Strategic Partnership | Edge-to-cloud hybrid architectures with Swiss data centers satisfy cantonal localization statutes without full infrastructure migration. |
Research Methodology
Initial hypotheses were tested against primary input from hospital CIOs, biomedical engineers, GPO contracts managers, and EMA regulatory affairs specialists and refined through secondary validation against hospital procurement databases, GPO contract repositories, CMS Medicare comparative data, and EU tender documentation. Bottom-up sizing of installed base and replacement cycles was triangulated with top-down macroeconomic healthcare expenditure projections across the analysis window.
Demand-supply balance modeling anchored volume forecasts across deployment architecture, facility scale, application function, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate convergence analysis incorporating EMA software-as-medical-device boundary evolution and national reimbursement code expansion for digital therapeutics as key forecast inputs.
Stress conditions across GDPR enforcement intensity, EU AI Act implementation timelines, and ISO 27001 auditor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding interoperability mandate adoption curves and cloud migration willingness. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Clinical Communication and Collaboration Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
Healthcare HR Software Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Clinical Practice Management Software Market