
 Right Hand Drive Electric Vehicle Market | 2026-2036
Right Hand Drive Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Right Hand Drive Electric Vehicle Market Analytics
The United Kingdom's zero-emission vehicle mandate is expanding the addressable market for right hand drive electric vehicles across Commonwealth-aligned markets. Toyota Motor Corporation leverages its hybrid-electric heritage to sustain production scale in Japanese and Thai manufacturing plants. Tata Motors Limited anchors its competitive position through captive battery supply and domestic Indian market dominance. BYD Co Ltd extends its vertical manufacturing scope into right hand drive variants for Australian and Southeast Asian export channels.
Right hand drive electric vehicles are passenger and light commercial automobiles engineered with steering systems, instrument clusters, and safety architectures configured for left-side road traffic, typically incorporating battery packs exceeding 40 kWh, front or dual-motor layouts, and CCS or CHAdeMO charging interfaces. Their primary commercial purpose is to serve the approximately seventy-five sovereign and territorial markets operating left-hand traffic rules, encompassing Japan, the United Kingdom, India, Australia, and numerous former British colonies. Battery Electric powertrains dominate unit economics through simplified drivetrains and declining lithium-ion cell costs, while Plug-in Hybrid configurations retain structural relevance in charging infrastructure gaps across South Asian and African markets. Commercial Fleets represent the fastest-expanding end user category as logistics operators and ride-hailing platforms standardize on total cost of ownership models that favor electric drivetrains.
The United Kingdom's Vehicle Certification Agency enforces UNECE regulatory alignment for type approval, while India's Automotive Research Association administers CMVR crashworthiness and electromagnetic compatibility testing that gates market access. Japan's Ministry of Land, Infrastructure, Transport and Tourism maintains distinct safety and homologation standards that fragment certification pathways for multi-market platforms. Australia's Design Rules under the Department of Infrastructure specify right hand drive compliance thresholds that limit parallel import volumes. Stakeholders must monitor regulatory divergence between left-hand traffic jurisdictions as battery passport requirements and software-defined vehicle standards proliferate without harmonized implementation timelines.
Market Dynamics
Fleet operators in left-hand traffic markets are consolidating procurement around total cost of ownership models that favor battery electric drivetrains over diesel equivalents, compressing replacement cycles and reshaping manufacturer order books.
Growth Catalysts
- Zero-Emission Vehicle Mandate:The United Kingdom's regulatory framework requires escalating shares of electric sales, forcing distributors to secure right hand drive inventory ahead of compliance deadlines.
- Congestion Pricing:Metropolitan authorities in London, Singapore, and Tokyo exempt battery electric vehicles from daily access charges, tilting fleet economics toward electrification.
- Battery Cost Curves:Lithium iron phosphate cell production scale in Chinese manufacturing hubs is compressing pack costs for right hand drive platforms serving Commonwealth markets.
Market Restraints
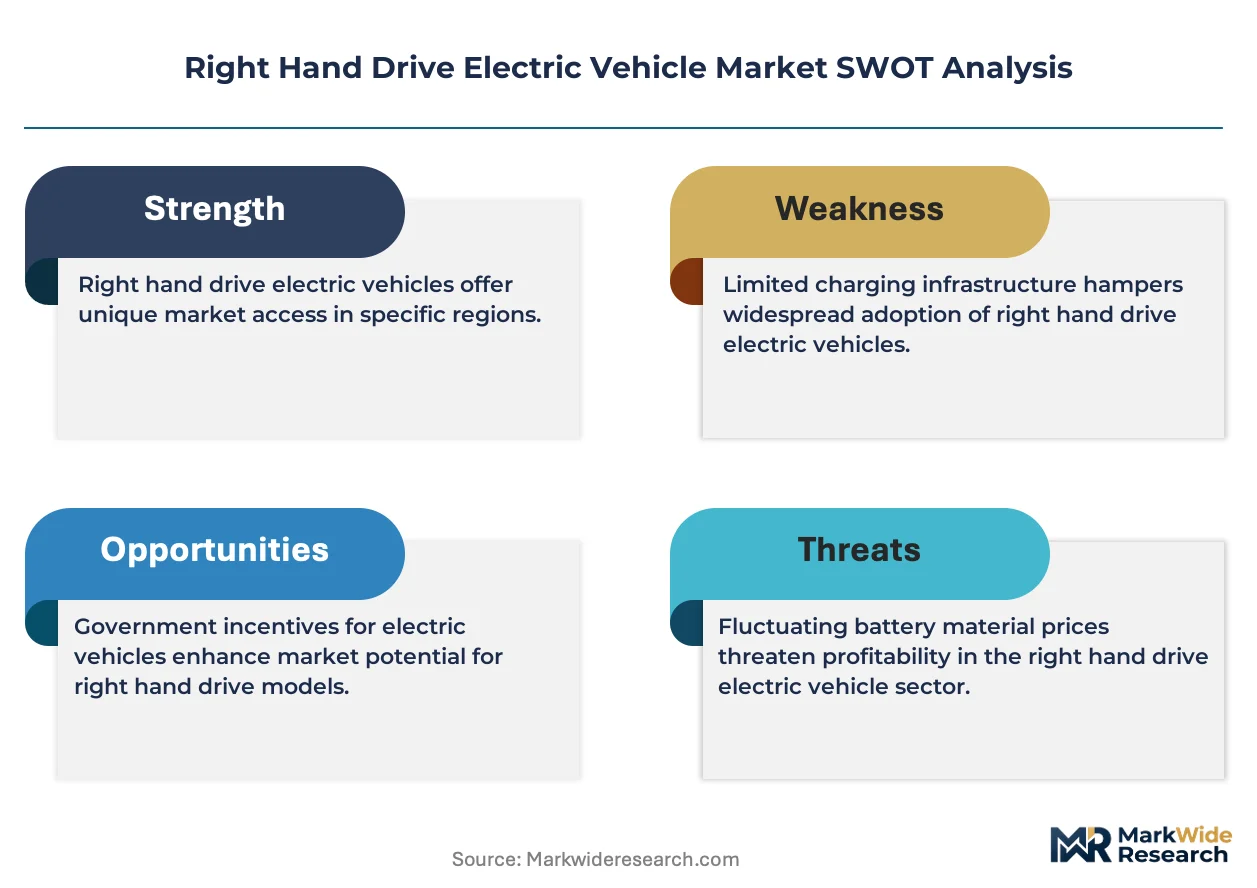
- Charging Infrastructure Gaps:Grid capacity constraints in Indian secondary cities and African left-hand traffic markets limit commercial fleet electrification outside metropolitan cores.
- Homologation Fragmentation:Japan's Ministry of Land, Infrastructure, Transport and Tourism maintains distinct crashworthiness and electromagnetic compatibility standards that prevent direct platform transfers from United Kingdom or Australian certification pathways.
- Residual Value Uncertainty:Secondary market liquidity for battery electric commercial vehicles remains thin across Southeast Asian left-hand traffic jurisdictions, elevating leasing costs.
Strategic Opportunities
- Captive Battery Supply:Indian PLI scheme incentives for cell manufacturing are enabling domestic right hand drive producers to secure upstream control over lithium-ion supply chains.
- Interoperable Charging Standards:Convergence between CCS and CHAdeMO protocols across Australian and Japanese networks is reducing fleet operator switching costs and charger redundancy.
- Software-Defined Vehicle Platforms:Over-the-air update capabilities are opening recurring revenue streams for right hand drive manufacturers serving ride-hailing and logistics fleets in Thailand and Malaysia.
Industry Challenges
- Homologation Engineer Scarcity:Specialized talent capable of navigating simultaneous United Kingdom Vehicle Certification Agency and Japan Ministry of Land, Infrastructure, Transport and Tourism approval processes commands premium compensation.
- Pack Thermal Management:Right hand drive battery architectures must accommodate steering column intrusion and localized climate extremes across Australian outback and Indian monsoon conditions without platform redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Right Hand Drive Electric Vehicle Market |
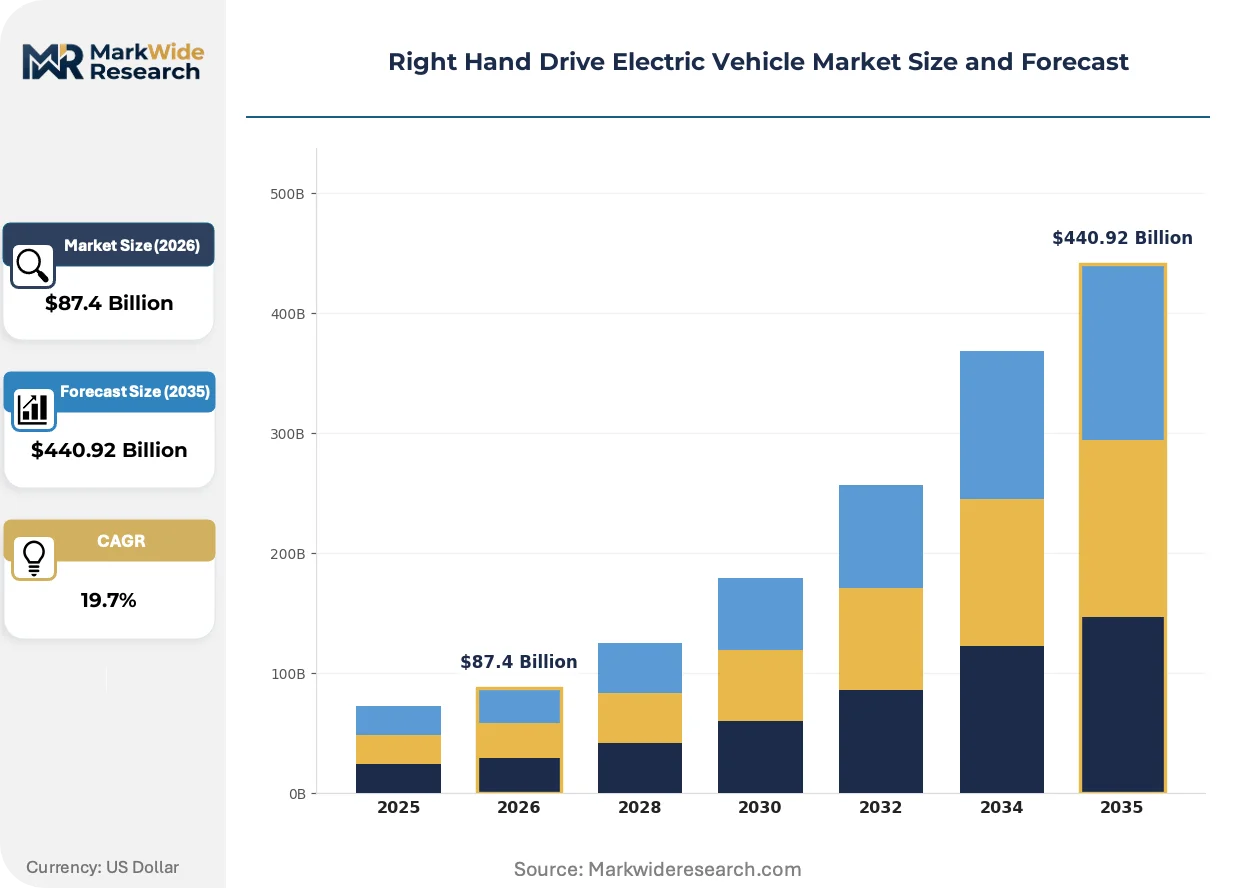
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $440.92 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, MPV Powertrain: Battery Electric, Plug-in Hybrid, Fuel Cell, Range Extender End User: Commercial Fleets, Private Owners, Ride-Sharing Services, Government Agencies Charging Infrastructure: Home Charging, Public Chargers, Fast Chargers, Wireless Charging |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Company, Tata Motors Limited, BMW Group, Audi AG, BYD Co Ltd, Nissan Motor Company, Mahindra & Mahindra Limited, MG Motor India Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Right Hand Drive Electric Vehicle Market Evolving Landscape
Vehicle-level energy management is migrating from hardware-centric architectures toward software-controlled systems that enable fleet-specific optimization. This shift is compressing development cycles and opening new competitive vectors beyond traditional manufacturing scale.
Vehicle-to-grid bidirectional charging hardware is decentralizing energy asset ownership across commercial fleet operators. Logistics platforms in the United Kingdom and Japan are installing bidirectional-capable depots to arbitrage peak grid pricing. This capability is converting parked fleet assets into distributed storage resources that offset charging infrastructure capital requirements.
The United Kingdom's zero-emission vehicle mandate is accelerating type approval timelines for right hand drive platforms. Manufacturers must front-load homologation investments to secure 2024-2025 model year certification slots. Australian Design Rules under the Department of Infrastructure are tightening in parallel, forcing suppliers to consolidate testing programs across Commonwealth-aligned markets.
Logistics procurement teams are consolidating supplier relationships around full-service electrification partnerships rather than discrete vehicle transactions. Fleet managers in Mumbai and Sydney now specify charging infrastructure, maintenance, and energy management as bundled contract terms. This behavior is most pronounced among last-mile delivery operators facing municipal diesel restrictions.
Right Hand Drive Electric Vehicle Market Segmentation
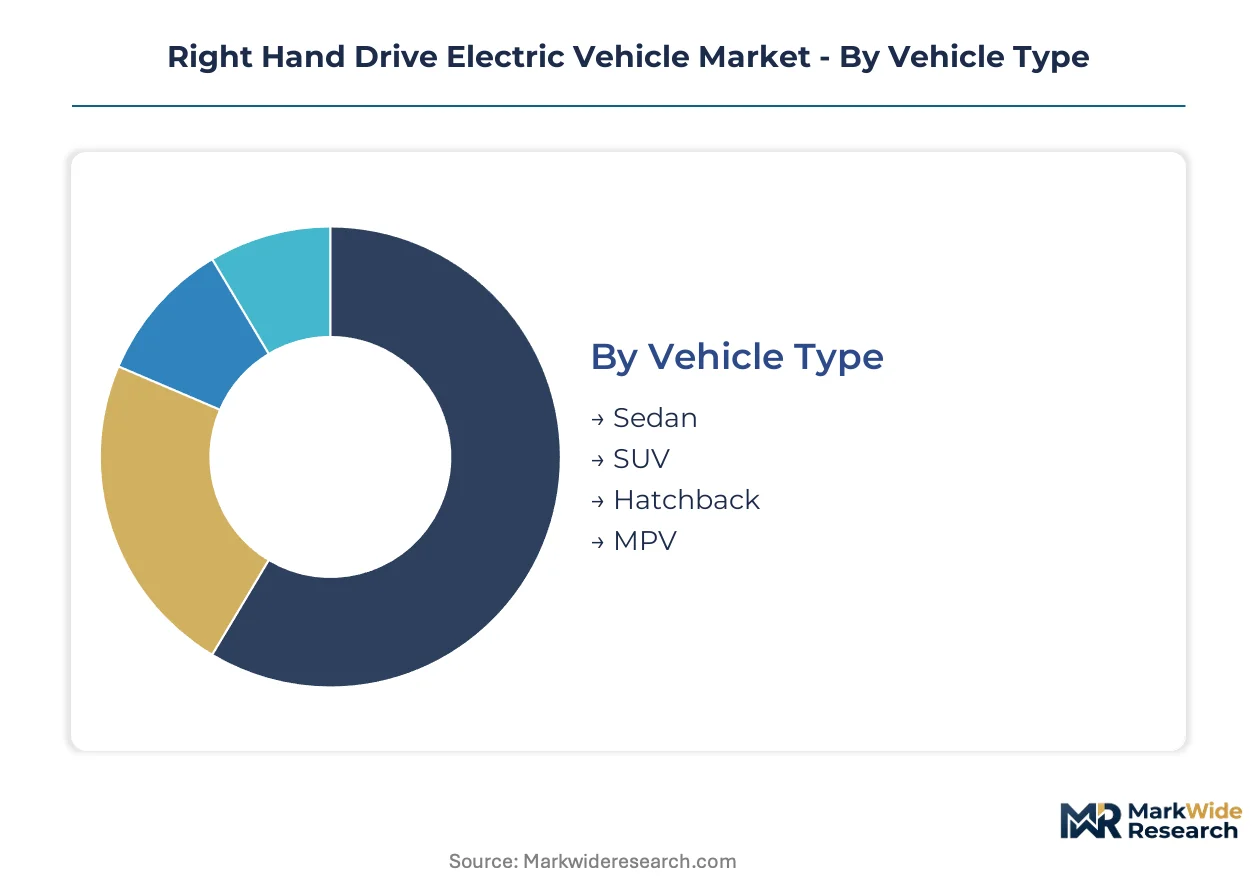
Right hand drive electric vehicle procurement decisions diverge sharply across vehicle formats, powertrain architectures, and charging access models. Fleet operators in London, Tokyo, and Mumbai weight total cost of ownership differently than private buyers, creating distinct certification and homologation pathways for each segment cluster.
Vehicle Type:
Certification burden varies by crashworthiness testing intensity and steering column intrusion geometry, with larger platforms demanding more extensive electromagnetic compatibility validation under Japan's Ministry of Land, Infrastructure, Transport and Tourism protocols.
- Sedan:Three-box configurations with battery packs mounted beneath the passenger compartment dominate corporate fleet procurement in the United Kingdom and Singapore. Demand concentrates among ride-hailing operators seeking standardized maintenance protocols and aerodynamic efficiency for highway-intensive duty cycles.
- SUV:Raised ride heights accommodate larger battery capacities above 75 kWh while preserving cabin space for left-hand traffic steering conversions. Australian mining corridor fleets and Indian premium private buyers drive order concentration, though higher kerb weights trigger additional brake performance certification under Australian Design Rules.
- Hatchback:Compact footprints suit Japanese kei-car regulations and Indian urban congestion constraints. Battery thermal management must adapt to monsoon humidity without platform redesign.
- MPV:Multi-purpose configurations serve airport shuttle and hotel transfer fleets across Thailand and Malaysia with flat-floor architectures enabling wheelchair accessibility compliance.
SUV sits at the top of the volume ranking, with MPV climbing the fastest as tourism-dependent economies electrify hospitality logistics.
Powertrain:
Homologation complexity scales with energy storage chemistry and propulsion architecture diversity, forcing manufacturers to maintain parallel certification tracks across Commonwealth and Japanese regulatory spheres.
- Battery Electric:Simplified drivetrains with front-mounted motors and liquid-cooled lithium iron phosphate packs dominate total cost of ownership calculations for London last-mile delivery operators. Procurement is accelerating where congestion pricing exemptions and depot-based overnight charging align.
- Plug-in Hybrid:Parallel hybrid architectures with 15-20 kWh usable battery capacity retain structural relevance across Indian secondary cities and African left-hand traffic markets where grid reliability constrains pure-electric operations.
- Fuel Cell:Proton exchange membrane systems with 700-bar hydrogen storage serve Japanese commercial corridor demonstration projects and select Australian heavy fleet trials.
- Range Extender:Series-hybrid configurations with onboard gasoline generators address range anxiety in Southeast Asian markets with sparse fast-charging coverage along intercity routes.
Battery Electric commands the dominant revenue share, with Plug-in Hybrid expanding most quickly in charging infrastructure gap markets.
End User:
Customer type determines warranty structure, residual value guarantees, and software subscription bundling, with fleet contracts demanding telematics integration that private sales rarely require.
- Commercial Fleets:Logistics operators and corporate mobility managers in Sydney and Mumbai specify bundled charging infrastructure, predictive maintenance, and energy management as contract terms rather than discrete vehicle transactions.
- Private Owners:Individual purchasers in Tokyo and London prioritize home charging compatibility and manufacturer-backed battery degradation warranties over upfront acquisition cost.
- Ride-Sharing Services:Platform operators in Bangkok and Jakarta standardize on interchangeable battery swap-capable models to minimize downtime during shift changes.
- Government Agencies:Municipal procurement across the United Kingdom and Australian states mandates minimum local content thresholds and cybersecurity certification for connected vehicle architectures.
Commercial Fleets anchor procurement volume, with Government Agencies gaining share fastest as zero-emission mandates harden into enforceable quotas.
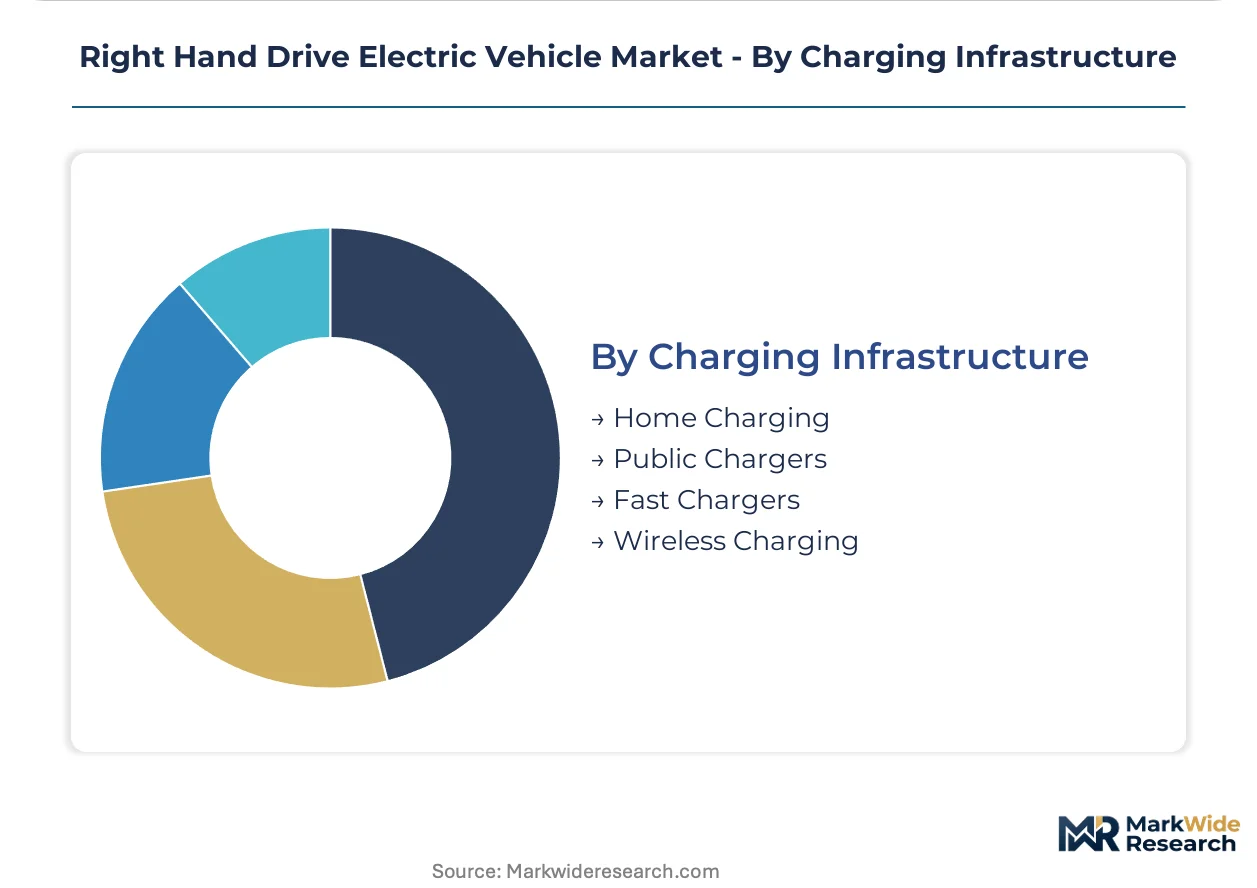
Charging Infrastructure:
Access modality shapes battery sizing, thermal management specification, and warranty terms, with high-power charging exposure accelerating cell degradation in ways that home charging rarely replicates.
- Home Charging:Overnight alternating current replenishment at 7-22 kW dominates private owner utilization patterns in the United Kingdom and Japan, enabling smaller battery configurations and extended cycle life.
- Public Chargers:Curbside alternating current infrastructure in London boroughs and Tokyo wards serves apartment dwellers without dedicated parking, though utilization rates remain below 15% at many locations.
- Fast Chargers:Direct current stations exceeding 150 kW concentrate along Australian highway corridors and Indian expressway nodes, demanding liquid-cooled cable interfaces and battery preconditioning algorithms.
- Wireless Charging:Inductive pad systems at 11-22 kW power levels pilot with taxi queues in Singapore and Seoul, requiring precise vehicle positioning and foreign object detection certification.
Home Charging retains the largest installed base, with Fast Chargers showing the steepest expansion trajectory as corridor electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Right hand drive electric vehicle manufacturing traces its modern lineage to Japanese kei-car electrification programs and United Kingdom fleet conversion mandates. These dual origins established divergent regulatory pathways that persist across Commonwealth and Japanese market spheres. Today procurement concentrates in metropolitan clusters where congestion pricing and zero-emission deadlines compress replacement cycles.
United Kingdom
Fleet operators in Greater London and Birmingham accelerate battery electric procurement ahead of zero-emission vehicle mandate deadlines. The Vehicle Certification Agency enforces UNECE type approval alignment that gates market access for Commonwealth export platforms. Manufacturing concentration in the Midlands supports right hand drive conversion programs for European-sourced platforms.
Japan
Commercial corridor operators in Tokyo and Osaka standardize on battery electric models for last-mile logistics under metropolitan environmental targets. The Ministry of Land, Infrastructure, Transport and Tourism maintains distinct crashworthiness standards that fragment certification pathways from United Kingdom or Australian approvals. Kei-car electrification in Nagoya manufacturing clusters preserves domestic supply chain density.
India
Logistics platforms in Mumbai and Delhi-NCR consolidate procurement around total cost of ownership models favoring electric drivetrains over diesel equivalents. The PLI scheme for automotive manufacturing incentivizes domestic cell production and right hand drive platform localization. Tamil Nadu and Gujarat manufacturing corridors anchor captive battery supply investments.
Australia
Mining corridor fleets in Western Australia and Queensland drive heavy-duty electric commercial vehicle trials along highway networks. Design Rules under the Department of Infrastructure specify right hand drive compliance thresholds that limit parallel import volumes. Sydney and Melbourne metropolitan procurement concentrates around depot-based charging infrastructure.
Thailand
Automotive export platforms in the Eastern Economic Corridor convert existing internal combustion capacity toward right hand drive electric assembly for Southeast Asian distribution. Board of Investment incentives target battery pack and electric motor localization. Bangkok ride-hailing operators standardize on interchangeable battery swap-capable models.
Right Hand Drive Electric Vehicle Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent homologation pathways in this market. The competitive structure fragments across Japanese, Commonwealth, and emerging market regulatory spheres rather than consolidating around unified platforms. Three archetypes dominate: established automakers with hybrid-electric heritage, state-backed Chinese manufacturers with vertical manufacturing scope, and domestic champions leveraging captive battery supply. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers front-load homologation investments.
Within the established automaker tier, Toyota Motor Corporation and Hyundai Motor Company occupy positions shaped by hybrid-electric manufacturing heritage and multi-market certification capabilities. Among state-backed manufacturers, BYD Co Ltd exemplifies vertical manufacturing scope extending into right hand drive variants. Tata Motors Limited anchors the domestic champion archetype through Indian market dominance and PLI scheme-aligned battery supply investments.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Tata Motors Limited |
| BMW Group |
| Audi AG |
| BYD Co Ltd |
| Nissan Motor Company |
| Mahindra & Mahindra Limited |
| MG Motor India Pvt Ltd |
| Others |
Value Network & Pricing Analysis
Lithium carbonate spot indices cascading through cell manufacturing economics compress pack costs for right hand drive platforms while amplifying pricing power for producers with captive cathode supply. Battery chemistry selection separates premium long-range variants from standard fleet configurations across Commonwealth procurement markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates right hand drive electric vehicle transactions. Price differentiation hinges on battery capacity certification under United Kingdom Vehicle Certification Agency protocols and fleet volume scale. Pricing pressure stems from lithium iron phosphate cell oversupply in Chinese manufacturing hubs. Commercial fleet operators in Mumbai and Sydney exhibit highest price sensitivity; premium private buyers in Tokyo show lowest.
Supply Chain Analysis
Certification gating through Japan's Ministry of Land, Infrastructure, Transport and Tourism and Australia's Design Rules fragments supplier qualification pathways. Manufacturing concentrates in China, South Korea, and Japan for lithium-ion cells; Thailand and India for right hand drive assembly. Raw material dependencies span lithium carbonate, nickel sulfate, and rare earth permanent magnets. Single-source vulnerability pervades Japanese homologation engineering talent. Distribution runs through OEM captive networks and fleet direct contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The right hand drive electric vehicle market functions as a regulatory compounder where the United Kingdom's zero-emission vehicle mandate hardens demand visibility across Commonwealth-aligned procurement channels.
For Market Incumbents: Anticipate margin compression from state-backed Chinese manufacturers expanding into Australian and Southeast Asian export channels. Defend positioning through backward integration into battery cell production under India's PLI scheme and accelerated homologation investment for simultaneous United Kingdom-Japan certification. For New Entrants and Emerging Players: Fleet charging infrastructure providers offer partnership pathways into bundled electrification contracts. White-space concentrates in Indian secondary cities and African left-hand traffic markets where plug-in hybrid architectures bridge charging infrastructure gaps. Penetrate through depot-based energy management service bundling rather than discrete vehicle sales. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic champions possessing captive battery supply and single-country regulatory dominance. Long-term viability favors producers securing Tamil Nadu or Gujarat manufacturing corridors with PLI-aligned cell investments. Watch for United Kingdom zero-emission mandate enforcement intensity as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive lithium iron phosphate cell access insulates Tata Motors from commodity volatility under India's PLI scheme. |
| Software-Defined Vehicle Investment | Over-the-air capability opens recurring revenue streams for Toyota serving Tokyo ride-hailing fleets. |
| Geographic Manufacturing Footprint | Thailand's Eastern Economic Corridor conversion enables BYD right hand drive export scale across Southeast Asia. |
| Charging Infrastructure Partnership | Depot-based bidirectional hardware converts London logistics fleets into distributed grid storage assets. |
| Platform Standardization | Unified architectures reduce homologation burden across United Kingdom and Australian Design Rules compliance. |
Research Methodology
Direct dialogue with OEM platform engineers, fleet procurement managers, homologation consultants, and charging infrastructure developers grounded qualitative findings. Secondary validation drew from United Kingdom Vehicle Certification Agency type approval registers, Australian Design Rules amendments, Indian PLI scheme disbursement records, and IHS Markit vehicle registration databases. Bottom-up unit economics modeling triangulated against top-down market sizing across the analysis window.
Bottom-up segmentation modeling aggregated vehicle class, propulsion architecture, and regional production cluster dimensions. Top-down macro validation incorporated regulatory mandate timelines and battery cost curve assumptions throughout the forecast period. CAGRs derived from logistic curve adoption modeling fitted to fleet replacement cycle data and congestion pricing policy trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium carbonate price volatility and Japanese-Australian regulatory divergence. Forecasts reflect documented assumptions regarding PLI scheme continuity and United Kingdom mandate enforcement. A model refresh is warranted upon material change in Japanese Ministry of Land, Infrastructure, Transport and Tourism certification protocol alignment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
India Electric Vehicle Financing Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
Electric Van Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market