
 Colombia Fruits and Vegetables Market | 2026-2036
Colombia Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Fruits and Vegetables Market Outlook
Antioquia's avocado packing cooperatives is pivoting toward export-grade certification to capture premium European channels. Greenyard Fresh Colombia leverages integrated cold-chain logistics to sustain year-round supply consistency for supermarket clients. Banacol anchors Atlantic coast banana operations with scale advantages in port-adjacent ripening infrastructure. Daabon Group differentiates through organic certification depth that commands price premiums in North American retail.
Colombia fruits and vegetables encompass fresh and minimally processed plant products cultivated across altitudinal zones from sea-level plantains to Andean stone fruits, requiring controlled-atmosphere storage at 0-4°C for shelf-life extension beyond fourteen days. The category serves domestic food security, foodservice ingredient supply, and export revenue generation through phytosanitary-compliant shipments. Avocados and bananas dominate volume throughput due to established grafting protocols and coast-to-port logistics density, while online retail channels represent the fastest-expanding distribution vector as urban consumers bypass traditional intermediaries. Health-conscious buyers concentrate margin pools through willingness to pay for organic and pesticide-residue-tested SKUs.
INVIMA enforces sanitary registration and Good Agricultural Practice audits that determine export eligibility for Colombian producers accessing regulated markets. The USDA equivalency agreement shapes phytosanitary inspection intensity for avocado and mango shipments to United States ports. Stakeholders must monitor how EU deforestation-free supply chain due diligence rules redirect investment toward traceable farm-gate sourcing systems.
Market Dynamics
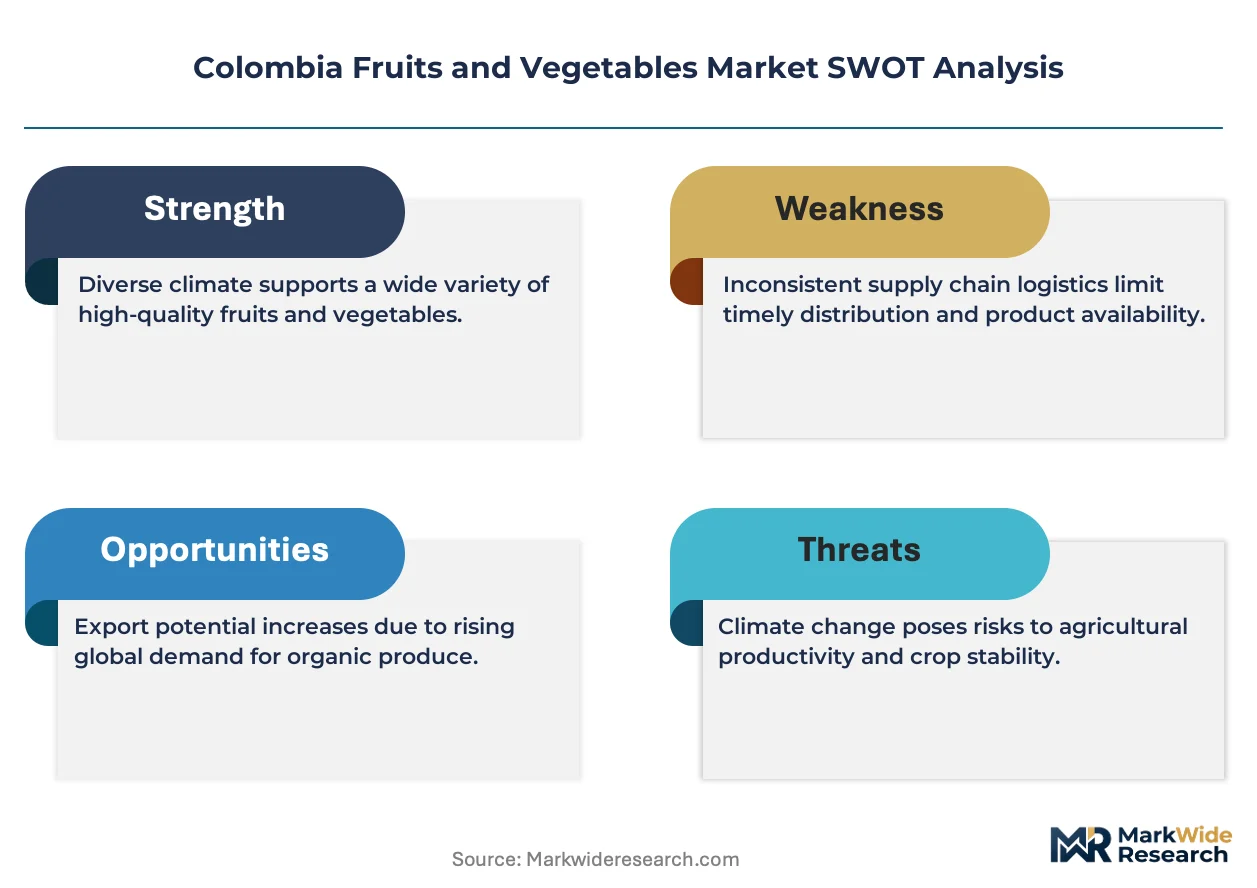
INVIMA's escalating sanitary audit frequency is compressing export readiness timelines for Colombian avocado and mango packers. Cold-chain infrastructure gaps in the Coffee Axis corridor force producers to consolidate around port-adjacent ripening facilities.
Growth Catalysts
- INVIMA Certification Acceleration:The national sanitary regulator's streamlined Good Agricultural Practice audits are shortening export eligibility windows for tropical fruit producers targeting North American retail channels.
- Restaurant Procurement Consolidation:Premium foodservice buyers in Bogotá and Medellín are establishing direct farm-gate contracts that bypass traditional wholesale intermediaries.
- Post-Harvest Infrastructure Investment:Controlled-atmosphere storage deployment across Antioquia and Valle del Cauca is extending shelf life for high-value stone fruits and berries.
Market Restraints
- Fuel Cost Volatility:Diesel price fluctuations directly compress margins for trucking-dependent producers moving product from Andean growing regions to Atlantic and Pacific ports.
- Atlantic Coast Logistics Concentration:Banana and plantain throughput dependence on Cartagena and Barranquilla port infrastructure creates single-point vulnerability for export volumes.
- Phytosanitary Equivalency Delays:USDA inspection intensity variations for mango shipments introduce unpredictable clearance timelines at United States entry points.
Strategic Opportunities
- EU Deforestation-Free Compliance:The European Union's supply chain due diligence rules are redirecting investment toward traceable farm-gate sourcing systems that command premium positioning.
- Online Retail Channel Expansion:Urban consumers in Cali and Bucaramanga are bypassing traditional market intermediaries through direct-to-home produce delivery platforms.
- Organic Certification Depth:Pesticide-residue-tested and organic SKUs attract health-conscious buyers willing to pay tiered premiums in domestic supermarket channels.
Industry Challenges
- Cold-Chain Technician Scarcity:Controlled-atmosphere equipment maintenance and refrigerated transport logistics require specialized skills that outpace vocational training output in growing regions.
- Export Facility Capex Burden:INVIMA-compliant packing house construction and port-adjacent ripening infrastructure demand capital commitments that strain cooperative balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Fruits and Vegetables Market |
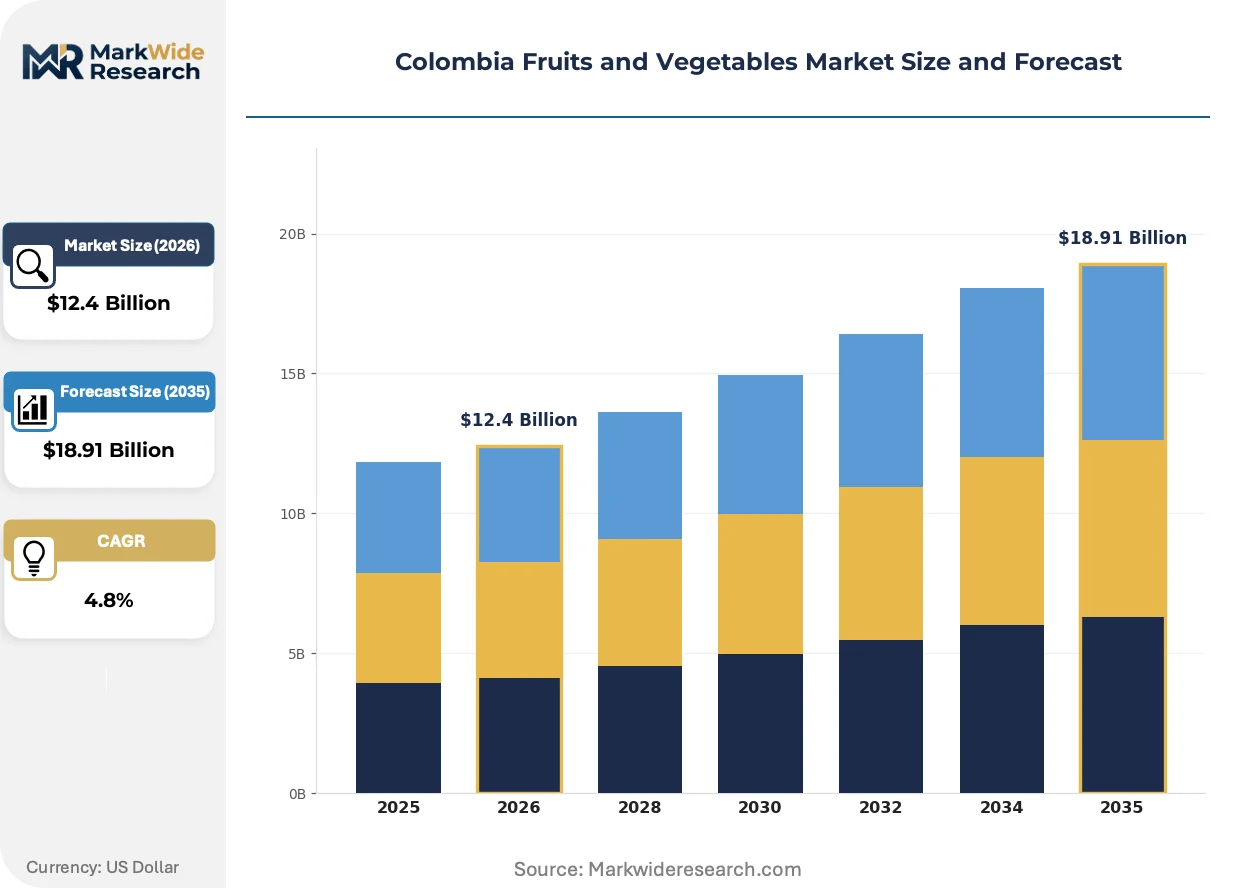
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Avocados, Bananas, Mangoes, Tomatoes Distribution Channel: Supermarkets, Farmers' Markets, Online Retail, Wholesalers Consumer Segment: Health-Conscious Buyers, Families, Restaurants, Exporters Seasonality: Peak Season, Off-Season, Year-Round, Transitional |
| Companies Covered | Greenyard Fresh Colombia, Fruti Reyes, Uniban S.A., CI Agrofrut SA, Listo & Fresco Ltda., Banacol, Daabon Group, FRUVECO S.A., Grupo Cartama, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Fruits and Vegetables Market Strategic Shifts
Digital traceability platforms and precision agriculture tools are compressing information asymmetries between Colombian growers and international buyers. These technologies reshape how quality premiums are captured and verified across the value chain.
Blockchain-enabled provenance tracking is unifying farm-gate data with retail shelf claims for avocado and banana shipments. European supermarket chains now mandate lot-level traceability as a procurement condition. This unifying technology is collapsing the information gap that previously separated smallholder cooperatives from premium channel access.
INVIMA's alignment with FDA-equivalent protocols is intensifying documentation requirements for export-bound operations. Producers must now maintain continuous temperature logs and sanitary registration records across the post-harvest chain. Medium-scale packing cooperatives in Antioquia face the steepest compliance adaptation costs as they scale toward international eligibility.
Urban consumer purchasing is fragmenting across multiple channels as traditional wholesale markets lose share. Direct sourcing apps and supermarket e-commerce platforms now capture produce transactions that previously flowed through central market intermediaries. This behavioral shift concentrates most visibly in Bogotá's affluent northern districts where time-scarcity drives premium convenience positioning.
Colombia Fruits and Vegetables Market Segmentation
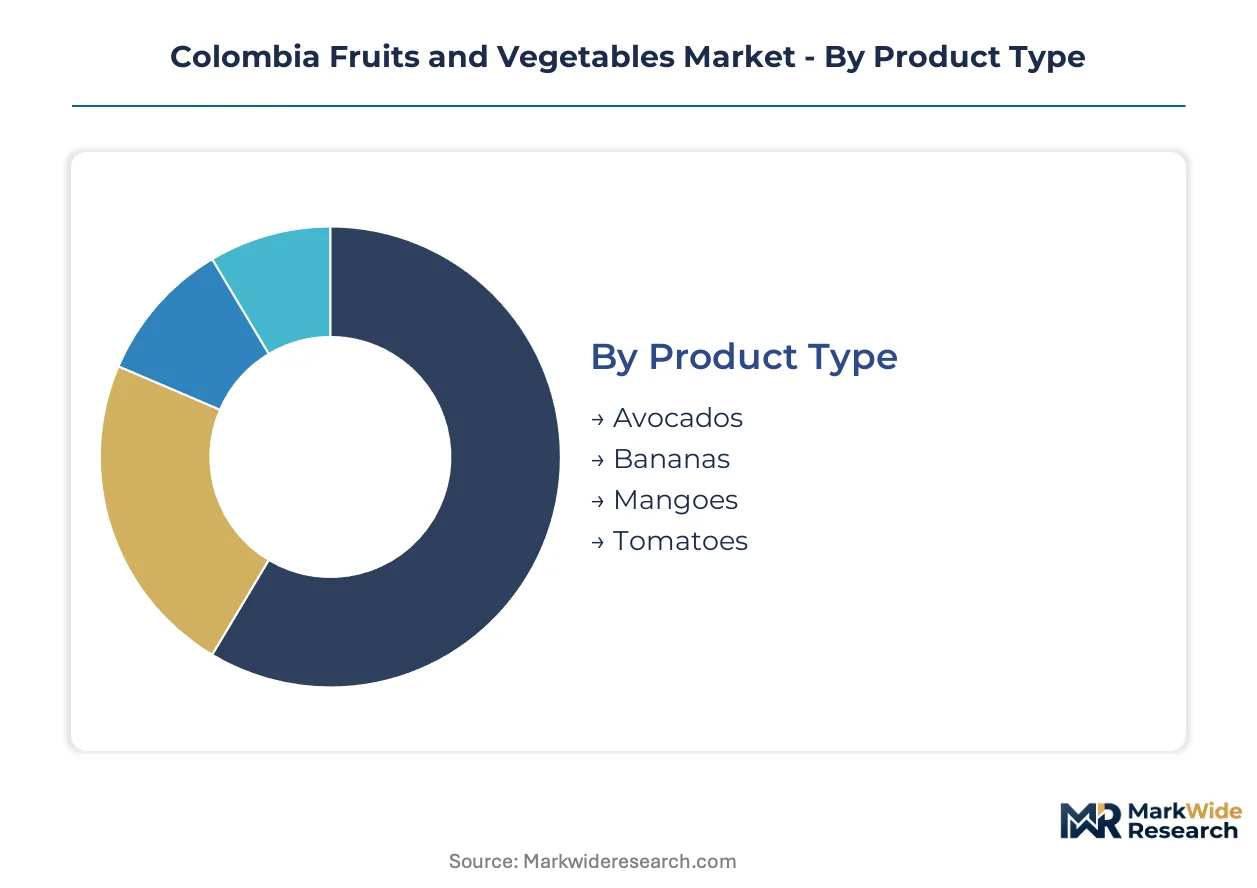
Colombia's altitudinal diversity and dual domestic-export demand structure create distinct segment performance profiles. Product type and distribution channel splits reveal where cold-chain investment and phytosanitary compliance concentrate value capture.
Product Type:
Standalone export commodities dominate revenue pools, while embedded domestic-use categories serve different margin structures.
- Avocados:Hass and Fuerte varieties require controlled-atmosphere storage at 4-6°C to maintain oil content above 8% for European supermarket eligibility. Antioquia's packing cooperatives are consolidating around INVIMA export certification to access premium Dutch and German retail channels.
- Bananas:Cavendish cultivars move through coast-adjacent ripening infrastructure at Cartagena and Barranquilla, with Daabon Group's organic-certified operations commanding tiered premiums in North American retail. Atlantic port logistics density creates scale advantages unavailable to interior growers.
- Mangoes:Tommy Atkins and Kent varieties face USDA inspection intensity variations that introduce unpredictable clearance timelines at United States entry points.
- Tomatoes:Cherry and beefsteak varieties serve Bogotá and Medellín foodservice contracts with shorter shelf-life requirements than export-oriented fruits.
Bananas lead volumes today; avocados are gaining share fastest.
Distribution Channel:
Channel selection determines cold-chain intensity and margin retention for Colombian producers.
- Supermarkets:Greenyard Fresh Colombia leverages integrated logistics to sustain year-round supply consistency for Exito and Carulla banners, with private-label programs demanding pesticide-residue documentation. This channel concentrates margin pools through consolidated procurement power.
- Online Retail:Direct-to-home platforms in Cali and Bucaramanga bypass traditional market intermediaries, capturing time-scarce urban consumers willing to pay convenience premiums. Last-mile refrigerated delivery requirements strain operator economics outside Bogotá's northern districts.
- Farmers' Markets:Traditional plaza de mercado channels retain volume leadership in secondary cities with weaker cold-chain penetration.
- Wholesalers:Central market intermediaries in Paloquemao and Minorista are losing share to farm-gate contracting as restaurant procurement consolidates.
Supermarkets lead volumes today; online retail is expanding most quickly.
Consumer Segment:
End-user type shapes certification requirements and price elasticity across the value chain.
- Restaurants:Premium foodservice buyers in Bogotá's Zona G and Medellín's El Poblado establish direct farm-gate contracts for tropical produce, bypassing wholesale markups. Chef-driven procurement demands consistent sizing and traceability documentation.
- Exporters:European supermarket chains mandate lot-level blockchain traceability as a procurement condition, collapsing information asymmetries for compliant cooperatives.
- Health-Conscious Buyers:Organic and pesticide-residue-tested SKUs attract tiered premiums in domestic supermarket channels.
- Families:Price-sensitive household procurement concentrates in traditional market channels with minimal certification requirements.
Restaurants lead value capture today; exporters are climbing the fastest.
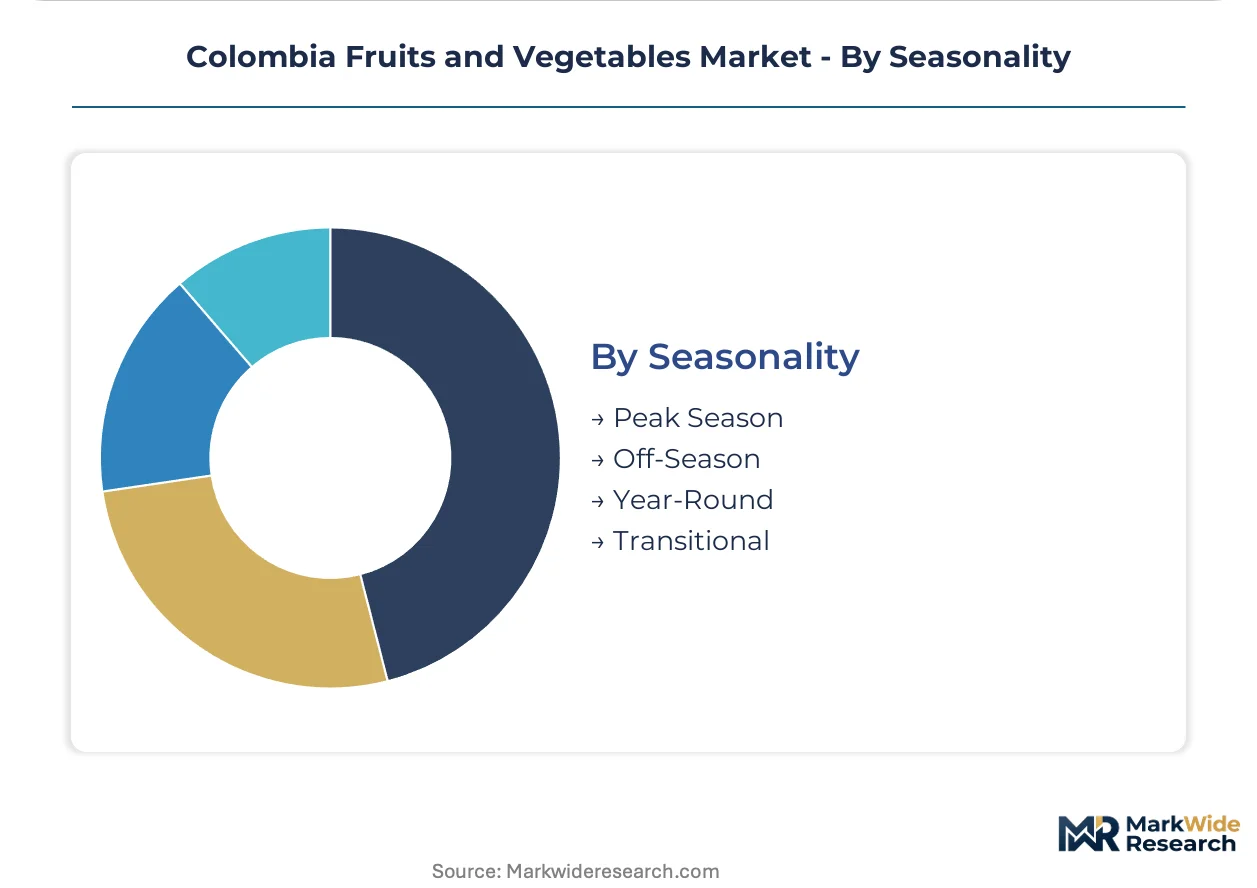
Seasonality:
Temporal supply patterns determine post-harvest infrastructure utilization rates.
- Year-Round:Banana production maintains continuous harvest cycles through Atlantic coast irrigation, sustaining port infrastructure utilization.
- Peak Season:Mango and avocado harvest windows concentrate labor demand and cold-chain bottlenecks in Valle del Cauca.
- Off-Season:Controlled-atmosphere storage deployment extends stone fruit availability during supply gaps.
- Transitional:Weather-dependent harvest shifts create procurement uncertainty for supermarket category managers.
Year-Round supply leads volume stability today; Peak Season categories show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as growers migrate toward sub-regions with lower compliance-cost structures. INVIMA audit intensity varies across Colombia's growing zones, creating cost-of-compliance gaps that influence investment flows. The Coffee Axis corridor, Atlantic coast, and Pacific lowlands each present distinct regulatory and logistics profiles.
Antioquia
Hass avocado expansion drives land-use conversion in the Aburrá Valley and eastern highlands. INVIMA Good Agricultural Practice audits concentrate in this department due to export-certification demand. Medellín anchors post-harvest infrastructure investment with controlled-atmosphere storage facilities serving European supermarket contracts.
Valle del Cauca
Sugar cane conversion to fruit cultivation accelerates as growers seek higher-margin export crops. The national sanitary regulator maintains regional inspection offices in Cali to streamline certification timelines. Palmira and Buga host expanding mango packing operations targeting USDA-compliant shipments.
Cundinamarca
Andean stone fruit production serves Bogotá's restaurant procurement consolidation with shorter logistics loops. INVIMA registration requirements for domestic foodservice are less stringent than export protocols, reducing compliance burdens. Zipaquirá and Chía cluster greenhouse tomato operations supplying capital-city supermarket banners.
Magdalena
Banana and plantain throughput depends on Cartagena port-adjacent ripening infrastructure with coast-specific phytosanitary protocols. The Atlantic coast logistics concentration creates single-point vulnerability for export volumes. Santa Marta's irrigated lowlands sustain year-round production cycles unavailable in Andean zones.
Meta
Oil palm displacement by fruit cultivation is emerging as land-tenure dynamics shift toward agricultural diversification. The country's national sanitary regulator is extending audit capacity to this llanos frontier to capture expanding production. Villavicencio serves as a logistics hub connecting eastern plains growing regions to Bogotá distribution channels.
Colombia Fruits and Vegetables Market Competitive Environment
Antioquia-based producers anchor the export-certification tier; Atlantic coast specialists hold scale advantages in port-adjacent operations. The vendor base distributes across cooperative, family-owned, and integrated corporate structures with varying capital access. Three archetypes dominate: integrated logistics operators, organic-certified specialists, and cooperative packers. Competitive moves concentrate on cold-chain infrastructure expansion and farm-gate traceability system deployment.
Within the integrated logistics tier, Greenyard Fresh Colombia and Banacol exemplify operators with port-proximate ripening infrastructure and supermarket contract consolidation. Daabon Group occupies a position in the organic-certification archetype, commanding price premiums through residue-tested supply chains. Cooperative packers in Antioquia, represented by CI Agrofrut SA, sit within the export-readiness segment as they scale toward INVIMA eligibility for European retail channels.
| Leading Market Players |
|---|
| Greenyard Fresh Colombia |
| Fruti Reyes |
| Uniban S.A. |
| CI Agrofrut SA |
| Listo & Fresco Ltda. |
| Banacol |
| Daabon Group |
| FRUVECO S.A. |
| Grupo Cartama |
| Others |
Value Chain & Pricing Dynamics
European supermarket chains mandating lot-level blockchain traceability for avocado and banana shipments are forcing Colombian packers to absorb certification costs that compress farm-gate returns while elevating retail shelf prices for compliant SKUs.
Pricing Analysis
Retailer markup layers dominate final consumer pricing, with supermarket banners capturing margin pools through consolidated procurement power and private-label programs demanding pesticide-residue documentation. Pricing stratifies across organic-certified premium tiers, conventional export-grade tiers, and domestic economy tiers, with certification depth and cold-chain integrity as primary differentiation drivers. Cost compression in the domestic economy tier is intensifying because fuel volatility and INVIMA compliance investments strain cooperative balance sheets. Price-sensitive family households concentrate in traditional plaza de mercado channels, while least-sensitive health-conscious buyers absorb tiered premiums for residue-tested supermarket SKUs.
Supply Chain Analysis
Dual-sourcing requirements from European retail procurement desks are compelling Colombian avocado packers to qualify multiple Antioquia cooperatives simultaneously, fragmenting volume commitments across smaller operators. Geographic supply concentration centers on Colombia's Coffee Axis corridor, Ecuador's parallel Andean production zones, and Peru's emerging avocado belt as alternative origins. Raw material dependencies include grafted Hass rootstock, controlled-atmosphere equipment, and diesel for Andean-to-port trucking. Single-source vulnerability runs through Cartagena and Barranquilla port infrastructure for Atlantic coast banana volumes. Distribution runs through integrated logistics operators with port-adjacent ripening facilities serving supermarket contract consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
INVIMA's alignment with FDA-equivalent protocols functions as a regulatory compounder, accelerating export eligibility demand for compliant packers while disqualifying lagging cooperatives from premium channel access.
For Market Incumbents: Anchor cold-chain infrastructure expansion in port-proximate locations to defend supermarket contract consolidation against emerging logistics operators. Deepen backward integration into grafted rootstock propagation to secure varietal consistency for European oil-content specifications. Certification investment in organic and residue-tested tiers serves as the primary margin defense against price erosion in conventional export segments. For New Entrants and Emerging Players: Capture white-space in direct-to-home online retail channels across Cali and Bucaramanga, where last-mile refrigerated delivery gaps strain incumbent economics. The most penetrable segment lies in time-scarce urban professionals bypassing traditional market intermediaries. A farm-gate sourcing app paired with subscription box logistics offers the clearest go-to-market angle for bypassing established wholesale layers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale Antioquia packing cooperatives approaching INVIMA export certification thresholds, where compliance completion unlocks immediate European retail channel access. Long-term viability over the coming decade hinges on traceability infrastructure deployment and deforestation-free supply chain verification. The signal to watch as inflection indicator is EU due diligence rule enforcement intensity redirecting procurement toward fully traceable farm-gate systems.| Strategic Initiative | Industry Significance |
|---|---|
| INVIMA Export Certification Investment | Unlocks premium European retail channel access for Antioquia avocado cooperatives previously confined to domestic markets. |
| Blockchain Traceability Deployment | Collapses information asymmetries between smallholder farms and supermarket procurement desks demanding lot-level provenance. |
| Port-Adjacent Ripening Infrastructure | Consolidates banana throughput scale advantages at Cartagena and Barranquilla against interior growers facing logistics bottlenecks. |
| Organic Certification Depth Expansion | Commands tiered price premiums in North American retail channels where Daabon Group has established residue-tested positioning. |
| Direct-to-Consumer Platform Launch | Bypasses Paloquemao and Minorista wholesale intermediaries for Bogotá's affluent northern districts seeking convenience. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cold-chain logistics directors, INVIMA compliance officers, supermarket category buyers, cooperative packing managers, and port operations specialists with secondary validation. Secondary sources included Colombian customs export records, INVIMA sanitary registration databases, USDA phytosanitary inspection protocols, EU deforestation-free supply chain guidance documents, and controlled-atmosphere equipment manufacturer technical specifications. Bottom-up volume aggregation from departmental production statistics and top-down demand validation from import-country entry data provided cross-check triangulation.
Comparable-period anchoring linked projection assumptions to historical harvest cycles, export certification timelines, and infrastructure investment patterns across the analysis window. Segmentation dimensions modeled encompassed product type, distribution channel, consumer segment, and seasonal supply pattern. CAGRs derived from trend extrapolation of certification acceleration rates, cold-chain deployment curves, and channel-shift velocity metrics. Industry-specific forecast inputs included INVIMA audit frequency trends and EU due diligence rule implementation phasing.
Fuel price volatility, phytosanitary equivalency negotiation delays, and cold-chain technician training output shortfalls are the dominant revision risks to the outlook. Deviation in INVIMA audit capacity expansion would shift export eligibility timelines and associated revenue capture materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Jujube Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Frozen Vegetables Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Packaged Fresh Fruits Market
Fruits and Vegetables
Cucumber and Gherkins Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
Grapefruit Peel Market
Fruits and Vegetables
Asia-Pacific Shiitake Mushroom Market
Fruits and Vegetables
Europe Dried Mushroom Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Brazil Fruits and Vegetables Market