
 Mango Puree Market | 2026-2036
Mango Puree Market Size, Share, and Industry Trends Forecast 2026-2036
Mango Puree Market Intelligence
FSSC 22000 certification is unwinding the competitive landscape for mango puree suppliers, as major retailers and co-manufacturers now require documented food safety management systems for vendor qualification. Dohler leverages its integrated fruit ingredient platform to sustain long-term supply contracts with multinational beverage brands. Cargill anchors its position through backward integration into tropical fruit sourcing networks across Southeast Asia and Latin America. Capricorn Food Products India Ltd specializes in aseptic pulp processing for export markets, competing on thermal treatment precision rather than commodity volume.
Mango puree is a homogenized, thermally processed fruit preparation typically containing 90-100% mango solids with controlled Brix levels between 14 and 28 degrees, produced through mechanical pulping, deaeration, and pasteurization to preserve color and flavor for industrial formulation. The pulp segment dominates current volume as food manufacturers standardize on single-strength puree for yogurt, ice cream, and confectionery applications. Concentrate occupies the fastest-growing structural position, since beverage brands seek reduced freight costs and extended shelf stability for remote production facilities. Frozen puree retains premium margin pools in artisanal baking and specialty dessert channels where texture integrity commands price premiums over reconstituted alternatives.
FDA enforcement of the Food Safety Modernization Act's preventive controls for human food shapes import requirements for mango puree entering the United States, while the EU's REACH and residual pesticide regulations under EFSA jurisdiction constrain which orchard sources qualify for European formulation use. India's FSSAI mandates BIS certification for packaged fruit products sold domestically, creating a dual-track compliance burden for exporters serving both local retail and international industrial buyers. Stakeholders must monitor evolving maximum residue limits across destination markets and decide whether captive orchard investments or third-party audit networks offer superior risk-adjusted compliance pathways.
Market Dynamics
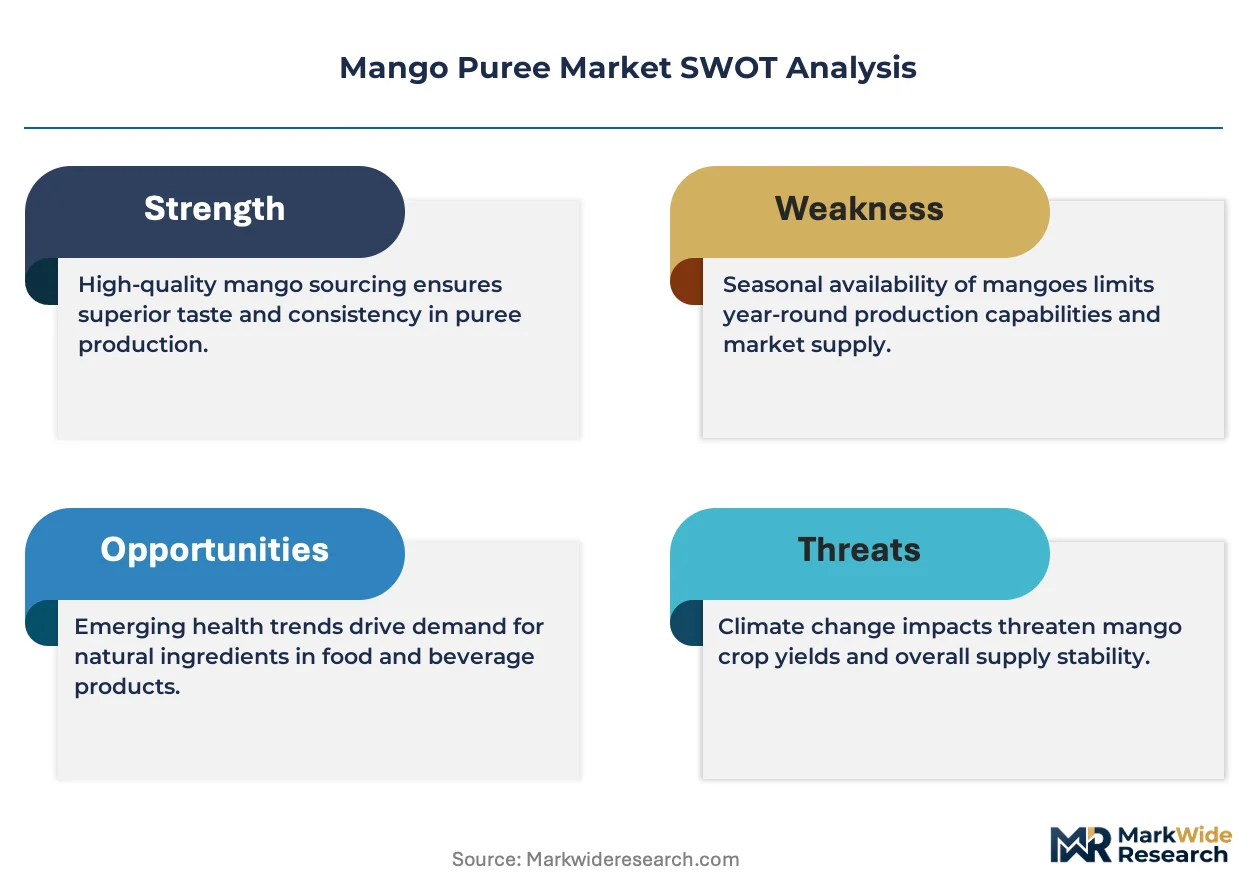
Contract farming agreements in Maharashtra and Andhra Pradesh are displacing spot-market sourcing, concentrating procurement power among integrated pulp processors with captive orchard control and FSSC 22000 certification.
Growth Catalysts
- Aseptic processing technology:Beverage manufacturers across Asia-Pacific are accelerating procurement of aseptic mango puree for smoothie and juice formulations, requiring thermal treatment precision that commodity processors cannot match.
- FSSAI residual pesticide limits:India's tightened standards for processed fruit products are pushing exporters toward integrated orchards with traceability systems, filtering out fragmented smallholder supply.
- Concentrate demand:Beverage brands seek reduced freight costs and extended shelf stability for remote production facilities, pulling formulation toward higher-Brix concentrate over single-strength pulp.
Market Restraints
- Input cost volatility:Alphonso and Totapuri mango prices fluctuate with monsoon patterns and pest pressure, compressing margins for processors locked into annual supply contracts.
- Supply concentration risk:Maharashtra and Andhra Pradesh account for disproportionate processing capacity, exposing buyers to regional climate shocks and logistics bottlenecks.
- Regulatory friction:Dual-track compliance for FSSAI domestic certification and FDA/EFSA import requirements adds audit burden and extends qualification timelines for exporters.
Strategic Opportunities
- Underpenetrated artisanal channels:Frozen puree retains premium margin pools in specialty dessert and artisanal baking segments where texture integrity commands price premiums over reconstituted alternatives.
- Regulatory tailwind:EU REACH and EFSA residual pesticide regulations favor orchard sources with documented integrated pest management, creating competitive moat for certified integrated operators.
- Technology convergence:Blockchain traceability systems combined with IoT orchard monitoring enable real-time compliance documentation for multinational co-manufacturer qualification.
Industry Challenges
- Thermal processing skill gap:Aseptic pulp processing requires specialized operators capable of maintaining pasteurization parameters within narrow bands; talent scarcity constrains capacity expansion at mid-tier facilities.
- FSSC 22000 certification timeline:Documented food safety management systems require 12-18 month implementation cycles, delaying vendor qualification for retailers and co-manufacturers with mandatory certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mango Puree Market |
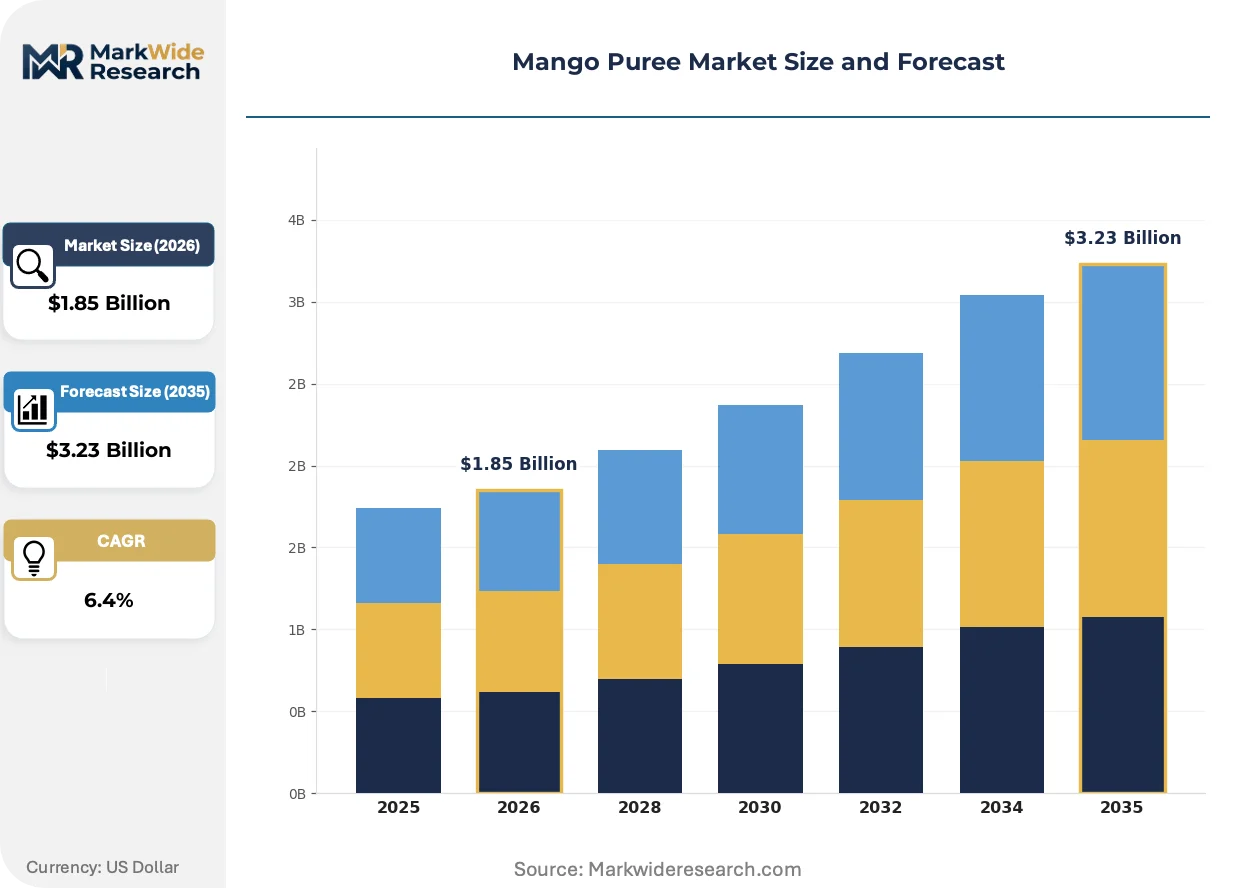
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulp, Concentrate, Frozen, Dried End User: Food Industry, Beverage Sector, Baking, Snacks Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales Packing Type: Bottles, Tetra Paks, Cans, Pouches |
| Companies Covered | SVZ International B.V., Cargill, Dohler, Kerr Concentrates, Ingredion Inc., ITC Limited, Tree Top Inc., Capricorn Food Products India Ltd, Kiril Mischeff Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mango Puree Market Strategic Shifts & Innovations
Processing technology and procurement protocols are actively reshaping competitive positioning, with thermal treatment precision and traceability systems becoming primary differentiators over commodity volume.
High-pressure processing (HPP) is fragmenting the thermal treatment landscape by preserving volatile aromatic compounds that conventional pasteurization degrades. Premium juice and smoothie brands in North America and Western Europe are adopting HPP-treated puree for clean-label positioning. This technology is fragmenting the market into flavor-differentiated premium tiers versus cost-optimized conventional pasteurization.
India's FSSAI has mandated BIS certification for packaged fruit products sold domestically, creating divergent compliance pathways for exporters serving local retail versus international industrial buyers. Processors must maintain parallel quality systems or sacrifice one market segment. Integrated operators with captive orchards are absorbing this burden more readily than contract-dependent competitors.
Buyers are consolidating vendor relationships around processors with documented backward integration into tropical fruit sourcing networks. Spot-market sourcing is contracting as multinational beverage brands demand supply security and batch traceability. This concentration is most visible in Asia-Pacific procurement offices, where technical audits now precede price negotiations in supplier selection protocols.
Mango Puree Market Segmentation
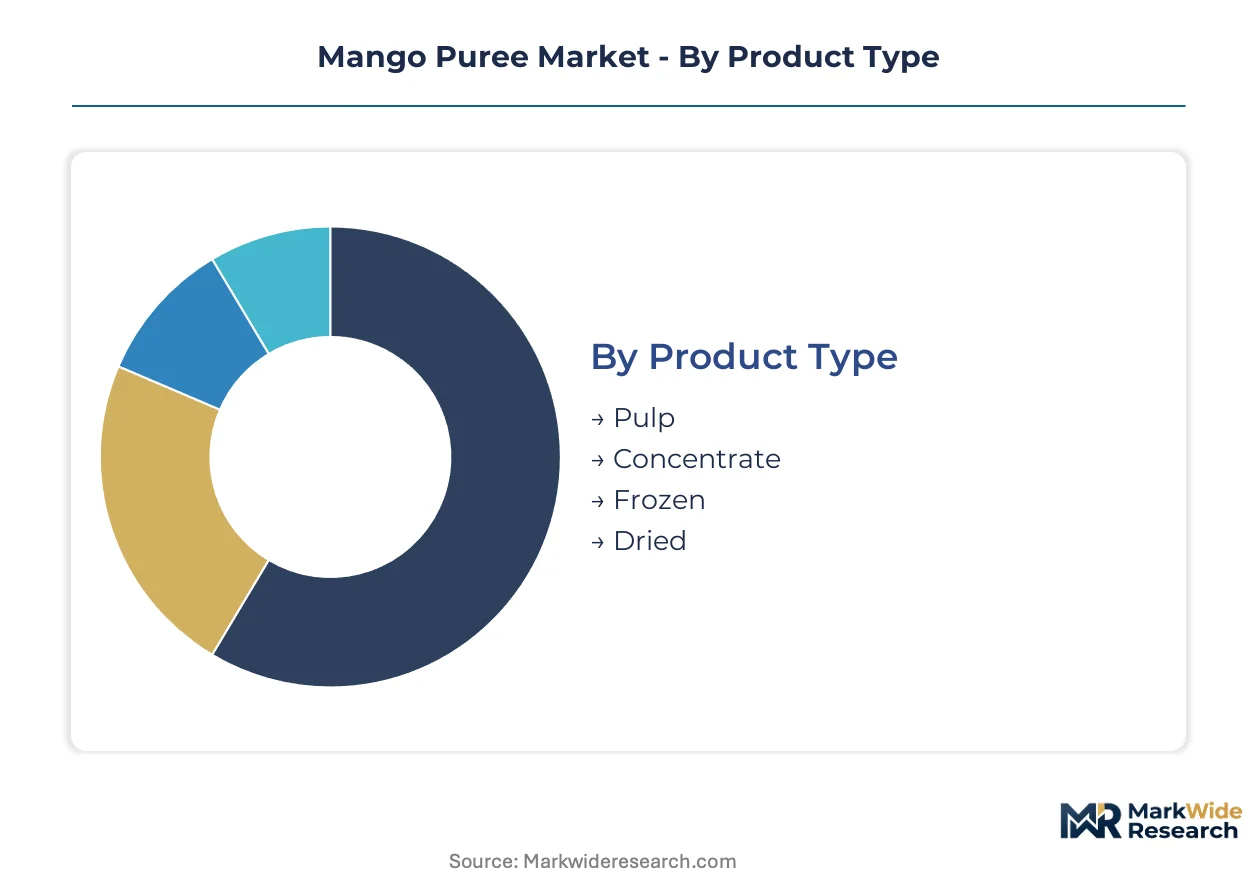
Formulation requirements diverge sharply across end-use channels, forcing processors to maintain parallel production lines with distinct thermal profiles and Brix specifications. Segmentation clarity enables buyers to match puree structural properties—viscosity, water activity, aromatic retention—to specific manufacturing constraints.
Product Type:
Premium margin pools concentrate in segments where thermal degradation risk demands precision processing equipment and batch-level documentation.
- Concentrate:Higher-Brix formulations (28-32 degrees) reduce water content for freight efficiency. Beverage manufacturers in remote production zones are pulling procurement toward concentrate to cut logistics spend and extend ambient shelf stability without refrigeration dependency.
- Pulp:Single-strength puree retains 14-22 Brix with intact fiber structure. Food manufacturers standardize on pulp for yogurt, ice cream, and confectionery where mouthfeel consistency outweighs transport cost concerns.
- Frozen:Blast-frozen at -18°C to preserve volatile aromatic compounds for artisanal baking and specialty dessert channels.
- Dried:Low-moisture powder formats for confectionery inclusions and dry mix applications requiring extended ambient stability.
The dominant share belongs to pulp, while concentrate is closing the gap fastest.
End User:
Volume concentration tracks manufacturing scale, with multinational co-manufacturers imposing qualification barriers that filter out uncertified suppliers.
- Beverage Sector:Smoothie and juice brands demand aseptic processing with documented pasteurization parameters. Asia-Pacific procurement offices now require FSSC 22000 certification before price negotiations commence.
- Food Industry:Dairy and confectionery formulators prioritize batch-to-batch color consistency for product line standardization.
- Baking:Artisanal producers pay premiums for frozen puree with intact cell structure over reconstituted alternatives.
- Snacks:Fruit leather and dried snack manufacturers favor concentrate for reduced drying energy input.
Beverage sector procurement commands the largest volume allocation, though food industry contracts deliver more stable annual offtake.
Distribution Channel:
Channel selection determines compliance documentation requirements and minimum order thresholds that exclude smaller processors.
- Direct Sales:Industrial buyers contract directly with integrated pulp processors for batch traceability and supply security. Maharashtra-based processors with captive orchard control are displacing spot-market intermediaries.
- Supermarkets:Retail private-label programs require dual FSSAI-BIS certification for domestic shelf placement.
- Specialty Stores:Gourmet and ethnic food retailers stock frozen and organic-certified SKUs at price multiples.
- Online:E-commerce platforms aggregate small-batch artisanal producers for direct-to-consumer frozen puree sales.
Direct sales channels capture the dominant procurement volume, with online expanding most quickly in premium frozen segments.
Packing Type:
Packaging technology investment separates commodity processors from operators capable of serving multinational beverage brands.
- Tetra Paks:Aseptic carton systems enable ambient distribution with 12-month shelf life. Capricorn Food Products India Ltd competes on thermal treatment precision in this format for export markets.
- Pouches:Flexible packaging reduces freight cube and material cost for food service bulk users.
- Bottles:PET and glass formats for retail-branded premium juices requiring visible product clarity.
- Cans:Metal containers for institutional food service with retort sterilization compatibility.
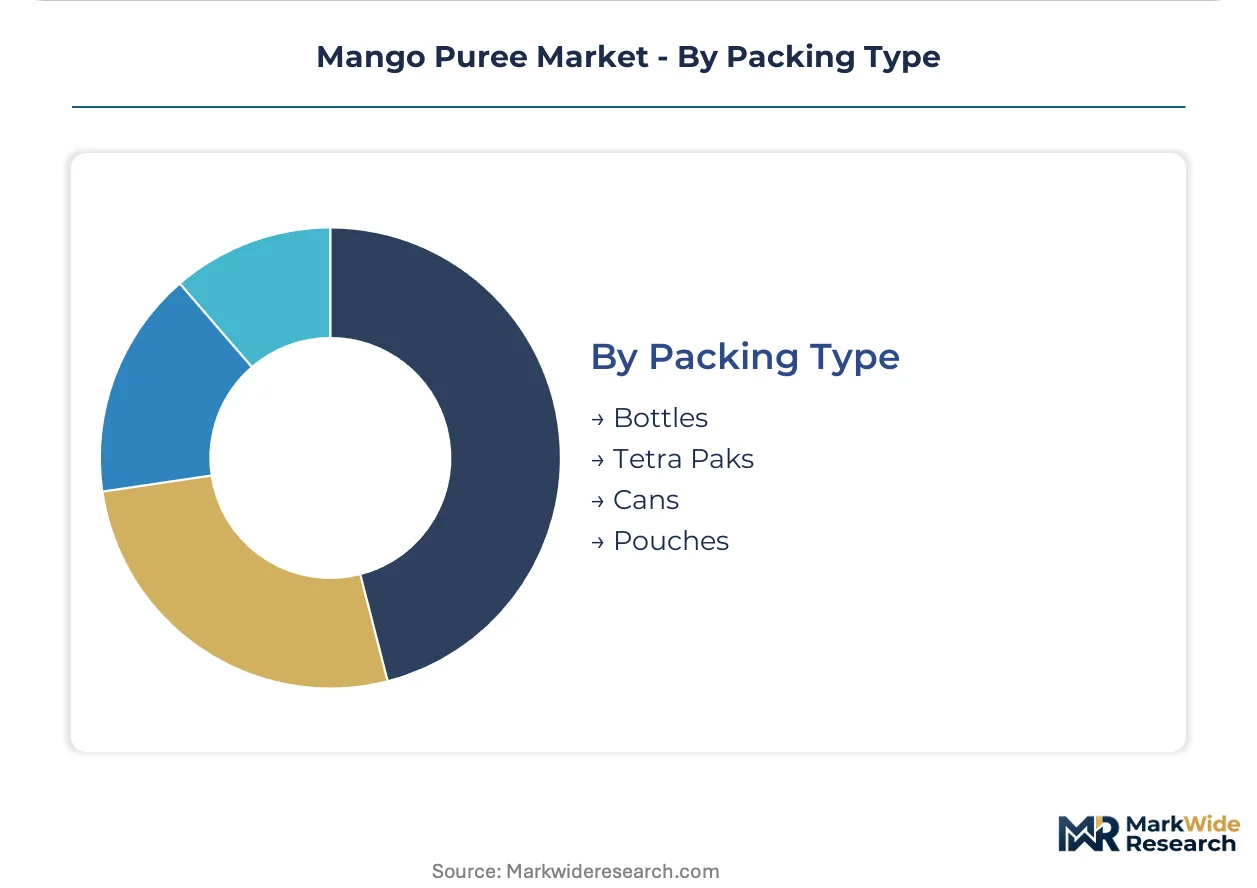
Tetra Pak aseptic formats hold the dominant position, while pouch packaging is gaining share fastest in food service channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Maharashtra handles the bulk of India's aseptic mango puree exports, connecting integrated pulp processors to European and North American beverage manufacturers. Cold chain infrastructure investments at Mundra Port in Gujarat have expanded westbound shipping capacity for frozen puree consignments. These port assets anchor South Asia's position in global tropical fruit ingredient trade.
India
Contract farming agreements in Maharashtra and Andhra Pradesh are displacing spot-market sourcing as FSSAI tightens residual pesticide limits for processed fruit products. The FSSAI mandates BIS certification for packaged fruit products sold domestically, creating dual-track compliance for exporters. Chittoor district in Andhra Pradesh hosts concentrated aseptic processing capacity where Capricorn Food Products India Ltd operates thermal treatment facilities for export markets.
United States
Beverage manufacturers in California and Florida are accelerating procurement of aseptic mango puree for smoothie and juice formulations requiring documented pasteurization parameters. FDA enforcement of the Food Safety Modernization Act's preventive controls shapes import requirements for mango puree entering the United States. Los Angeles County distribution hubs consolidate inbound shipments from Southeast Asian processors for West Coast co-manufacturers.
Germany
EU REACH and EFSA residual pesticide regulations constrain which orchard sources qualify for European formulation use, favoring suppliers with documented integrated pest management. The EFSA jurisdiction creates competitive moats for certified integrated operators over fragmented smallholder supply. Hamburg's port infrastructure serves as the primary entry point for aseptic mango puree distributed to beverage co-manufacturers across the Benelux region.
Brazil
Processors in São Paulo state leverage backward integration into tropical fruit sourcing networks across the Northeast and Amazon regions to secure supply security for multinational contracts. ANVISA regulations for processed fruit products require documented traceability systems that filter out uncertified intermediaries. The Port of Santos handles expanding volumes of concentrate shipments destined for European beverage production facilities.
Thailand
Aseptic processing facilities in Chonburi province supply mango puree to Asia-Pacific procurement offices where technical audits now precede price negotiations in supplier selection protocols. The country's national food and drug administration enforces standards aligned with CODEX guidelines for processed fruit products. Bangkok-based logistics hubs coordinate just-in-time delivery schedules for Japanese and South Korean dairy formulators.
Mango Puree Market Key Industry Players
Listed leaders compete with private specialists across certification tiers, with FSSC 22000 documentation becoming the primary vendor qualification filter for multinational beverage brands. The vendor base stratifies into three archetypes: integrated pulp processors with captive orchard control, diversified ingredient platforms with multi-fruit portfolios, and regional specialists competing on thermal treatment precision. Consolidation pressure intensifies as buyers demand supply security and batch traceability, driving M&A activity among mid-tier processors and strategic partnerships between Southeast Asian sourcers and European distributors.
Within the integrated processor tier, Capricorn Food Products India Ltd and SVZ International B.V. exemplify operators competing on aseptic thermal treatment precision rather than commodity volume. Cargill anchors the diversified ingredient platform segment through backward integration into tropical fruit sourcing networks. These three entities occupy positions that reflect the market's shift toward documented food safety management systems and captive orchard control as competitive differentiators over price-based procurement.
| Leading Market Players |
|---|
| SVZ International B.V. |
| Cargill |
| Dohler |
| Kerr Concentrates |
| Ingredion Inc. |
| ITC Limited |
| Tree Top Inc. |
| Capricorn Food Products India Ltd |
| Kiril Mischeff Ltd. |
| Others |
Cost & Logistics Intelligence
Concentrate substitution for single-strength pulp is redrawing procurement economics across Asia-Pacific beverage manufacturing, compressing freight spend while pulling processing capacity toward Maharashtra and Andhra Pradesh where integrated operators command premium positioning. This input shift simultaneously elevates Brix specification requirements and consolidates vendor relationships around FSSC 22000-certified facilities with captive orchard control.
Pricing Analysis
Certification level creates the primary spread between procurement tiers, with FSSC 22000 and BIS-certified operators capturing contract premiums from multinational beverage brands while uncertified processors compete on spot-market pulp pricing. Price differentiation hinges on thermal treatment precision and documented traceability systems, with concentrate formats commanding logistics-adjusted premiums over single-strength alternatives. Cost compression in commodity pulp is intensifying as Alphonso and Totapuri input volatility squeezes mid-tier processor margins. Beverage sector buyers exhibit lowest price sensitivity, prioritizing supply security and batch documentation over per-unit cost.
Supply Chain Analysis
Jawaharlal Nehru Port Trust throughput constraints expose European and North American buyers to seasonal bottlenecks during peak export windows. Geographic supply concentrates in India, Brazil, and Thailand, with Maharashtra and São Paulo state anchoring aseptic processing capacity. Raw material dependencies center on Alphonso, Totapuri, and Kent mango varieties with monsoon-sensitive harvest cycles. Single-source vulnerability runs through Maharashtra-Andhra Pradesh processing clusters. Distribution runs through direct industrial contracts displacing spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized aseptic thermal treatment expertise has become the constraining asset in this market, with qualified operators capable of maintaining pasteurization parameters within narrow bands commanding disproportionate procurement access. The capability gap between certified integrated processors and commodity pulp suppliers is widening vendor qualification barriers.
For Market Incumbents: Shield margin pools by accelerating backward integration into captive orchard networks across Southeast Asia and Latin America before FSSAI residual pesticide limits harden further. Invest in blockchain-IoT traceability systems to preempt EU EFSA documentation requirements. Certification investment in dual FSSC 22000-BIS pathways secures access to both domestic retail and international industrial buyer segments.
For New Entrants and Emerging Players: Differentiate on high-pressure processing technology for premium North American and Western European juice brands seeking clean-label aromatic retention. Target artisanal baking and specialty dessert channels where frozen puree texture integrity commands price multiples over reconstituted alternatives. Lead with HPP-treated concentrate formats to bypass incumbent thermal treatment scale advantages.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated operators with documented orchard control and multi-certification compliance infrastructure. Mid-tier processors lacking captive supply sources represent acquisition targets for platform roll-up strategies. Watch FSSAI enforcement intensity and EU REACH maximum residue limit revisions as inflection indicators for regulatory compliance premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Orchards | FSSAI residual pesticide limits and EU EFSA documentation requirements favor integrated operators with traceable supply. |
| High-Pressure Processing Technology Deployment | HPP-treated puree enables clean-label positioning for premium North American and Western European beverage brands. |
| Blockchain-IoT Traceability Implementation | Real-time compliance documentation accelerates multinational co-manufacturer qualification timelines. |
| Dual FSSC 22000-BIS Certification Investment | Parallel quality systems unlock both domestic retail and international industrial buyer segments. |
| Concentrate Format Capacity Expansion | Higher-Brix formulations reduce freight costs for remote Asia-Pacific beverage production facilities. |
Research Approach
Initial hypotheses were tested against primary input from procurement directors at multinational beverage brands, aseptic processing plant managers, FSSAI regulatory compliance officers, and tropical fruit sourcing specialists, then refined through secondary validation. Primary fieldwork combined structured interviews with trade data from Indian customs authorities, EU RASFF notification databases, and FDA import refusal records. Secondary sources included FSSAI gazette notifications, EFSA scientific opinions on pesticide residues, and CODEX Alimentarius processed fruit standards. Bottom-up capacity modeling and top-down demand estimation were triangulated against export shipment manifests.
Variance decomposition across product type, end-use channel, and distribution format structured the analytical framework over the projection horizon. Segmentation dimensions modeled include concentrate versus pulp versus frozen structural formats, beverage versus food industry versus baking end-use applications, and direct industrial versus retail versus online distribution channels. CAGRs were derived from shipment volume trajectories and capacity expansion announcements. Industry-specific forecast inputs encompassed monsoon pattern correlations with Alphonso pricing and FSSC 22000 certification adoption curves.
Material uncertainties — monsoon failure frequency, FSSAI maximum residue limit revisions, and EU EFSA substance re-evaluations — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline completion rates and concentrate adoption elasticity in remote production zones. Practitioners should keep alternative scenarios live as climate volatility and regulatory enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Venezuela Fruits and Vegetable Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Dry Beans Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Fresh Figs Market
Fruits and Vegetables
Pomegranate Market
Fruits and Vegetables
Europe Shiitake Mushroom Market