
 Asia-Pacific Freeze-Dried Fruits and Vegetables Market | 2026-2036
Asia-Pacific Freeze-Dried Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Freeze-Dried Fruits and Vegetables Market Outlook
Thai fruit processors is pivoting toward dedicated lyophilization lines for durian, mango, and pineapple to serve export contracts. Nagatanien Co., Ltd. leverages its heritage in traditional Japanese food preservation to anchor premium domestic distribution. Totally Pure Fruits Pty Ltd. competes through rigorous cold-chain control from Queensland orchards to drying facilities. Bajaj Agro Foods India Ltd. specializes in cost-optimized vegetable variants for institutional buyers across South Asia.
Freeze-dried fruits and vegetables retain cellular structure through sublimation at pressures below 6.1 mbar and shelf temperatures typically ranging from -40°C to -50°C, yielding products with moisture content under 5% and rehydration ratios near 1:8 for commercial food manufacturing. The fruits segment dominates volume as tropical varieties from Southeast Asia command premium positioning in export markets. Nutraceutical applications are expanding fastest, driven by clean-label encapsulation demand from supplement manufacturers in Australia and Japan. Supermarkets remain the primary distribution channel, though online retail is gaining traction among urban households seeking single-serve snack formats.
FSSAI in India enforces pesticide residue limits and labeling standards that directly determine which freeze-dried imports reach food processors. Japan's METI and PMDA coordinate on novel food ingredient approvals, creating compliance gateways for functional fruit powders. Australia's TGA monitors therapeutic claims on nutraceutical products containing freeze-dried botanicals. Stakeholders must track evolving shelf-life testing protocols and country-of-origin documentation requirements as cross-border e-commerce channels multiply.
Market Dynamics
Vacuum freeze-drying equipment upgrades across India and Southeast Asia are compressing processing timelines while tightening contaminant controls reshape procurement criteria for export-bound processors.
Growth Catalysts
- FSSAI contaminant thresholds:India's tightened pesticide residue limits for processed foods push domestic processors toward vacuum freeze-drying equipment that delivers sub-5% moisture content.
- Pet food ingredient demand:Premium pet food brands in China's urban coastal provinces source low-moisture tropical fruit ingredients for clean-label formulations.
- Queensland-to-Asia cold chains:Australian orchard operators are extending controlled-atmosphere logistics directly into Southeast Asian manufacturing clusters.
Market Restraints
- Energy-intensive sublimation:Maintaining shelf temperatures at -40°C to -50°C and pressures below 6.1 mbar requires continuous high-load electricity input.
- Durian supply concentration:Thai processors depend on narrow seasonal windows and specific cultivar availability from Chanthaburi and Rayong provinces.
- Conventional drying substitution:Air-dried and osmotic-dehydrated alternatives from Vietnam and the Philippines compete at lower price points for institutional buyers.
Strategic Opportunities
- Infant nutrition encapsulation:Clean-label fruit powder demand from Australian and Japanese supplement manufacturers opens nutraceutical white space.
- Single-serve online retail:Urban households in Shanghai, Bangkok, and Jakarta are migrating snack purchases from supermarkets to direct-to-consumer platforms.
- METI novel food approvals:Japan's coordinated ingredient gateway creates regulatory tailwinds for functional botanical powders with therapeutic positioning.
Industry Challenges
- Lyophilization technician scarcity:Operating sublimation chambers and managing condenser defrost cycles requires specialized training unavailable in most Vietnamese and Indonesian processing zones.
- Cross-border e-commerce documentation:Multiplication of country-of-origin verification requirements and shelf-life testing protocols strains compliance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Freeze-Dried Fruits and Vegetables Market |
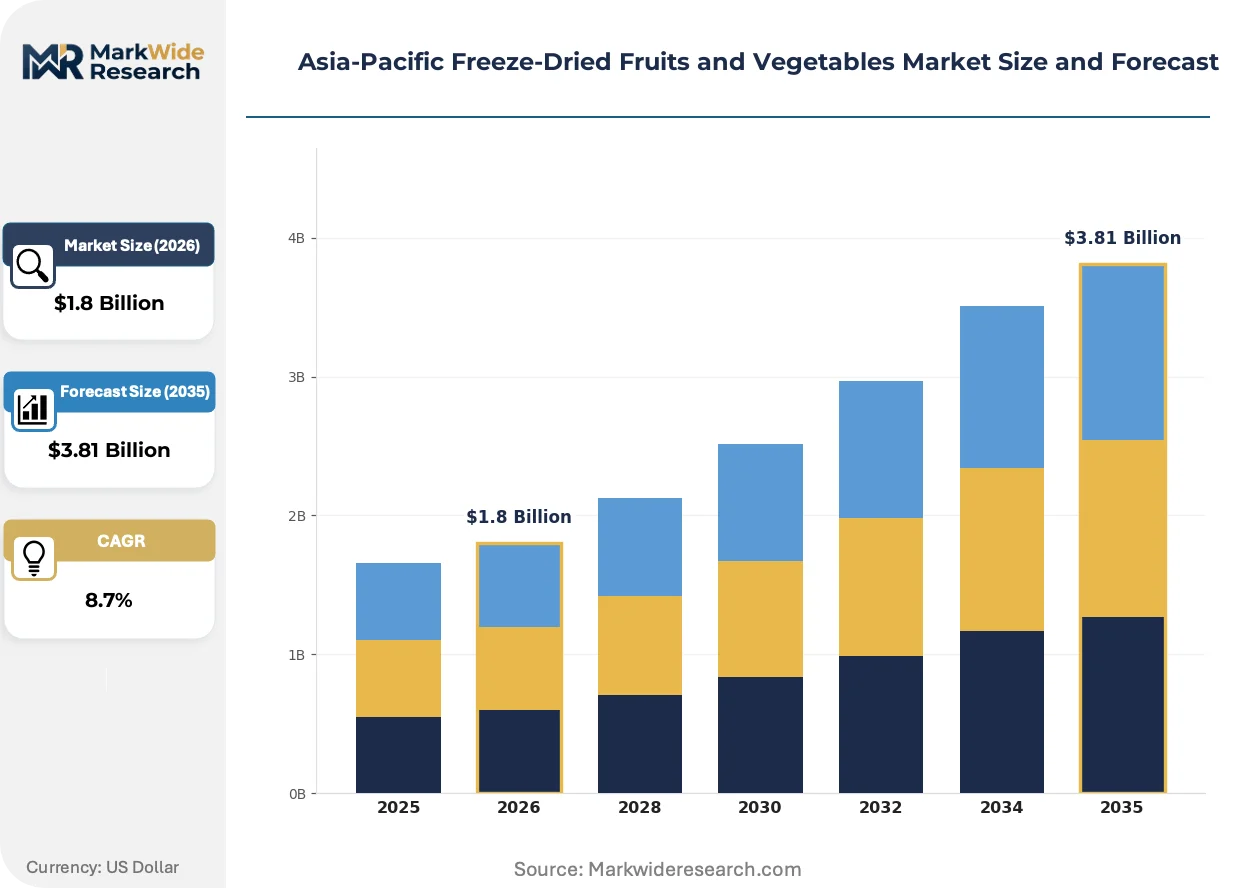
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Mixes, Snacks Application: Food & Beverage, Nutraceuticals, Ingredients, Retail Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers End User: Restaurants, Households, Food Processors, Caterers |
| Companies Covered | Nagatanien Co., Ltd., Totally Pure Fruits Pty Ltd., Bajaj Agro Foods India Ltd., Asahi Group Holdings, Ltd., Ajinomoto Co., Inc., Thai Ao Chi Fruits Co., Ltd., Nutra Grand Co., Ltd., Saraf Foods Ltd., Mercer Foods LLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Freeze-Dried Fruits and Vegetables Market Strategic Shifts
Equipment miniaturization and modular drying units are redrawing capital deployment patterns across Southeast Asian fruit processing zones.
Radio-frequency-assisted freeze-drying is decentralizing production geography by enabling smaller-batch operations without industrial-scale vacuum chambers. Regional cooperatives in Vietnam's Mekong Delta are adopting 50-kg capacity units for pineapple and dragon fruit. This technology is decentralizing supply concentration away from centralized Bangkok and Ho Chi Minh City facilities toward orchard-proximate micro-processing sites.
Australia's TGA monitoring of therapeutic claims on nutraceutical products containing freeze-dried botanicals is tightening label substantiation requirements. Supplement manufacturers must now commission stability studies before functional positioning. Australian and Japanese brands are responding by segregating cosmetic-grade from therapeutic-grade production lines.
Brand procurement teams in China's infant nutrition sector are compressing supplier qualification cycles from 18 months to 9 months. Direct technical audits of Queensland drying facilities are replacing third-party certification reliance. This acceleration is most visible among coastal province formulators targeting premium positioning in tier-one cities.
Asia-Pacific Freeze-Dried Fruits and Vegetables Market Segmentation
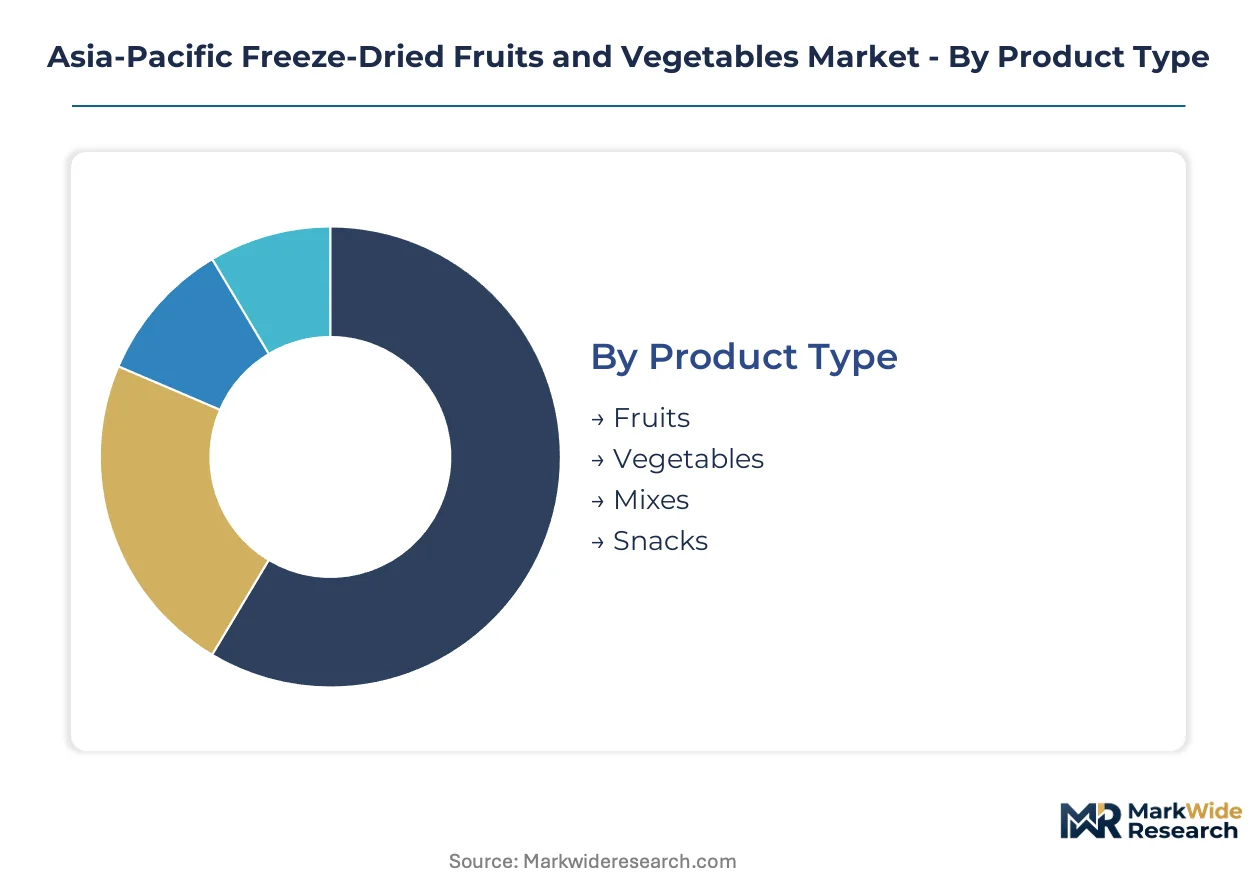
Freeze-dried product specifications vary sharply across end-use requirements, from sub-5% moisture thresholds for infant nutrition to rehydration ratios near 1:8 for commercial food manufacturing. Procurement patterns in this market track directly to application-driven quality tiers and channel-specific packaging formats.
Product Type:
Supply concentration in Southeast Asian processing zones favors fruit-dominant output, with equipment configurations optimized for tropical varieties versus temperate vegetables.
- Fruits:Tropical varieties—durian, mango, pineapple, dragon fruit—undergo sublimation at pressures below 6.1 mbar and shelf temperatures of -40°C to -50°C, preserving cellular structure for premium export positioning. Demand concentrates in China's urban coastal provinces, where premium pet food and infant nutrition brands source low-moisture ingredients for clean-label formulations.
- Vegetables:Cost-optimized variants target institutional buyers across South Asia, with vacuum freeze-drying equipment upgrades in India compressing processing timelines while meeting FSSAI contaminant thresholds. Procurement from domestic processors is accelerating as tightened pesticide residue limits reshape import eligibility.
- Mixes:Blended fruit-vegetable combinations serve ready-to-eat snack manufacturers in Thailand and Vietnam scaling procurement for export contracts.
- Snacks:Single-serve formats are gaining traction among urban households in Shanghai, Bangkok, and Jakarta migrating purchases to direct-to-consumer platforms.
Fruits absorb the bulk of installed capacity; snacks are expanding most quickly.
Application:
Cost tier differentiation separates commodity ingredient supply from premium nutraceutical positioning, with stability study requirements widening the compliance gap.
- Food & Beverage:Commercial manufacturers specify rehydration ratios and moisture content under 5% for consistent batch performance in bakery and confectionery applications.
- Nutraceuticals:Clean-label encapsulation demand from Australian and Japanese supplement manufacturers is opening white space, though Australia's TGA monitoring of therapeutic claims now requires segregated cosmetic-grade and therapeutic-grade production lines.
- Ingredients:Brand procurement teams in China's infant nutrition sector are compressing supplier qualification cycles from 18 months to 9 months, with direct technical audits of Queensland drying facilities replacing third-party certification reliance.
- Retail:Supermarket distribution remains primary, though online retail penetration is climbing fastest among urban households seeking convenience formats.
Ingredients command the steepest expansion trajectory as qualification cycles accelerate; food and beverage maintains volume dominance.
Distribution Channel:
Customer type stratification separates bulk institutional procurement from household-level convenience purchasing, with channel-specific packaging and logistics requirements.
- Online Retail:Direct-to-consumer platforms are capturing migration from supermarkets among urban households in tier-one cities, with single-serve snack formats driving basket composition.
- Supermarkets:Primary channel for household purchasing, though shelf-space competition from air-dried alternatives at lower price points is intensifying.
- Specialty Stores:Premium positioning for functional botanical powders with therapeutic claims, particularly in Japanese domestic distribution anchored by heritage preservation brands.
- Wholesalers:Serve institutional buyers and food processors across South Asia with cost-optimized vegetable variants at volume scale.
Supermarkets retain the largest throughput base; online retail is climbing fastest as urban purchasing patterns shift.
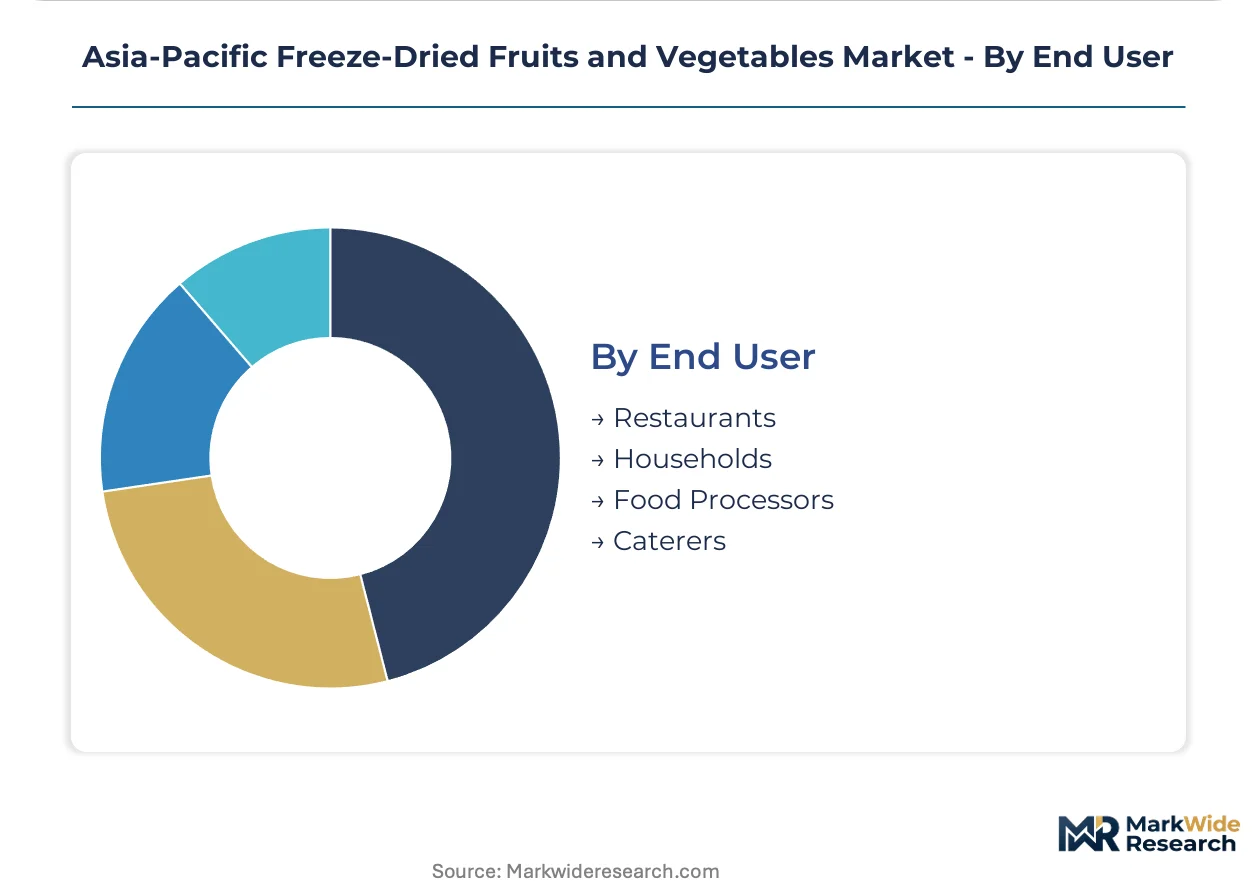
End User:
Volume concentration in food processing contrasts with margin concentration in premium household and restaurant applications, with distinct specification requirements at each tier.
- Restaurants:Premium positioning in tier-one cities drives specification of low-moisture tropical fruit ingredients for dessert and beverage applications.
- Households:Urban consumers in Shanghai, Bangkok, and Jakarta are migrating snack purchases from supermarkets to direct-to-consumer platforms, favoring single-serve convenience formats.
- Food Processors:Thai fruit processors are pivoting toward dedicated lyophilization lines for durian, mango, and pineapple to serve export contracts, with procurement scaling from ready-to-eat snack manufacturers.
- Caterers:Institutional demand concentrates in cost-optimized vegetable variants for large-scale meal preparation across South Asia.
Food processors absorb the bulk of installed capacity; households are expanding most quickly as online retail penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chanthaburi and Rayong provinces in eastern Thailand anchor Southeast Asian tropical fruit supply for lyophilization, with durian and mango harvests feeding dedicated processing corridors. Equipment upgrades across India and Australia are reshaping procurement geography for export-bound processors.
China
Premium pet food brands in Shanghai, Guangzhou, and Shenzhen drive demand for low-moisture tropical fruit ingredients. SAMR's novel food ingredient approvals create compliance gateways for functional botanical powders entering infant nutrition formulations. Yangtze River Delta processors are compressing supplier qualification cycles through direct technical audits of Queensland drying facilities.
India
Domestic food processors are accelerating procurement from local freeze-dried vegetable suppliers as FSSAI contaminant thresholds tighten pesticide residue limits. The PLI scheme for food processing machinery is subsidizing vacuum freeze-drying equipment upgrades across Maharashtra and Gujarat. Karnataka's Bangalore-Mysore corridor hosts emerging contract manufacturers serving South Asian institutional buyers.
Japan
METI and PMDA coordination on functional food approvals is creating regulatory tailwinds for clean-label encapsulation demand from supplement manufacturers. Kansai region heritage preservation brands anchor premium domestic distribution through traditional food preservation positioning. Osaka-based processors are segregating cosmetic-grade from therapeutic-grade production lines under TGA-influenced stability study requirements.
Australia
Queensland orchard operators are extending controlled-atmosphere logistics directly into Southeast Asian manufacturing clusters. TGA monitoring of therapeutic claims on nutraceutical products is tightening label substantiation requirements for freeze-dried botanicals. Brisbane-to-Bangkok cold-chain corridors are replacing third-party certification reliance with direct technical audits.
Vietnam
Ready-to-eat snack manufacturers in Ho Chi Minh City are scaling procurement of freeze-dried tropical fruit for export contracts. Mekong Delta cooperatives are adopting radio-frequency-assisted modular drying units for pineapple and dragon fruit micro-processing. Equipment miniaturization is decentralizing supply concentration toward orchard-proximate sites in Tien Giang and Long An provinces.
Asia-Pacific Freeze-Dried Fruits and Vegetables Market Competitive Environment
Global majors compete with regional champions across equipment technology and cold-chain integration, producing a tiered structure where heritage preservation specialists, scale-driven commodity processors, and modular technology adopters occupy distinct competitive spaces. Japanese and Australian heritage brands anchor premium positioning through traditional preservation credibility. Indian and Thai operators compete on cost-optimized vegetable variants and tropical fruit export contracts respectively. Dominant competitive moves include backward integration into orchard operations and technology licensing partnerships for radio-frequency-assisted equipment.
Among Japan-based heritage specialists, Nagatanien Co., Ltd. exemplifies traditional food preservation anchoring, while Ajinomoto Co., Inc. occupies a position bridging commodity and functional ingredient supply. Australian operators include Totally Pure Fruits Pty Ltd., which represents rigorous cold-chain control from orchard to drying facility. Indian fabricators such as Bajaj Agro Foods India Ltd. sit within the cost-optimized institutional supply tier. These named entities illustrate how geographic origin and company structure correlate with archetype positioning across the regional competitive map.
| Leading Market Players |
|---|
| Nagatanien Co., Ltd. |
| Totally Pure Fruits Pty Ltd. |
| Bajaj Agro Foods India Ltd. |
| Asahi Group Holdings, Ltd. |
| Ajinomoto Co., Inc. |
| Thai Ao Chi Fruits Co., Ltd. |
| Nutra Grand Co., Ltd. |
| Saraf Foods Ltd. |
| Mercer Foods LLC |
| Others |
Value Chain & Pricing Dynamics
Dual carbon goals in China are tightening energy-use standards for lyophilization facilities, gating qualified supply to processors with grid-connected renewable capacity and premium-tier pricing to brands with carbon-neutral certification. This regulatory filter concentrates pricing power among Thai and Australian operators with verified low-carbon footprints while compressing margins for conventional energy-dependent competitors.
Pricing Analysis
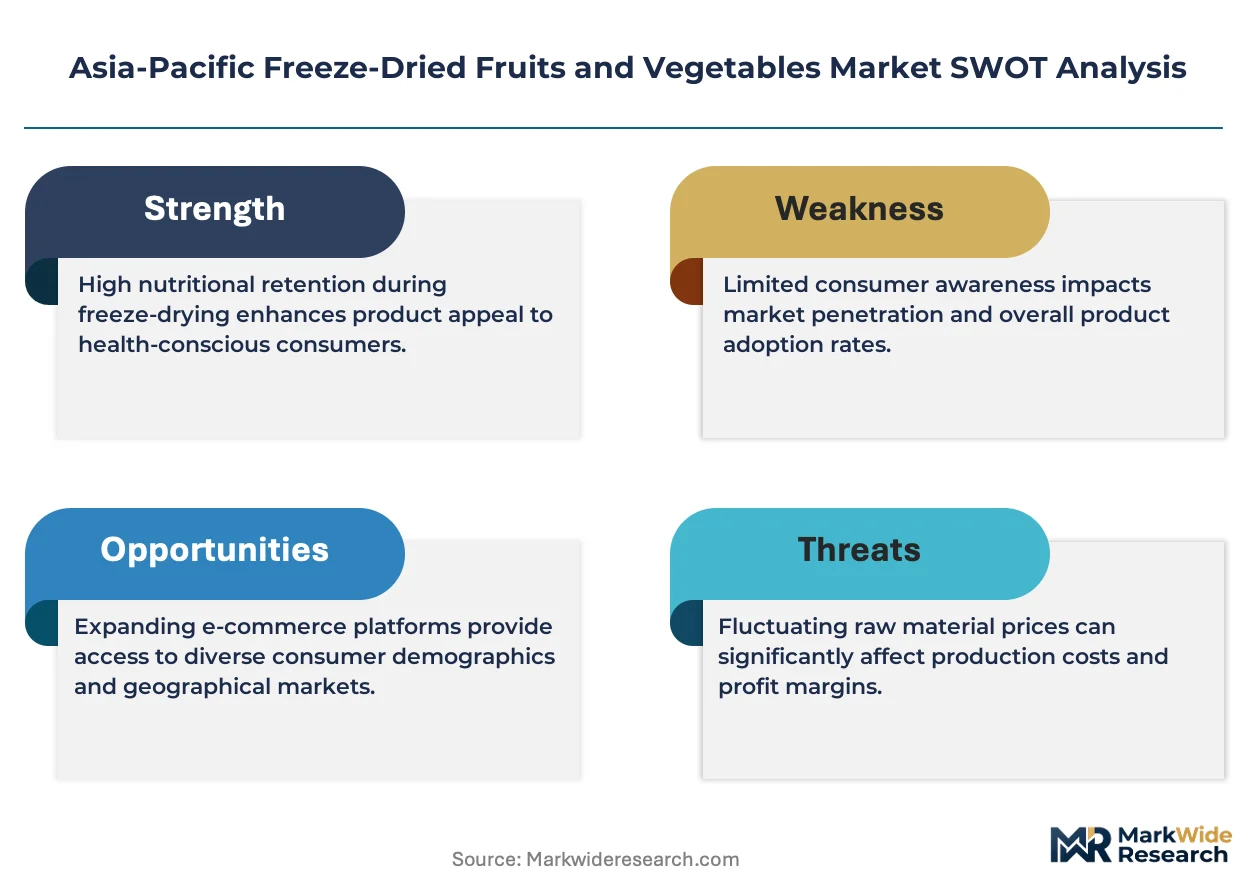
Warranty and service bundling separates premium Thai durian processors offering 24-month shelf-life guarantees from unbundled Vietnamese commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks moisture-content precision and organic certification tiers. Pricing pressure stems from radio-frequency-assisted equipment lowering batch-scale minimums and enabling Mekong Delta cooperatives to undercut Bangkok facility rates. Institutional buyers across South Asia exhibit highest price sensitivity, while Japanese nutraceutical brands prioritize stability-study documentation over unit cost.
Supply Chain Analysis
Controlled-atmosphere freight costs from Queensland orchards to Ho Chi Minh City processing clusters absorb 12-18% of landed ingredient value for Australian tropical fruit exporters. Supply concentrates in Thailand's Chanthaburi-Rayong corridor and Vietnam's Mekong Delta, with raw material dependencies on seasonal durian cultivar availability, vacuum pump components from Japanese fabricators, and food-grade nitrogen supply. Single-source vulnerability runs through Thai durian harvest windows concentrated in April-July. Distribution runs through direct technical audits replacing third-party certification for Chinese infant nutrition brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is executing a technology-transition phase as radio-frequency-assisted freeze-drying displaces conventional vacuum chamber infrastructure, compressing capital barriers and decentralizing production geography toward orchard-proximate micro-sites.
For Market Incumbents: Anchor premium positioning through backward integration into Queensland and Chanthaburi orchard operations, capturing cultivar-specific supply windows. Invest in segregated cosmetic-grade and therapeutic-grade production lines ahead of TGA stability-study mandates. Defend against modular equipment entrants by locking multi-year offtake agreements with Chinese pet food brands. For New Entrants and Emerging Players: The price-point gap between Nagatanien-tier heritage premiums and Vietnamese commodity economy tiers opens white space for mid-market clean-label positioning. Target Australian nutraceutical contract manufacturing with rapid 9-month qualification cycles. Enter through direct-to-consumer single-serve formats on Jakarta and Bangkok e-commerce platforms, bypassing supermarket slotting fees. For Investors and Strategic Acquirers: FSSAI equipment upgrade subsidies crossing Maharashtra and Gujarat is the leading indicator that Indian domestic processing capacity will consolidate around PLI-backed fabricators. Long-term viability favors acquisition targets with radio-frequency-assisted modular technology licenses and established Queensland-to-Asia cold-chain relationships. Watch for METI novel food approval acceleration as signal for functional botanical powder valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Operations | Captures Chanthaburi durian cultivar specificity and compresses seasonal supply risk. |
| Radio-Frequency Equipment Licensing Partnerships | Enables Mekong Delta cooperatives to bypass centralized Bangkok facility concentration. |
| Segregated Therapeutic-Grade Production Lines | Anticipates TGA stability-study requirements for Australian nutraceutical claims. |
| Direct Technical Audit Programs | Replaces third-party certification reliance for Yangtze River Delta infant nutrition brands. |
| Carbon-Neutral Lyophilization Certification | Aligns with dual carbon goals gating premium-tier Chinese pet food ingredient access. |
Study Parameters
Document review covered FSSAI contaminant threshold notifications, METI novel food approval registers, and Queensland cold-chain logistics disclosures, complemented by interviews with Thai fruit processing operations directors, Australian nutraceutical formulators, Chinese pet food brand procurement leads, and Indian PLI scheme machinery applicants. Secondary validation drew from customs trade data, TGA therapeutic claims registers, and ASEAN food processing equipment import records. Bottom-up capacity modeling and top-down demand segmentation were triangulated against vacuum freeze-drying equipment shipment data.
Cross-referencing historical lyophilization adoption curves against expert panel input on radio-frequency-assisted equipment penetration shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application tier, distribution channel, and end-user procurement scale, with regional regulatory clusters treated as distinct demand environments. CAGRs were derived from equipment capacity expansion trajectories and end-use qualification cycle compression rates, incorporating infant nutrition encapsulation demand curves and pet food ingredient specification tightening as industry-specific inputs.
Inputs from TGA stability-study documentation and METI approval timelines were available through the study window; gaps in real-time Vietnamese cooperative equipment deployment data introduce uncertainty bands around Mekong Delta decentralization velocity. Forecasts reflect assumptions on energy cost trajectories and regulatory enforcement intensity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Guanabana Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Colombia Fruits and Vegetables Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Sudachi Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Banana Flakes Market