
 Canned Fruits and Vegetables Market | 2026-2036
Canned Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Fruits and Vegetables Market Intelligence
The expansion of online retailers is tilting distribution away from traditional supermarkets. This shift benefits companies with strong brand recognition like Dole PLC, which leverages its global presence. Conagra Brands sustains its market position through a diverse portfolio of canned goods. Meanwhile, Bonduelle specializes in vegetable canning, targeting both retail and food service channels.
Canned fruits and vegetables are produce preserved by sealing them in airtight containers, typically steel or aluminum cans, and applying heat. This sterilization process ensures a long, stable shelf life without refrigeration. Canned Corn and Canned Peaches represent mature, high-volume product types. While Steel Cans dominate packaging due to cost, alternatives like Tetra Pak Cartons are emerging for premium product lines.
Food safety regulations from bodies like the US FDA and the European Food Safety Authority (EFSA) govern processing standards and material safety. These rules dictate acceptable preservation methods and limit contaminants in packaging materials like can linings. Future profitability will hinge on balancing consumer demand for clean label products with the inherent cost advantages of conventional canning techniques.
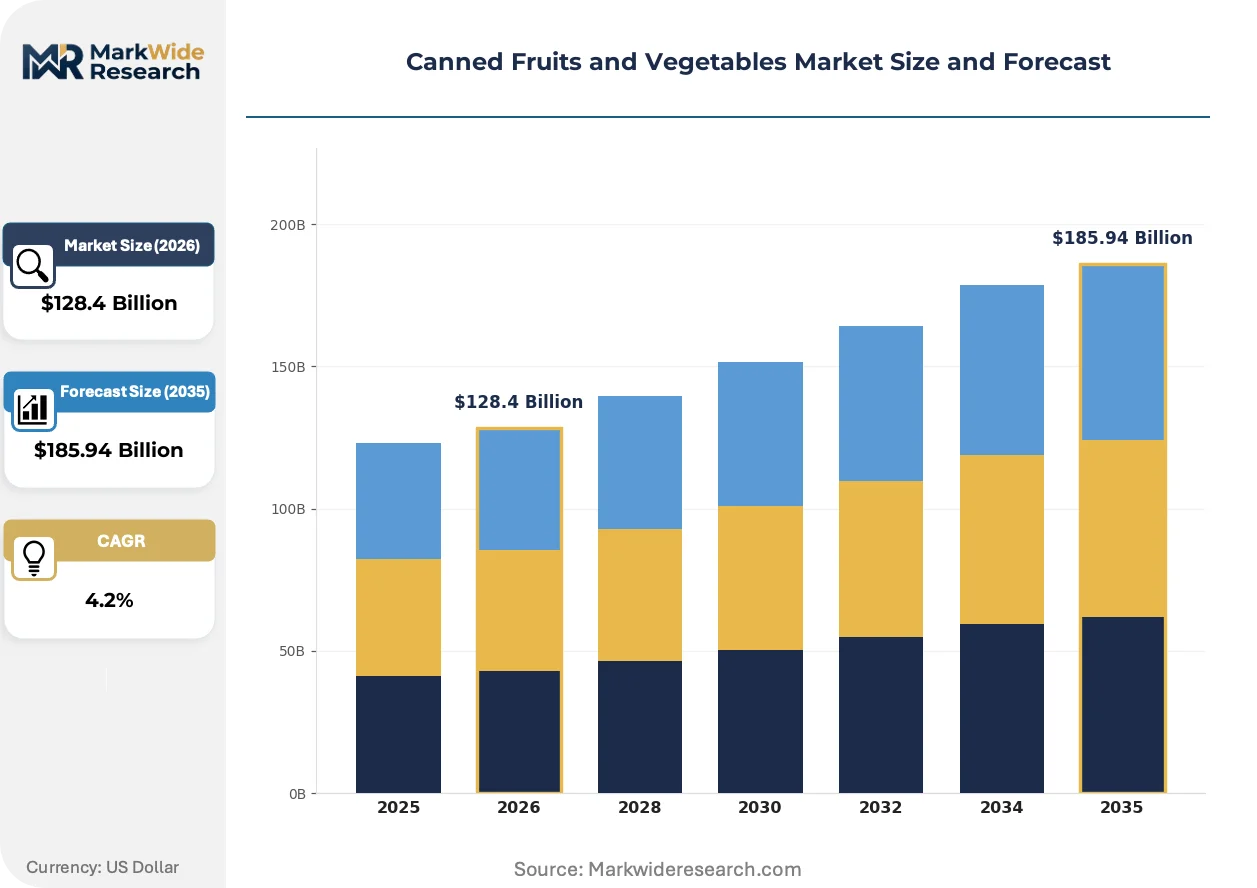
Market Dynamics
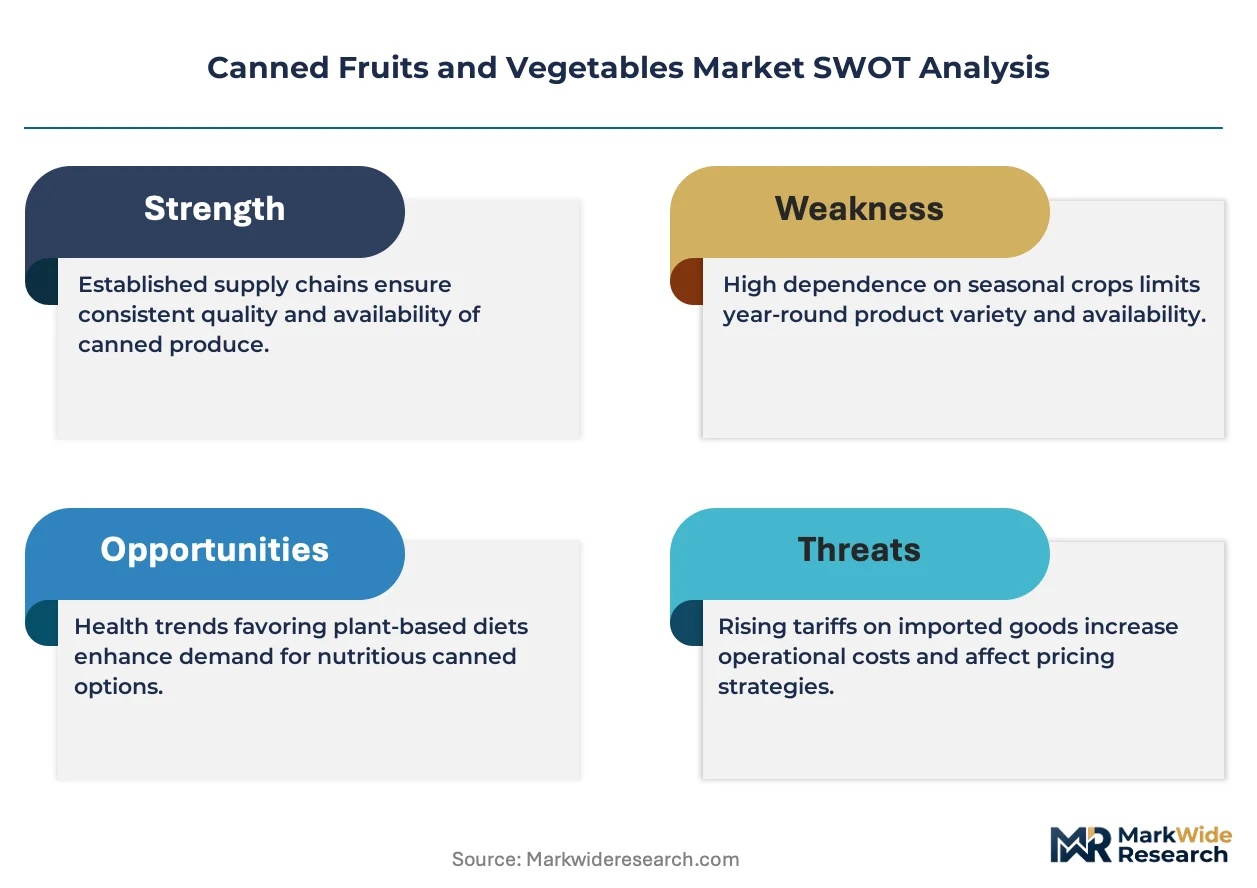
The central tension shaping the market is the conflict between consumer demand for clean-label products with minimal preservatives and the inherent cost advantages of conventional, high-volume canning. This dynamic forces producers to innovate in formulation and packaging to maintain relevance.
Growth Catalysts
- Urbanization in Developing Nations:Rapid urbanization in countries like India and Brazil increases demand for convenient, shelf-stable foods as dietary habits shift away from reliance on daily fresh produce markets.
- Food Service Expansion:The growth of quick-service restaurants and institutional catering creates substantial demand for standardized, long-shelf-life ingredients that simplify kitchen operations and supply chain management.
- BPA-Free Initiatives:Regulatory pressure from bodies like the European Food Safety Authority and consumer health concerns are driving the adoption of bisphenol A-free can linings, opening new avenues for product differentiation.
Market Restraints
- Negative Health Perceptions:A persistent consumer bias favoring fresh and frozen produce over canned alternatives, often associated with high sodium, sugar, and preservatives, limits household penetration.
- Raw Material Price Volatility:The market is exposed to fluctuations in the prices of agricultural commodities and packaging materials, particularly steel and aluminum, which can compress processor margins.
- Competition from Private Labels:The proliferation of store-brand canned goods from major retailers creates intense price competition, eroding brand loyalty and profitability for established national brands.
Strategic Opportunities
- Premium and Specialty Niches:There is significant opportunity in developing value-added product lines, such as organic, non-GMO certified, or exotic fruit and vegetable varieties that appeal to affluent, health-conscious consumers.
- Packaging Diversification:Exploring alternative formats like glass jars, retort pouches, and Tetra Pak cartons can help brands target premium segments and address consumer concerns about metal can linings.
- E-commerce Channel Development:Building direct-to-consumer platforms or partnering with online grocery services allows brands to bypass traditional retail gatekeepers and reach a wider audience with niche products.
Industry Challenges
- Supply Chain Seasonality:Processors face the operational challenge of managing highly seasonal crop harvests, requiring significant logistical coordination and capital investment in capacity that may be underutilized off-season.
- Energy Cost Management:The heat-intensive sterilization process is a major component of operational expenses, making processors vulnerable to volatile energy prices and increasing pressure to invest in energy-efficient technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Fruits and Vegetables Market |
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $185.94 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Pineapple, Canned Peas, Canned Corn, Canned Mixed Vegetables, Canned Peaches Packaging Type: Steel Cans, Aluminum Cans, Glass Jars, Plastic Containers, Tetra Pak Cartons Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesale Distributors, Specialty Food Stores Customer Type: Food Service Providers, Household Consumers, Institutional Buyers, Catering Companies, Wholesale Buyers |
| Companies Covered | Conagra Brands, Rhodes Food Group, Dole PLC, Dongwon Industries, Bonduelle, The Kraft Heinz Company, Seneca Foods Corporation, B&G Foods, Del Monte Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Fruits and Vegetables Market Strategic Shifts & Innovations
Producers are responding to evolving consumer expectations and regulatory landscapes by modernizing a traditionally industrial process. The focus is shifting toward enhanced transparency, cleaner ingredients, and more sustainable packaging solutions to bridge the gap between convenience and health-consciousness.
Advanced sensor technology is being integrated into sterilization and processing lines to monitor quality control parameters in real time. Food service and industrial buyers are increasingly requiring this data for traceability and compliance verification. This automation is digitizing the entire quality assurance function, providing verifiable proof of safety and consistency from the farm to the finished can.
Regulatory frameworks mandating clearer front-of-pack nutritional labeling, such as the Nutri-Score system in several European countries, are forcing product reformulation. This directly impacts the canned goods industry by pressuring manufacturers to reduce sodium and added sugars. Canned fruits packed in juice instead of heavy syrup are a direct market response to these policy-driven shifts.
A notable behavioral shift is occurring in product discovery and purchasing, moving beyond the traditional supermarket aisle. The rise of online grocery platforms and direct-to-consumer websites allows niche and ethnic food brands to gain national visibility without competing for limited physical shelf space. This trend is most prominent in North American and Western European markets, benefiting specialized producers.
Canned Fruits and Vegetables Market Segmentation
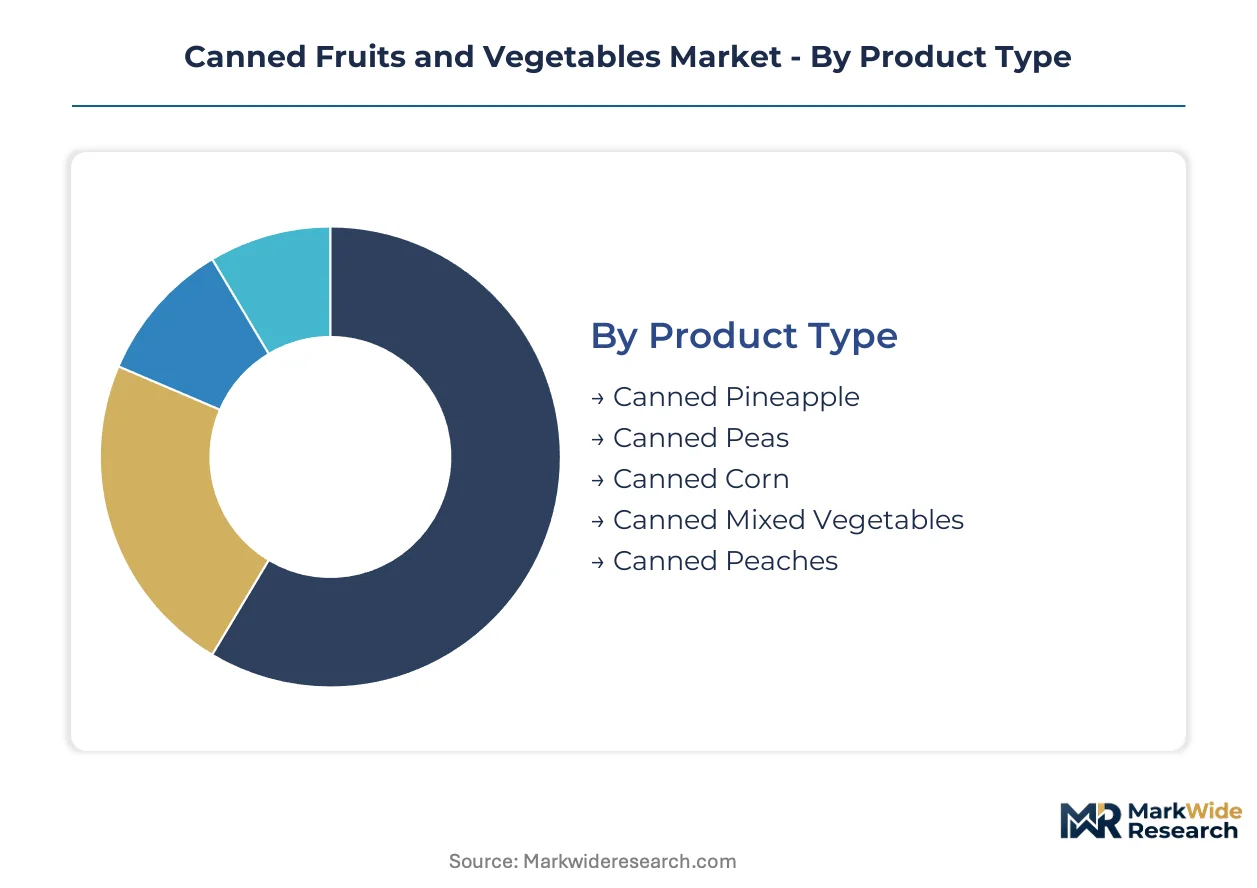
Market segmentation offers a granular understanding of the diverse factors influencing the Canned Fruits and Vegetables market, from product formulation to consumer purchasing habits. Analyzing these distinct categories helps producers tailor offerings, optimize distribution strategies, and respond effectively to evolving consumer and industrial demands.
Product Type:
Product types in the canned goods market exhibit varied consumption cycles, influencing inventory management and production schedules across the supply chain.
- Canned Corn:This mature product consists of corn kernels preserved in brine or water, offering a stable and convenient vegetable option. Demand remains consistently high from household consumers and food service providers seeking cost-effective, long-shelf-life ingredients for diverse culinary applications.
- Canned Peaches:Peaches preserved in syrup or juice represent a high-volume fruit segment, valued for their extended shelf life and versatility in desserts or as a standalone snack. Major processors target both retail and institutional buyers, particularly in North American and European markets.
- Canned Pineapple:Pineapple chunks or slices are preserved in syrup or juice, appealing to consumers seeking tropical fruit convenience.
- Canned Peas:Green peas preserved in brine offer a classic, shelf-stable vegetable side dish for everyday meals.
- Canned Mixed Vegetables:This category combines various vegetables, providing a convenient, ready-to-use ingredient for stews and casseroles.
Canned Corn anchors the volume base while Canned Pineapple gains share at the steepest rate.
Packaging Type:
Packaging types differentiate significantly by cost-effectiveness and consumer perception, impacting both manufacturing expenses and market positioning for canned goods.
- Steel Cans:These durable and cost-effective containers, often coated with BPA-free linings, dominate the market due to their excellent barrier properties and recyclability. The material's strength ensures product integrity during transport and storage, making it preferred by large-scale food processors.
- Tetra Pak Cartons:These multi-layered aseptic cartons are gaining traction for premium and organic product lines, addressing consumer concerns about metal packaging. Their lighter weight reduces shipping costs and offers a perception of freshness, particularly for fruit-based products in European markets.
- Aluminum Cans:Lighter than steel, these cans are used for certain products, offering good recyclability and ease of opening.
- Glass Jars:Offering product visibility and a premium aesthetic, glass jars appeal to health-conscious consumers for specialty canned goods.
- Plastic Containers:Limited use in canning due to heat sterilization requirements, these are sometimes employed for retort pouches or specialty items.
Steel Cans continue to dominate due to their cost advantages, while Tetra Pak Cartons represent an expanding segment for premium product lines.
Distribution Channel:
Distribution channels vary widely in their reach and direct customer interaction, from broad-market penetration to niche-segment targeting for canned food products.
- Online Retailers:The expansion of e-commerce platforms allows brands to reach a broader audience, bypass traditional shelf space constraints, and cater to niche dietary preferences. This channel is particularly significant in North America and Western Europe, facilitating direct-to-consumer sales.
- Supermarkets:These large-format stores remain the primary purchasing point for household consumers, offering extensive product ranges and competitive pricing. Their widespread presence ensures broad market accessibility for established canned goods brands.
- Convenience Stores:These smaller retail formats provide quick access to essential canned goods for impulse purchases or immediate needs.
- Wholesale Distributors:These entities supply bulk quantities of canned fruits and vegetables to institutional buyers and smaller retailers.
- Specialty Food Stores:These outlets cater to specific consumer tastes, offering organic, gourmet, or ethnic canned produce.
The shift towards Online Retailers is reshaping competitive dynamics, though Supermarkets maintain a substantial share of consumer purchases.
Customer Type:
Customer segments exhibit distinct purchasing patterns and volume requirements, influencing product formats and supply chain strategies for canned fruits and vegetables.
- Food Service Providers:This segment, including restaurants, cafeterias, and catering companies, demands large volumes of consistent, long-shelf-life ingredients for operational efficiency. Standardized product quality simplifies kitchen operations and inventory management, particularly in fast-paced environments.
- Household Consumers:Individual shoppers represent the largest customer base, purchasing canned goods for home consumption due to convenience, affordability, and extended shelf life. Product differentiation through clean labels and varied packaging appeals directly to this segment.
- Institutional Buyers:Schools, hospitals, and government agencies purchase canned goods in bulk for meal preparation and emergency rations.
- Catering Companies:These businesses rely on canned ingredients for their scalability and ease of preparation across various events.
- Wholesale Buyers:These purchasers acquire large quantities of canned products for resale to smaller businesses or for distribution networks.
Food Service Providers drive significant bulk demand, complementing the consistent, smaller-volume purchases from Household Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government initiatives promoting food security and accessible nutrition are influencing regional market dynamics for canned fruits and vegetables. These policies often encourage the production and distribution of shelf-stable food options, particularly in areas prone to supply chain disruptions. Urbanization trends further amplify demand for convenient food solutions in these growing markets.
United States
Consumer demand for convenient meal solutions and the robust food service sector drive significant volume in the United States. US FDA regulations govern processing standards, ensuring product safety and quality. California's Central Valley represents a core processing hub for canned fruits and vegetables, leveraging local produce.
India
Rapid urbanization and evolving dietary habits are fueling substantial demand for shelf-stable foods in India. The FSSAI establishes stringent food safety and quality standards for canned products. Processing clusters in Maharashtra and Gujarat are expanding capacity to meet both domestic consumption and export opportunities.
China
A burgeoning middle class and a preference for convenient options underpin market expansion in China. GB standards enforce strict quality and safety requirements for all canned food products. Shandong province, a major agricultural region, hosts numerous large-scale canning facilities catering to domestic and international markets.
France
Established retail and food service channels contribute significantly to consistent consumption of canned goods in France. European Food Safety Authority (EFSA) guidelines and Nutri-Score labeling influence product formulation. The Brittany region, known for its agricultural output, maintains a strong presence in vegetable canning and processing.
Brazil
Urban population growth and an expanding food service industry are increasing uptake of canned fruits and vegetables across Brazil. ANVISA, the national health surveillance agency, enforces comprehensive food regulations. Processing operations in São Paulo and Minas Gerais states benefit from proximity to agricultural production and major consumer markets.
Canned Fruits and Vegetables Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing large multinational food conglomerates and specialized regional processors. This market includes both diversified food companies and those focused exclusively on canned goods. Dominant competitive moves involve portfolio diversification into premium segments and strategic partnerships to enhance distribution networks.
Within the established global players, Dole PLC exemplifies a diversified international food producer leveraging its strong brand recognition across multiple product categories and geographies. Conagra Brands, a US-based food company, maintains a robust market presence through its extensive portfolio of canned goods and other packaged foods, serving a broad consumer base across North America. Bonduelle, a French-headquartered specialist, anchors the vegetable canning segment, targeting both retail and food service channels with its focused, quality-driven offerings and sustainable practices.
| Leading Market Players |
|---|
| Conagra Brands |
| Rhodes Food Group |
| Dole PLC |
| Dongwon Industries |
| Bonduelle |
| The Kraft Heinz Company |
| Seneca Foods Corporation |
| B&G Foods |
| Del Monte Foods |
| Others |
Cost & Logistics Intelligence
Steel and aluminum production, concentrated in a few global regions, significantly influences packaging costs and ultimately impacts processor margins in canned goods. This upstream concentration dictates a substantial portion of the final product's cost structure.
Pricing Analysis
Volume-based pricing structures dominate the canned fruits and vegetables market, differentiating between bulk institutional purchases and smaller retail units. Price differentiation also stems from certification levels, such as organic or non-GMO, and brand recognition. Pricing pressure intensifies for conventional, high-volume products due to private label competition. Household consumers demonstrate high price sensitivity for everyday canned goods, while food service providers prioritize consistent quality and volume discounts.
Supply Chain Analysis
Raw material price volatility, particularly for agricultural commodities and packaging materials like steel and aluminum, represents a significant supply chain risk. Supply concentration for agricultural inputs often centers in regions such as California's Central Valley, Shandong province in China, and Brittany in France. Processors depend heavily on steel and aluminum for can production. Distribution primarily runs through wholesale distributors to food service and supermarkets for household consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The canned fruits and vegetables market is undergoing a buyer-power shift, driven by the consolidation of online retailers. This concentration allows these platforms to exert greater influence over pricing and distribution terms for packaged food brands.
For Market Incumbents:
Pre-empt negative health perceptions by investing in clean label reformulations, reducing sodium and sugar, and promoting the nutritional benefits of canned goods. Diversify packaging formats beyond traditional steel cans, exploring Tetra Pak cartons and glass jars, to appeal to health-conscious consumers and mitigate competitive pressure from private labels. Invest in advanced sensor technology for quality control to ensure product consistency and traceability.
For New Entrants and Emerging Players:
Establish a beachhead in premium and specialty niches, focusing on organic, non-GMO, or exotic fruit and vegetable varieties. Leverage e-commerce channels to reach affluent, health-conscious consumers directly, bypassing traditional retail gatekeepers. Differentiate through transparent sourcing and sustainable packaging solutions to gain market share.
For Investors and Strategic Acquirers:
Capital is best deployed toward mid-sized processors specializing in value-added product lines or those with strong regional supply chain integration. Long-term viability depends on companies capable of balancing cost advantages with consumer demand for clean label and sustainable practices. Watch for increased adoption of BPA-free linings and alternative packaging as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Reformulation | Reducing sodium and sugar content addresses consumer health concerns and complies with evolving nutritional labeling mandates. |
| Packaging Diversification | Exploring Tetra Pak and glass jars appeals to premium segments and mitigates metal can perception issues. |
| E-commerce Channel Development | Direct-to-consumer platforms expand market reach for niche products beyond traditional supermarket shelf space. |
| Supply Chain Digitization | Integrating advanced sensor technology enhances quality control and provides verifiable traceability for food service buyers. |
| Sustainable Sourcing Programs | Implementing ethical and environmentally friendly practices attracts environmentally conscious consumers and enhances brand reputation. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from published reports. This involved direct conversations with food service procurement managers, canning facility operators, brand managers, and retail buyers. Secondary sources included government food safety regulations, agricultural commodity market reports, and corporate financial disclosures, triangulating bottom-up and top-down insights.
Forecast inputs considered urbanization rates, food service expansion, and raw material price trends across the analysis window. The analytical framework modeled market segmentation by product type, packaging type, distribution channel, customer type, and regional regulatory environments. Compound annual growth rates were derived from historical data and projected demand shifts. Consumer preference for clean label products was a key forecast input.
Stress conditions across agricultural commodity supply, energy costs, and regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding consumer dietary shifts and technological advancements in food preservation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Romanesco Broccoli Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Yellow Oyster Mushroom Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
Cranberries Market
Fruits and Vegetables
Dates Market
Fruits and Vegetables
Butterfly Pea Flowers Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Mango Puree Market