
 Hardware Engineering and Design Services Market | 2026-2036
Hardware Engineering and Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
Hardware Engineering and Design Services Market Intelligence
The substitution of traditional silicon with Gallium Nitride (GaN) in power electronics is hardening the requirement for specialized high-frequency design expertise. This shift necessitates advanced thermal management and PCB layout skills. Siemens EDA leverages its comprehensive software suite for complex system-on-chip verification. Synopsys dominates the electronic design automation (EDA) market, providing critical IP blocks for both ASIC and FPGA development projects.
Hardware engineering and design services encompass the outsourced expertise for creating and validating physical electronic components and systems. This includes processes like multi-layer PCB layout and signal integrity analysis to ensure performance. The primary purpose is to accelerate product development cycles and access specialized talent not available in-house. Within technology segments, demand for FPGA Design and Embedded Systems is driven by IoT expansion, while the Medical Devices end-user industry commands premium rates for services requiring stringent validation protocols.
Regulatory frameworks such as the EU's RoHS directive and the US FCC's rules on electromagnetic interference directly shape service requirements. RoHS dictates material selection in board design, while FCC Part 15 necessitates specific testing and validation for market access in the United States. Vendor selection will increasingly hinge on demonstrated expertise in navigating disparate international compliance standards for both hardware and embedded firmware.
Market Dynamics
The market's central dynamic is the escalating complexity of electronic systems, driven by the convergence of advanced materials like Gallium Nitride (GaN) and stringent regulatory frameworks such as the EU's MDR, demanding higher-level system design capabilities.
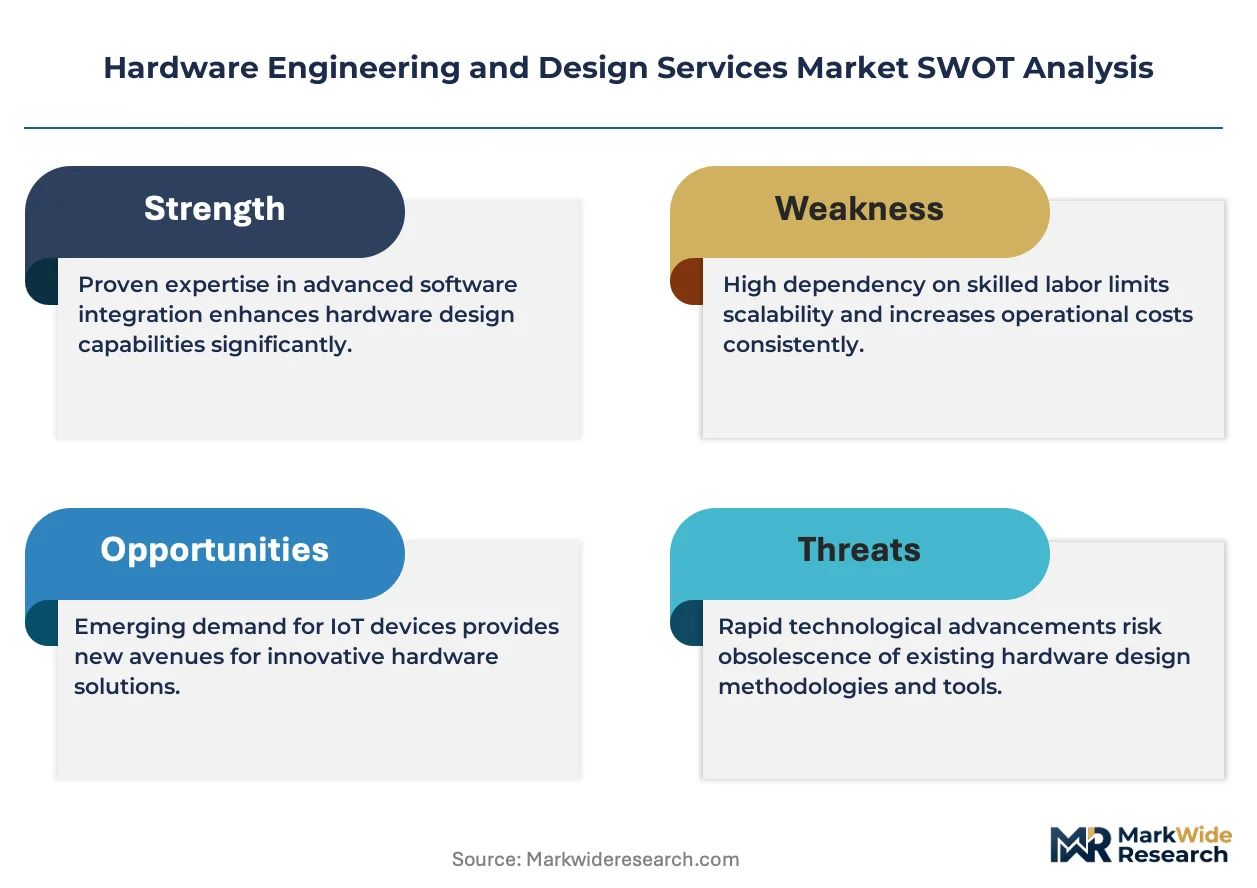
Growth Catalysts
- IoT Expansion:The proliferation of connected devices in industrial and consumer segments drives demand for FPGA design and embedded systems engineering to enable edge computing and low-power operation.
- Medical Device Regulation:The EU's Medical Device Regulation (MDR) mandates extensive redesign and re-validation of existing products, creating a significant demand pipeline for specialized compliance and testing services.
- Semiconductor Hub Concentration:Demand for advanced Application-Specific Integrated Circuit (ASIC) design services is intensifying within specialized technology clusters in Taiwan and South Korea, pulling in global R&D projects.
Market Restraints
- Talent Scarcity:A critical shortage of engineers with specialized skills in high-frequency design for materials like GaN and advanced thermal management constrains service provider capacity and inflates project costs.
- EDA Tool Licensing Costs:The market's dependency on a small number of dominant electronic design automation (EDA) software vendors creates high licensing costs, acting as a significant barrier for smaller design firms.
- Intellectual Property Barriers:The complexity and expense associated with licensing essential IP blocks for System-on-Chip (SoC) and FPGA development can deter or delay new product initiatives, particularly for startups.
Strategic Opportunities
- Automotive Electrification:The transition to electric vehicles and advanced driver-assistance systems (ADAS) opens a vast opportunity for services in power electronics, sensor integration, and functional safety (ISO 26262) compliance.
- AI at the Edge:The convergence of artificial intelligence and edge computing creates new demand for custom hardware accelerators and low-power neural network processors, a segment with high-value service potential.
- Circular Economy Initiatives:Policies promoting right-to-repair and product longevity, such as elements of the EU Green Deal, can spur demand for modular design, reverse engineering, and component-level refurbishment services.
Industry Challenges
- Fragmented Compliance Regimes:Service providers face significant operational overhead in navigating and maintaining expertise across disparate international standards, such as FCC Part 15 in the US and CE marking requirements in Europe.
- System Integration Complexity:Ensuring seamless interoperability between new custom-designed hardware and clients' legacy software stacks and IT infrastructure remains a persistent and complex implementation hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardware Engineering and Design Services Market |
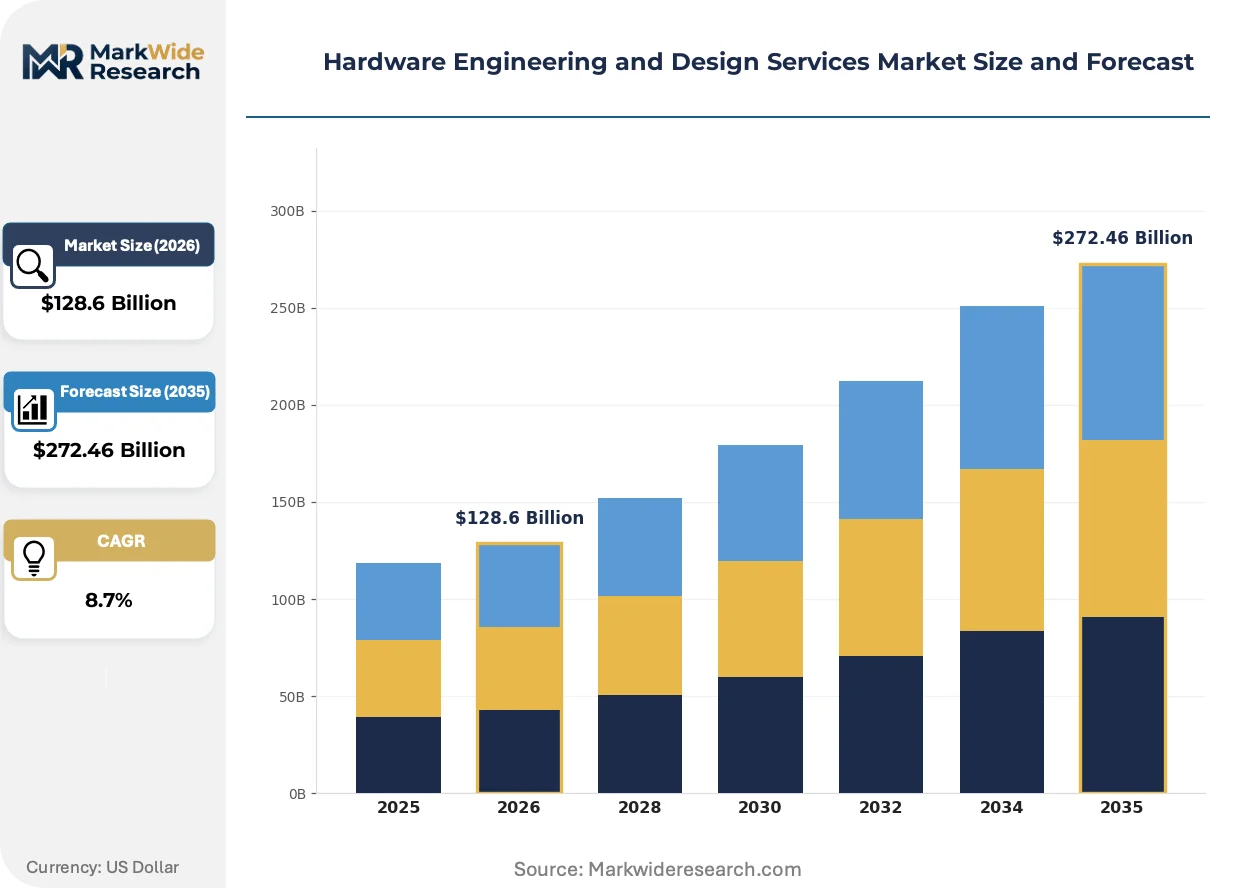
| Market Size in 2026 | $128.6 Billion |
| Market Size in 2035 | $272.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Concept Development, Prototype Design, System Integration, Testing & Validation, Technical Documentation Technology: Embedded Systems, FPGA Design, PCB Layout, ASIC Design, Signal Processing End User Industry: Consumer Electronics, Aerospace & Defense, Telecommunications, Industrial Automation, Medical Devices Project Size: Small Scale, Medium Scale, Large Scale, Enterprise Level |
| Companies Covered | Sigma Connectivity, Cadence Design Systems, InTechHouse, Siemens EDA, Synopsys, Softeq, Yalantis, Altium, Prevas AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardware Engineering and Design Services Market Strategic Shifts & Innovations
Component miniaturization and functional integration are exerting dual pressures on the market. This forces a move beyond discrete component design toward holistic system-level architecture, verification, and validation services that encompass both hardware and embedded firmware.
System-on-Chip (SoC) design integrates diverse functionalities like processing and memory onto a single circuit. The automotive and consumer electronics sectors are rapidly adopting SoCs to reduce size and power consumption. This shift is decentralizing development focus from PCB layout to complex front-end verification, demanding specialized EDA tool expertise.
The EU's Restriction of Hazardous Substances (RoHS) directive dictates strict limits on materials like lead and cadmium. This regulation imposes rigorous material declaration and supply chain auditing on designs for the European market. Consumer electronics and industrial automation segments now prioritize firms that offer integrated compliance management and material lifecycle tracking.
Client engagement models are evolving from discrete, project-based contracts toward dedicated, long-term outsourced design teams. This partnership approach replaces the traditional RFP process with an integrated relationship where the provider acts as an extension of the client's R&D. The aerospace and defense industry favors this model for long development cycles requiring continuous engineering support.
Hardware Engineering and Design Services Market Segmentation
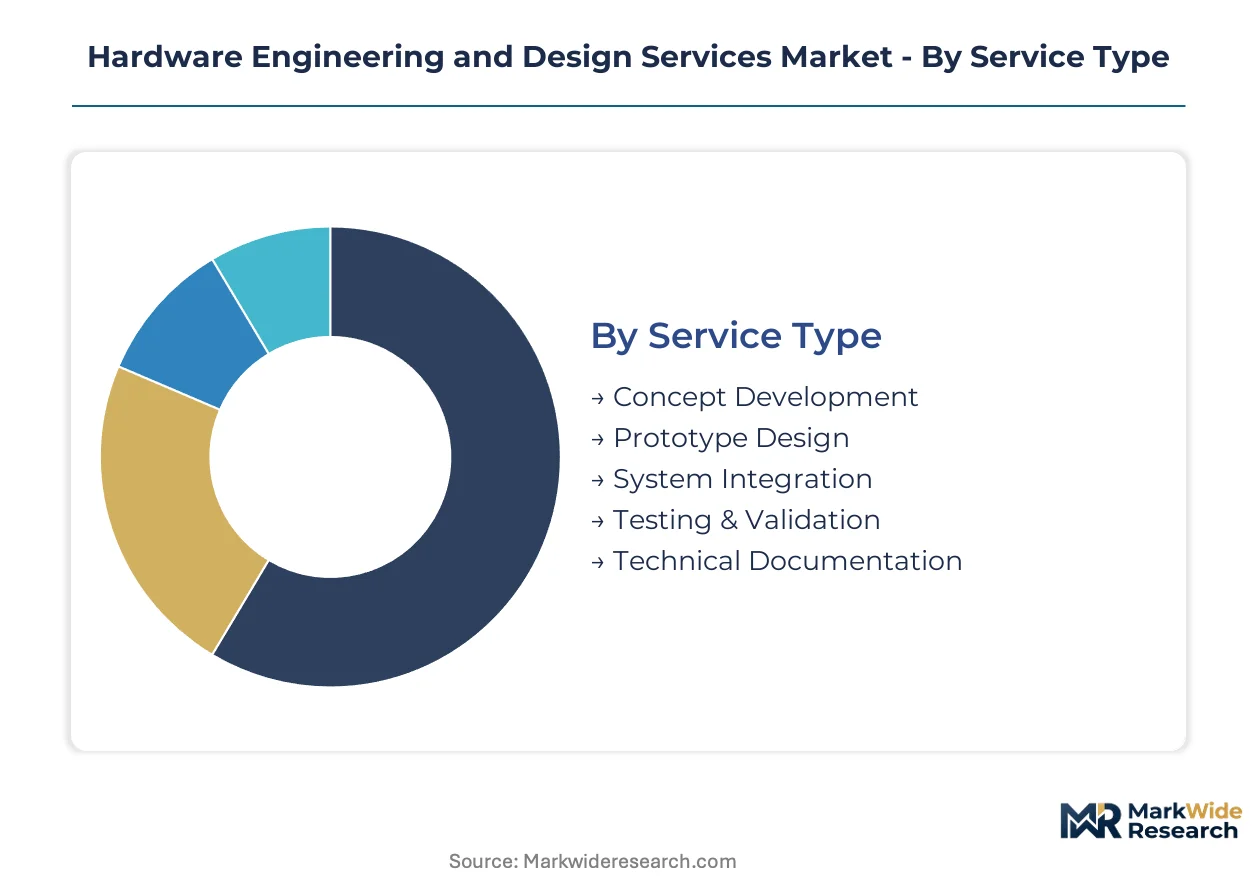
The Hardware Engineering and Design Services market is segmented to provide a granular view of client needs and service provider specializations. This detailed breakdown helps identify areas of concentrated demand and emerging technological requirements across diverse industries.
Service Type:
Client needs often dictate the specific type of hardware engineering service required, ranging from initial ideation to final product validation.
- Testing & Validation:This service involves rigorous verification processes to ensure hardware functionality, performance, and compliance with industry standards. Demand is particularly high in the medical devices sector due to EU MDR and in automotive for functional safety standards like ISO 26262.
- System Integration:This entails combining various hardware and software components into a cohesive, interoperable system, often requiring complex interface design. The IoT expansion drives significant demand for seamless integration of edge devices with cloud platforms.
- Concept Development:This initial phase focuses on ideation, feasibility studies, and high-level architectural design for new products.
- Prototype Design:This involves creating early physical models or working samples to test design concepts and gather feedback.
- Technical Documentation:This service provides comprehensive records, specifications, and manuals essential for product manufacturing, maintenance, and regulatory compliance.
Volume sits with Prototype Design; growth tilts toward Testing & Validation.
Technology:
Technology specialization is often driven by the unique application requirements of various electronic systems.
- ASIC Design:This involves creating custom integrated circuits optimized for specific applications, offering high performance and low power consumption. Demand for these specialized services is concentrating in semiconductor hubs like Taiwan and South Korea for AI accelerators and advanced computing.
- Embedded Systems:These are integrated hardware and software solutions designed for dedicated functions within larger mechanical or electrical systems. The proliferation of connected devices in industrial and consumer segments drives demand for low-power edge computing solutions.
- FPGA Design:Field-Programmable Gate Arrays offer reconfigurable logic for rapid prototyping, specialized processing, and flexible hardware acceleration.
- PCB Layout:This critical service focuses on the physical arrangement of electronic components and traces on printed circuit boards to ensure signal integrity and manufacturability.
- Signal Processing:This involves the manipulation and analysis of analog and digital signals, crucial for applications in telecommunications, imaging, and sensor systems.
Demand for PCB Layout remains foundational, while ASIC Design is expanding most quickly.
End User Industry:
Distinct regulatory and performance demands define the service requirements across different end-user industries.
- Medical Devices:This sector requires highly specialized engineering services for devices that must meet stringent safety, reliability, and regulatory compliance standards. The EU's Medical Device Regulation (MDR) mandates extensive redesign and re-validation, creating significant demand.
- Aerospace & Defense:This industry demands services for mission-critical systems where extreme reliability, long operational lifecycles, and adherence to rigorous certifications are paramount. Long-term outsourced design teams are favored for continuous engineering support.
- Consumer Electronics:This segment focuses on rapid product cycles, cost-effectiveness, and miniaturization for devices like smartphones, wearables, and smart home products.
- Telecommunications:Services in this industry support the development of infrastructure and devices for high-speed data transmission, networking, and wireless communication.
- Industrial Automation:This involves designing control systems, robotics, and sensors for manufacturing, process control, and logistics applications.
The Consumer Electronics segment drives consistent volume, but Medical Devices presents the steepest expansion trajectory.
Project Size:
The scale of a project directly influences the complexity of engineering tasks and the required resource allocation.
- Enterprise Level:These are strategic, often multi-year engagements involving comprehensive platform development or extensive product portfolios for large organizations. The aerospace and defense industry frequently utilizes this model for continuous R&D.
- Large Scale:Projects in this category require substantial engineering teams and extended timelines, often involving complex system development or significant product redesigns. Automotive electrification for ADAS systems represents a typical large-scale project.
- Small Scale:These engagements typically involve focused tasks such as specific component design, rapid prototyping, or targeted bug fixes.
- Medium Scale:Projects of this size involve moderate complexity, requiring dedicated teams and structured development processes for defined product modules or sub-systems.
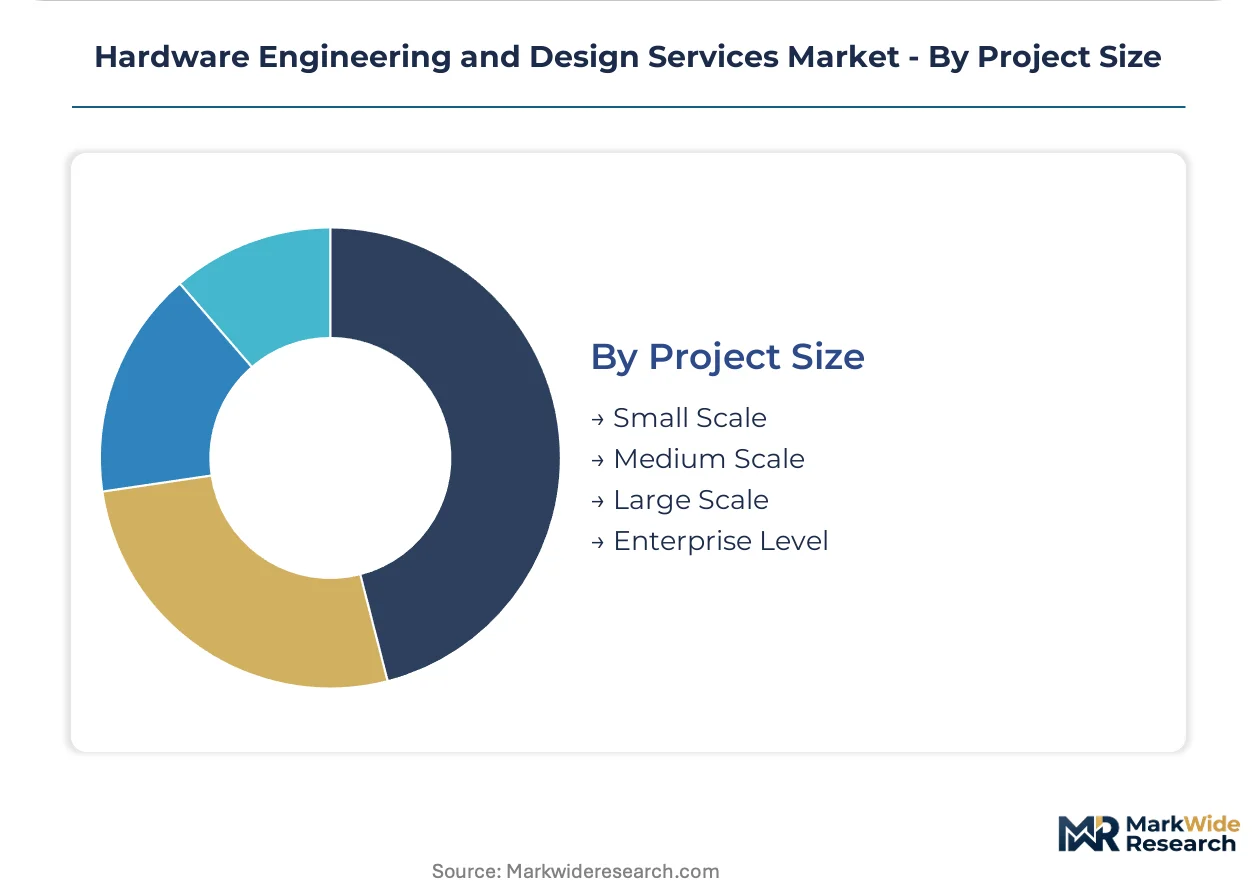
While Small Scale projects are numerous, Enterprise Level engagements command higher value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park exemplifies a special economic zone driving significant concentration in hardware engineering and design services. This park attracts global R&D investments, particularly for advanced ASIC design and semiconductor innovation. Its robust ecosystem supports specialized talent and rapid prototyping capabilities.
Taiwan
Demand for advanced Application-Specific Integrated Circuit (ASIC) design services intensifies within Taiwan, driven by global technology giants. The country's industrial policy, including significant incentives for semiconductor manufacturing, reinforces its position. Hsinchu Science Park remains a critical hub for global R&D projects, fostering specialized chip development and high-frequency design expertise.
United States
The United States experiences strong demand for embedded systems and FPGA design, particularly for aerospace and defense applications. The CHIPS and Science Act provides substantial funding to bolster domestic semiconductor research and manufacturing. Silicon Valley and Boston continue as major centers for innovation, attracting significant hardware engineering investments.
Germany
Germany's automotive electrification initiatives drive substantial demand for power electronics and functional safety engineering. The country's Industry 4.0 strategy supports advanced industrial automation, requiring complex system integration services. Bavaria and Baden-Württemberg are key regions, hosting numerous automotive and industrial design centers.
South Korea
South Korea's focus on advanced memory and logic semiconductors fuels demand for specialized ASIC design and verification. The government's K-Semiconductor Belt strategy aims to create a world-class chip ecosystem. Seoul and Gyeonggi Province concentrate leading technology firms and R&D facilities, advancing next-generation hardware.
India
India's expanding electronics manufacturing and IoT sector generates significant demand for embedded systems and PCB layout services. The Production Linked Incentive (PLI) scheme encourages domestic hardware production and design activities. Bengaluru and Hyderabad serve as prominent technology hubs, attracting global companies for design and validation work.
Hardware Engineering and Design Services Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the hardware engineering and design services market. The market exhibits a tiered structure, with a few dominant electronic design automation (EDA) software providers at the top. Strategic archetypes include specialized design houses, broad-scope engineering consultancies, and in-house R&D arms of large enterprises. Companies frequently engage in strategic partnerships to expand their service portfolios and pursue geographic expansion into key semiconductor hubs.
The competitive landscape features established electronic design automation (EDA) tool providers like Synopsys and Siemens EDA, which offer comprehensive software suites for complex system-on-chip verification. These firms anchor the market by supplying critical IP blocks for ASIC and FPGA development projects, enabling advanced hardware design. Additionally, specialized design service firms such as Cadence Design Systems exemplify expertise in high-frequency design and advanced thermal management, crucial for next-generation materials like Gallium Nitride (GaN) and complex multi-layer PCB layouts.
| Leading Market Players |
|---|
| Sigma Connectivity |
| Cadence Design Systems |
| InTechHouse |
| Siemens EDA |
| Synopsys |
| Softeq |
| Yalantis |
| Altium |
| Prevas AB |
| Others |
Cost & Logistics Intelligence
Medical device manufacturers' stringent regulatory requirements often dictate a value-based pricing model for specialized hardware engineering services. This approach prioritizes compliance and reliability over cost, reflecting the high stakes involved in product validation.
Pricing Analysis
Lead-time-driven pricing commands a premium for rapid prototyping and urgent compliance verification in this market. Project-based pricing remains the dominant model, reflecting the custom nature of hardware design engagements. Price differentiation stems from specialized talent in areas like GaN design and certification levels such as ISO 26262 functional safety. Pricing pressure stems from the critical shortage of high-frequency design engineers. Consumer electronics companies exhibit the highest price sensitivity, while medical device and aerospace clients prioritize expertise over cost.
Supply Chain Analysis
Dual-sourcing requirements are increasingly mandated by buyers for critical IP blocks and EDA software licenses to mitigate single-source risk. Geographic supply concentration for advanced ASIC design services centers in Taiwan and South Korea, while the United States remains a hub for FPGA and embedded systems for defense. The market relies heavily on specialized IP blocks and advanced EDA software tools. A structural risk is the single-source vulnerability inherent in dominant EDA software vendors. Distribution primarily runs through direct service provision from specialized design houses and engineering consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is supply-constrained, with a critical shortage of specialized engineering talent propping up service pricing. This talent bottleneck impacts project timelines and overall market capacity.
For Market Incumbents:
Extend specialized talent pools through targeted university partnerships and continuous upskilling programs to address high-frequency design expertise. Acquire smaller, niche design houses with proven capabilities in areas like GaN or AI at the Edge to counter talent scarcity. Deepen strategic partnerships with dominant EDA software vendors to secure preferential access and influence future tool development. Invest in advanced compliance certifications such as EU MDR and ISO 26262 to maintain a competitive edge against emerging threats.
For New Entrants and Emerging Players:
Small-to-medium enterprises requiring specific compliance expertise represent an underserved buyer archetype. Target the burgeoning automotive electrification sector with focused offerings in power electronics and functional safety. Offer modular service packages for specific regulatory compliance, such as FCC Part 15 testing or RoHS material declaration. Adopt a value-based pricing model that highlights specialized expertise rather than competing solely on cost, particularly for complex system integration tasks.
For Investors and Strategic Acquirers:
The window for entry favors strategic acquirers seeking to consolidate specialized engineering capabilities. Long-term viability remains strong due to increasing electronic system complexity and regulatory demands. Target niche design houses with deep expertise in advanced materials like GaN, or those specializing in functional safety for automotive and medical devices. A key signal to watch is the increasing consolidation of smaller, highly specialized design firms by larger engineering consultancies seeking to expand their service portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Specialized Talent Development Programs | Addresses critical skill shortages in high-frequency design and advanced thermal management. |
| Strategic EDA Tool Partnerships | Secures access to essential design software and IP blocks for complex SoC development. |
| Compliance Certification Investment | Ensures adherence to stringent regulations like EU MDR, opening high-value market segments. |
| Modular Design Service Offerings | Attracts small-to-medium enterprises with flexible, cost-effective engineering solutions. |
| Geographic Expansion into Semiconductor Hubs | Positions firms closer to demand centers for ASIC design in Taiwan and South Korea. |
Research Approach
Document review covered industry reports, regulatory body publications such as the EU Medical Device Regulation, and technical journals, complemented by interviews. Primary research included discussions with hardware design engineers, R&D directors, compliance officers, and procurement managers. This approach leveraged both bottom-up market insights and top-down industry perspectives for comprehensive data triangulation.
The analytical framework cross-referenced historical performance data with expert panel input across the analysis window. Segmentation dimensions modeled included service type, technology, end-user industry, project size, and regional regulatory frameworks. Compound annual growth rates were derived from an assessment of market drivers, restraints, and strategic opportunities. Industry-specific forecast inputs included global semiconductor manufacturing capacity and R&D spending in the medical devices sector.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts affecting semiconductor supply and rapid technological obsolescence. Forecasts reflect underlying assumptions regarding market dynamics and regulatory stability. A model refresh is warranted upon material change in international trade policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Ticketing Solution Market
Digital Solutions
Cloud Monetization Market
Digital Solutions
Construction Design App Market
Digital Solutions
Graph Technology Market
Digital Solutions
Data Extraction Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
Digital Assistant Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Service Virtualization Market
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Global Domain and Hosting Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
Cloud Field Service Management (FSM) Market
Digital Solutions
Webrtc Market
Digital Solutions
Global Connected Enterprise Market
Digital Solutions
Location Targeted Mobile Advertising Market