
 Graph Technology Market | 2026-2036
Graph Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Graph Technology Market Analytics
The EU AI Act is broadening the addressable market for explainable graph systems as European enterprises seek auditable relationship-mapping tools for high-risk AI deployments. Neo4j, Inc. dominates native graph database deployments with its property graph model and Cypher query language. TigerGraph competes on massively parallel analytics for enterprise-scale fraud detection. Amazon Web Services, Inc. leverages Neptune to anchor cloud-native graph workloads within its broader data services ecosystem.
Graph technology encompasses data management systems that store entities as nodes and relationships as edges, enabling traversal queries across billions of connections with millisecond latency through index-free adjacency. Its primary commercial purpose centers on revealing non-obvious patterns in interconnected data for recommendation engines, supply chain optimization, and threat intelligence. Graph databases command the largest installed base among technology segments, while graph query languages such as GQL and openCypher are standardizing to reduce vendor lock-in. Knowledge graphs represent the fastest-growing application segment as pharmaceutical and technology firms build enterprise semantic layers for generative AI grounding.
The Federal Trade Commission scrutinizes algorithmic transparency in consumer-facing recommendation systems, pushing vendors toward interpretable graph architectures. ISO and IEC develop interoperability standards for graph query languages and property graph schemas, shaping procurement requirements for multinational enterprises. Healthcare regulators in the United States, including the FDA, examine knowledge graph applications for drug interaction validation and clinical trial matching. Stakeholders must monitor standardization timelines and regulatory divergence between jurisdictions when selecting graph platforms for cross-border deployments.
Market Dynamics
The EU AI Act's mandatory explainability requirements for high-risk AI systems are forcing enterprises to replace black-box neural networks with auditable knowledge graph architectures that expose relationship logic.
Growth Catalysts
- EU AI Act Compliance:European enterprises must deploy interpretable relationship-mapping tools for automated decision-making systems, creating procurement mandates for explainable graph platforms.
- Real-Time Fraud Detection:Financial institutions require millisecond-latency traversal across billions of transaction connections, driving native graph database deployments in banking and payments.
- Generative AI Grounding:Pharmaceutical and technology firms build enterprise semantic layers to reduce hallucinations in large language model outputs, accelerating knowledge graph construction.
Market Restraints
- Specialized Talent Scarcity:Shortage of engineers proficient in graph query languages and schema design limits deployment velocity and increases implementation costs.
- Legacy Data Migration Friction:Relational database incumbents resist displacement as enterprises face high switching costs for reconfiguring ETL pipelines and retraining analytics teams.
- Query Language Fragmentation:Divergence between Cypher, Gremlin, and GQL dialects creates vendor lock-in risks that procurement committees weigh against standardization timelines.
Strategic Opportunities
- Clinical Trial Matching:FDA interest in knowledge graph applications for drug interaction validation opens regulatory pathway for healthcare-specific graph platforms in the United States.
- Supply Chain Resilience:ISO interoperability standards for property graph schemas enable cross-enterprise data sharing for multinational manufacturers seeking disruption visibility.
- Federal Agency Standardization:Cloud hyperscalers and United States federal agencies drive platform consolidation, creating anchor customer opportunities for compliant vendors.
Industry Challenges
- Schema Design Complexity:Enterprise data teams struggle to model evolving relationship types across heterogeneous source systems, delaying production deployments.
- Performance-at-Scale Engineering:Maintaining sub-100ms traversal latency as node counts exceed tens of billions requires specialized hardware configurations and query optimization expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graph Technology Market |
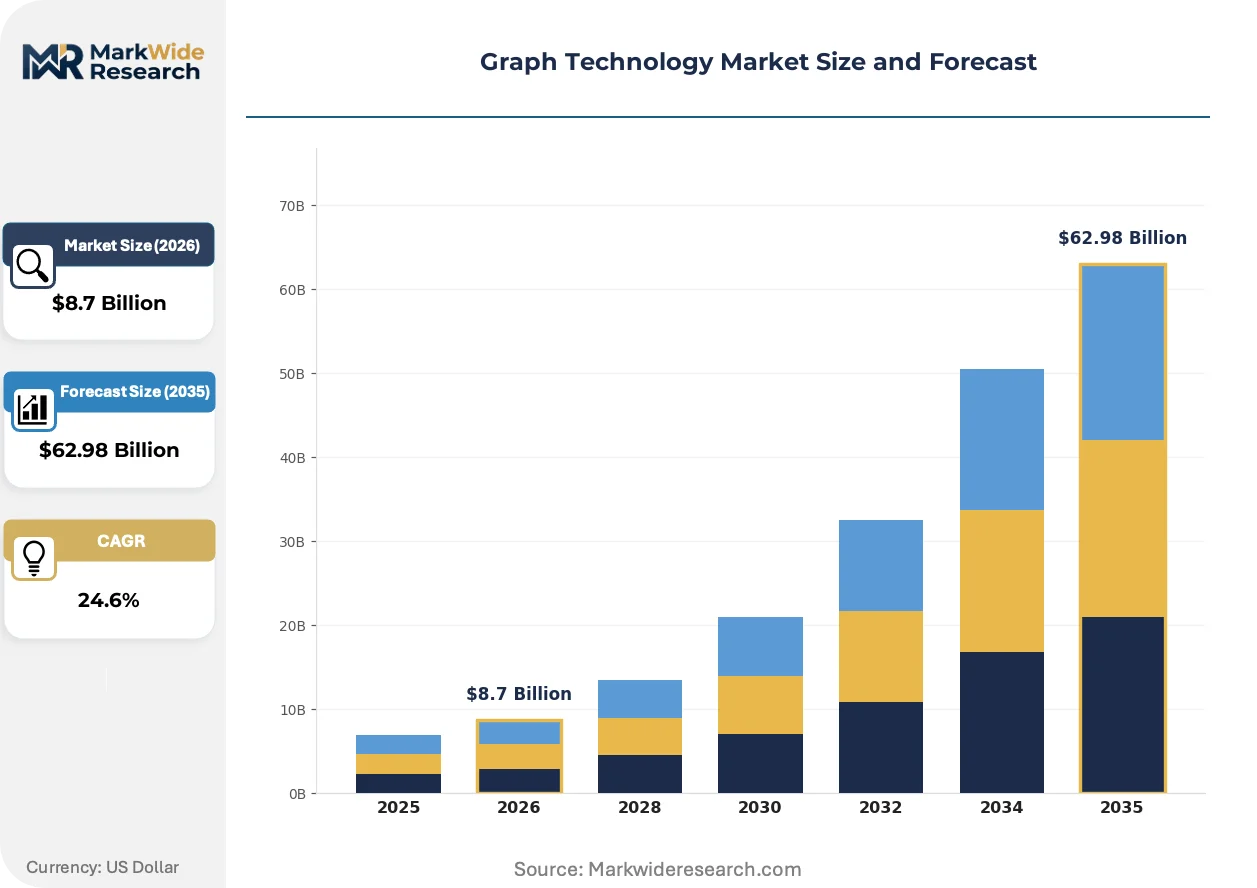
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Social Network Analysis, Fraud Detection, Recommendation Engines, Knowledge Graphs Deployment: On-Premises, Cloud, Hybrid, Managed Services Technology: Graph Databases, Graph Processing Frameworks, Graph Query Languages, Visualization Tools End User: Healthcare, Telecommunications, Retail, Finance |
| Companies Covered | Amazon Web Services, Inc., TigerGraph, Neo4j, Inc., DataStax, ArangoDB, Inc., IBM, Microsoft, Progress Software Corporation, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graph Technology Market Evolving Landscape
Graph technology is bifurcating into operational transaction processing and analytical pattern-discovery workloads, with vendors racing to unify both modes under single platforms.
Vector index integration is expanding into native graph databases, enabling hybrid semantic search that combines symbolic relationship traversal with embedding-based similarity matching. Biotechnology firms adopt these architectures to accelerate target identification by querying protein interaction networks with natural language prompts. The structural consequence is compression of the traditional ETL-to-warehouse-to-BI pipeline into unified graph serving layers.
GDPR Article 22 enforcement is tightening automated decision-making audit requirements across European member states. Enterprises processing personal data in recommendation engines must now expose the relational pathways leading to individual outcomes. Financial services and human resources technology vendors in Germany and France are rebuilding scoring models around explicit knowledge graphs to satisfy CNIL and BfDI scrutiny.
Buyer committees now require ISO/IEC 39075 GQL compliance as a procurement gate before vendor shortlisting, compressing evaluation cycles for non-standard platforms. Systems integrators in the United States and United Kingdom report that RFP language increasingly mandates openCypher or GQL certification, disqualifying proprietary query dialects. This certification-driven preference shift favors established vendors with standards-committee participation while raising barriers for emerging entrants.
Graph Technology Market Segmentation
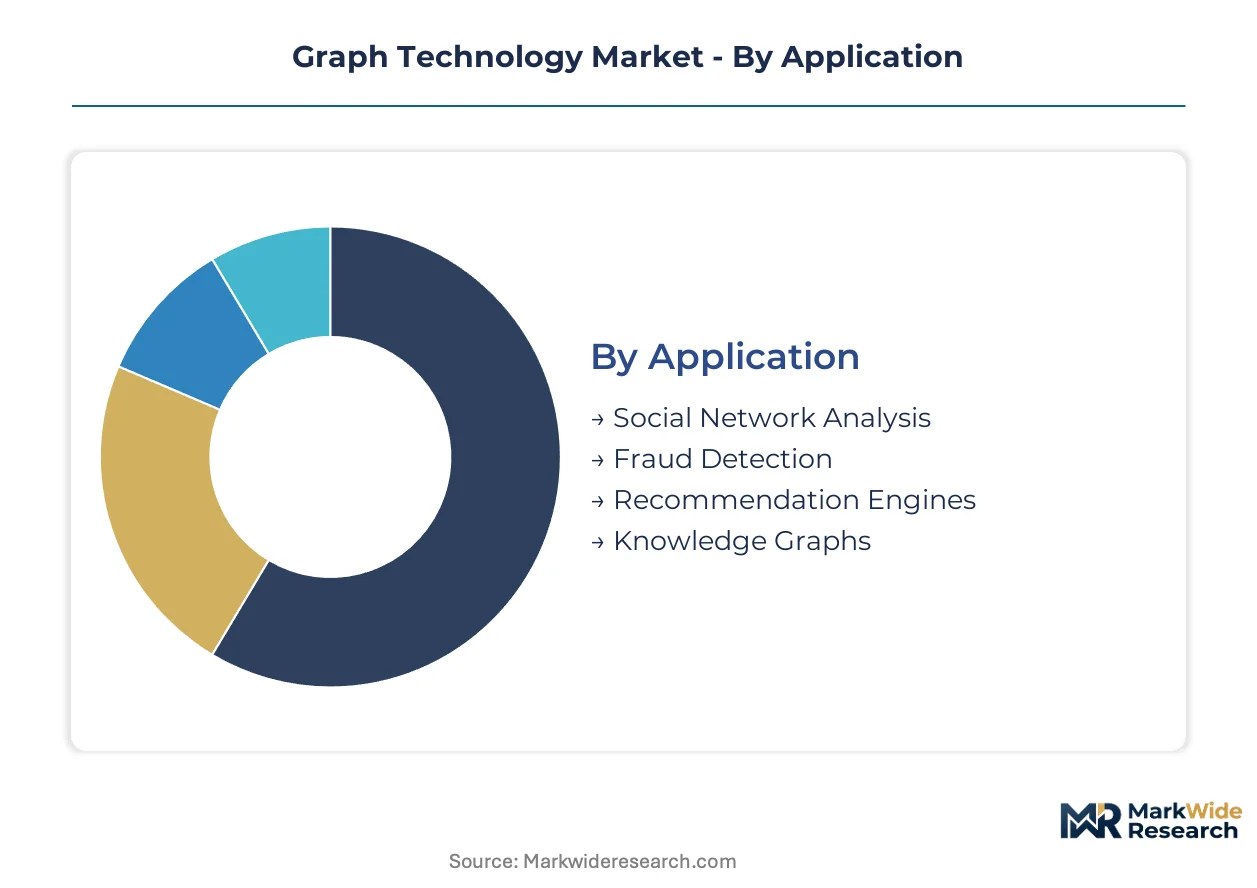
Graph technology vendors configure product roadmaps around four intersecting dimensions: application use case, infrastructure deployment model, core technology layer, and vertical industry requirements. Procurement committees evaluate platforms across these categories to match latency constraints, compliance mandates, and existing data architecture investments.
Application:
Buyer differentiation hinges on whether the primary need centers on real-time transaction processing or analytical pattern discovery across static datasets.
- Knowledge Graphs:Enterprise semantic layers map entities and relationships into machine-readable ontologies for generative AI grounding and regulatory audit trails. Pharmaceutical firms in the United States deploy these architectures to satisfy FDA documentation requirements for drug interaction validation.
- Fraud Detection:Native graph databases traverse billions of transaction edges with millisecond latency to flag anomalous connection patterns. Financial institutions in Germany and France prioritize this segment to meet BfDI and CNIL scrutiny of automated scoring systems.
- Recommendation Engines:Relationship traversal powers personalized content and product suggestions.
- Social Network Analysis:Influence mapping and community detection for marketing and security applications.
Volume sits with Fraud Detection; growth tilts toward Knowledge Graphs.
Deployment:
Cost tier and operational control requirements separate enterprise buyers selecting infrastructure configurations.
- Cloud:Hyperscaler-managed graph services eliminate capital expenditure for storage and compute scaling. United States federal agencies drive standardization here through FedRAMP-authorized platform procurement.
- Hybrid:Sensitive data resides on-premises while analytics workloads burst to cloud infrastructure. European enterprises favor this model to reconcile GDPR data residency rules with elastic compute demands.
- On-Premises:Complete operational control for classified or regulated environments.
- Managed Services:Vendor-operated deployments reducing internal graph engineering headcount requirements.
Volume concentrates in Cloud; Hybrid deployments are expanding most quickly among regulated industries.
Technology:
Maturity and standardization timelines fragment buyer preferences across the technology stack.
- Graph Databases:Native storage engines using index-free adjacency for traversal performance. ISO/IEC 39075 GQL compliance now gates procurement shortlists at multinational enterprises.
- Graph Query Languages:Standardized syntax for relationship traversal commands. Systems integrators report RFP language increasingly mandates openCypher or GQL certification.
- Graph Processing Frameworks:Distributed computation engines for batch analytics on billion-node graphs.
- Visualization Tools:Interactive rendering of network structures for analyst exploration and presentation.
Volume sits with Graph Databases; Graph Query Languages gain share fastest as standardization pressures mount.
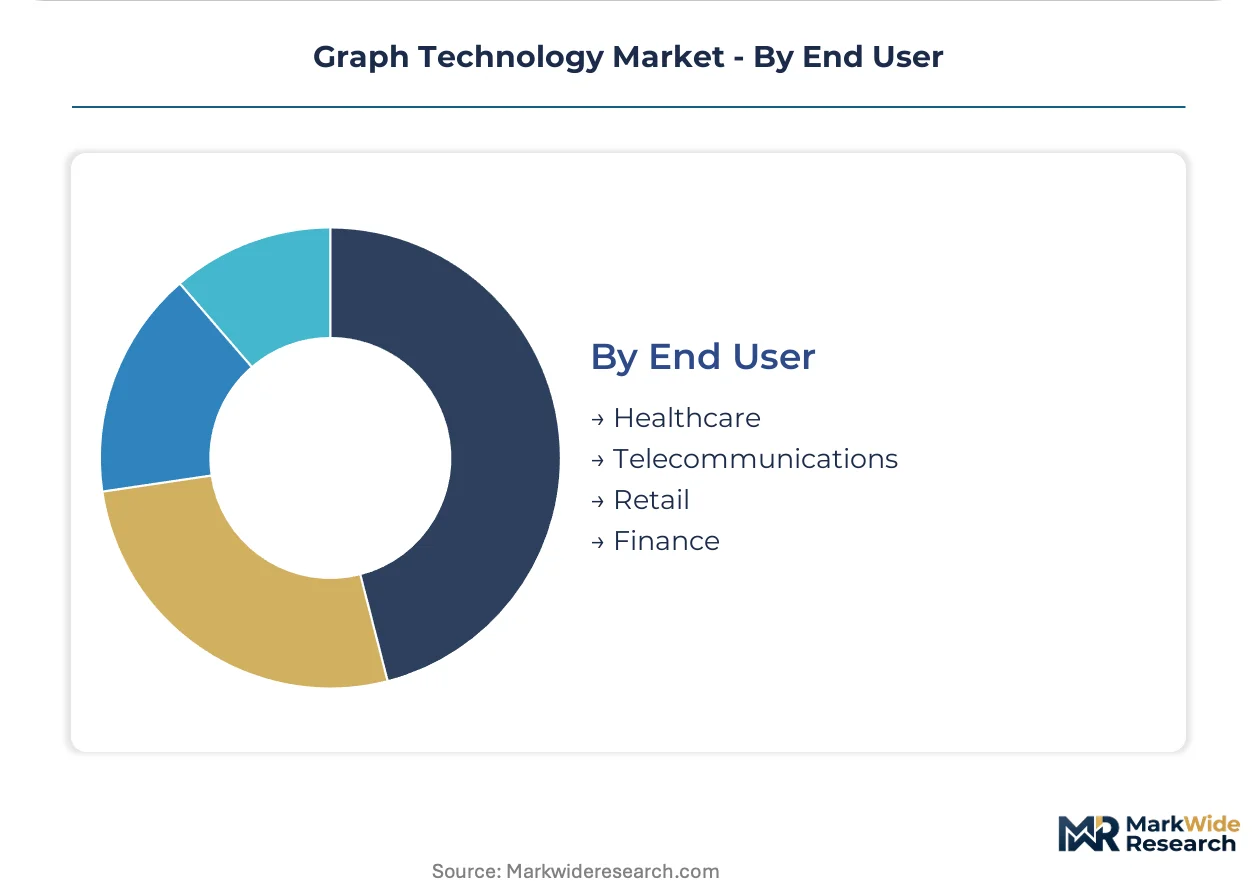
End User:
Vertical-specific compliance and latency requirements shape platform selection criteria.
- Finance:Real-time anti-money laundering and transaction monitoring with explainable relationship logic. EU AI Act mandates are accelerating knowledge graph procurement for automated credit decisions.
- Healthcare:Clinical trial matching and drug interaction networks requiring FDA-validated data lineage. Biotechnology firms integrate vector indices for protein interaction queries via natural language.
- Telecommunications:Network topology optimization and fraud prevention across subscriber connection graphs.
- Retail:Supply chain resilience mapping and customer journey analysis for inventory positioning.
Volume concentrates in Finance; Healthcare shows the steepest expansion trajectory as regulatory pathways clarify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors enterprise graph technology adoption, where hyperscaler headquarters and venture capital concentration accelerate platform deployment cycles. Federal procurement standardization and EU regulatory mandates are redistributing investment across national technology corridors.
United States
Cloud hyperscalers and federal agencies drive platform standardization through FedRAMP-authorized procurement. The FTC scrutinizes algorithmic transparency in consumer-facing recommendation systems, pushing vendors toward interpretable architectures. Greater Boston biotechnology clusters deploy knowledge graphs for protein interaction validation.
Germany
Automotive manufacturers and financial institutions require auditable relationship-mapping for automated decision systems. BfDI enforcement of GDPR Article 22 tightens audit requirements for scoring models in human resources technology. Berlin-Brandenburg hosts enterprise software vendors rebuilding compliance architectures around explicit knowledge graphs.
France
Pharmaceutical firms and banking conglomerates seek explainable AI infrastructure for high-risk deployment scenarios. CNIL oversight of automated decision-making mandates exposed relational pathways in recommendation engines. Paris-Saclay research clusters advance semantic layer construction for generative AI grounding.
United Kingdom
Financial services regulators and systems integrators mandate ISO/IEC 39075 GQL compliance in procurement specifications. Open Banking standards accelerate graph database deployment for transaction monitoring and fraud detection. London fintech corridors concentrate native graph engineering talent for real-time analytics workloads.
China
Technology conglomerates and telecommunications operators invest in distributed graph processing for network topology optimization. MIIT standards for data governance shape enterprise semantic layer construction. Yangtze River Delta manufacturing hubs deploy supply chain resilience mapping for disruption visibility.
Graph Technology Market Competitive Landscape
The competitive structure tilts toward cloud-native platform consolidation. Native graph database specialists and hyperscaler-managed services occupy distinct strategic tiers, with interoperability standardization compressing evaluation cycles for proprietary dialects. Two dominant competitive moves are reshaping positioning: strategic partnerships with systems integrators to accelerate enterprise deployment velocity, and vector index integration to capture hybrid semantic search demand from biotechnology and pharmaceutical segments.
Within the native graph database tier, Neo4j, Inc. and TigerGraph exemplify divergent technical philosophies—property graph traversal versus massively parallel analytics—while Amazon Web Services, Inc. anchors cloud-native deployment through managed service integration with broader data infrastructure ecosystems.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| TigerGraph |
| Neo4j, Inc. |
| DataStax |
| ArangoDB, Inc. |
| IBM |
| Microsoft |
| Progress Software Corporation |
| Oracle Corporation |
| Others |
Value Network & Pricing Analysis
Cloud compute spot pricing indices cascade through graph technology supply chains, compressing margins for on-premises hardware configurations while elevating SaaS-tiered subscription premiums for managed graph services.
Pricing Analysis
Throughput-based pricing anchors enterprise graph database contracts, with charges scaling per billion edges traversed monthly. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized deployments from self-managed open-source configurations. Pricing pressure stems from hyperscaler-managed services bundling graph engines with broader data infrastructure at marginal cost. Financial services buyers exhibit lowest price sensitivity due to regulatory compliance mandates, while mid-market technology firms drive hardest bargain negotiations.
Supply Chain Analysis
ISO/IEC 39075 GQL certification gates vendor qualification for multinational procurement shortlists, filtering non-compliant platforms from enterprise RFP pipelines. Hardware supply concentrates in Taiwan, South Korea, and the United States for specialized GPU and memory configurations supporting billion-node traversals. Graph database software draws from open-source foundations and proprietary query engine development. Single-source vulnerability runs through hyperscaler cloud infrastructure dependencies. Distribution runs through systems integrators and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Graph technology markets are consolidating around standardization pressures, with ISO query language mandates forcing proprietary dialect vendors toward acquisition or obsolescence.
For Market Incumbents: Anticipate hyperscaler encroachment by deepening FedRAMP certification portfolios and embedding vector index capabilities for hybrid semantic search. Fortify position through strategic partnerships with biotechnology firms building protein interaction networks. Prioritize backward integration into managed services to capture recurring revenue streams from cloud-averse European enterprises facing GDPR data residency constraints.
For New Entrants and Emerging Players: Mid-market healthcare providers in Germany and France present underserved buyer archetype seeking explainable AI infrastructure for automated clinical decision support. White-space targets include FDA-validated knowledge graph platforms for drug interaction validation and BfDI-compliant scoring model architectures. Go-to-market angle should emphasize rapid deployment timelines against legacy relational migration friction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vector-native graph engine specialists in Greater Boston and San Francisco corridors facing runway compression from certification-driven procurement delays. Long-term viability hinges on standards-committee participation securing GQL compliance moats. Acquisition target archetype: boutique healthcare graph consultancies with FDA submission track records. Signal to watch is CNIL enforcement velocity accelerating explainability mandates across French enterprise procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| GQL Standardization Certification | ISO/IEC 39075 compliance gates multinational enterprise procurement shortlists and disqualifies proprietary dialects. |
| Vector Index Integration | Hybrid semantic search capabilities capture biotechnology demand for natural language protein interaction queries. |
| FedRAMP Authorization Pursuit | United States federal agency procurement mandates anchor customer opportunities for compliant cloud-native platforms. |
| Healthcare Regulatory Pathway | FDA-validated data lineage opens pharmaceutical knowledge graph deployments for clinical trial matching applications. |
| Strategic Systems Integrator Partnership | Deployment velocity acceleration through channel relationships with United States and United Kingdom integration specialists. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with graph database engineering leads, enterprise IT procurement officers, healthcare regulatory affairs specialists, and systems integration partners. Secondary sources encompassed SEC 10-K disclosures from cloud hyperscalers, FDA device and drug approval databases, EU AI Act implementation guidance documents, and hyperscaler capital expenditure reports. Bottom-up deployment estimates triangulated against top-down market sizing from technology spending surveys.
Data-stream reconciliation across vendor revenue disclosures, enterprise procurement pipeline tracking, and regulatory certification timelines informed the analytical framework. Segmentation dimensions modeled encompass deployment model, organization size, vertical industry, query language standard, and regional regulatory cluster. CAGRs derived from curve-fitting historical adoption curves against compliance mandate effective dates and generative AI grounding demand inflections. Forecast inputs included cloud infrastructure pricing trajectories and ISO standardization committee publication schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement variance and hyperscaler bundling strategy pivots. Model assumptions reflect current regulatory timelines and technology standardization trajectories. A model refresh is warranted upon material change in GQL certification adoption velocity or federal procurement standardization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Database Management Platform Market
Digital Solutions
South Korea Digital Twin Market
Digital Solutions
Business Transcription Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Data Extraction Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Legal Transcription Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Europe Smart Government Market
Digital Solutions
Smart Government Market
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Global Inventory Optimization Software Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Equipment Tracking Software Market
Digital Solutions
Cloud Field Service Management (FSM) Market