
 Revops Platform Market | 2026-2036
Revops Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Revops Platform Market Analytics
Enterprise SaaS is broadening its share of RevOps platform deployments as manufacturing and financial services buyers accelerate adoption. Salesforce anchors the competitive landscape through its native CRM-to-revenue data lineage. Gong differentiates via proprietary conversation intelligence that feeds predictive deal scoring. Clari specializes in forecast-commitment workflows that reduce pipeline variance for large field sales organizations.
A RevOps platform integrates data from sales, marketing, and customer success operations into unified revenue intelligence systems, typically processing pipeline signals through machine learning models that score deal probability and predict quarterly attainment. The platform's primary commercial purpose is eliminating siloed forecasting by creating a single source of truth across customer-facing teams. Public cloud deployment leads functionality uptake due to faster implementation cycles and lower infrastructure overhead for mid-market buyers. Revenue forecasting functionality captures disproportionate margin attention as CFO offices demand greater predictability in board reporting. API-based integration types are expanding fastest as composable tech stacks replace monolithic CRM configurations.
The US Federal Trade Commission scrutinizes data aggregation practices in revenue intelligence tools, while the EU AI Act imposes risk-classification requirements on automated forecasting algorithms that influence compensation decisions. ISO 27001 certification has become a non-negotiable procurement filter for enterprise buyers evaluating vendor shortlists. Stakeholders must monitor how emerging algorithmic accountability rules reshape feature development roadmaps and cross-border data residency requirements.
Market Dynamics
AI-powered forecasting algorithms are compressing sales cycle visibility from quarterly snapshots to real-time probability scoring, forcing vendors to re-architect data pipelines around explainable machine learning models that satisfy emerging algorithmic accountability mandates.
Growth Catalysts
- GDPR and SOC 2 mandates:European and North American compliance requirements are accelerating certified data architecture procurement among enterprise SaaS buyers who treat ISO 27001 as a non-negotiable vendor filter.
- Manufacturing sector adoption:Industrial equipment sellers are deploying unified revenue intelligence to synchronize field sales with aftermarket service operations across distributed dealer networks.
- Public cloud deployment preference:Mid-market buyers favor SaaS delivery models that eliminate infrastructure overhead and compress implementation cycles relative to on-premise alternatives.
Market Restraints
- Data residency fragmentation:Cross-border data localization rules in Germany, France, and Switzerland force vendors to maintain region-specific infrastructure, raising operational complexity.
- Legacy CRM entrenchment:Incumbent customer relationship management platforms capture pipeline data in proprietary formats that resist standardized API extraction.
- Algorithmic audit costs:EU AI Act risk-classification requirements for automated compensation-influencing systems impose documentation and human-oversight burdens on feature development.
Strategic Opportunities
- Financial services vertical:Asset management and commercial banking sales organizations remain underpenetrated relative to technology sector adoption, presenting greenfield deployment potential.
- API-first composable stacks:Integration architectures that displace monolithic CRM configurations are expanding fastest among buyers seeking modular best-of-breed assembly.
- Conversation intelligence convergence:Natural language processing models trained on sales call transcripts are feeding predictive deal scoring engines that reduce forecast variance.
Industry Challenges
- Revenue operations talent scarcity:Organizations struggle to hire professionals who bridge data engineering, sales process design, and machine learning interpretation.
- Multi-system integration complexity:Unifying signals across marketing automation, customer success platforms, and contract lifecycle tools requires expensive custom pipeline development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Revops Platform Market |
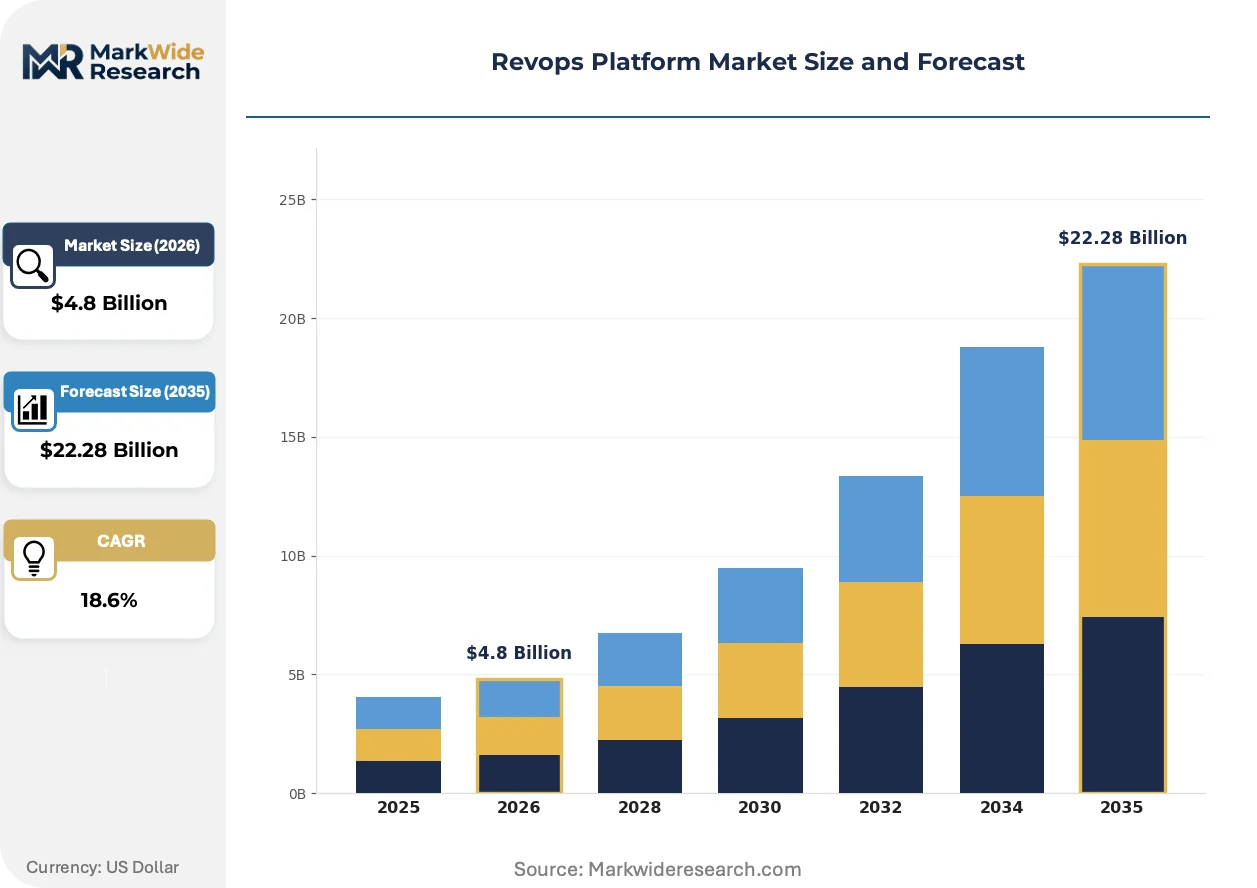
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Functionality: Sales Automation, Marketing Automation, Customer Analytics, Revenue Forecasting End User Type: SMEs, Large Enterprises, Startups, Consulting Firms Integration Type: API-Based, Pre-built Connectors, Custom Integrations, Others |
| Companies Covered | HubSpot, Salesforce, Clari, Salesloft, Gong, Zapier, Vitally, Apollo, Aviso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Revops Platform Market Evolving Landscape
Machine learning inference at the edge of sales workflows is collapsing the latency between signal capture and forecast adjustment, enabling real-time pipeline interventions that were previously impossible with batch-processed analytics.
Natural language processing engines trained on sales conversation transcripts are modularizing how deal intelligence gets constructed, allowing revenue teams to assemble custom scoring models from component parts rather than accepting vendor-defined algorithms. Enterprise field sales organizations are adopting these modular architectures fastest, building proprietary signal combinations that differentiate their forecasting precision from competitors using standardized configurations.
The EU AI Act imposes risk-tier documentation requirements on automated systems that influence compensation decisions, forcing vendors to engineer human-in-the-loop approval workflows for high-stakes forecast adjustments. This regulatory friction is compressing feature release cycles as product teams allocate engineering capacity to compliance infrastructure. European deployments are experiencing the steepest implementation delays as buyers demand audit trails that satisfy national supervisory authorities.
Chief financial officers are consolidating vendor relationships around platforms that deliver board-ready attainment predictions, displacing point solutions that require manual reconciliation across spreadsheets. This concentration behavior is reshaping procurement evaluation criteria toward unified data lineage and out-of-the-box executive dashboards. United States Fortune 500 sales organizations are driving this pattern most aggressively, using procurement leverage to extract implementation guarantees and dedicated customer success resources.
Revops Platform Market Segmentation
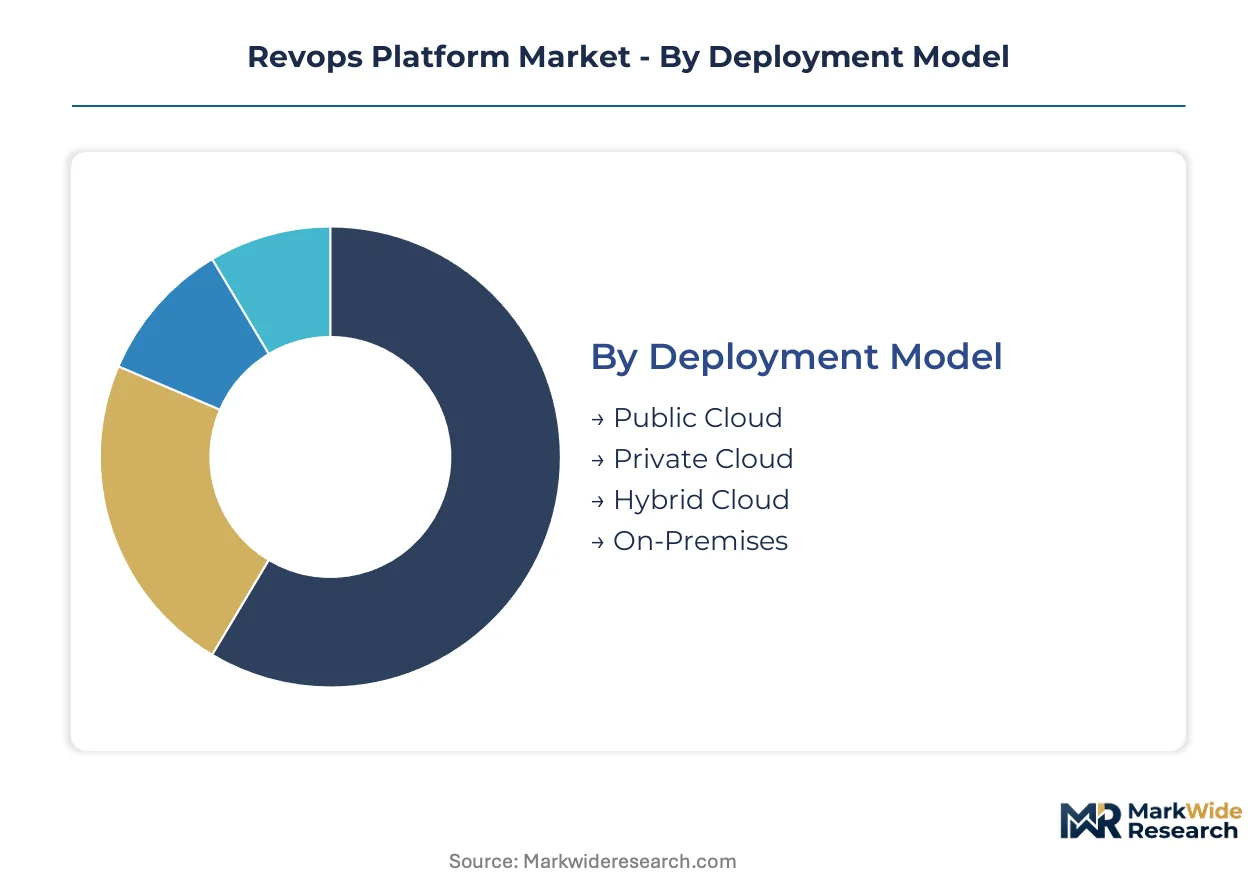
RevOps platform buyers segment their procurement decisions across deployment architecture, functional depth, and integration complexity. Each dimension carries distinct cost-to-value tradeoffs that shape vendor selection criteria and implementation timelines.
Deployment Model:
Mid-market buyers prioritize total cost of ownership and speed-to-value when selecting infrastructure architecture.
- Public Cloud:Multi-tenant SaaS architectures eliminate server provisioning overhead and compress implementation cycles. United States mid-market technology companies favor this model for quarterly board reporting deadlines.
- Private Cloud:Single-tenant environments with dedicated compute resources address data residency mandates. German financial services organizations require this architecture for BaFin supervisory compliance.
- Hybrid Cloud:Workload-splitting between on-premise and cloud resources balances latency-sensitive operations with elastic scaling. Japanese automotive suppliers deploy this model for field sales synchronization across distributed dealer networks.
- On-Premises:Fully self-hosted installations retain complete data custody within corporate firewalls. Swiss pharmaceutical sales organizations mandate this architecture for product launch confidentiality.
Public Cloud leads on scale; Hybrid Cloud leads on momentum.
Functionality:
CFO offices concentrate procurement evaluation on modules that reduce forecast variance in board presentations.
- Revenue Forecasting:Machine learning models score deal probability and predict quarterly attainment with explainable outputs. United States Fortune 500 sales organizations drive disproportionate margin attention to this capability.
- Sales Automation:Workflow engines capture pipeline signals and trigger next-best-action recommendations. Manufacturing equipment sellers in Texas and Ohio deploy these tools to synchronize field reps with aftermarket service teams.
- Marketing Automation:Campaign-to-revenue attribution modules track lead progression across funnel stages. Asset management marketers in London use these systems to demonstrate ROI on institutional investor outreach.
- Customer Analytics:Churn prediction and expansion scoring models unify usage data with contract telemetry. SaaS customer success teams in California leverage these insights for net revenue retention reporting.
Revenue Forecasting dominates procurement budgets; Customer Analytics expands most quickly.
End User Type:
Organizational maturity and data infrastructure sophistication determine platform configuration complexity.
- Large Enterprises:Multi-divisional deployments require customized data lineage across CRM, ERP, and contract lifecycle systems. Procurement teams in New York and Chicago extract implementation guarantees and dedicated customer success resources.
- SMEs:Standardized configurations with out-of-box dashboards accelerate time-to-value. Regional commercial banking sales organizations in Atlanta and Dallas favor pre-configured forecasting templates.
- Startups:Lightweight implementations prioritize core pipeline visibility over advanced predictive features. Venture-backed SaaS companies in San Francisco and Boston adopt these platforms for Series B fundraising preparation.
- Consulting Firms:Multi-client deployments demand tenant isolation and cross-customer analytics benchmarking. Revenue operations advisors in London and Singapore use these architectures to deliver comparative performance insights.
Large Enterprises lead on scale; Startups lead on momentum.
Integration Type:
Technical architecture preferences are shifting from monolithic CRM configurations toward composable best-of-breed assembly.
- API-Based:REST and GraphQL endpoints enable real-time data synchronization across heterogeneous tech stacks. European buyers in France and the Netherlands favor this flexibility for GDPR-compliant data residency controls.
- Pre-built Connectors:Native integrations with Salesforce, HubSpot, and Marketo accelerate deployment without engineering resources. Mid-market healthcare technology sellers in Minnesota and Massachusetts prioritize this reduced-IT-dependency model.
- Custom Integrations:Bespoke pipeline development unifies proprietary internal systems with standardized revenue intelligence layers. Industrial conglomerates in Germany and Japan require these configurations for legacy ERP connectivity.
- Others:File-based batch transfers and middleware platforms serve edge cases with limited real-time requirements. Public sector contractors in Virginia and Maryland use these methods for air-gapped security environments.
API-Based leads on scale; Pre-built Connectors leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 sales organizations in the United States drive the dominant share of platform procurement, while compliance mandates in Europe and Asia-Pacific reshape vendor deployment architectures.
United States
Enterprise SaaS buyers in New York and Chicago extract implementation guarantees and dedicated customer success resources from vendors. The FTC scrutinizes data aggregation practices in revenue intelligence tools. Silicon Valley venture-backed startups adopt lightweight implementations for Series B fundraising preparation.
Germany
Industrial equipment sellers deploy unified revenue intelligence to synchronize field sales with aftermarket service operations across distributed dealer networks. BaFin supervisory compliance mandates private cloud architectures for financial services organizations. Bavarian automotive suppliers favor hybrid cloud deployments for field sales synchronization.
United Kingdom
Asset management marketers in London use campaign-to-revenue attribution modules to demonstrate ROI on institutional investor outreach. GDPR requirements accelerate certified data architecture procurement among enterprise buyers. Revenue operations advisors in the capital deliver comparative performance insights through multi-client deployments.
Japan
Automotive suppliers deploy hybrid cloud models for field sales synchronization across distributed dealer networks. METI standards influence data residency requirements for enterprise software procurement. Nagoya-based industrial conglomerates require custom integrations for legacy ERP connectivity.
Switzerland
Pharmaceutical sales organizations mandate on-premises architectures for product launch confidentiality. Swissmedic oversight shapes data custody requirements for life sciences technology procurement. Basel-based enterprises prioritize complete data sovereignty within corporate firewalls.
Revops Platform Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to bridge CRM-native data lineage with specialized forecasting intelligence. The competitive structure concentrates around three tiers: established CRM platforms with native revenue modules, pure-play forecasting specialists, and workflow automation integrators. Two strategic archetypes define differentiation: conversation intelligence engines that feed predictive scoring, and forecast-commitment workflow providers that reduce pipeline variance. M&A activity and API-first ecosystem expansion represent the dominant competitive vectors reshaping vendor positioning.
Within the pure-play forecasting tier, Clari and Gong exemplify specialized architectures that compress sales cycle visibility through machine learning inference. Salesforce anchors the CRM-native tier through data lineage integration. Among workflow automation providers, Zapier occupies a position enabling composable tech stack assembly for mid-market buyers seeking modular best-of-breed configurations.
| Leading Market Players |
|---|
| HubSpot |
| Salesforce |
| Clari |
| Salesloft |
| Gong |
| Zapier |
| Vitally |
| Apollo |
| Aviso |
| Others |
Value Network & Pricing Analysis
Fortune 500 sales organizations in the United States concentrate procurement leverage, compressing vendor margins through volume-based SaaS tiering and implementation guarantee demands.
Pricing Analysis
Distributor margins in the RevOps platform channel run thin as direct enterprise sales teams capture the premium tier. Pricing stratifies across enterprise, mid-market, and startup tiers with differentiation driven by data residency controls and API call volume limits. Pricing pressure stems from CFO offices consolidating vendor relationships around unified forecasting suites. Startups exhibit highest price sensitivity while financial services buyers absorb premiums for private cloud architectures.
Supply Chain Analysis
Reverse-logistics flows for data migration and platform offboarding remain underdeveloped, creating switching-cost stickiness that vendors exploit. Cloud infrastructure provisioning concentrates in the United States, Ireland, and Germany to satisfy data sovereignty mandates. Compute resources and machine learning inference capacity feed from hyperscaler partnerships. Single-source vulnerability sits with AWS and Azure dominance in certified compliance zones. Distribution runs through direct sales teams for enterprise accounts and self-service portals for mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
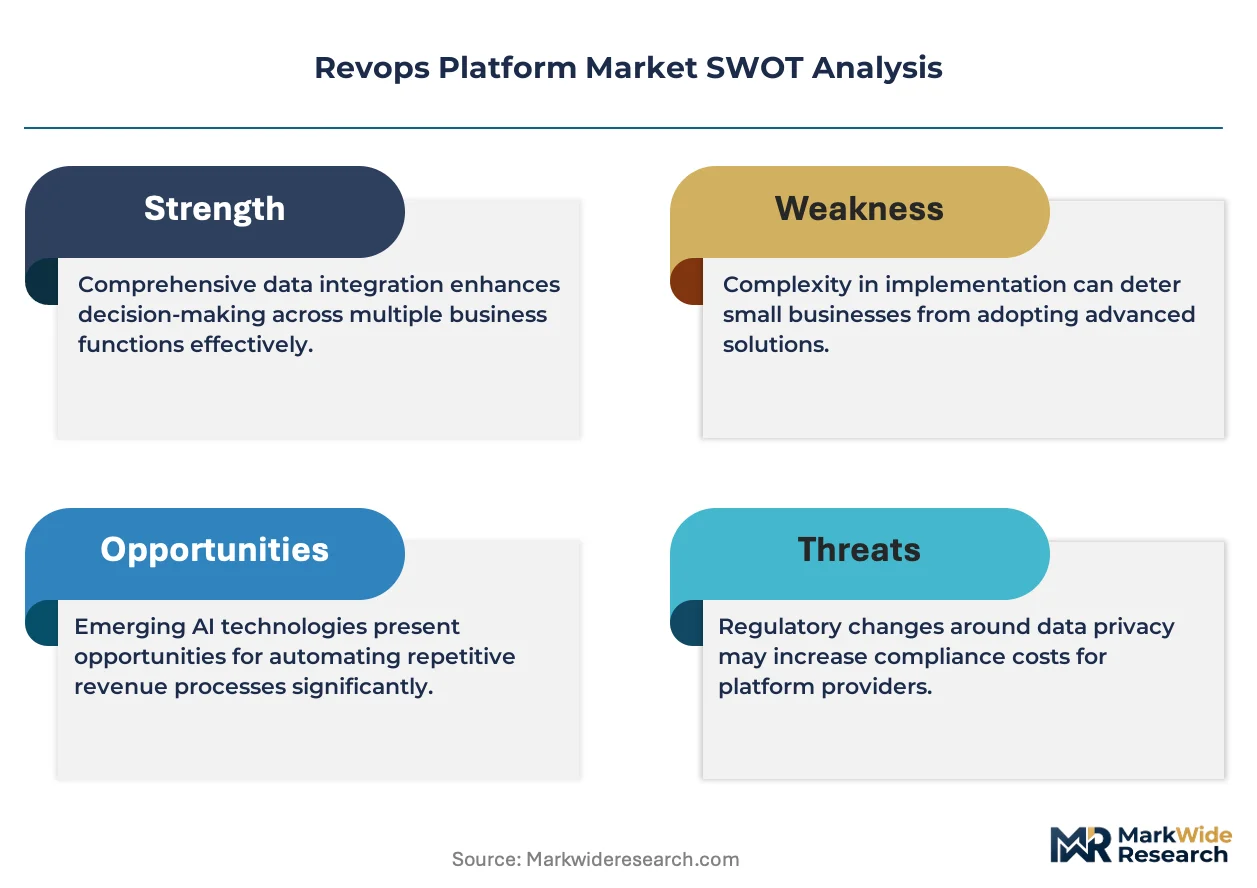
The RevOps platform market reads as a late-cycle quality story as buyers shift procurement criteria toward ISO 27001-certified architectures and explainable AI documentation.
For Market Incumbents: Anchor forecasting precision through proprietary conversation intelligence pipelines that resist commoditization. Defend against API-first composable challengers by deepening native CRM data lineage. Invest in human-in-the-loop compliance infrastructure to satisfy EU AI Act risk-tier documentation before competitors achieve certification parity. For New Entrants and Emerging Players: GDPR and SOC 2 mandates in Europe and North America open a window for compliance-native architectures that incumbent vendors retrofit slowly. Target financial services verticals in London and Frankfurt where asset management sales organizations remain underpenetrated. Lead with modular API-based deployment to displace monolithic CRM configurations in mid-market manufacturing accounts. For Investors and Strategic Acquirers: Private equity firms with SaaS portfolio expertise are the most active acquirer in this space, consolidating point-solution vendors into unified revenue intelligence suites. Acquisition targets should demonstrate proprietary machine learning models with audit-trail documentation for algorithmic accountability. Monitor EU AI Act enforcement patterns for early signals of compliance-cost advantage shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified data lineage from CRM to forecasting reduces manual reconciliation for CFO offices. |
| Acquisition of Specialist Firm | Conversation intelligence engines feed predictive scoring models that compress sales cycle visibility. |
| Strategic Partnership | Hyperscaler alliances accelerate certified data architecture deployment for European buyers. |
| Product Launch | Human-in-the-loop approval workflows satisfy EU AI Act compensation-influencing system requirements. |
| Geographic Expansion | Region-specific infrastructure addresses BaFin and Swissmedic data custody mandates. |
Research Methodology
Direct dialogue with revenue operations leaders, CFO office procurement directors, platform engineers, and integration specialists anchored the qualitative foundation. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie enterprise software rankings, and GDPR enforcement databases. Bottom-up deployment estimates across organization sizes and verticals triangulated against top-down SaaS spend projections.
Segment-level outputs across deployment models, functionality modules, end-user types, and integration architectures populated the analytical framework across the projection horizon. CAGRs derived from weighted average growth assumptions by buyer maturity tier and regional compliance intensity. Forecast inputs incorporated API adoption velocity curves and algorithmic accountability regulatory phase-in schedules.
Revisions become necessary when EU AI Act enforcement intensifies, hyperscaler pricing resets occur, or Fortune 500 procurement consolidation accelerates beyond modeled rates. Practitioners should monitor regulatory guidance publications and enterprise RFP requirement shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Service Orchestration Market
Digital Solutions
Voice Picking Headset Market
Digital Solutions
Global Product Lifecycle Management Market
Digital Solutions
North America API Management Market
Digital Solutions
France Digital Twin Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Defense IT Spending Market
Digital Solutions
Distributed Order Orchestration Market
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Graph Technology Market
Digital Solutions
Web Content Management Market