
 IT Operations and Service Management (ITOSM) Market | 2026-2036
IT Operations and Service Management (ITOSM) Market Size, Share, and Industry Trends Forecast 2026-2036
IT Operations and Service Management (ITOSM) Market Foresight
Platform licensing revenue is reconfiguring margin pools away from perpetual software sales toward recurring subscription streams. ServiceNow dominates enterprise IT workflow orchestration through its native cloud architecture. Microsoft Corporation extends platform stickiness by embedding ITOSM capabilities within Azure and Microsoft 365 ecosystems. BMC Software anchors mainframe-era accounts with hybrid operations bridging on-premises and cloud environments.
IT Operations and Service Management encompasses the integrated processes, tools, and methodologies used to deliver, monitor, and optimize enterprise technology services, typically leveraging event correlation engines, configuration management databases, and automated remediation playbooks to maintain service level agreements. The discipline ensures operational continuity across distributed infrastructure while minimizing mean time to resolution for service disruptions. Cloud-Based deployment models capture the fastest expansion as organizations retire data center footprints, while Help Desk and Incident Management services command the largest revenue share due to their universal applicability across enterprise tiers. Artificial Intelligence and Automation technologies are displacing rules-based workflows, concentrating vendor R&D spending on predictive analytics and autonomous remediation capabilities.
The US Federal Risk and Authorization Management Program and the European Union's NIS2 Directive impose stringent operational resilience requirements on critical infrastructure operators, directly expanding mandatory ITOSM procurement scope. ISO 20000 and ITIL 4 standards shape service maturity benchmarks that enterprise buyers use to qualify vendors and structure outsourcing contracts. Stakeholders must weigh sovereign data requirements against cloud platform consolidation as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
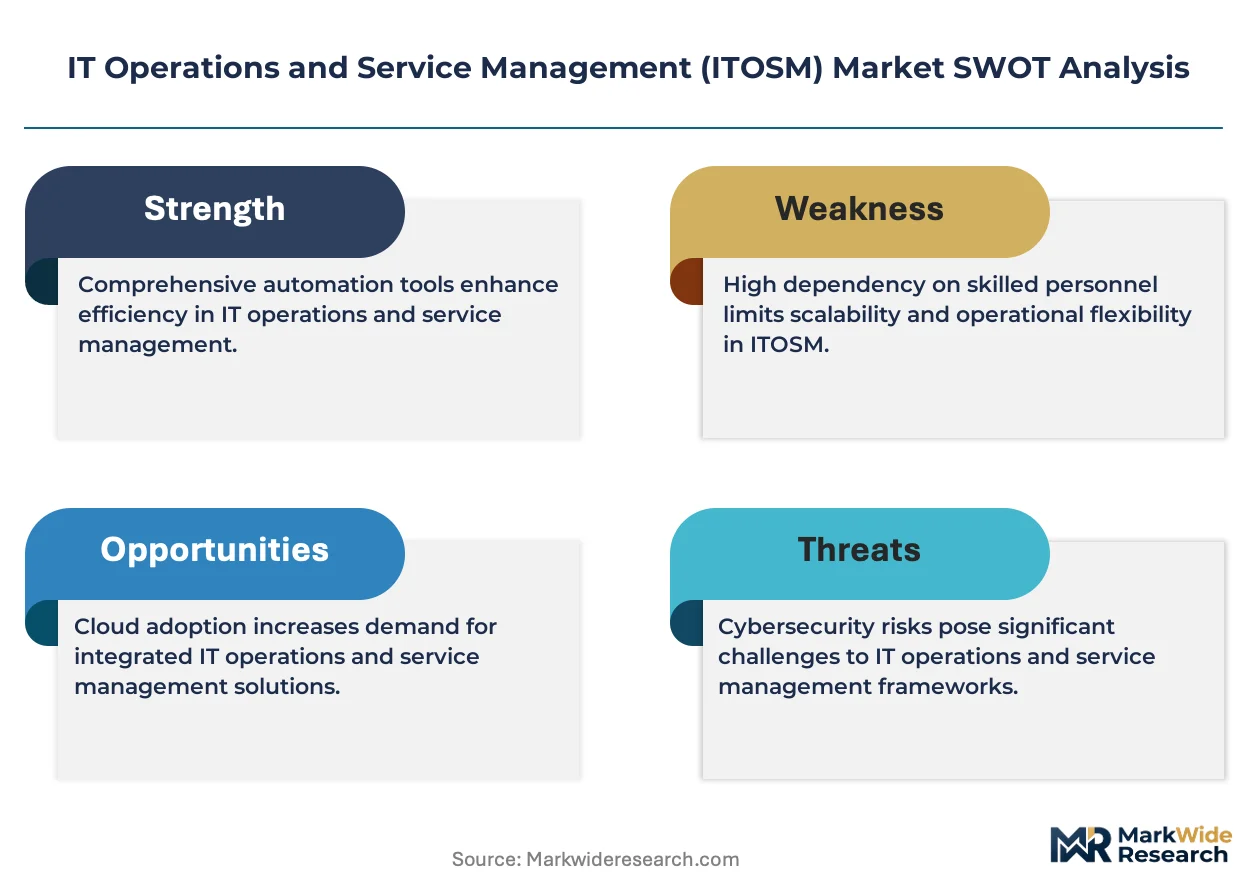
Cloud migration among financial services institutions is compressing legacy infrastructure footprints while forcing platform consolidation across enterprise IT estates. ISO 20000 and ITIL 4 frameworks are reshaping procurement criteria, elevating service maturity benchmarks above feature-checklist evaluations.
Growth Catalysts
- ITIL 4 framework adoption:European enterprises are mandating ITIL 4-aligned service catalogs in outsourcing RFPs, expanding addressable market for certified vendors.
- AI-driven predictive analytics:Event correlation engines with machine learning capabilities are reducing mean time to resolution by automating root-cause analysis.
- India's digital infrastructure modernization:RBI-mandated operational resilience requirements for banks and NBFCs are accelerating ITOSM procurement across Mumbai, Bangalore, and Hyderabad clusters.
Market Restraints
- Specialized talent scarcity:Shortage of Site Reliability Engineers with hybrid cloud-mainframe expertise constrains implementation velocity for complex migrations.
- Data sovereignty fragmentation:Divergent localization requirements across Germany, India, and US jurisdictions force redundant infrastructure investments.
- Legacy integration technical debt:COBOL-era systems in financial services resist API-native orchestration, extending project timelines.
Strategic Opportunities
- Edge computing convergence:Distributed telemetry from IoT endpoints is creating demand for lightweight ITOSM agents outside traditional data center boundaries.
- EU NIS2 Directive compliance:Mandatory operational resilience reporting for critical infrastructure operators opens consulting and managed services revenue streams.
- Sovereign cloud expansion:Germany's Gaia-X and India's MeitY empanelment requirements favor domestic cloud providers with embedded ITOSM tooling.
Industry Challenges
- Multi-cloud orchestration complexity:Enterprises struggle to maintain unified service level agreements across AWS, Azure, and Google Cloud environments.
- ISO 20000 certification timeline:Protracted audit cycles delay go-live dates for outsourcing contracts tied to service maturity benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Operations and Service Management (ITOSM) Market |
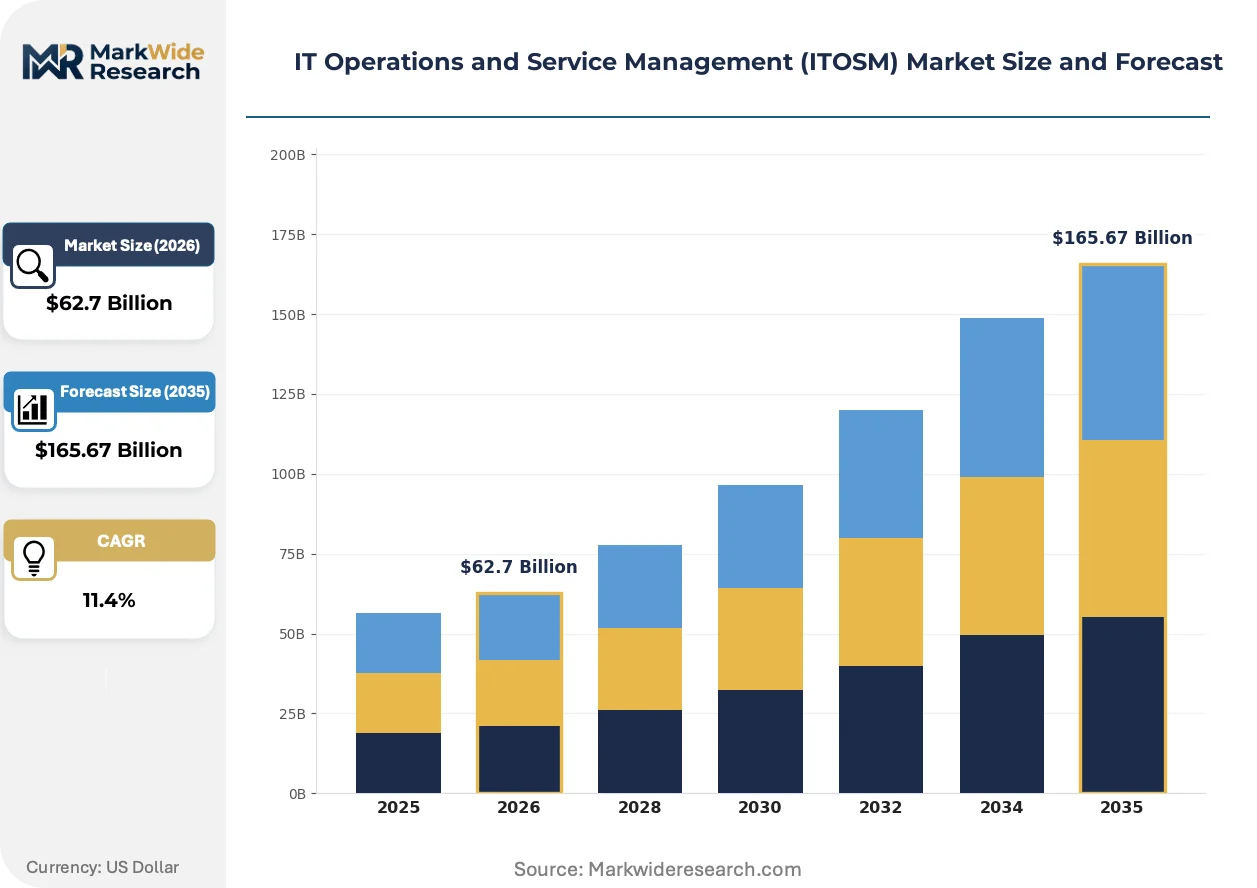
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $165.67 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Help Desk, IT Asset Management, Incident Management, Change Management Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Service End User: Small Enterprises, Large Enterprises, Government, Educational Institutions Technology: Artificial Intelligence, Machine Learning, Automation, Analytics |
| Companies Covered | ServiceNow, BMC Software, Broadcom, IBM Corporation, Ivanti, Atlassian, Microsoft Corporation, Oracle Corporation, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Operations and Service Management (ITOSM) Market Shifts & Advancements
Artificial Intelligence and Automation technologies are displacing rules-based workflows across IT operations, concentrating vendor R&D spending on predictive analytics and autonomous remediation capabilities rather than monitoring dashboards.
Generative AI copilots for incident response are collapsing the tier-1 help desk staffing model by synthesizing runbook knowledge and suggesting remediation steps in natural language. Mid-market enterprises in the United States are piloting these tools aggressively, compressing headcount ratios from fifteen analysts per thousand endpoints toward eight. The structural consequence is a bifurcation between premium autonomous platforms and commoditized ticketing systems.
The European Union's NIS2 Directive is mandating incident reporting timelines and supply chain security attestations for critical infrastructure operators. Financial services and energy utilities face the steepest compliance curves, with German regulators already enforcing binding technical standards through BSI. Vendors are responding by embedding compliance documentation automation directly into service management workflows.
Enterprise buyers are unbundling after-sales support from perpetual license agreements, preferring consumption-based pricing tied to ticket volume or automated resolution rates. This pattern is most visible among US healthcare systems navigating HIPAA audit cycles, where CFOs demand cost predictability. Channel partners are restructuring compensation models away from upfront commissions toward recurring revenue shares.
IT Operations and Service Management (ITOSM) Market Segmentation
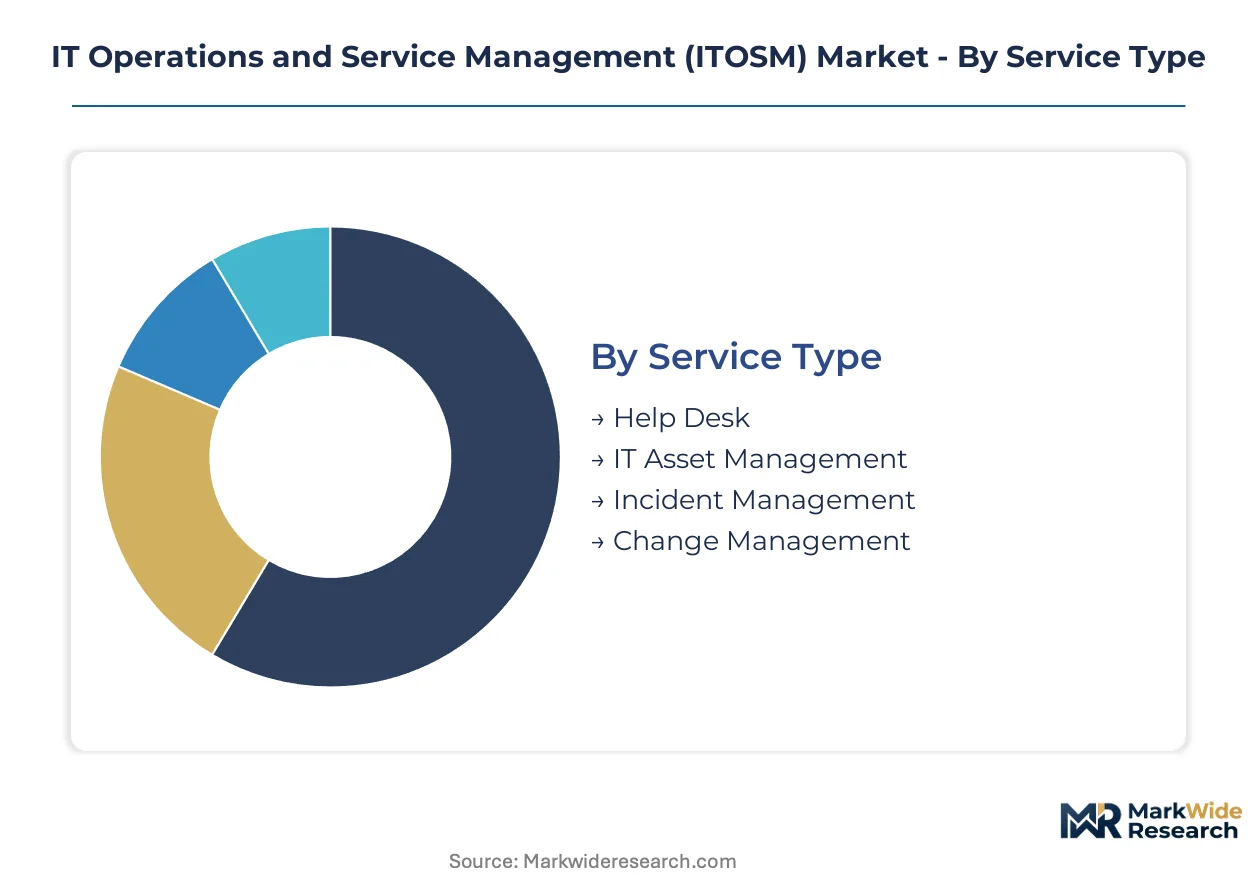
ITOSM procurement patterns diverge sharply across deployment architectures and organizational scale, with cloud-native solutions displacing perpetual licenses while AI-augmented service tiers command premium positioning. Understanding these fault lines reveals where vendor R&D investments concentrate and which customer profiles drive margin expansion.
Service Type:
Cost tier differentiation separates commoditized support functions from strategic workflow orchestration capabilities that anchor enterprise outsourcing contracts.
- Help Desk:Tier-1 incident intake and routing functions, typically delivered through web portals, chatbots, and voice queues. Demand concentrates among US healthcare systems navigating HIPAA audit cycles, where CFOs demand cost predictability through consumption-based pricing tied to ticket volume.
- Incident Management:Root-cause analysis and remediation orchestration leveraging event correlation engines and automated playbooks. European financial institutions under NIS2 Directive mandates are expanding procurement scope here, with German regulators enforcing binding technical standards through BSI.
- IT Asset Management:Configuration management database maintenance and lifecycle tracking across hardware and software estates.
- Change Management:Risk assessment workflows for production deployments, increasingly embedded in DevOps pipelines.
Help Desk holds installed capacity. Incident Management is rotating up the share rankings.
Deployment Model:
Application architecture preferences are bifurcating between cloud-native consolidation and sovereign data requirements that preserve on-premises footprints.
- Cloud-Based:Multi-tenant SaaS delivery with automatic updates and elastic scaling. India's digital infrastructure modernization—driven by RBI-mandated operational resilience requirements for banks and NBFCs—is accelerating procurement across Mumbai, Bangalore, and Hyderabad clusters despite data localization pressures.
- Hybrid:Orchestration layers bridging legacy mainframe assets with cloud-native services. Financial services institutions in Germany face particular complexity here as Gaia-X sovereignty requirements intersect with COBOL-era technical debt.
- On-Premises:Single-tenant installations for air-gapped environments and classified workloads.
- Managed Service:Third-party operational responsibility for entire ITOSM stacks, priced per endpoint or resolution SLA.
Cloud-Based deployments are climbing the fastest. Hybrid configurations retain strategic accounts with compliance complexity.
End User:
Customer type determines feature depth, with large enterprises demanding predictive analytics while smaller buyers prioritize out-of-box functionality.
- Large Enterprises:Global service catalogs with multi-language support and federated CMDB architectures. US federal agencies under FedRAMP authorization requirements are expanding mandatory procurement scope, directly benefiting vendors with existing ATOs.
- Small Enterprises:Standardized templates with rapid deployment and minimal customization. Mid-market buyers in the United States are piloting generative AI copilots aggressively, compressing headcount ratios from fifteen analysts per thousand endpoints toward eight.
- Government:Sovereign cloud mandates and supply chain security attestations.
- Educational Institutions:Semester-cycle pricing and student-facing service portals.
Large Enterprises hold installed capacity. Small Enterprises are gaining share fastest as AI-augmented tiers democratize access.
Technology:
Maturity gradients separate experimental capabilities from production-hardened automation stacks that vendors are embedding as standard features.
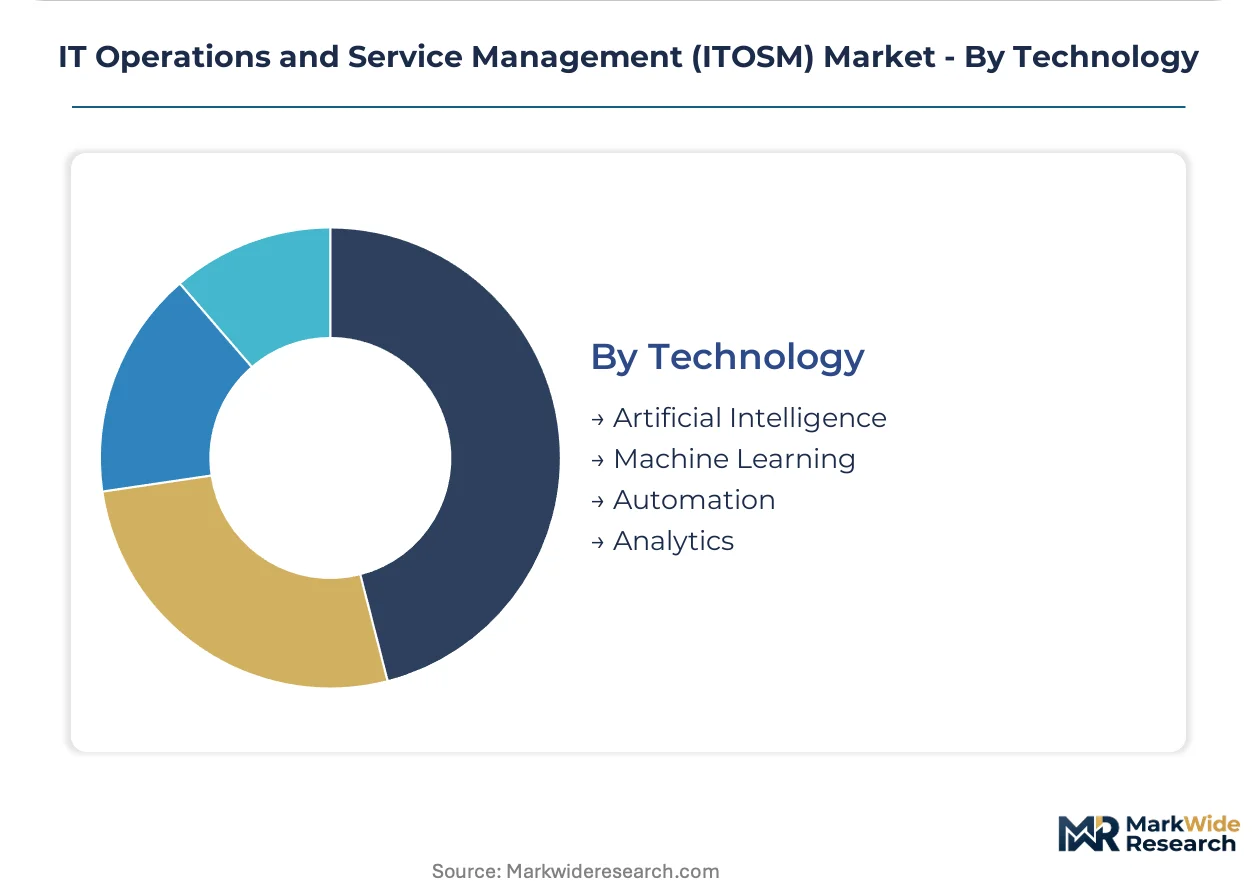
- Automation:Rules-based and AI-driven remediation playbooks that execute without human intervention. Event correlation engines with machine learning capabilities are reducing mean time to resolution by automating root-cause analysis across distributed infrastructure.
- Artificial Intelligence:Natural language interfaces for incident triage and knowledge synthesis. Generative AI copilots are collapsing the tier-1 help desk staffing model by synthesizing runbook knowledge and suggesting remediation steps.
- Machine Learning:Predictive models for capacity planning and anomaly detection trained on historical telemetry.
- Analytics:Operational dashboards and compliance reporting for ISO 20000 and ITIL 4 maturity benchmarks.
Automation holds installed capacity. Artificial Intelligence is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Germany demonstrate the sharpest price elasticity as sovereign data mandates inflate total cost of ownership, while US federal agencies absorb premium pricing for FedRAMP-authorized platforms without procurement friction.
United States
Healthcare systems navigating HIPAA audit cycles and federal agencies under FedRAMP requirements anchor domestic demand. The SEC's cybersecurity disclosure rules for publicly traded companies expand mandatory ITOSM procurement scope. Silicon Valley clusters and Washington DC metro corridors concentrate pilot deployments of generative AI copilots that compress help desk staffing ratios.
Germany
Gaia-X sovereignty requirements intersect with COBOL-era technical debt in financial services, creating hybrid complexity that preserves on-premises footprints. BSI enforces binding technical standards under NIS2 Directive mandates for critical infrastructure operators. Frankfurt and Munich banking clusters drive incident management procurement for operational resilience reporting.
India
RBI-mandated operational resilience requirements for banks and NBFCs accelerate cloud-based procurement despite data localization pressures. MeitY empanelment requirements favor domestic providers with embedded tooling. Mumbai, Bangalore, and Hyderabad technology corridors concentrate implementation velocity for digital infrastructure modernization.
United Kingdom
Financial conduct regulators impose operational resilience deadlines that elevate ITIL 4-aligned service catalogs in outsourcing RFPs. The Financial Conduct Authority's third-party risk management rules expand vendor due diligence scope. London's insurance and fintech clusters drive demand for predictive analytics capabilities.
Japan
METI's cybersecurity framework for critical infrastructure operators mandates incident response automation timelines. Financial institutions face convergence of aging mainframe assets and cloud-native service requirements. Tokyo and Osaka enterprise hubs concentrate procurement for multi-language service catalogs with federated CMDB architectures.
IT Operations and Service Management (ITOSM) Market Competitive Landscape
Capability concentration sits with native cloud specialists; scale advantage sits with platform conglomerates that embed ITOSM within broader enterprise software ecosystems. The market structure bifurcates between premium autonomous platforms and commoditized ticketing systems, with mid-market buyers driving consolidation toward integrated suites. Three archetypes dominate: workflow orchestration pure-plays, hyperscaler-embedded offerings, and mainframe-era vendors bridging hybrid environments. Competitive moves center on AI capability acquisition and sovereign cloud partnership structures.
Within the workflow orchestration tier, ServiceNow exemplifies cloud-native architecture dominance. Among platform conglomerates, Microsoft Corporation and Oracle Corporation occupy positions that leverage existing enterprise relationships to displace point solutions. BMC Software represents the hybrid bridge archetype, anchoring accounts with mainframe-era infrastructure while extending cloud orchestration capabilities.
| Leading Market Players |
|---|
| ServiceNow |
| BMC Software |
| Broadcom |
| IBM Corporation |
| Ivanti |
| Atlassian |
| Microsoft Corporation |
| Oracle Corporation |
| Hewlett Packard Enterprise |
| Others |
Supply & Pricing Matrix
Trans-Pacific fiber routes between Singapore and Los Angeles carry the bulk of cloud platform traffic for ITOSM vendors, with bandwidth cost volatility directly compressing SaaS margins and forcing tiered subscription differentiation between premium AI-augmented tiers and baseline automation packages.
Pricing Analysis
Managed services and extended support contracts generate lifetime value multiples exceeding initial platform licenses by factors of three to five across enterprise accounts. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, with FedRAMP-authorized cloud instances commanding substantial premiums over standard commercial tiers. Cost compression in mid-market SaaS tiers is intensifying because generative AI copilots are collapsing help desk staffing ratios and commoditizing basic incident intake functions. Healthcare systems under HIPAA audit cycles demonstrate the sharpest price sensitivity, while US federal agencies absorb premium pricing without procurement friction for authorized platforms.
Supply Chain Analysis
Extended payment terms from hyperscaler cloud providers now stretch to ninety days for ITOSM vendors, compressing working capital and favoring balance-sheet-strong incumbents. Software development concentrates in India, Ireland, and Poland, with technical talent pools in Bangalore, Dublin, and Krakow feeding platform engineering pipelines. Cloud compute and API-native orchestration tools constitute the critical input dependencies, with GPU availability for AI training emerging as a binding constraint. Single-source vulnerability runs through NVIDIA's datacenter chip supply, which feeds from Taiwan Semiconductor Manufacturing. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for complex hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ITOSM market fragmentation creates opportunity pockets as sovereign data mandates splinter procurement requirements across jurisdictions, generating specialized vendor niches that resist platform consolidation.
For Market Incumbents: Entrench cloud-native architecture dominance by accelerating AI capability embedding ahead of generative AI commoditization curves. Acquire specialist firms with FedRAMP authorization credentials to lock out federal procurement competition. Vertical integration into sovereign cloud partnerships across Germany's Gaia-X and India's MeitY frameworks defends margin position against domestic provider challenges.
For New Entrants and Emerging Players: Establish a beachhead in edge computing telemetry orchestration for industrial IoT deployments, where lightweight agent requirements outstrip incumbent platform bloat. Target mid-market healthcare systems navigating HIPAA audit cycles with consumption-based pricing models that displace perpetual license incumbents. Lead with ISO 20000 certification investment to qualify for European outsourcing RFPs mandating ITIL 4-aligned service catalogs.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy mainframe-era vendors with stranded hybrid cloud assets and federal agency relationships ripe for modernization. Long-term viability hinges on AI-native workflow automation capabilities that displace rules-based orchestration over the coming decade. Watch for NIS2 Directive enforcement intensity across German critical infrastructure operators as an inflection indicator for compliance-driven procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Platform Integration | ServiceNow's embedding of predictive analytics displaces tier-1 help desk staffing models across US healthcare systems. |
| Sovereign Cloud Partnership | Gaia-X alignment in Germany preserves on-premises footprints for financial services institutions facing COBOL-era technical debt. |
| FedRAMP Authorization Acquisition | US federal agencies under SEC cybersecurity disclosure rules expand mandatory procurement scope for authorized vendors. |
| Edge Computing Agent Development | Distributed IoT telemetry creates demand for lightweight orchestration outside traditional data center boundaries. |
| ISO 20000 Certification Investment | European outsourcing RFPs mandating ITIL 4-aligned service catalogs expand addressable market for certified vendors. |
Research Methodology
The analysis maps cloud-native workflow orchestration, hybrid infrastructure management, AI-augmented service tiers, and sovereign cloud deployments, each validated through CTOs, IT procurement officers, platform engineers, and channel partners across primary interviews combined with SEC filings, hyperscaler capex disclosures, App Annie enterprise mobility data, and ISO certification registries as secondary sources. Bottom-up sizing of vendor revenue pipelines and top-down macroeconomic calibration ensure triangulation integrity.
Assumptions held fixed include prevailing regulatory enforcement intensity for NIS2 and FedRAMP frameworks, cloud migration velocity among financial services institutions, and AI capability diffusion rates across mid-market enterprises. The projection horizon spans deployment model evolution, organization size tiers, vertical industry patterns, and regional adoption clusters. CAGRs derive from segment-level growth rate synthesis anchored to infrastructure modernization spending patterns and RBI-mandated operational resilience procurement timelines for Indian banks and NBFCs.
Stress conditions across sovereign data localization requirements, GPU supply availability for AI training workloads, and Site Reliability Engineer talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology substitution curves and regulatory enforcement trajectories. Macroeconomic contraction, regulatory fragmentation acceleration, or autonomous remediation capability breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
UAE Digital Twin Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Virtual Closet Market
Digital Solutions
Data Fusion Solutions Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
Global Smart Lecture Capture System Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Canada ICT Market
Digital Solutions
Smart Connected Assets and Operations Market
Digital Solutions
Global Correspondence Management System Market
Digital Solutions
North America Data Virtualization Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Data Monetization Solutions for Life Science Companies Market
Digital Solutions
Product Information Management Market
Digital Solutions
Global Data Historian Market