
 North America Rechargeable Battery Market | 2026-2036
North America Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rechargeable Battery Market Insights
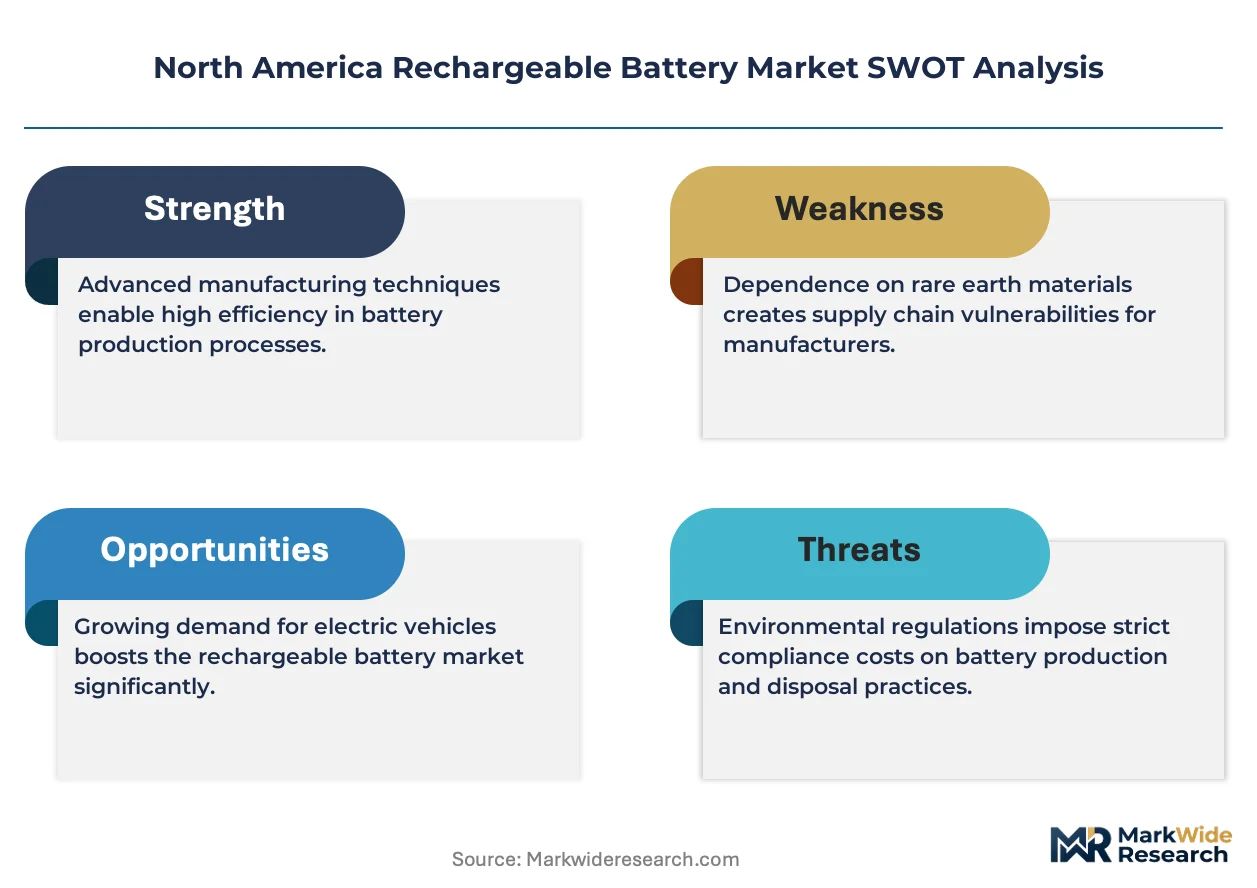
Energy density thresholds above 300 Wh/kg is collapsing the cost-per-kilometer calculus for long-range transportation. Tesla Inc. leverages its Nevada cell production to anchor vertical integration across cathode active material and pack assembly. LG Energy Solution competes through specialized cylindrical and prismatic formats tailored to Detroit automaker platforms. Contemporary Amperex Technology Co. Limited extends its North American position through licensing arrangements with regional manufacturers seeking LFP cell technology.
A rechargeable battery stores electrochemical energy through reversible reduction-oxidation reactions, with lithium-ion variants employing lithium cobalt oxide or lithium iron phosphate cathodes paired with graphite anodes separated by microporous polyolefin membranes to achieve cycle lives exceeding 2,000 charge events. The primary commercial purpose centers on portable and stationary energy storage where grid connectivity remains impractical or intermittent power supply disrupts operations. Lithium-ion chemistry dominates value capture across electric vehicle applications where nickel-rich cathodes command premium positioning. Lead-acid technology occupies mature industrial backup power segments where capital sensitivity outweighs energy density requirements. Energy storage deployments represent the fastest-expanding end user category as utility-scale battery installations absorb surplus renewable generation.
The Inflation Reduction Act directs EPA and Department of Energy standards toward domestic content verification, compelling manufacturers to document North American mineral sourcing and cell assembly location. NHTSA crashworthiness protocols for battery enclosures add structural engineering requirements that filter market access for imported pack designs. OSHA workplace exposure limits for nickel and cobalt compounds impose industrial hygiene investments across electrode manufacturing facilities. Stakeholders must monitor how forthcoming EPA hazardous waste classifications for end-of-life lithium-ion cells reshape collection infrastructure economics and recycler licensing obligations.
Market Dynamics
The Inflation Reduction Act's domestic content verification regime is restructuring procurement geography across the North American rechargeable battery supply chain, compelling manufacturers to requalify mineral sourcing and cell assembly locations to maintain federal incentive eligibility.
Growth Catalysts
- Inflation Reduction Act domestic content provisions:The EPA and Department of Energy standards redirect capital toward North American mineral extraction and electrode manufacturing, creating localized supply chain clusters.
- Utility-scale energy storage deployments:Grid operators across Texas, California, and the Midwest absorb surplus renewable generation through containerized lithium-ion installations, expanding addressable demand beyond mobility applications.
- Nickel-rich cathode chemistry advancement:Energy density thresholds above 300 Wh/kg compress cost-per-kilometer economics for long-range electric vehicle platforms, accelerating OEM platform redesign cycles.
Market Restraints
- Cobalt and nickel price volatility:Concentrated Democratic Republic of Congo cobalt mining and Indonesian nickel processing expose cathode active material costs to geopolitical disruption and ESG scrutiny.
- NHTSA crashworthiness compliance:Structural engineering requirements for battery enclosure integrity filter market access for imported pack designs lacking North American certification data.
- Lead-acid substitution persistence:Capital-sensitive industrial backup power segments retain mature lead-acid technology where energy density requirements remain secondary to upfront cost minimization.
Strategic Opportunities
- LFP chemistry licensing arrangements:Regional manufacturers seeking lithium iron phosphate cell technology access Chinese process expertise through technology transfer agreements, bypassing direct import tariffs.
- Canadian critical mineral extraction:Ontario and Quebec hard-rock lithium deposits offer IRA-compliant sourcing alternatives to South American brine operations, attracting processing facility investments.
- Second-life stationary applications:End-of-life electric vehicle packs transition to grid storage with degraded capacity, creating circular economy revenue streams and reducing raw material intensity.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and manufacturing process optimization expertise concentrates among a limited cohort of specialists, constraining facility ramp rates across Nevada and Tennessee gigafactory sites.
- OSHA nickel and cobalt exposure compliance:Workplace air monitoring and industrial hygiene infrastructure investments impose operational overhead across electrode coating and dry room facilities, extending commissioning timelines.
- End-of-life hazardous waste classification uncertainty:Forthcoming EPA lithium-ion cell disposal designations threaten to reshape collection infrastructure economics and recycler licensing obligations before secondary supply chains mature.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rechargeable Battery Market |
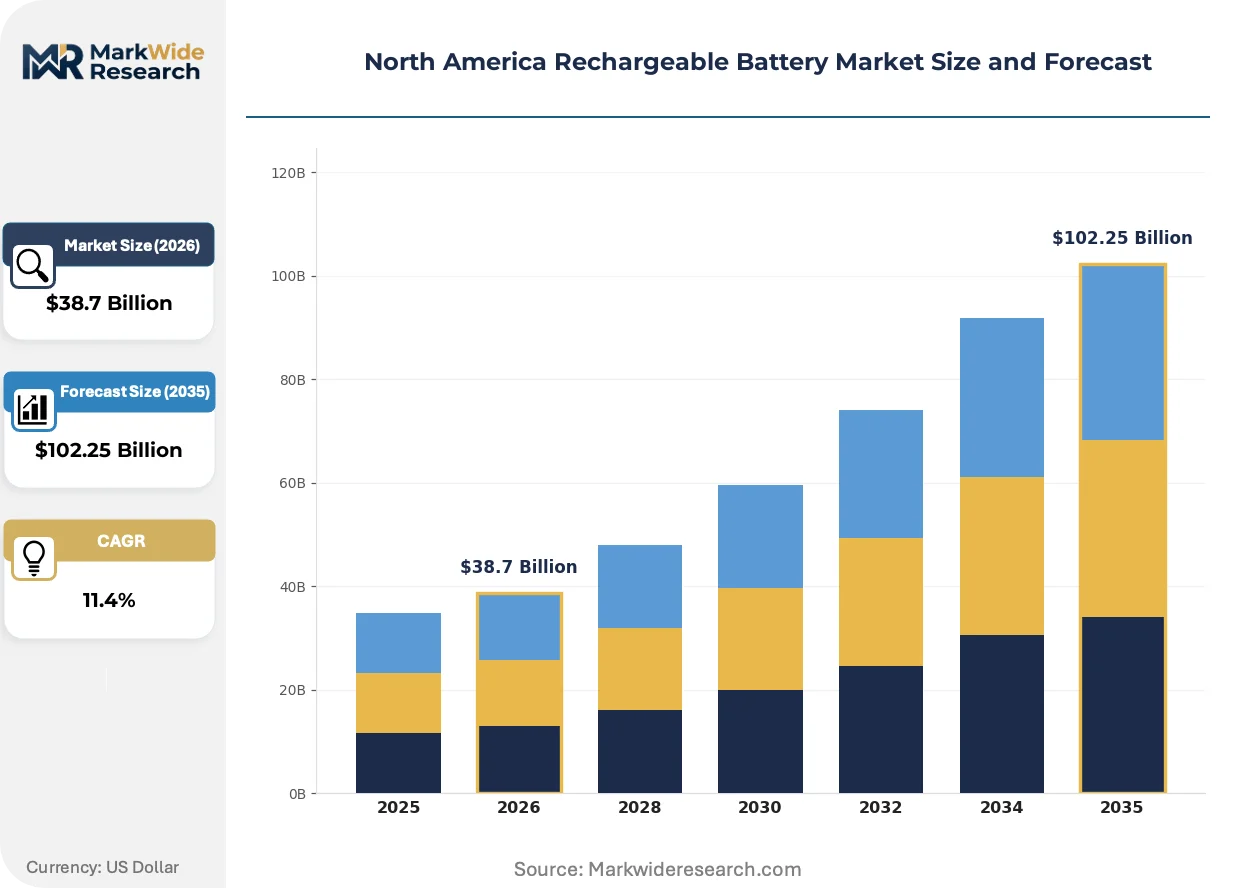
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Lithium Polymer End User: Consumer Electronics, Automotive, Industrial, Energy Storage Application: Telecommunications, Power Tools, Electric Vehicles, Renewable Energy Distributor Type: Online Retailers, Wholesalers, Direct Sales, Others |
| Companies Covered | Panasonic Corporation, Contemporary Amperex Technology Co. Limited, Tesla Inc., EnerSys, Samsung SDI Co. Ltd., LG Energy Solution, A123 Systems, East Penn Manufacturing Co., Saft America, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rechargeable Battery Market Trends and Innovations
Cell chemistry and pack architecture are diverging toward specialized formats, with cylindrical, prismatic, and pouch constructions each capturing distinct end-use verticals based on thermal management requirements and space constraints.
Solid-state electrolyte development is bifurcating research investment between sulfide and oxide ceramic pathways, with automotive OEMs prioritizing the former for energy density gains while industrial storage favors the latter for manufacturing scalability. Cell manufacturers in Michigan and Tennessee pilot production lines targeting 2026-2028 qualification timelines. The technology is compressing incumbent liquid electrolyte market share in premium automotive segments while leaving cost-sensitive applications to conventional lithium-ion.
The EPA's forthcoming hazardous waste classification for spent lithium-ion cells is compelling reverse logistics infrastructure investment, with original equipment manufacturers establishing collection networks before regulatory mandates crystallize. Recycler licensing requirements are tightening across California and New York, favoring domestic processing capacity over export-dependent dismantling. Pack designers now incorporate disassembly protocols anticipating end-of-life material recovery obligations.
Fleet operators and utilities are consolidating procurement through long-term offtake agreements rather than spot market purchases, compressing supplier margins while securing volume commitments for gigafactory output. Direct contracting between battery manufacturers and renewable developers is displacing distributor-mediated transactions in utility-scale storage. This pattern concentrates most visibly in ERCOT and CAISO grid territories where interconnection queue delays favor pre-committed supply arrangements.
North America Rechargeable Battery Market Segmentation
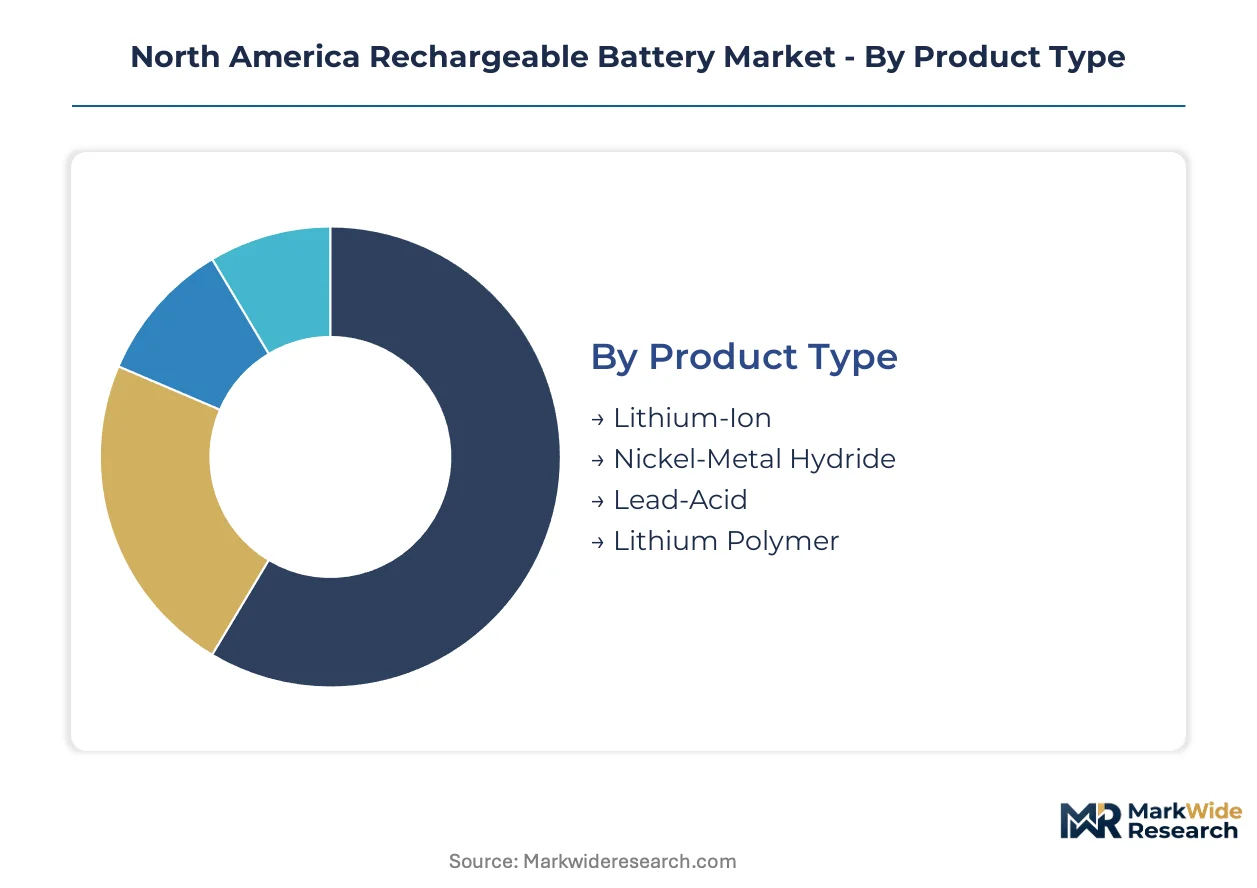
Segmentation in the North American rechargeable battery market reveals how chemistry choices and procurement channels determine access to federal incentives. Product type and end-use concentration directly shape which manufacturers qualify for IRA domestic content credits.
Product Type:
Substitution pressure from alternative chemistries and solid-state prototypes is reshaping investment allocation across established formats.
- Lithium-Ion:Nickel-rich cathode formulations achieve energy density thresholds above 300 Wh/kg for long-range electric vehicle platforms. Procurement concentrates among Michigan and Tennessee gigafactory clusters serving Detroit automaker supply chains, with IRA domestic content verification driving electrode manufacturing localization.
- Lead-Acid:Mature flooded and absorbed glass mat constructions dominate industrial backup power where capital sensitivity outweighs cycle life requirements. Demand persists in data center uninterruptible power systems across Texas and Virginia, though lithium iron phosphate displacement accelerates in price-sensitive utility storage.
- Nickel-Metal Hydride:Rare-earth hydride anode chemistry retains position in hybrid electric vehicle battery packs where moderate energy density suffices.
- Lithium Polymer:Gel electrolyte construction enables flexible form factors in consumer electronics and drone applications.
Lithium-Ion retains volume leadership; Lithium Polymer holds the steepest expansion curve in specialized portable applications.
End User:
Cost tier stratification separates premium automotive qualification requirements from price-sensitive industrial procurement.
- Automotive:Cell-to-pack architectures integrate prismatic and cylindrical formats directly into chassis structures, eliminating module-level components. Platform engineering concentrates at Nevada and Tennessee production sites, with NHTSA crashworthiness protocols filtering imported pack designs lacking North American certification data.
- Energy Storage:Containerized lithium-ion installations absorb surplus renewable generation across ERCOT and CAISO grid territories. Utility procurement through long-term offtake agreements is displacing distributor-mediated transactions, compressing supplier margins while securing gigafactory volume commitments.
- Consumer Electronics:Pouch cell formats dominate smartphone and laptop applications where space constraints override thermal management complexity.
- Industrial:Forklift motive power and telecommunications backup systems balance cycle life against charging infrastructure availability.
Automotive commands the highest revenue tier; Energy Storage is expanding most quickly as interconnection queue delays favor pre-committed supply arrangements.
Application:
Volume concentration in electric vehicle platforms is redirecting cell chemistry R&D toward automotive-specific qualification timelines.
- Electric Vehicles:Battery electric and plug-in hybrid platforms consume cylindrical 4680 and prismatic blade cell formats tailored to Detroit OEM thermal management architectures. Solid-state electrolyte pilot lines in Michigan target qualification timelines that would compress incumbent liquid electrolyte market share in premium segments.
- Renewable Energy:Grid-scale installations pair lithium iron phosphate cells with power conversion systems for four-hour duration storage, capturing investment tax credit extensions.
- Telecommunications:Remote cell tower backup systems prioritize reliability over energy density, sustaining mature chemistries.
- Power Tools:High-discharge cylindrical cells enable cordless construction equipment with rapid charging protocols.
Electric Vehicles anchors procurement volume; Renewable Energy gains share fastest as utility-scale deployments accelerate.
Distributor Type:
Customer type segmentation separates institutional procurement through direct contracting from fragmented retail channels.
- Direct Sales:Original equipment manufacturers and utility developers negotiate multi-year offtake agreements with cell producers, bypassing intermediary margins. Tesla's Nevada facility leverages this channel for captive supply to its vehicle and energy storage divisions.
- Online Retailers:E-commerce platforms aggregate replacement battery demand from consumer electronics and power tool end users, with logistics networks competing on delivery velocity.
- Wholesalers:Regional distributors serve industrial maintenance and telecommunications contractor segments with stocked inventory and technical support.
- Others:Auction and surplus channels handle secondary market transactions for end-of-life packs transitioning to second-life stationary applications.
Direct Sales captures the highest transaction values; Online Retailers show the steepest volume trajectory in replacement and aftermarket segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in the North American rechargeable battery sector favor domestic assembly over foreign finished pack imports. The United States runs a substantial deficit in cell components while building electrode manufacturing capacity. Canada and Mexico contribute critical mineral processing and assembly integration respectively.
United States
Michigan and Tennessee host gigafactory clusters serving Detroit automaker supply chains with prismatic and cylindrical cell formats. The Inflation Reduction Act's domestic content verification compels electrode manufacturing localization to maintain federal tax credit eligibility. Nevada anchors Tesla's vertical integration from cathode active material through pack assembly.
Canada
Ontario and Quebec hard-rock lithium deposits offer IRA-compliant sourcing alternatives to South American brine operations. Health Canada and PMRA coordinate with EPA standards on hazardous waste classifications for end-of-life cells. Processing facility investments concentrate in the Canadian Shield region to serve both domestic and US battery manufacturers.
Mexico
Baja California and Sonora develop lithium clay extraction projects to supply cathode active material producers. Mexican manufacturing integration focuses on module and pack assembly for US-bound electric vehicle platforms. The country's trade agreements facilitate tariff-advantaged component flows while IRA rules limit finished cell qualification.
North America Rechargeable Battery Market Competitive Landscape
Concentration sits with integrated cell-to-pack manufacturers and specialized chemistry licensors. The market structure splits between captive automotive supply divisions and independent merchant cell producers. Three archetypes dominate: vertically integrated OEM affiliates, Korean-Japanese technology specialists, and Chinese process licensors. Capacity expansion and strategic technology licensing constitute the primary competitive moves as firms race to qualify IRA-compliant supply chains.
Within the integrated OEM tier, Tesla Inc. anchors captive production for vehicle and energy storage divisions from its Nevada operations. LG Energy Solution and Panasonic Corporation exemplify the technology specialist archetype, occupying positions as merchant suppliers to multiple Detroit platforms. Contemporary Amperex Technology Co. Limited represents the licensing pathway, enabling regional manufacturers to access lithium iron phosphate process expertise without direct import exposure.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Contemporary Amperex Technology Co. Limited |
| Tesla Inc. |
| EnerSys |
| Samsung SDI Co. Ltd. |
| LG Energy Solution |
| A123 Systems |
| East Penn Manufacturing Co. |
| Saft America |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between utility developers and cell manufacturers lock in both IRA-compliant supply access and five-year price visibility, compressing spot market liquidity while insulating gigafactory output from cobalt and nickel volatility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the North American rechargeable battery market. Three-tier pricing structure across premium nickel-rich automotive cells, standard LFP utility formats, and economy lead-acid industrial backup separates qualification-intensive OEM supply from price-sensitive grid storage procurement. Cost compression in standard-tier LFP cells is intensifying because Chinese process licensors are expanding technology transfer arrangements with regional manufacturers. Data center operators and telecommunications contractors exhibit the highest price sensitivity, while Detroit automakers absorbing cells into platform-integrated packs demonstrate the least.
Supply Chain Analysis
China, South Korea, and Japan anchor cathode active material and separator membrane production for North American cell assembly. The regional supply chain draws from Indonesian nickel processing, Democratic Republic of Congo cobalt mining, and Australian spodumene concentrate. Single-source vulnerability concentrates in Chinese graphite anode supply and South Korean electrolyte salt production. Distribution runs through direct sales channels linking gigafactory output to OEM and utility offtake partners, with limited wholesaler penetration in aftermarket replacement segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through utility-scale procurement alliances and Detroit automaker platform standardization, shifting margin capture toward volume-committed purchasers and away from fragmented spot-market suppliers.
For Market Incumbents: Consolidate electrode manufacturing capacity within IRA-compliant North American zones to defend federal tax credit eligibility against emerging Chinese licensors establishing technology transfer partnerships. Deepen captive supply of cathode active material through backward integration into Canadian hard-rock lithium processing. Prioritize NHTSA crashworthiness certification investment to filter imported pack competition. For New Entrants and Emerging Players: Differentiate on LFP chemistry process expertise licensed to regional manufacturers seeking tariff-advantaged cell production without direct Chinese import exposure. Target second-life stationary applications where degraded electric vehicle packs transition to grid storage with minimal qualification overhead. Pursue direct contracting with ERCOT and CAISO utility developers bypassing established distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap electrode coating specialists with established dry room infrastructure and OSHA nickel exposure compliance systems already operational. Five-to-ten year viability hinges on IRA domestic content rule durability and solid-state electrolyte qualification timelines. Monitor EPA hazardous waste classification finalization as the critical inflection signal for recycler licensing economics and collection infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| IRA-Compliant Supply Chain Localization | Electrode manufacturing relocation to Michigan and Tennessee secures federal tax credit eligibility for Detroit automaker platforms. |
| Solid-State Electrolyte Pilot Line Investment | Michigan and Tennessee qualification timelines target premium automotive segments with sulfide ceramic pathway energy density gains. |
| LFP Technology Licensing Arrangement | Chinese process expertise transfer enables regional manufacturers to bypass direct import tariffs while accessing proven cell chemistry. |
| Second-Life Stationary Application Development | End-of-life electric vehicle pack redeployment to grid storage creates circular economy revenue streams and reduces raw material intensity. |
| Canadian Critical Mineral Processing Facility | Ontario and Quebec hard-rock lithium deposits offer IRA-compliant sourcing alternatives attracting joint venture investment. |
Research Methodology
Operator-level perspectives from gigafactory production managers, utility procurement directors, OEM platform engineers, and electrode coating facility operators anchored the qualitative base for this study. Primary interview data combined with secondary validation from Department of Energy funding disclosures, EPA regulatory filings, NHTSA safety protocols, and customs trade records. Bottom-up cell production capacity estimates triangulated against top-down electric vehicle platform deployment projections.
Sensitivity analysis tested forecast robustness across alternative IRA domestic content enforcement scenarios and solid-state electrolyte qualification timelines. Segmentation dimensions modeled include chemistry type, end-use vertical, cell format architecture, and regional production cluster. CAGRs derived from installed base turnover rates, platform redesign cycles, and interconnection queue progression patterns. Forecast inputs incorporated cathode active material cost curves, dry room commissioning timelines, and recycler licensing capacity buildout.
The analysis sits within stated boundaries; outcomes outside sustained IRA incentive continuity, NHTSA protocol stability, and OSHA exposure limit enforcement would require recalibration. Forecasts reflect documented assumptions regarding mineral supply concentration, gigafactory ramp rates, and utility procurement contract structures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Rechargeable Coin Cell Market
Batteries
United States Household Battery Market
Batteries
Wireless Power Bank Market
Batteries
GCC Rechargeable Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
Asia Power Tool Batteries Market
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
Dry Cell Battery Market
Batteries
Solid Electrolyte Market
Batteries
United Kingdom SLI Battery Market
Batteries
Lead Acid Battery Market
Batteries
Yacht Battery Market
Batteries
AAA Battery Market
Batteries
Europe Lead-Acid Battery Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market