
 Asia-Pacific Electronics Adhesives Market | 2026-2036
Asia-Pacific Electronics Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electronics Adhesives Market Outlook
GB/T 33372 compliance for volatile organic compound limits in electronics adhesives is reorganizing supplier eligibility across the Asia-Pacific region. Henkel AG & Co. KGaA leverages its Shanghai technical center to localize formulations for Chinese OEM qualification cycles. Dow anchors its position through captive silane chemistry production in Zhangjiagang. Shin-Etsu Chemical dominates thermal conductive silicone adhesive supply to Japanese automotive electronics tiers.
Electronics adhesives are polymer-based bonding systems formulated with epoxy, silicone, acrylic, or polyurethane chemistries, cured through thermal, moisture, or ultraviolet initiation to achieve dielectric strength exceeding 10 kV/mm and thermal conductivity up to 3 W/m·K for heat-dissipating interfaces. Their primary purpose is mechanical fixation, environmental sealing, and thermal management of printed circuit assemblies, semiconductor packages, and display modules. Epoxy adhesives retain the largest volume share due to established use in chip-on-board encapsulation and underfill applications, while UV-curable adhesives represent the fastest-expanding category as display manufacturers in South Korea and Vietnam adopt line-speed curing for OLED lamination. Conductive adhesives command premium pricing in telecommunications base station and satellite component applications where solder replacement is mandated.
China's SAMR enforces GB standards for hazardous substance limits in electronic products, while Japan's METI oversees chemical substance reporting under its industrial safety framework, and South Korea's MFDS aligns with REACH-equivalent pre-registration for imported adhesive raw materials. These regulatory layers elevate testing costs for new market entrants and favor incumbents with established compliance infrastructure. Stakeholders must monitor evolving perfluorinated substance restrictions across multiple Asia-Pacific jurisdictions, as these chemistry families currently serve critical moisture-barrier and dielectric functions in high-reliability formulations.
Market Dynamics
Semiconductor miniaturization below 5nm nodes is compressing bondline thickness requirements below 25 micrometers, forcing adhesive suppliers to reformulate thermal interface materials for void-free dispensing on high-density fan-out packages.
Growth Catalysts
- GB/T 33372 VOC limits:China's tightened volatile organic compound thresholds are filtering out non-compliant suppliers and expanding procurement volumes for certified domestic formulators serving Guangdong PCB clusters.
- Miniaturized semiconductor packaging:South Korean memory manufacturers are scaling adhesive consumption for chip-on-board encapsulation as die-shrink cycles accelerate.
- UV-curable display lamination:Vietnamese and South Korean OLED panel producers are converting assembly lines to ultraviolet curing systems, shortening takt times from minutes to seconds.
Market Restraints
- Silane monomer concentration:Captive production of critical silane chemistry concentrates in Zhangjiagang and two Japanese coastal sites, exposing buyers to single-source disruption risk.
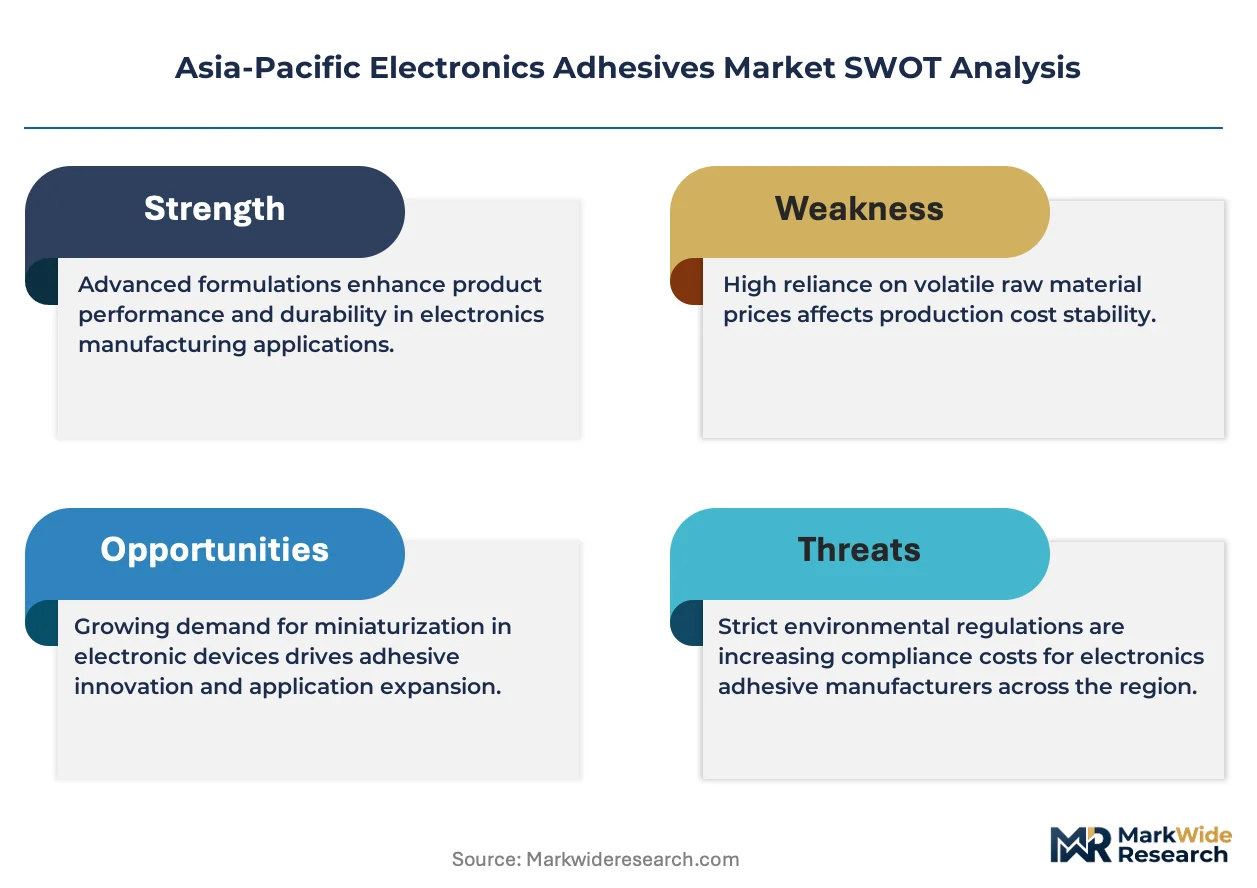
- Perfluorinated substance restrictions:Emerging regulatory limits on PFAS chemistry families across multiple Asia-Pacific jurisdictions threaten moisture-barrier formulations in high-reliability automotive electronics.
- Epoxy resin cost volatility:Bisphenol-A and specialty hardener feedstock prices fluctuate with crude oil derivatives and regional refinery utilization rates.
Strategic Opportunities
- Thailand automotive electronics tier:Japanese and Chinese adhesive suppliers are establishing localized compounding facilities to serve EV inverter and battery management module assembly plants.
- India PLI scheme for electronics:Production-linked incentives for semiconductor and component manufacturing are attracting adhesive distributors to establish technical service centers in Karnataka and Tamil Nadu.
- 5G base station conductive adhesives:Telecommunications infrastructure deployment across Indonesia and the Philippines is creating demand for isotropic conductive formulations as solder replacement in RF components.
Industry Challenges
- Formulation chemist scarcity:Asia-Pacific universities produce insufficient polymer scientists with expertise in dielectric property optimization for high-frequency applications.
- Dual certification timelines:Simultaneous qualification under Japan's JIS thermal interface standards and China's GB protocols extends OEM approval cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electronics Adhesives Market |
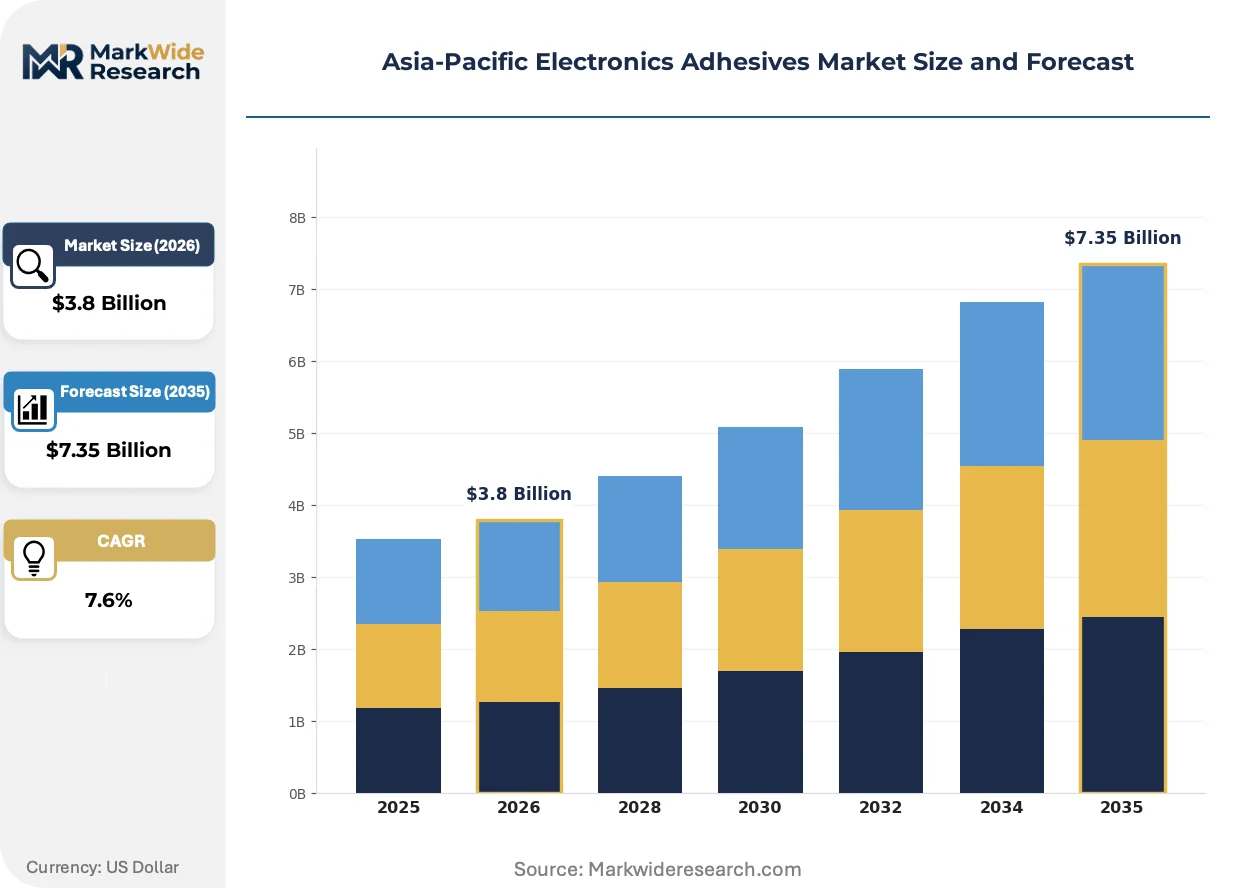
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Adhesives, Epoxy Adhesives, Silicone Adhesives, UV-Curable Adhesives End User: Consumer Electronics, Automotive Electronics, Industrial Electronics, Telecommunications Form: Liquid, Paste, Film, Granules Application: Bonding, Sealing, Coating, Encapsulation |
| Companies Covered | Henkel AG & Co. KGaA, Dow, 3M, H.B. Fuller Company, Sika AG, BASF SE, Shin-Etsu Chemical, Hubei Huitian New Materials, Master Bond, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electronics Adhesives Market Strategic Shifts
Adhesive functionality is bifurcating between ultra-thin thermal management layers for advanced packaging and reworkable formulations for circular electronics mandates, reshaping R&D allocation across the region.
Thermally conductive silicone adhesives with boron nitride fillers are supplanting traditional metal-oxide-loaded epoxies in automotive power module applications. Japanese tier-one suppliers are qualifying these materials for 150°C continuous operation. The shift is compressing epoxy volume share in thermal interface categories above 2 W/m·K conductivity.
Japan's METI chemical substance reporting framework and South Korea's MFDS REACH-equivalent pre-registration requirements are elevating raw material traceability obligations. Importers now face mandatory substance volume documentation for silane coupling agents and specialty curing agents. Formulators with established compliance infrastructure in Osaka and Seoul are capturing specification authority from smaller competitors.
Direct technical engagement models are displacing traditional distributor-led specifications in high-volume display panel procurement. South Korean and Vietnamese OLED manufacturers now require adhesive suppliers to station application engineers at fabrication sites for real-time viscosity adjustment. This pattern concentrates in Gumi and Bac Ninh, where line-speed curing parameters demand same-day formulation tuning.
Asia-Pacific Electronics Adhesives Market Segmentation
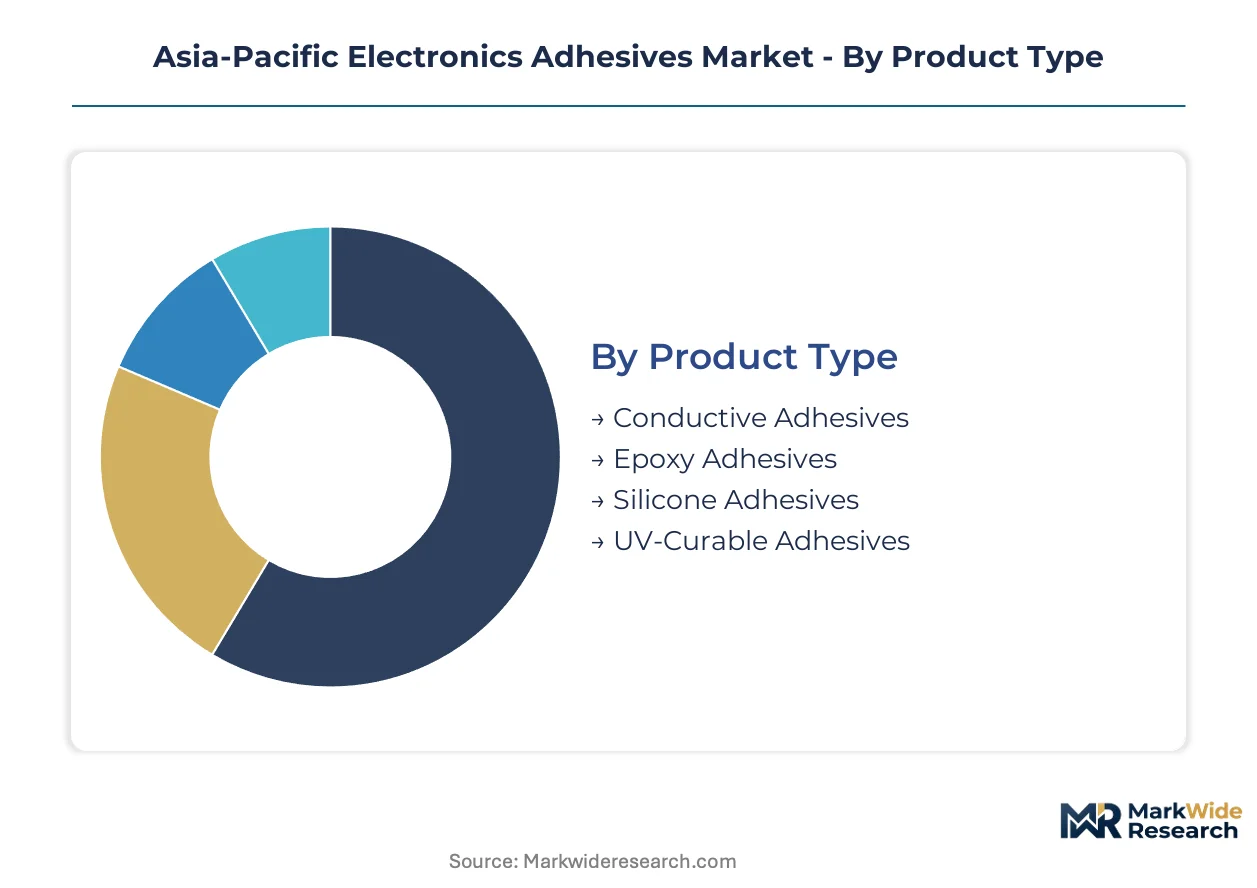
Segmentation in Asia-Pacific electronics adhesives reflects divergent compliance burdens and thermal performance requirements across semiconductor packaging, display lamination, and automotive power modules. Formulators must match chemistry families to specific JIS, GB, and MFDS certification pathways while optimizing for bondline thickness and conductivity specifications.
Product Type:
GB/T 33372 VOC thresholds and JIS thermal interface standards are segmenting supplier eligibility by chemistry family, with epoxy and silicone formulations facing distinct testing protocols in China and Japan.
- Epoxy Adhesives:Bisphenol-A and specialty hardener-based systems dominate chip-on-board encapsulation and underfill applications for memory manufacturers in South Korea. Guangdong PCB clusters consume these formulations at scale, though feedstock cost volatility tied to regional refinery rates compresses margin stability for formulators.
- Silicone Adhesives:Boron nitride-filled thermal conductive variants are supplanting metal-oxide epoxies in automotive power modules above 2 W/m·K conductivity. Japanese tier-one suppliers qualify these materials for 150°C continuous operation, tightening specification authority around Osaka-based formulators with METI compliance infrastructure.
- Conductive Adhesives:Isotropic formulations serve as solder replacement in 5G base station RF components across Indonesia and the Philippines, commanding premium pricing in telecommunications infrastructure.
- UV-Curable Adhesives:Ultraviolet initiation systems enable line-speed curing for OLED lamination in Vietnamese and South Korean display fabs, shortening takt times from minutes to seconds.
Epoxy adhesives handle the majority of throughput; UV-curable adhesives are the fastest mover on share.
End User:
Customer procurement patterns split between high-volume display panel contracts with embedded application engineers and automotive electronics specifications demanding 150°C thermal endurance validation.
- Consumer Electronics:Smartphone and wearable manufacturers in South Korea and Taiwan drive adhesive consumption for miniaturized semiconductor packaging below 5nm nodes, compressing bondline thickness requirements below 25 micrometers.
- Automotive Electronics:EV inverter and battery management module assembly in Thailand attracts localized compounding investments from Japanese and Chinese suppliers seeking proximity to Japanese automotive electronics tiers.
- Telecommunications:Base station and satellite component applications mandate conductive adhesive formulations where solder replacement is required, with deployment concentrated across Indonesian and Philippine infrastructure rollouts.
- Industrial Electronics:Factory automation and power electronics consume thermally conductive formulations for heat-dissipating interfaces, with demand clustering in China's eastern manufacturing corridors.
Consumer electronics commands the largest procurement volumes; automotive electronics is expanding most quickly as EV production scales across Thailand and Vietnam.
Form:
Dispensing equipment compatibility and void-free application requirements on high-density fan-out packages are favoring liquid and paste formats over film alternatives in advanced packaging.
- Liquid:Low-viscosity systems enable precision dispensing for void-free thermal interface layers on high-density fan-out packages, with real-time viscosity adjustment required at South Korean and Vietnamese OLED fabrication sites.
- Paste:Thixotropic formulations support stencil printing and dot dispensing in PCB assembly operations across Guangdong province, accommodating high-throughput surface mount lines.
- Film:Pre-cast adhesive sheets serve display lamination and large-area bonding applications where thickness uniformity is critical, though format flexibility lags liquid alternatives.
- Granules:Solid feedstock forms support hot-melt compounding operations and specialized encapsulation processes in industrial electronics manufacturing.
Liquid formulations absorb the highest throughput; paste formats are gaining share fastest in automotive electronics specifications.
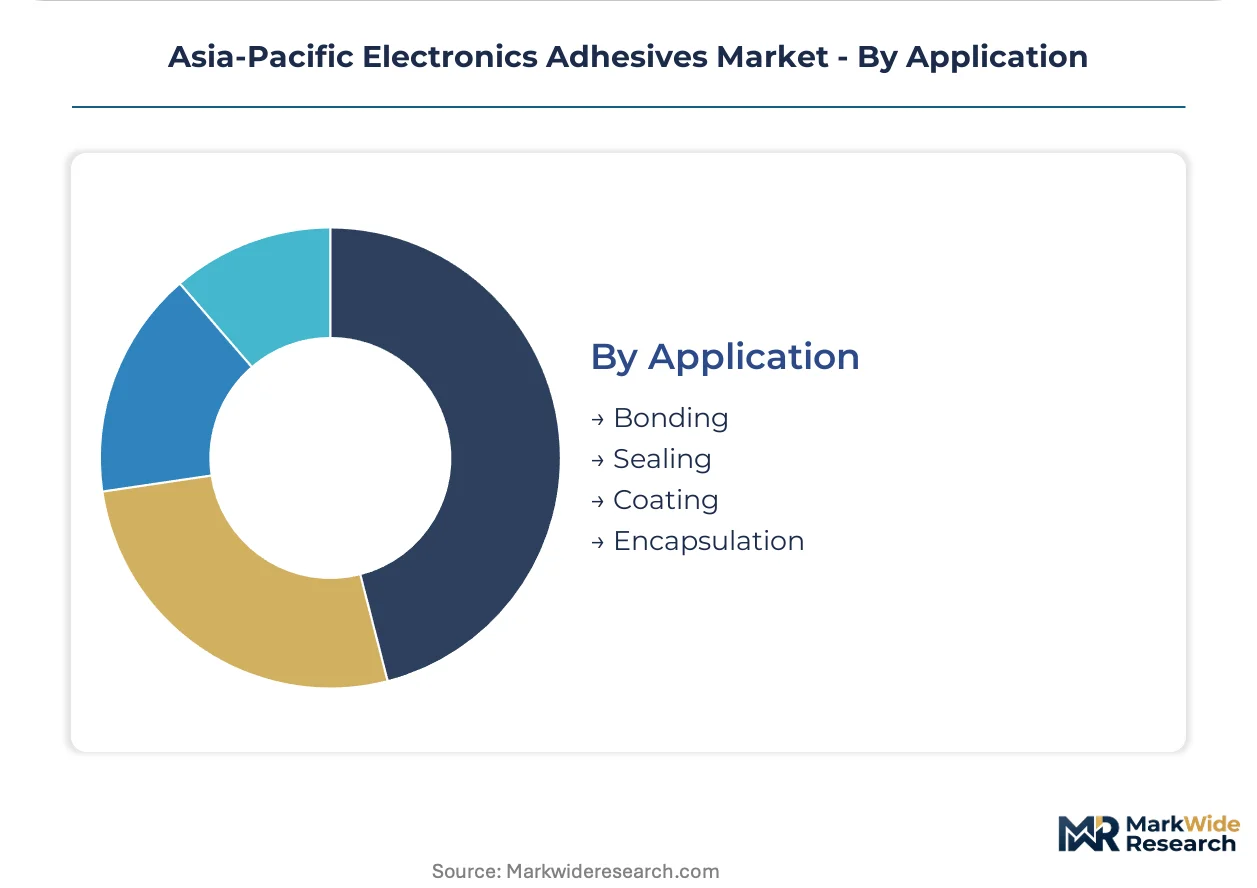
Application:
Functional requirements diverge between mechanical fixation with environmental sealing and thermal management optimization, with encapsulation demanding the most stringent dielectric strength validation.
- Encapsulation:Chip-on-board and underfill applications require dielectric strength exceeding 10 kV/mm combined with moisture-barrier performance, with perfluorinated substance restrictions threatening incumbent formulations.
- Bonding:Structural adhesive joints in display modules and PCB assemblies balance peel strength with reworkability as circular electronics mandates emerge in Japanese and South Korean regulatory frameworks.
- Sealing:Environmental protection for outdoor telecommunications and automotive electronics demands UV and thermal cycling resistance, with qualification protocols extending OEM approval cycles.
- Coating:Conformal and protective layers shield sensitive components from humidity and particulate contamination in industrial electronics deployments.
Encapsulation represents the largest application segment; bonding is climbing the fastest as display manufacturers prioritize reworkable formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforces GB/T 33372 VOC limits that filter supplier eligibility across the Asia-Pacific region. Japan's METI chemical reporting framework elevates raw material traceability obligations. South Korea's MFDS REACH-equivalent pre-registration requirements extend qualification timelines for imported adhesive raw materials.
China
Guangdong province PCB and display panel clusters consume specialty adhesive formulations at industrial scale. SAMR's GB standards on hazardous substance limits in electronic products tighten compliance thresholds for domestic and imported suppliers. Zhangjiagang hosts captive silane chemistry production that anchors regional supply security for thermal interface materials.
Japan
Japanese automotive electronics tiers demand thermal conductive silicone adhesives qualified for 150°C continuous operation. METI oversees chemical substance reporting under the country's industrial safety framework, elevating documentation burdens for silane coupling agents. Osaka-based formulators leverage established compliance infrastructure to capture specification authority from smaller competitors.
South Korea
Memory manufacturers in Gumi scale adhesive consumption for chip-on-board encapsulation as die-shrink cycles accelerate below 5nm nodes. MFDS aligns with REACH-equivalent pre-registration for imported adhesive raw materials, extending testing costs for new market entrants. OLED panel producers require suppliers to station application engineers at fabrication sites for real-time viscosity adjustment.
Vietnam
OLED panel producers in Bac Ninh convert assembly lines to ultraviolet curing systems, shortening takt times from minutes to seconds. The country's electronics manufacturing zones attract adhesive distributors establishing technical service centers for display lamination procurement. Local facilities prioritize line-speed curing parameters that demand same-day formulation tuning from supplier personnel.
Thailand
Japanese and Chinese adhesive suppliers establish localized compounding facilities to serve EV inverter and battery management module assembly plants. The country's automotive electronics tier benefits from proximity to Japanese OEM qualification protocols. Bangkok-adjacent industrial corridors concentrate demand for thermally conductive formulations in power electronics applications.
Asia-Pacific Electronics Adhesives Market Competitive Environment
Listed leaders compete with private specialists across formulation chemistry and certification infrastructure. The market structure concentrates around diversified chemical conglomerates with captive raw material production and regional specialists with localized technical service capabilities. Three archetypes dominate: integrated silane producers with backward chemistry control, formulation houses with dual GB-JIS certification competence, and application engineering specialists embedded at customer fabrication sites. Capacity expansion in Thailand and Vietnam and strategic partnerships for METI compliance infrastructure represent the dominant competitive vectors.
Among Germany-based diversified chemical groups, Henkel AG & Co. KGaA exemplifies the integrated formulator archetype through its Shanghai technical center localization. Dow occupies a position representing captive silane chemistry production in Zhangjiagang. Shin-Etsu Chemical sits within the Japanese specialty chemical tier, anchoring regional supply of thermal conductive silicone adhesives to automotive electronics manufacturers.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Dow |
| 3M |
| H.B. Fuller Company |
| Sika AG |
| BASF SE |
| Shin-Etsu Chemical |
| Hubei Huitian New Materials |
| Master Bond |
| Others |
Value Chain & Pricing Dynamics
GB/T 33372 VOC compliance thresholds gate supplier eligibility while simultaneously stratifying price tiers across the Asia-Pacific electronics adhesives landscape. Chinese OEM qualification cycles favor domestic formulators with certified formulations, compressing margins for non-compliant imports while rewarding incumbents with established testing infrastructure.
Pricing Analysis
Certification level (GB/JIS/MFDS-grade) creates the primary spread between premium and economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects dual-certification burdens and raw material traceability costs. Cost compression in standard-tier epoxy formulations is intensifying because bisphenol-A feedstock volatility feeds directly into spot pricing. Consumer electronics manufacturers in South Korea exhibit the highest price sensitivity due to high-volume procurement contracts, while automotive electronics tiers in Thailand accept premium pricing for 150°C thermal endurance validation.
Supply Chain Analysis
China and Japan anchor captive silane chemistry production for thermal interface materials. Specialty hardener feedstocks draw from regional refinery operations in South Korea and Taiwan. Single-source vulnerability concentrates in Zhangjiagang silane facilities and two Japanese coastal sites. Distribution runs through technical service centers embedded at major OLED fabrication sites in Gumi and Bac Ninh.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with dielectric optimization expertise for high-frequency applications represent the critical capability gap constraining competitive expansion in this market.
For Market Incumbents: Secure backward integration into silane coupling agent production to insulate margin structures from single-source disruption risk. Deepen certification competence across simultaneous GB-JIS qualification pathways to compress OEM approval cycles. Expand captive boron nitride filler compounding capacity for automotive power module specifications above 2 W/m·K conductivity. For New Entrants and Emerging Players: Application engineering staffing gaps at Vietnamese OLED fabrication sites present the most penetrable service-layer entry point. Target technical service center establishment in Bac Ninh and Ho Chi Minh City electronics zones. Lead with real-time viscosity adjustment capabilities and same-day formulation tuning protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermal conductive silicone adhesive compounding as boron nitride loading requirements escalate. Over a five-to-ten year viability window, acquisition targets should exhibit dual GB-JIS certification infrastructure and embedded application engineering relationships with display panel manufacturers. Monitor perfluorinated substance restriction timelines across multiple Asia-Pacific jurisdictions as the primary demand-destruction signal.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Infrastructure Investment | Simultaneous GB-JIS qualification capability compresses OEM approval cycles by 8-14 months for formulators. |
| Captive Silane Chemistry Production | In-house production of coupling agents insulates margin structures from Zhangjiagang concentration risk. |
| Embedded Application Engineering Deployment | Stationing technical personnel at Gumi and Bac Ninh fabrication sites enables real-time viscosity adjustment. |
| Thermal Conductive Filler Compounding Expansion | Boron nitride loading capacity for 150°C automotive specifications captures specification authority from epoxy incumbents. |
| Localized Compounding Facility Establishment | Thailand-based production serves EV inverter and battery management module assembly with Japanese OEM proximity. |
Study Parameters
Operator-level perspectives from adhesive formulators, display panel procurement managers, automotive electronics tier engineers, and thermal interface material R&D directors anchored the qualitative base. Primary field engagement combined with secondary validation from customs trade data, SEC chemical company filings, SAMR certification registries, and METI substance reporting disclosures. Bottom-up demand modeling across end-use segments triangulated against top-down supply capacity assessments.
Sensitivity analysis tested forecast robustness across feedstock price volatility scenarios and regulatory acceleration timelines. Segmentation dimensions modeled include chemistry family, end-use industry, thermal conductivity tier, and regional certification cluster. CAGRs were derived from segment-level volume trajectories and value-per-unit trends across the projection horizon. Specific inputs captured die-shrink cycle acceleration in memory manufacturing and UV-curing line conversion rates in display fabrication.
Forecasts assume regulatory continuity in China's SAMR GB standards framework and Japan's METI chemical reporting regime; material policy shifts would require re-modeling. Specific risks include perfluorinated substance prohibition acceleration, silane supply disruption events, and epoxy resin feedstock price spikes. Recalibration cycles align with material shifts in semiconductor packaging node transitions and display technology curing system adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Russia Adhesives Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Global Bone Cement and Glue Market
Adhesives & Sealants
De-Seamable Adhesives Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
Anti-Seize Compounds Market