
 Ddos Protection and Mitigation Security Market | 2026-2036
Ddos Protection and Mitigation Security Market Size, Share, and Industry Trends Forecast 2026-2036
Ddos Protection and Mitigation Security Market Analytics
North America is fragmenting into competing capability clusters spanning Silicon Valley, Northern Virginia, and Dallas-Fort Worth. Akamai Technologies leverages its distributed edge network to sustain sub-second mitigation response times for enterprise clients. Cloudflare anchors its position through in-house production of custom DDoS-scrubbing silicon, reducing reliance on commodity hardware. Radware competes aggressively in the carrier segment, where volumetric attack thresholds now exceed multiple terabits per second.
DDoS protection and mitigation security encompasses hardware, software, and cloud-delivered systems engineered to detect, divert, and absorb malicious traffic floods before they reach target infrastructure, typically operating at network layers 3-4 and layer 7 with scrubbing capacities scaling from 10 Gbps to 10+ Tbps. Its primary industrial purpose is ensuring business continuity for internet-facing services during coordinated denial-of-service campaigns. Cloud-based services now capture the fastest expansion as organizations abandon capex-heavy on-premises appliances in favor of elastic, usage-billed protection. Managed services concentrate margin pools through recurring revenue contracts that bundle 24/7 security operations center oversight with guaranteed response service-level agreements. Hybrid solutions occupy a transitional position for regulated entities requiring local traffic inspection before cloud handoff.
The Federal Communications Commission enforces communications reliability standards that indirectly mandate DDoS resilience for critical telecommunications infrastructure, while the EU AI Act and NIS2 Directive impose baseline cybersecurity requirements on digital service providers operating across member states. ISO 27001 certification has become a de facto procurement filter, with enterprise buyers refusing vendor shortlists that lack demonstrable information security management systems. Stakeholders must monitor the divergence between sovereign cloud mandates and hyperscaler global architectures, as data-localization requirements reshape where scrubbing centers can physically reside.
Market Dynamics
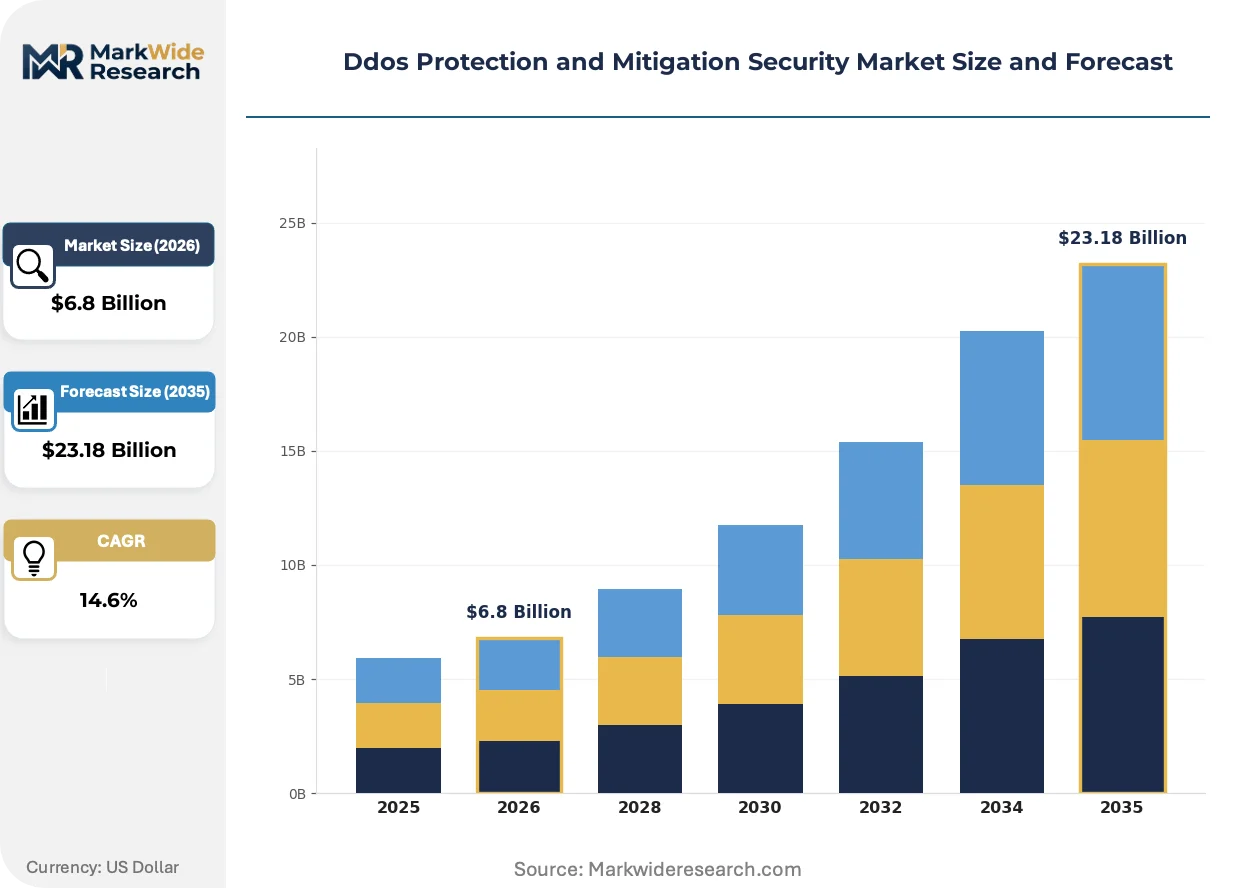
Attack volume inflation is compressing scrubbing infrastructure economics, forcing providers to absorb terabit-scale floods while maintaining sub-second response guarantees. This pressure is redistributing margin pools from hardware vendors toward cloud-delivered managed services with elastic capacity contracts.
Growth Catalysts
- NIS2 Directive:The EU's cybersecurity framework mandates baseline resilience for digital service providers, accelerating procurement of hybrid protection architectures across member states.
- Financial services:Banks and payment processors are expanding always-on mitigation contracts as attack sophistication escalates beyond reactive defense capabilities.
- Hyperscaler convergence:Cloud platform consolidation in the United States is creating integrated security stacks that bundle DDoS protection with compute and storage commitments.
Market Restraints
- Silicon supply concentration:Custom ASIC production for high-throughput scrubbing depends on a limited foundry base in Taiwan and South Korea, creating capacity bottlenecks during demand surges.
- Specialized engineering talent:The scarcity of professionals combining network protocol expertise with machine learning operations limits vendor scaling velocity.
- Capex intensity:Terabit-scale scrubbing centers require substantial power and cooling infrastructure, constraining geographic expansion to established data hub markets.
Strategic Opportunities
- India's digital infrastructure:The country's expanding fintech and e-commerce sectors remain underpenetrated by premium mitigation services, creating first-mover positioning potential.
- 5G network slicing:Telecommunications carriers can embed DDoS protection as a native network function, opening subscription revenue streams distinct from enterprise IT budgets.
- Federal procurement mandates:United States government cloud security requirements are creating certified provider categories that exclude non-compliant competitors.
Industry Challenges
- Attack attribution complexity:Sophisticated actors employ spoofed infrastructure and cryptocurrency payment rails, complicating legal response and insurance claim validation.
- Multi-cloud integration friction:Enterprises operating across AWS, Azure, and Google Cloud require consistent policy enforcement across incompatible native security controls.
- ISO 27001 certification timelines:Vendor qualification processes extend 12-18 months, delaying market entry for emerging technology providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ddos Protection and Mitigation Security Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, On-Premises Solutions, Cloud-Based Services, Hybrid Solutions Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Solution: Intrusion Prevention, Traffic Analysis, Threat Intelligence, Firewall Enhancements End User: Government Agencies, Financial Institutions, E-Commerce, Telecommunications |
| Companies Covered | Akamai Technologies, Cloudflare, NetScout Systems, Radware, Fortinet, F5, Imperva, A10 Networks, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ddos Protection and Mitigation Security Market Evolving Landscape
Real-time traffic analysis is converging with automated response orchestration, compressing the window between attack detection and mitigation activation. This capability shift is redefining competitive differentiation away from raw bandwidth toward intelligence-driven precision.
Machine learning inference at the network edge is digitizing attack pattern recognition, enabling scrubbing nodes to classify traffic anomalies without centralized data exchange. Financial institutions with sub-50 millisecond latency requirements are deploying these capabilities as standard procurement specifications. The technology is digitizing vendor selection criteria, displacing throughput metrics with detection accuracy benchmarks.
The EU AI Act imposes algorithmic transparency requirements on automated security decision systems, compelling vendors to document training data provenance and model validation protocols. Industrial consequence includes extended product development cycles for European market entry. Cloud service providers operating across member states are responding by segregating AI-driven scrubbing functions into explainable rule-based modules for regulatory audit.
Enterprise buyers are unbundling security operations center oversight from infrastructure contracts, creating standalone managed detection and response procurement categories. This pattern disrupts traditional bundled pricing models and compresses vendor margins through competitive benchmarking. The shift is most visible in United States federal contractor segments, where cyber hygiene requirements mandate independent SOC validation.
Ddos Protection and Mitigation Security Market Segmentation
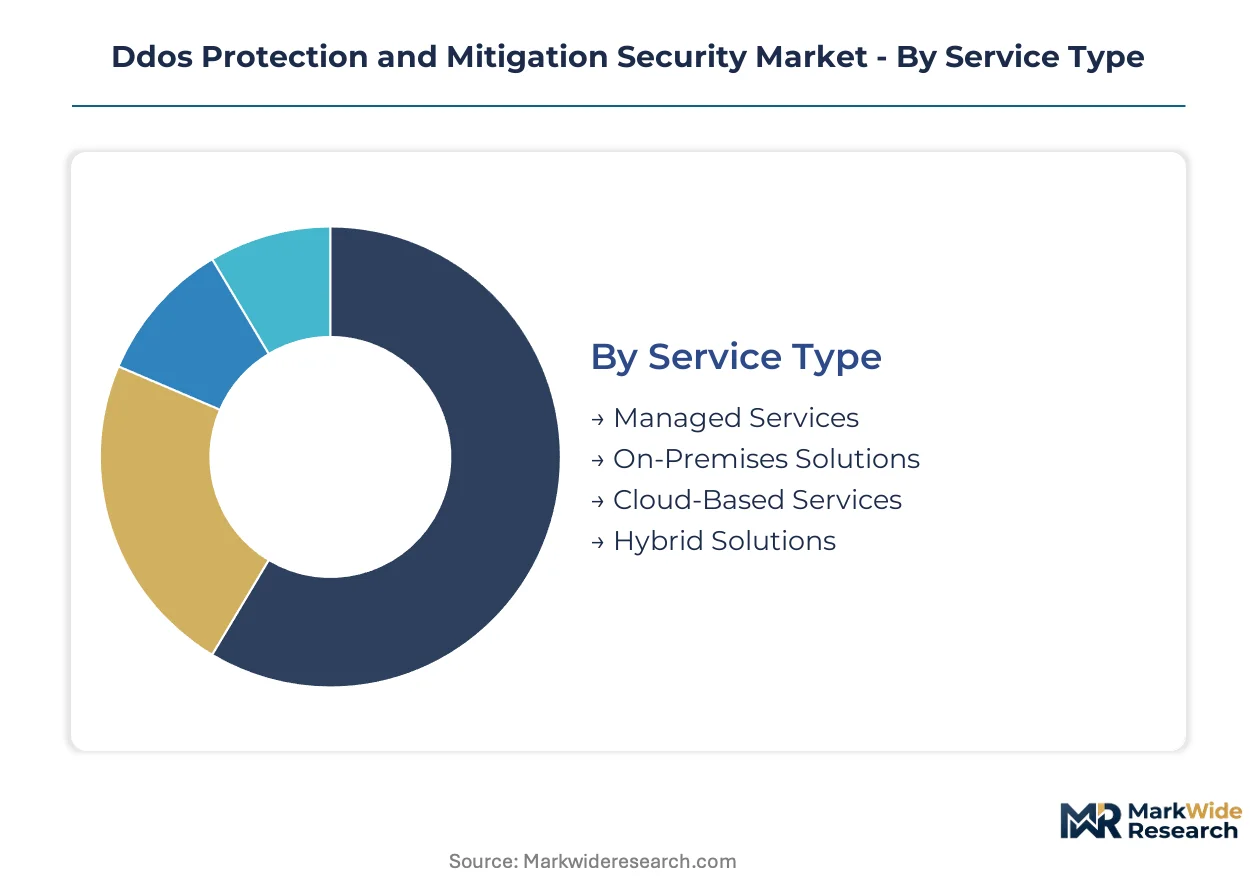
DDoS protection architectures fragment across four critical dimensions: service delivery economics, infrastructure placement, functional capability, and organizational risk profile. Each segmentation layer reveals distinct procurement patterns, margin structures, and vendor competitive positioning that shape enterprise buying behavior.
Service Type:
Cost tier stratification separates capex-intensive ownership from elastic operational expenditure models, with procurement committees weighting total cost of ownership against agility requirements.
- Cloud-Based Services:Elastic capacity contracts bill by clean traffic volume or attack peak magnitude, eliminating upfront scrubbing center investment. Financial institutions in the United States are standardizing these arrangements as baseline procurement specifications. The steepest expansion runs through this segment as hyperscaler integration reduces deployment friction.
- Managed Services:Twenty-four-hour security operations center oversight combines with guaranteed response service-level agreements under recurring revenue contracts. European banks facing NIS2 Directive compliance deadlines are consolidating vendor relationships here. This segment commands the established base through multi-year enterprise commitments.
- Hybrid Solutions:Local traffic inspection precedes cloud handoff, satisfying regulated entities requiring physical data sovereignty controls.
- On-Premises Solutions:Dedicated appliance ownership persists in classified government networks and air-gapped industrial control environments.
Managed services retain the deepest enterprise penetration. Cloud-based delivery is climbing the fastest as organizations abandon hardware refresh cycles.
Deployment Model:
Application context—latency sensitivity, data classification, and regulatory jurisdiction—determines whether infrastructure resides inside enterprise premises, within carrier facilities, or across distributed cloud edge nodes.
- Public Cloud:Shared scrubbing infrastructure scales instantaneously during volumetric attack spikes, with AWS Shield Advanced and Azure DDoS Protection embedding protection natively into compute subscriptions. United States federal contractors are migrating here under FedRAMP authorization requirements.
- Hybrid Cloud:Policy orchestration across on-premises appliances and cloud scrubbing centers enables consistent enforcement during partial infrastructure failures. German automotive manufacturers with multi-site production networks are deploying these architectures under ISO 27001 certification mandates.
- Private Cloud:Dedicated scrubbing instances serve sovereign cloud requirements in France and Saudi Arabia where data localization laws restrict cross-border traffic inspection.
- On-Premises:Physical appliance deployment continues in Japanese financial institutions governed by METI operational resilience guidelines.
Hybrid cloud configurations are expanding most quickly as multi-cloud complexity fractures single-vendor dependencies. Public cloud retains volume leadership through hyperscaler bundling.
Solution:
Functional maturity separates commodity packet filtering from intelligence-driven threat anticipation, with procurement specifications increasingly weighting detection precision over raw throughput capacity.
- Traffic Analysis:Real-time flow inspection identifies anomalous patterns through behavioral baselining, with machine learning inference compressing detection-to-mitigation windows below one second. United States payment processors now mandate sub-50 millisecond response guarantees in procurement specifications.
- Threat Intelligence:Distributed sensor networks and dark web monitoring feed predictive attack anticipation, enabling preemptive scrubbing rule deployment before campaign initiation. Israeli cybersecurity firms specialize in this capability layer.
- Intrusion Prevention:Deep packet inspection blocks protocol-level exploitation attempts that precede volumetric floods.
- Firewall Enhancements:Stateful inspection upgrades extend existing perimeter infrastructure rather than displacing it.
Traffic analysis commands premium pricing through latency-critical financial applications. Threat intelligence is gaining share fastest as attack anticipation displaces reactive defense postures.
End User:
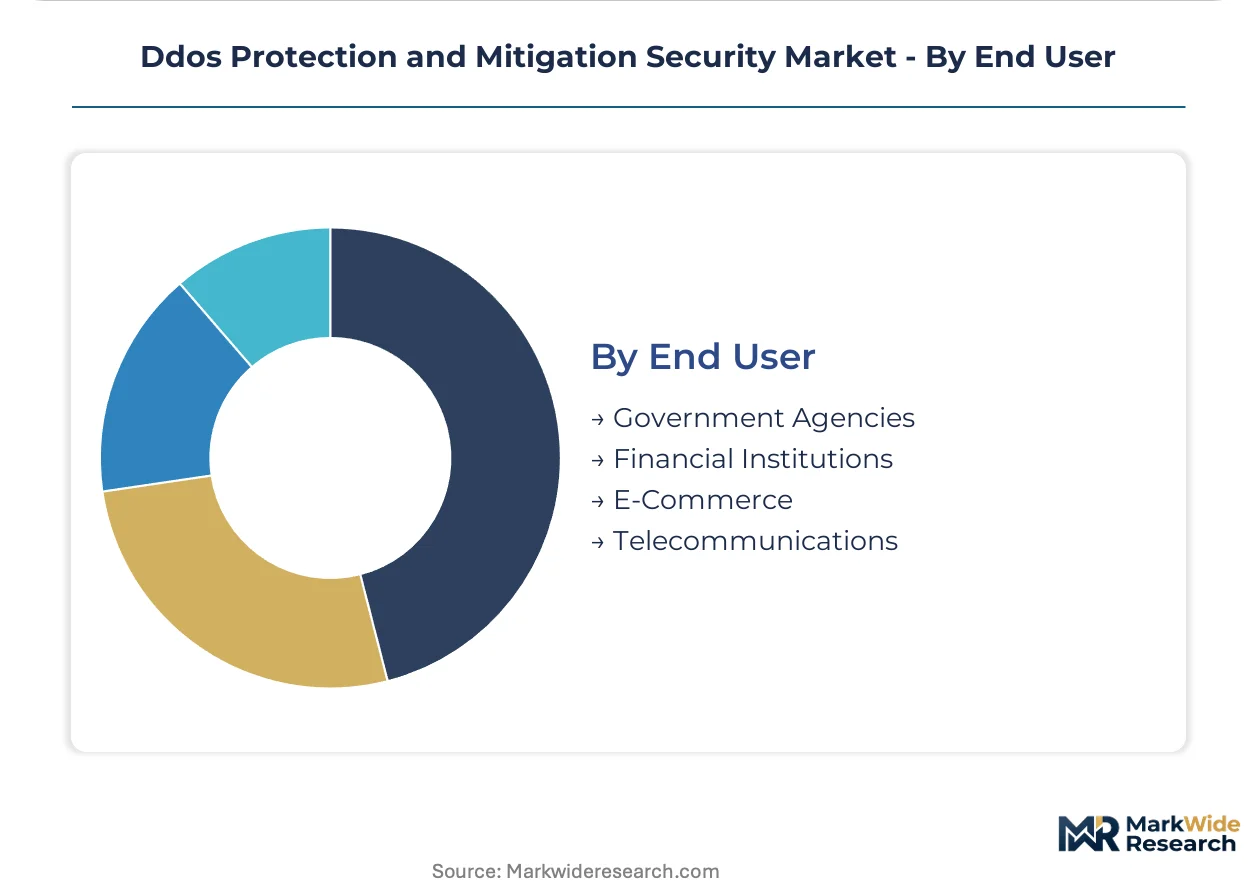
Customer type segmentation reflects divergent risk tolerances, regulatory exposure, and attack surface scale, with procurement authority centralizing differently across public sector, regulated finance, digital commerce, and carrier infrastructure.
- Financial Institutions:Banks and payment processors face coordinated campaigns exceeding terabit-per-second volumes, with the Federal Reserve's operational resilience guidance and the EU's Digital Operational Resilience Act mandating always-on protection. JPMorgan Chase and HSBC maintain dedicated scrubbing capacity through multi-vendor contracts.
- Telecommunications:Carrier networks experience the highest absolute attack volumes, with tier-1 providers in South Korea and Germany deploying inline scrubbing across peering points to protect downstream enterprise customers.
- Government Agencies:CISA directives in the United States and ENISA coordination in Europe mandate baseline protection for critical national infrastructure operators.
- E-Commerce:Retail platforms face seasonal attack spikes coinciding with promotional events, favoring elastic cloud-based procurement over fixed capacity commitments.
Financial institutions anchor vendor revenue through multi-year managed service contracts. Telecommunications represents the fastest-expanding vertical as 5G network slicing embeds protection as a native network function.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC communications reliability standards and federal cybersecurity mandates in the United States establish the regulatory foundation for DDoS resilience requirements across critical telecommunications infrastructure.
United States
Hyperscaler cloud platforms and federal contractors drive procurement of always-on mitigation services under FedRAMP authorization requirements. CISA directives mandate baseline protection for critical national infrastructure operators. Northern Virginia and Dallas-Fort Worth host competing capability clusters where scrubbing centers scale to absorb multi-terabit attack volumes.
Germany
Automotive manufacturers with multi-site production networks deploy hybrid cloud architectures to satisfy ISO 27001 certification mandates. The EU NIS2 Directive accelerates enterprise investment in hybrid protection architectures across member states. Bavaria and Baden-Württemberg concentrate vendor engineering talent for machine learning-driven traffic analysis systems.
United Kingdom
Financial institutions facing Digital Operational Resilience Act deadlines consolidate multi-vendor contracts for dedicated scrubbing capacity. ENISA coordination mandates baseline protection standards for critical infrastructure operators. London's fintech cluster generates concentrated demand for sub-50 millisecond latency guarantees in payment processing systems.
Japan
METI operational resilience guidelines govern physical appliance deployment in financial institutions requiring localized traffic inspection. The country's national cybersecurity regulator imposes data sovereignty controls on cross-border traffic inspection. Tokyo and Osaka anchor scrubbing infrastructure serving Asia-Pacific latency requirements.
India
Expanding fintech and e-commerce sectors remain underpenetrated by premium mitigation services, creating first-mover positioning potential. The country's central bank issues operational resilience guidelines for payment systems. Mumbai and Bengaluru concentrate domestic cloud platform development as hyperscalers establish local scrubbing nodes.
Ddos Protection and Mitigation Security Market Competitive Landscape
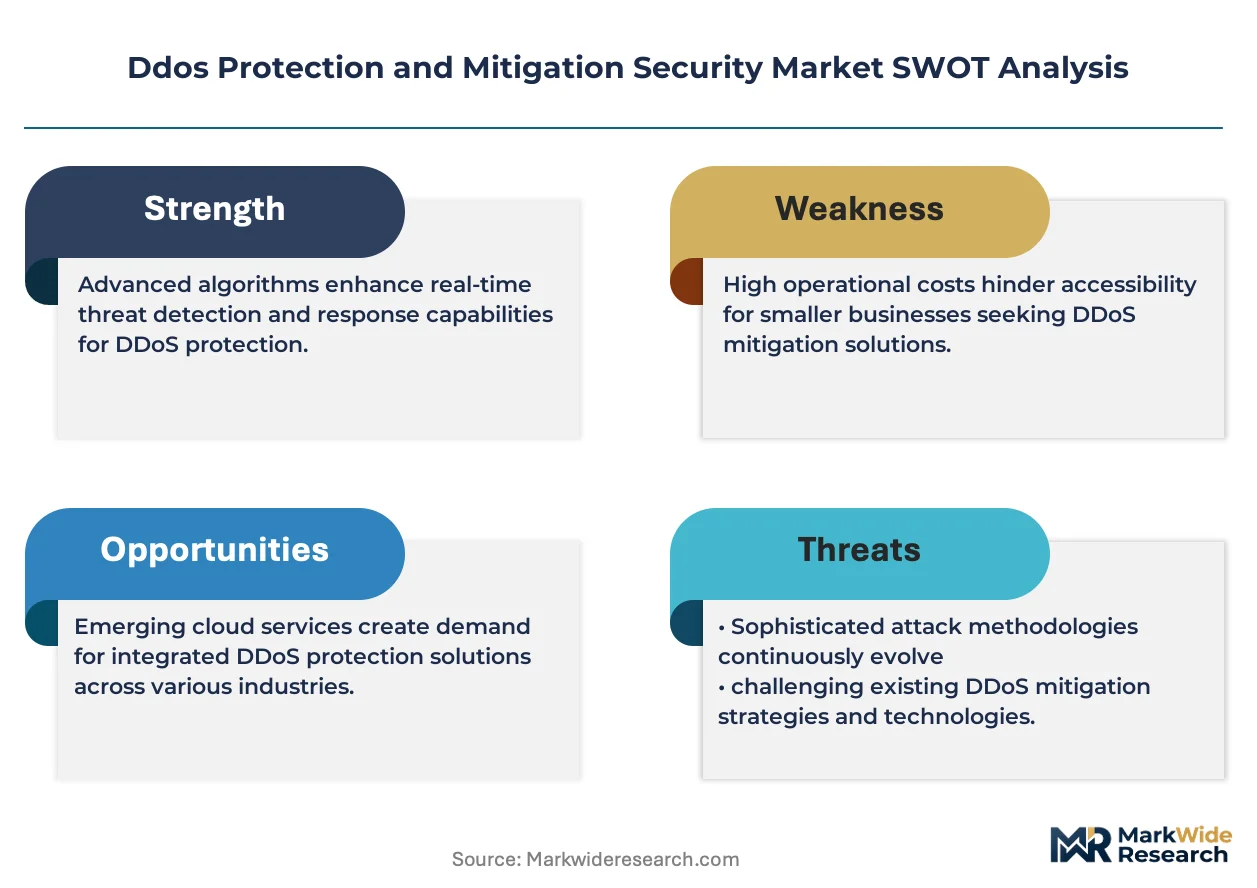
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three strategic archetypes: distributed edge networks with sub-second response guarantees, custom silicon producers reducing commodity hardware dependence, and carrier-focused specialists competing on volumetric attack thresholds. Dominant competitive moves include hyperscaler bundling of security stacks with compute commitments and geographic expansion of terabit-scale scrubbing centers into established data hub markets.
Among network infrastructure specialists, Akamai Technologies, Cloudflare, and Radware occupy distinct positioning vectors. Akamai exemplifies the distributed edge archetype through its sustained focus on enterprise latency requirements. Cloudflare anchors the custom silicon tier through in-house production of specialized scrubbing hardware. Radware sits within the carrier segment where attack volume thresholds now exceed multiple terabits per second.
| Leading Market Players |
|---|
| Akamai Technologies |
| Cloudflare |
| NetScout Systems |
| Radware |
| Fortinet |
| F5 |
| Imperva |
| A10 Networks |
| Amazon Web Services |
| Others |
Value Network & Pricing Analysis
Scrubbing center undercapacity in Northern Virginia and Dallas-Fort Worth is forcing providers into aggressive capacity expansion commitments while compressing margins on fixed-price enterprise contracts. This utilization squeeze simultaneously elevates spot pricing for surge capacity and accelerates vendor migration toward elastic, usage-billed cloud delivery models.
Pricing Analysis
Geographic price spreads between United States enterprise contracts and European NIS2-mandated deployments now exceed forty percent at equivalent service tiers. Three-tier pricing structure across premium always-on, standard on-demand, and economy burst-only levels dominates procurement frameworks, with ISO 27001 certification and sub-50 millisecond latency guarantees driving tier placement. Price erosion runs through the standard tier as hyperscaler bundling commoditizes baseline protection. Financial institutions exhibit lowest price sensitivity due to regulatory non-compliance penalties, while mid-market e-commerce platforms negotiate aggressively on per-gigabyte clean traffic rates.
Supply Chain Analysis
Custom ASIC production for high-throughput scrubbing hardware draws from a concentrated foundry base spanning Taiwan and South Korea, with packaging and testing operations anchored in Malaysia. Silicon wafers, advanced packaging substrates, and specialized cooling components constitute the critical input trinity. Single-source vulnerability around TSMC's advanced node capacity presents structural concentration risk during demand surges. Distribution runs through direct enterprise sales teams for managed services, while cloud-delivered protection embeds through hyperscaler marketplace channels and carrier resale partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buyer consolidation around multi-year managed service contracts has shifted negotiating leverage toward procurement committees demanding guaranteed response SLAs and independent SOC validation. This concentration among sophisticated buyers rewards vendors with proven operational scale and compliance certifications.
For Market Incumbents: Harden defensive positions by accelerating in-house silicon production to reduce foundry dependency, while expanding terabit-scale scrubbing capacity into Mumbai and Bengaluru to capture India's fintech procurement wave. Machine learning operations talent scarcity threatens scaling velocity; secure specialized engineering pipelines through university partnerships in Bavaria and Baden-Württemberg. FedRAMP authorization investments create exclusionary procurement categories that marginalize non-compliant competitors.
For New Entrants and Emerging Players: Build out threat intelligence specialization layers where Israeli cybersecurity firms currently concentrate, offering predictive attack anticipation as a standalone module unbundled from infrastructure contracts. India's underpenetrated premium mitigation services present the most penetrable geography, with central bank operational resilience guidelines creating compliance-driven demand. Channel partnerships with domestic cloud platforms in Mumbai and Bengaluru offer the cleanest go-to-market angle versus direct hyperscaler competition.
For Investors and Strategic Acquirers: Capital is best deployed toward custom silicon producers with demonstrated foundry relationships and carrier-focused specialists commanding volumetric attack thresholds above ten terabits per second. Long-term viability across the projection horizon rests on regulatory compliance automation capabilities as EU AI Act transparency requirements extend product development cycles. Watch for hyperscaler bundling intensity as the critical inflection signal; accelerated security stack integration with compute commitments would compress standalone vendor margins and trigger consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Production | In-house ASIC design at Cloudflare reduces Taiwan foundry dependency and enables sub-second response guarantees. |
| Geographic Scrubbing Expansion | Terabit-scale capacity buildout in Mumbai addresses India's fintech compliance deadlines and local data sovereignty requirements. |
| Threat Intelligence Unbundling | Standalone predictive attack modules disrupt bundled pricing models and capture enterprise SOC procurement categories. |
| Carrier Network Embedding | 5G network slicing partnerships with South Korean and German tier-1 providers open subscription revenue outside IT budgets. |
| FedRAMP Authorization Investment | Federal certification creates exclusionary provider categories for United States government cloud security requirements. |
Research Methodology
Initial hypotheses were tested against primary input from CISOs at financial institutions and payment processors, carrier network architects, hyperscaler security product managers, and regulatory compliance officers, then refined through secondary validation against FCC enforcement records, ENISA coordination frameworks, FedRAMP authorization databases, and ISO 27001 certification registries. Bottom-up segment sizing triangulated against top-down macroeconomic indicators and infrastructure investment disclosures from scrubbing center operators.
Demand-supply balance modeling across the analysis window incorporated service delivery economics, deployment model preferences, functional capability tiers, and organizational risk profiles as core segmentation dimensions. CAGRs were derived from elasticity-adjusted adoption curves and capacity expansion pipelines. Machine learning inference deployment rates and NIS2 Directive compliance timelines served as industry-specific forecast inputs alongside hyperscaler capex allocation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by custom silicon producers or sovereign cloud mandates would shift outcomes beyond modeled ranges. Cross-checking against hyperscaler security revenue disclosures and carrier capital expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Global Zero-Trust Security Market
Cybersecurity
Global Serverless Security Market
Cybersecurity
Belgium Cybersecurity Market
Cybersecurity
South Korea Cybersecurity Market
Cybersecurity
Global Ddos Protection Market
Cybersecurity
Finland Cybersecurity Market
Cybersecurity
E-Mail Security Market
Cybersecurity
Operational Technology Security Market
Cybersecurity
Post-Quantum Cryptography Market
Cybersecurity
Cloud Network Security Market
Cybersecurity
Cloud DLP Market
Cybersecurity
DNS Firewall Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
Japan Ransomware Protection Market
Cybersecurity
France Cybersecurity Market
Cybersecurity
Global Online Fraud Detection and Prevention Market